
 UV Lamps Market | 2026-2036
UV Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
UV Lamps Market Outlook
The EU Green Deal's zero-pollution ambition for water systems is recalibrating procurement criteria across European utilities. Heraeus Holding GmbH leverages its mercury vapor lamp foundry network to sustain long-term service contracts with German municipal operators. Seoul Viosys Co., Ltd. anchors UV-C LED chip production through in-house epitaxy capabilities that reduce reliance on legacy mercury supply chains.
UV lamps generate ultraviolet radiation through gas discharge or semiconductor electroluminescence, with peak germicidal efficacy occurring at 254 nanometers for low-pressure mercury designs and 265-280 nanometers for AlGaN-based LED architectures. Water treatment applications dominate installed base value as utilities face legacy infrastructure replacement cycles, while UV-C LED technology captures the fastest expansion trajectory due to mercury phase-out mandates and instant-on operational profiles. Healthcare end users concentrate margin pools around validation-intensive medical equipment sterilization systems requiring ISO 15883 compliance documentation.
The EPA regulates drinking water disinfection under the Safe Drinking Water Act while the EU F-Gas Regulation constrains mercury-containing lamp imports; China's MEE enforces dual carbon goals that favor LED-based ultraviolet systems in new municipal builds. Product standards from ISO 15883 and IEC 62471 shape market access thresholds for healthcare and consumer-facing deployments. Stakeholders must monitor regulatory divergence between mercury tolerance timelines and LED cost-parity achievements to time capacity investments.
Market Dynamics
Mercury phase-out mandates are compressing technology transition timelines across municipal water treatment infrastructure, forcing simultaneous capital redeployment toward UV-C LED architectures while legacy lamp service networks remain economically entrenched.
Growth Catalysts
- EPA Stage 2 Disinfectants Rule:US municipal utilities face binding disinfection byproduct limits that ultraviolet retrofits solve without chlorine residual complications.
- AlGaN epitaxy maturation:Semiconductor foundries achieve 265 nanometer wavelength precision at manufacturing scales that undercut mercury vapor lamp lifecycle costs.
- Healthcare sterilization validation:ISO 15883-compliant medical equipment manufacturers specify UV-C systems for terminal disinfection of endoscopes and surgical instruments.
Market Restraints
- Quartz sleeve supply concentration:High-purity fused quartz for low-pressure mercury lamps concentrates among three specialty glass manufacturers in Germany and Japan.
- Mercury import constraints:EU F-Gas Regulation creates customs friction for lamp assemblies containing elemental mercury above threshold quantities.
- LED thermal management:UV-C diode junction temperatures above 85 degrees Celsius degrade output intensity faster than predicted degradation curves.
Strategic Opportunities
- Ballast water treatment retrofits:IMO D-2 compliance deadlines for international shipping fleets create demand for medium-pressure UV systems in dry-dock installation windows.
- Consumer appliance integration:Residential HVAC manufacturers embed UV-C LED modules into ductwork for bioaerosol suppression during seasonal circulation cycles.
- Chinese dual carbon procurement:MEE-directed municipal builds favor mercury-free ultraviolet systems in Yangtze River basin water treatment expansions.
Industry Challenges
- Optical engineering talent scarcity:UV-C LED system design requires rare expertise in radiometric modeling and reflector geometry optimization.
- Legacy infrastructure interoperability:Mercury vapor lamp replacement cycles desynchronize with LED driver electronics upgrade timelines in installed treatment trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Lamps Market |
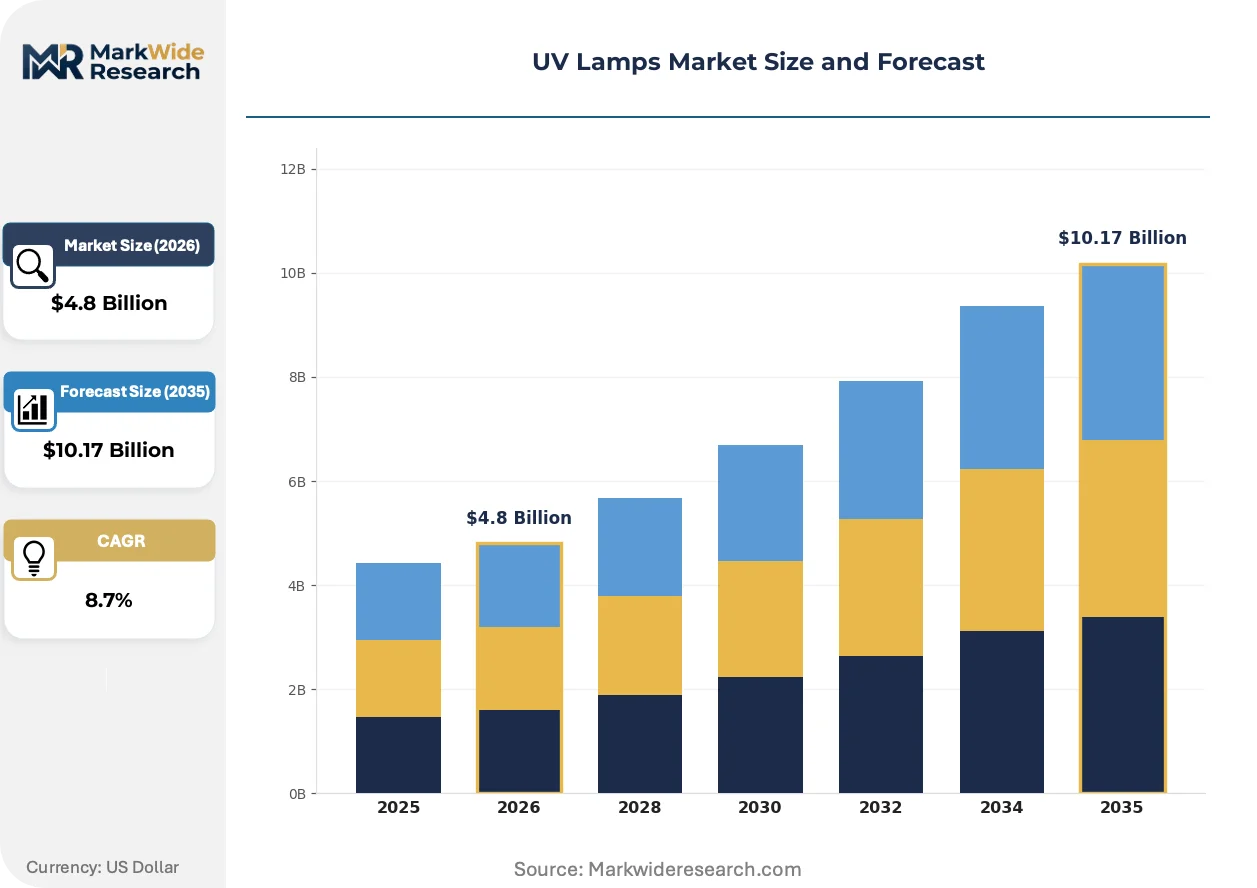
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mercury Vapor, LED, Low-Pressure, Medium-Pressure Application: Water Treatment, Air Purification, Surface Disinfection, Medical Equipment Sterilization End User: Residential, Industrial, Healthcare, Commercial Technology: Ultraviolet-C, Ultraviolet-A, Ultraviolet-B, Pulsed Xenon |
| Companies Covered | Heraeus Holding GmbH, Hamamatsu Photonics, Seoul Viosys Co., Ltd., Evoqua Water Technologies LLC, Xylem Inc., Nichia Corporation, Danaher Corporation, Crystal IS, Inc., ams OSRAM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Lamps Market Strategic Shifts
Technology substitution pressures and regulatory chemistry restrictions are rewriting procurement specifications faster than supplier production lines can reconfigure, creating temporary supply-demand mismatches across ultraviolet system categories.
UV-C LED architectures are overtaking mercury vapor designs in new municipal installations. Semiconductor electroluminescence at 275 nanometers delivers instant-on germicidal dosing without warm-up latency or mercury containment protocols. German and Dutch water utilities now specify LED-based reactors for greenfield treatment plants, compressing demand for legacy lamp foundry capacity.
REACH authorization timelines for mercury-containing products are tightening industrial substitution deadlines. The European Chemicals Agency's sunset date reviews force lamp manufacturers to accelerate AlGaN chip sourcing contracts ahead of supply chain readiness. Healthcare sterilization OEMs in France and Italy front-load validation documentation to secure CE marking under Medical Device Regulation transition periods.
After-sales service unbundling is fragmenting historical supplier relationships. Municipal procurement officers separate lamp replacement contracts from system maintenance agreements, enabling third-party LED module suppliers to displace integrated OEM service networks. This pattern concentrates in US states with centralized utility purchasing authorities such as California and Texas.
UV Lamps Market Segmentation
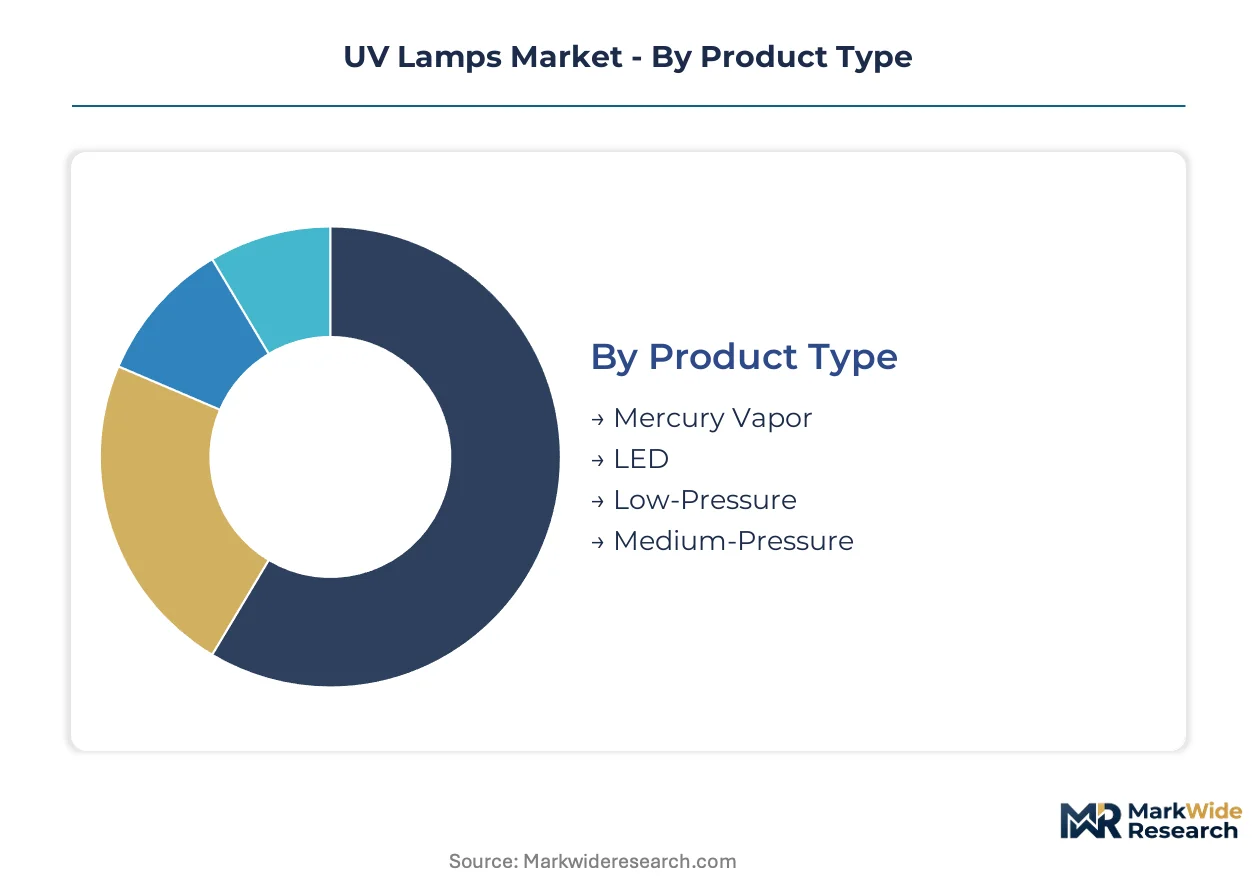
UV lamp procurement splits sharply between standalone reactor systems and embedded modules within larger equipment trains. Technology substitution timelines and regulatory chemistry restrictions create divergent margin profiles across each segment boundary.
Product Type:
Mercury vapor designs dominate installed base value as standalone infrastructure assets, while LED architectures embed more readily into distributed point-of-use systems.
- Mercury Vapor:Low-pressure mercury arc discharge at 254 nanometers delivers proven germicidal efficacy for high-volume municipal water treatment. German and Japanese utilities specify these lamps for legacy infrastructure replacement cycles where thermal management constraints exclude semiconductor alternatives.
- LED:AlGaN-based electroluminescence eliminates warm-up latency and mercury containment protocols entirely. Dutch greenfield treatment plants now mandate LED-based reactors under EU Green Deal procurement guidelines.
- Low-Pressure:Amalgam-doped designs sustain output across variable water temperatures in secondary wastewater disinfection.
- Medium-Pressure:Polychromatic output across 200-400 nanometers addresses UV-resistant pathogens in ballast water treatment systems.
Mercury vapor leads volumes today; LED is gaining share fastest.
Application:
Cost tier differentiation separates capital-intensive municipal infrastructure from consumable-intensive point-of-use deployments.
- Water Treatment:EPA Stage 2 Disinfectants Rule mandates drive ultraviolet retrofits across US municipal utilities. Chlorine residual complications disappear when 254 nanometer dosing replaces chemical oxidation.
- Air Purification:HVAC-integrated bioaerosol suppression commands premium pricing in healthcare and commercial real estate. Ductwork-mounted systems require continuous operation profiles that favor LED instant-on characteristics.
- Surface Disinfection:Mobile UV-C towers serve intermittent-use environments where permanent installation proves uneconomical.
- Medical Equipment Sterilization:ISO 15883 validation documentation creates barrier-to-entry for terminal disinfection of endoscopes and surgical instruments.
Water treatment commands absolute revenue scale; air purification shows steepest expansion trajectory.
End User:
Customer type determines specification intensity, with healthcare and industrial buyers demanding validated performance documentation absent in residential procurement.
- Residential:Point-of-use water pitchers and HVAC retrofits prioritize first-cost minimization over lifecycle efficiency. Consumer appliance OEMs embed UV-C LED modules into ductwork for seasonal circulation cycles.
- Industrial:Food and beverage processors specify validated UV systems for process water disinfection under HACCP protocols.
- Healthcare:Medical device sterilization OEMs front-load ISO 15883 compliance documentation to secure CE marking under Medical Device Regulation transition periods.
- Commercial:Office building and hospitality installations balance capital constraints against occupancy health liability exposure.
Industrial buyers lead current procurement volume; healthcare is expanding most quickly.
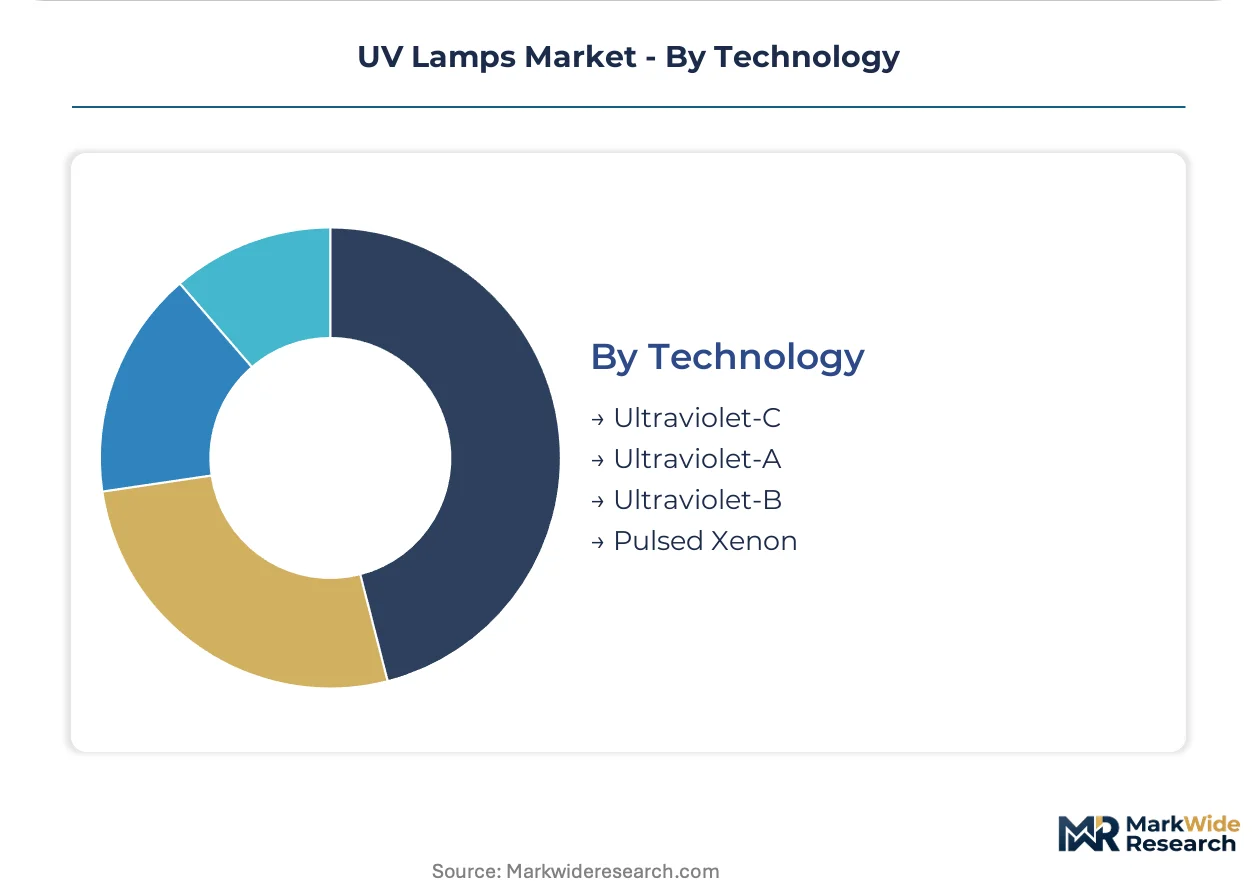
Technology:
Wavelength precision and pulse characteristics segment applications by germicidal mechanism and material compatibility requirements.
- Ultraviolet-C:Peak DNA absorption at 265 nanometers delivers maximum microbial inactivation per unit energy. Semiconductor foundries now achieve this wavelength precision at manufacturing scales that undercut mercury vapor lifecycle costs.
- Ultraviolet-A:Lower-energy emission serves photocatalytic oxidation processes in advanced oxidation train configurations.
- Ultraviolet-B:Intermediate wavelengths address niche applications in vitamin D synthesis and selective phototherapy.
- Pulsed Xenon:High-intensity broadband flashes enable rapid surface disinfection without continuous heat generation.
Ultraviolet-C dominates installed capacity; pulsed xenon climbs fastest in surface treatment niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent clusters in southern Germany and the Netherlands anchor European UV system design capabilities. Semiconductor fabrication expertise concentrates in East Asian foundry zones. Municipal procurement authorities in North America and East Asia drive divergent technology adoption timelines.
United States
EPA Stage 2 Disinfectants Rule mandates accelerate ultraviolet retrofits across Great Lakes and Southwest water utilities. Chlorine residual complications disappear when 254 nanometer dosing replaces chemical oxidation. California's State Water Resources Control Board enforces stricter pathogen standards than federal baselines, concentrating LED pilot deployments in Los Angeles and San Diego metropolitan treatment districts.
Germany
REACH authorization timelines for mercury-containing products compress industrial substitution deadlines across Rhineland manufacturing zones. The European Chemicals Agency's sunset date reviews force lamp manufacturers to accelerate AlGaN chip sourcing contracts. Heraeus Holding GmbH leverages its foundry network in Hanau to sustain long-term service contracts with municipal operators in North Rhine-Westphalia and Bavaria.
China
MEE-directed municipal builds favor mercury-free ultraviolet systems in Yangtze River basin water treatment expansions. Dual carbon goals privilege LED-based architectures in new infrastructure commissioning. Semiconductor foundries in Jiangsu and Zhejiang provinces achieve 265 nanometer wavelength precision at manufacturing scales that undercut mercury vapor lifecycle costs.
Japan
High-purity fused quartz supply concentrates among specialty glass manufacturers in Osaka and Nagoya industrial corridors. METI efficiency standards for water treatment equipment favor instant-on LED characteristics over mercury warm-up latency. Nichia Corporation anchors UV-C LED chip production through in-house epitaxy capabilities that reduce reliance on legacy mercury supply chains.
Netherlands
EU Green Deal procurement guidelines now mandate LED-based reactors for greenfield treatment plants in Randstad urban agglomerations. Dutch water utilities specify semiconductor electroluminescence at 275 nanometers for germicidal dosing without warm-up latency. Knowledge clusters around Eindhoven's photonics ecosystem supply optical engineering expertise for reflector geometry optimization.
UV Lamps Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent technology transition timelines. Mercury vapor lamp foundries retain entrenched service networks while semiconductor specialists capture greenfield specification authority. Three archetypes dominate: integrated lamp manufacturers with captive quartz sourcing, AlGaN chip foundries with epitaxy control, and system integrators unbundling after-sales service contracts. Competitive intensity concentrates around capacity expansion in UV-C LED fabrication and strategic partnerships bridging legacy infrastructure to semiconductor architectures.
Among German industrial conglomerates, Heraeus Holding GmbH exemplifies the integrated lamp manufacturer archetype through its mercury vapor foundry network. Seoul Viosys Co., Ltd. and Nichia Corporation represent East Asian semiconductor specialists with in-house epitaxy capabilities. These three anchors illustrate the geographic and technological bifurcation shaping procurement authority: European incumbents defend installed base service relationships while Korean and Japanese chip fabricators capture specification momentum in new municipal builds.
| Leading Market Players |
|---|
| Heraeus Holding GmbH |
| Hamamatsu Photonics |
| Seoul Viosys Co., Ltd. |
| Evoqua Water Technologies LLC |
| Xylem Inc. |
| Nichia Corporation |
| Danaher Corporation |
| Crystal IS, Inc. |
| ams OSRAM |
| Others |
Value Chain & Pricing Dynamics
The EU F-Gas Regulation's mercury phase-out timeline gates qualified supply for legacy lamp manufacturers while reserving premium-tier pricing access to AlGaN chip foundries with certified LED architectures. Municipal procurement officers now unbundle after-sales service contracts from system maintenance agreements, fragmenting historical supplier relationships and compressing margin pools across the value chain.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated OEM service networks from third-party LED module suppliers. Pricing stratifies across premium, standard, and economy tiers based on ISO 15883 certification grade and after-sales service bundling. Cost compression in standard-tier mercury vapor replacements is intensifying because municipal utilities front-load LED pilot deployments ahead of regulatory deadlines. Residential point-of-use buyers exhibit highest price sensitivity; healthcare sterilization OEMs demonstrate lowest sensitivity due to validation documentation requirements.
Supply Chain Analysis
Freight cost escalation for high-purity fused quartz from Germany and Japan amplifies working capital requirements for low-pressure mercury lamp manufacturers. AlGaN epitaxy wafer supply concentrates in South Korea, Taiwan, and Japan; mercury vapor lamp assembly draws from German and Chinese production bases. The supply chain rests on concentrated quartz sleeve sourcing from Osaka and Nagoya specialty glass manufacturers. Single-source vulnerability in 265 nanometer UV-C LED chip fabrication creates procurement risk for system integrators. Distribution runs through municipal utility purchasing authorities in California and Texas alongside European water operator consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UV lamps market functions as a geographic-arbitrage play where AlGaN foundry capacity in East Asia undercuts European mercury vapor lifecycle costs by eliminating warm-up latency and hazardous material protocols.
For Market Incumbents: Cement long-term service contracts with German and Dutch municipal operators before REACH authorization timelines sunset mercury-containing product categories. Defend installed base revenue by acquiring captive quartz sleeve suppliers in Japan to secure raw material continuity against import friction. Capacity addition in Jiangsu and Zhejiang provinces captures MEE-directed municipal build specifications.
For New Entrants and Emerging Players: Enter via unbundled LED module supply to US states with centralized utility purchasing authorities. White-space targets include residential HVAC-integrated bioaerosol suppression and ballast water treatment retrofits for IMO D-2 compliance. The most penetrable segment is consumer appliance integration where seasonal circulation cycles favor instant-on semiconductor characteristics.
For Investors and Strategic Acquirers: Roll-up economics work for optical engineering specialists because radiometric modeling expertise scarcity prevents rapid capability replication by generalist system integrators. Acquisition targets include AlGaN chip foundries with in-house epitaxy control and validated ISO 15883 documentation portfolios. The signal to watch is EU Green Deal procurement guideline adoption velocity across Randstad urban agglomerations.
| Strategic Initiative | Industry Significance |
|---|---|
| AlGaN Epitaxy Capacity Expansion | East Asian foundries achieve 265 nanometer precision at manufacturing scales undercutting mercury lifecycle costs. |
| ISO 15883 Validation Investment | Healthcare sterilization OEMs front-load compliance documentation to secure CE marking under Medical Device Regulation. |
| Quartz Sleeve Backward Integration | German lamp manufacturers acquire Japanese specialty glass suppliers to mitigate REACH-driven supply friction. |
| LED Module Unbundling | Third-party suppliers displace integrated OEM networks in California and Texas centralized purchasing authorities. |
| Ballast Water System Partnership | Medium-pressure UV manufacturers capture IMO D-2 dry-dock installation windows for international shipping fleets. |
Study Parameters
Bottom-up municipal utility procurement modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core. Primary interviews with water treatment plant engineers, municipal procurement officers, AlGaN epitaxy specialists, and healthcare sterilization OEMs combined with secondary validation from EPA Stage 2 compliance filings, ECHA REACH authorization databases, and MEE dual carbon procurement directives. Triangulation against customs records for mercury vapor lamp assemblies and LED module trade flows anchored supply-side estimates.
Historical trendline analysis of wavelength precision achievement and manufacturing scale economics informed projection frameworks across the analysis window. Segmentation dimensions modeled include lamp technology type, application vertical, end-user category, and regional regulatory cluster. CAGRs derived from unit shipment trajectories weighted by average selling price evolution in mercury vapor versus LED architectures. Forecast inputs incorporated MEE-directed build timelines and EU Green Deal procurement guideline adoption curves.
Inputs from ECHA sunset date reviews and EPA compliance filings were available through the study window; gaps in proprietary AlGaN chip foundry utilization rates introduce uncertainty bands around LED cost-parity achievement timing. Forecasts reflect documented assumptions regarding mercury tolerance timeline extensions and thermal management degradation curve improvements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Photography Light Box Market
Lighting
Industrial UV-C Disinfection Lighting Market
Lighting
North America Smart Lighting Market
Lighting
North America Outdoor Lighting Market
Lighting
Smart Lighting Market
Lighting
Bacteriological Light Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Global Flame Proof Lighting Market
Lighting
Solid State Lighting System Market
Lighting
Lighting Fixture Market
Lighting
Global Plasma Lamp Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Human Centric Lighting Market
Lighting
Plasma Lighting Market
Lighting
Ambient Lighting Market