
 Global in Ceiling Camera Market | 2026-2036
Global in Ceiling Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Global in Ceiling Camera Market Outlook
Cloud-managed video analytics subscriptions is restructuring how in-ceiling camera vendors monetize hardware deployments, shifting revenue from one-time equipment sales to recurring software tiers. Axis Communications leverages its open-platform architecture to sustain developer ecosystem loyalty across enterprise accounts. Hangzhou Hikvision Digital Technology anchors its position through vertical integration into image sensor fabrication and firmware development. Bosch Security Systems differentiates via its DIN-certified cybersecurity protocols that command premium positioning in European critical infrastructure bids.
An in-ceiling camera mounts flush within architectural ceiling cavities, typically incorporating motorized pan-tilt-zoom actuators, varifocal lenses with minimum illumination thresholds below 0.01 lux, and Power-over-Ethernet connectivity for centralized cable management. Its primary commercial purpose spans loss prevention, occupancy analytics, and automated access control in high-traffic indoor environments. PTZ cameras capture the fastest-growing share as retail and hospitality operators prioritize dynamic scene coverage over fixed-field monitoring. IP-based technology leads volume shipment while analog installations persist only in cost-constrained retrofit scenarios across developing economies.
FCC equipment authorization governs radio-frequency emissions for wireless in-ceiling models sold in the United States, while the EU AI Act imposes conformity assessment obligations on biometric analytics functions deployed across member states. China's GB/T standards from MIIT mandate network security certification for IP cameras connected to public infrastructure. Stakeholders must monitor divergence between regional AI surveillance restrictions and cloud-platform interoperability requirements as procurement specifications harden.
Market Dynamics
The transition from analog to IP-based surveillance infrastructure is compressing replacement cycles as building operators face simultaneous pressure from cybersecurity mandates and AI-enabled analytics requirements.
Growth Catalysts
- EU AI Act conformity assessments:Biometric analytics deployments across member states require certified hardware, accelerating hardware refresh timelines for legacy installations.
- Power-over-Ethernet standardization:Single-cable installations reduce labor costs and enable centralized cable management in commercial retrofits.
- Smart building integration:Facility managers in Germany and the United States prioritize occupancy analytics for HVAC optimization and space utilization.
Market Restraints
- Image sensor supply concentration:Fabrication capacity clusters in East Asian foundries, exposing procurement to geopolitical disruption and allocation constraints.
- GDPR biometric processing restrictions:Facial recognition deployments in European retail and hospitality require explicit consent frameworks that limit automated analytics adoption.
- Silicon carbide substrate costs:Advanced low-light sensor substrates carry 40-60% premiums over standard CMOS alternatives, constraining budget-constrained municipal bids.
Strategic Opportunities
- India commercial real estate modernization:PLI scheme incentives for electronics manufacturing are attracting domestic assembly investments for cost-optimized IP camera production.
- Cloud-native video management platforms:Subscription-based analytics tiers are displacing perpetual-license on-premise software in mid-market enterprise accounts.
- Edge AI inference acceleration:On-camera processing of motion detection and object classification reduces bandwidth requirements for remote facility monitoring.
Industry Challenges
- Cybersecurity certification timelines:DIN-certified protocol validation for European critical infrastructure bids extends product qualification cycles by 8-14 months.
- Legacy analog integration complexity:Hybrid NVR deployments require protocol translation layers that increase system failure points and maintenance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in Ceiling Camera Market |
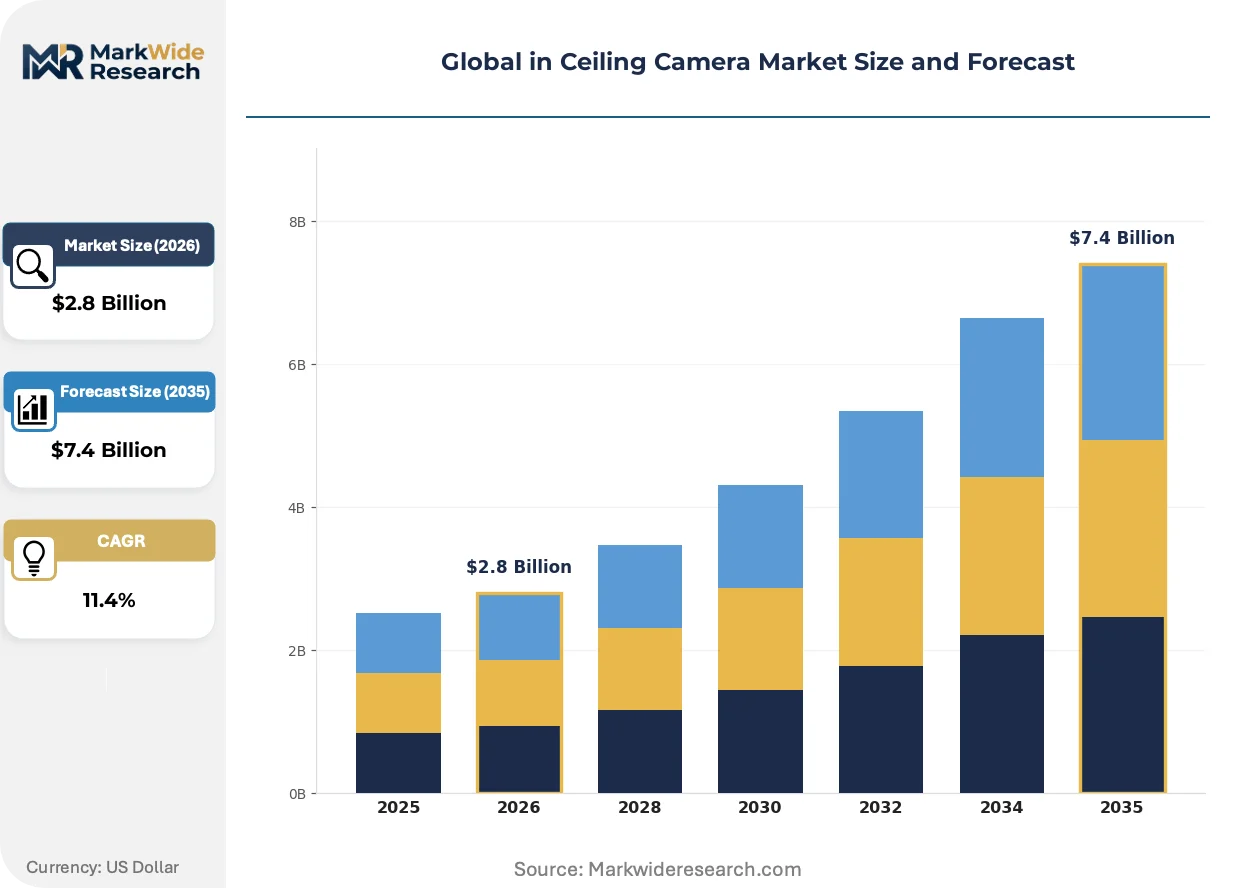
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cameras, PTZ Cameras, Dome Cameras, Bullet Cameras Technology: Analog, IP-Based, Wired, Wireless End User: Retail, Hospitality, Education, Healthcare Installation Type: Indoor, Outdoor, Suspended, Integrated |
| Companies Covered | Axis Communications, Hangzhou Hikvision Digital Technology, Bosch Security Systems, FLIR Systems, Zhejiang Dahua Technology, Honeywell Security Group, Panasonic Holdings Corporation, Sony Corporation, Hanwha Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in Ceiling Camera Market Strategic Shifts
Video analytics processing is migrating from centralized servers to edge devices, restructuring hardware specifications and vendor value capture across enterprise security deployments.
Multi-sensor panoramic cameras with stitched 360-degree fields of view are consolidating demand previously served by multiple fixed-position units. Large-format retail operators in the United States are standardizing on these devices for aisle coverage, reducing camera counts per square meter by 60-70% while maintaining forensic detail. The technology is consolidating supplier relationships as fewer vendors command the optical calibration and dewarping software expertise required for seamless deployment.
China's GB/T network security certification from MIIT now mandates firmware signing and encrypted boot sequences for IP cameras connected to public infrastructure. Manufacturers must maintain dual firmware streams—one for domestic compliance and another for export markets with different cryptographic requirements. Critical infrastructure operators in transportation and energy verticals face the steepest compliance burdens, with procurement specifications hardening faster than vendor certification timelines.
Building automation system integrators are bundling surveillance hardware into comprehensive facility management contracts, displacing standalone security contractor relationships. End-users in German commercial real estate now procure cameras through mechanical-electrical-plumbing specification packages rather than separate security tenders. This channel consolidation favors vendors with BACnet and Modbus protocol compatibility, compressing margins for pure-play camera manufacturers lacking building systems integration expertise.
Global in Ceiling Camera Market Segmentation
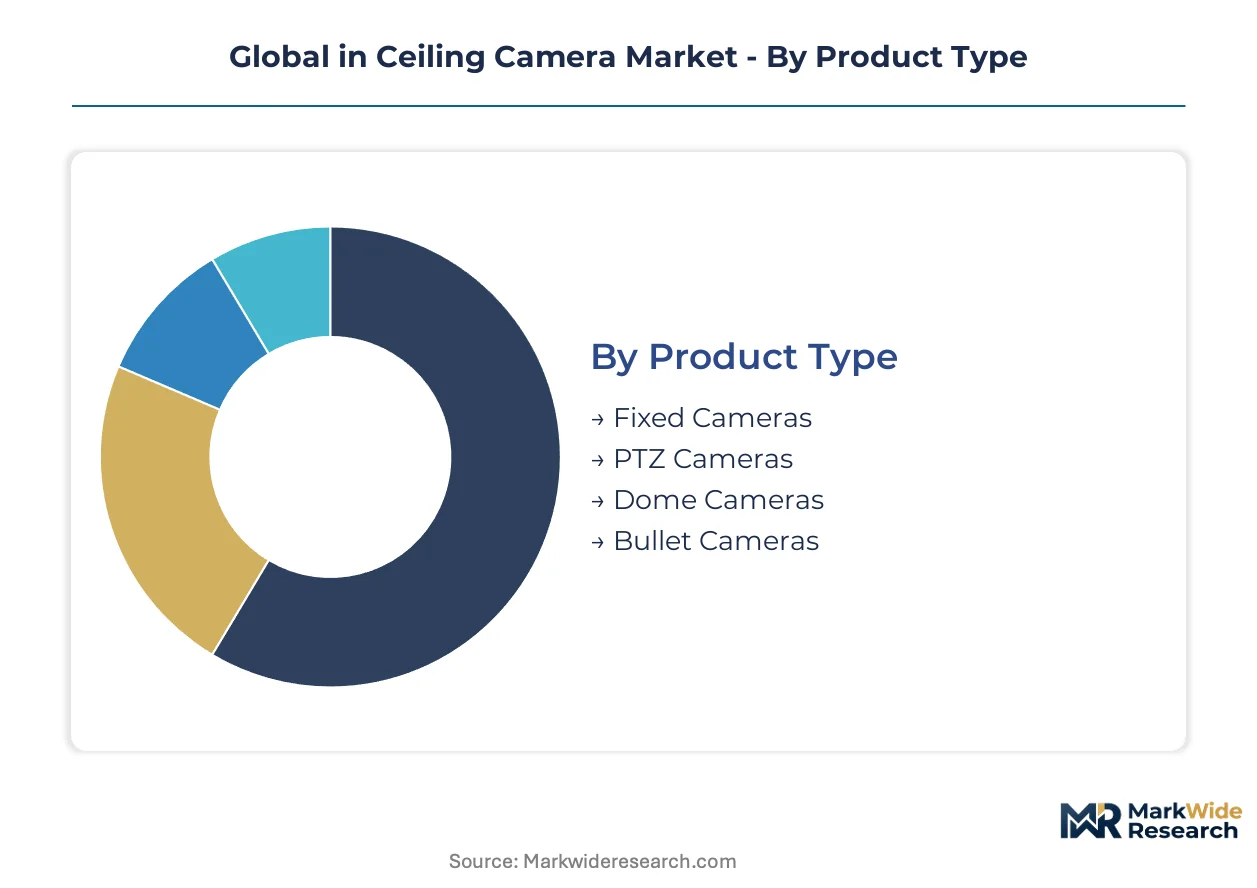
Segmentation in the in-ceiling camera market reveals how procurement specifications diverge across building automation maturity levels and regulatory environments. Understanding these divides enables vendors to align firmware development, certification investments, and channel partnerships with addressable demand pools.
Product Type:
Supply concentration in motorized actuator manufacturing tilts competitive advantage toward vendors with captive production or long-term supplier agreements.
- Fixed Cameras:Stationary units with fixed focal lengths and minimal illumination thresholds below 0.01 lux serve baseline loss-prevention requirements. German retail chains and US corporate campuses deploy these for aisle monitoring and perimeter coverage where scene dynamics remain predictable.
- PTZ Cameras:Motorized pan-tilt-zoom actuators enable dynamic scene coverage through programmable patrol patterns and operator-controlled positioning. Hospitality operators in Las Vegas and Macau prioritize these for gaming floor surveillance where real-time tracking of mobile subjects dominates operational requirements.
- Dome Cameras:Vandal-resistant housings with smoked or mirrored covers conceal lens orientation from subjects.
- Bullet Cameras:Cylindrical housings with external mounting brackets suit suspended ceiling installations.
Fixed cameras absorb the bulk of installed capacity; PTZ cameras are expanding most quickly.
Technology:
Cost tier differentiation separates premium IP deployments from budget-constrained analog retrofits.
- Analog:Coaxial-cable transmission with CVBS signaling persists in developing economies and legacy building stock where cable replacement costs dominate procurement decisions. Municipal budgets in India and Southeast Asia sustain demand despite limited analytics compatibility.
- IP-Based:Ethernet connectivity with H.265 compression and ONVIF interoperability enables cloud-managed analytics and centralized VMS integration. US healthcare systems and German commercial real estate operators mandate IP architectures for GDPR and HIPAA audit trails.
- Wired:Ethernet or coaxial physical layer eliminates radio-frequency interference concerns in dense deployments.
- Wireless:Wi-Fi 6 or proprietary mesh protocols reduce cabling labor in historic building retrofits.
IP-based technology captures dominant volume share; wireless configurations are climbing the fastest.
End User:
Application-specific performance requirements drive firmware customization and lens specification divergence.
- Retail:Occupancy analytics integration with POS systems and heat-mapping software for merchandising optimization. US big-box operators standardize on multi-sensor panoramic units for aisle coverage consolidation.
- Hospitality:Discreet form factors with audio privacy masking and low-light performance for lobby and corridor monitoring. Dubai and Singapore luxury properties demand bronze-finish housings matching interior design specifications.
- Education:Vandal-resistant dome housings with wide dynamic range for cafeteria and hallway coverage.
- Healthcare:Antimicrobial surface coatings and HIPAA-compliant encryption for patient area monitoring.
Retail absorbs the bulk of installed capacity; healthcare is gaining share fastest.
Installation Type:
Customer type segmentation separates specification-driven integrators from price-sensitive direct procurement.
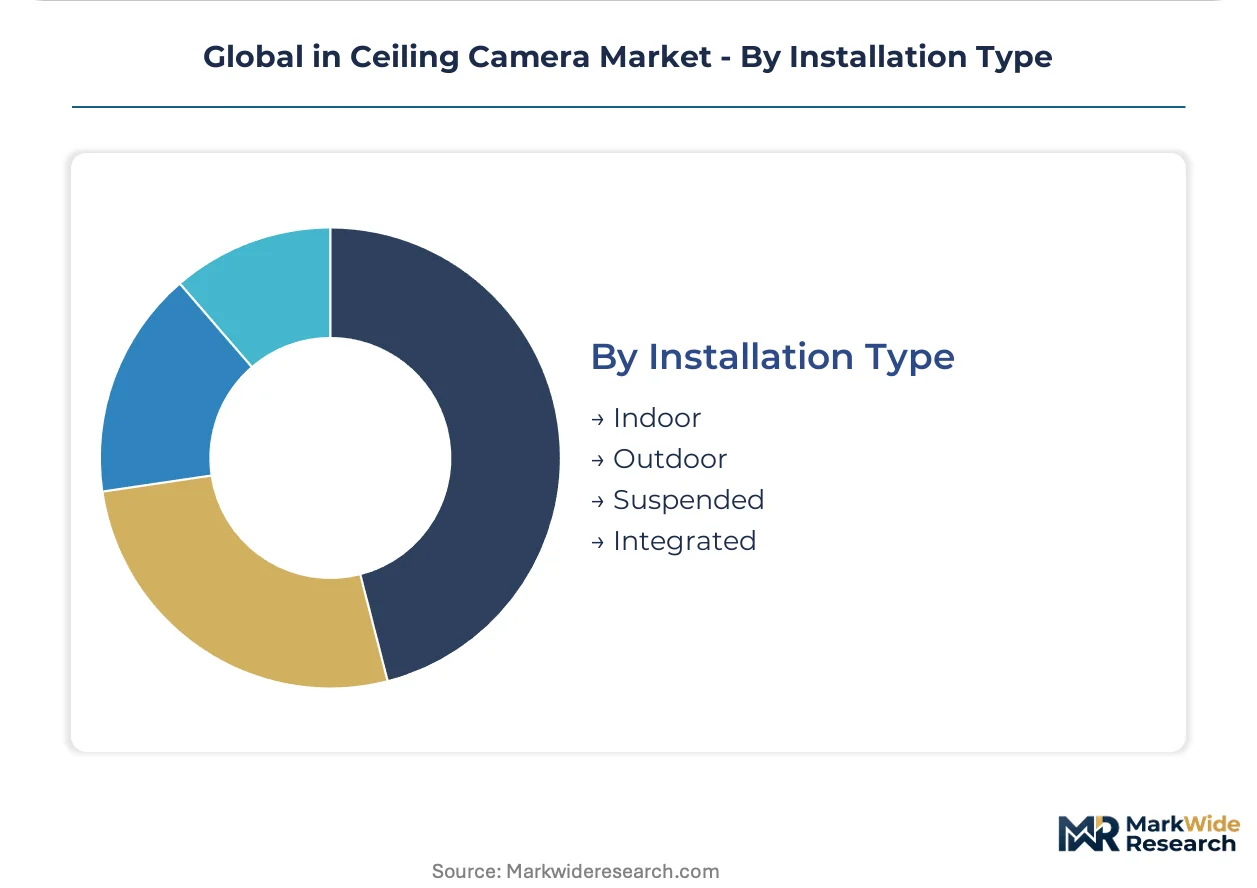
- Indoor:Flush-mount ceiling cavities with drop-tile compatibility and PoE single-cable installation dominate commercial new construction. German MEP contractors bundle these into comprehensive building automation specifications.
- Outdoor:IP66-rated housings with integrated heaters and hydrophobic lens coatings withstand temperature cycling and precipitation. Transportation authorities in Texas and California deploy these for transit station coverage.
- Suspended:Pendant-mount adapters for exposed ceiling structures and atrium installations.
- Integrated:Custom millwork concealment within architectural ceiling features for premium hospitality environments.
Indoor installations absorb the bulk of installed capacity; integrated configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabrication clusters supply image sensors to assembly operations across Germany, the United States, and China. Consumption concentrates in commercial real estate modernization programs where regulatory compliance accelerates hardware refresh cycles.
United States
Corporate campus security budgets and smart building automation specifications drive procurement volumes. FCC equipment authorization governs wireless in-ceiling models for radio-frequency compliance. Dallas-Fort Worth metroplex facilities managers bundle surveillance hardware into mechanical-electrical-plumbing contracts for new commercial construction.
Germany
Commercial real estate operators prioritize occupancy analytics integration with building management systems. EU AI Act conformity assessments mandate certified hardware for biometric analytics deployments across member states. Frankfurt Rhine-Main logistics hubs deploy DIN-certified cybersecurity protocols for critical infrastructure surveillance tenders.
China
Domestic demand concentrates in transportation and energy verticals requiring public infrastructure connectivity. MIIT GB/T standards mandate network security certification with firmware signing and encrypted boot sequences. Shenzhen manufacturing clusters maintain dual firmware streams for domestic compliance and export market cryptographic requirements.
India
Commercial real estate modernization and municipal security upgrades sustain procurement momentum. PLI scheme incentives for electronics manufacturing attract domestic assembly investments for cost-optimized IP camera production. Mumbai and Bengaluru facility managers prioritize PoE single-cable installations in retrofit scenarios.
Japan
Hospitality and retail operators demand discreet form factors with low-light performance for premium interior environments. METI industrial standards guide building automation system interoperability specifications. Tokyo and Osaka luxury properties specify bronze-finish housings matching interior design requirements.
Global in Ceiling Camera Market Competitive Environment
Top-tier vendors anchor premium-tier positioning through cybersecurity certification and open-platform architectures, while mid-tier specialists compete on cost-optimized assembly and regional distribution density. The vendor base stratifies across three archetypes: integrated electronics conglomerates with captive sensor fabrication, pure-play security specialists with developer ecosystem loyalty, and regional fabricators leveraging domestic certification pathways. Dominant competitive moves include backward integration into image sensor supply and strategic partnerships with building automation system integrators.
Within the integrated electronics tier, Hangzhou Hikvision Digital Technology and Zhejiang Dahua Technology represent Chinese-origin manufacturers with scale-driven positioning. Bosch Security Systems, a German GmbH-structured entity, exemplifies the premium-tier vector through European critical infrastructure focus. Axis Communications, a Swedish-based open-platform specialist, occupies a position emphasizing developer ecosystem cultivation across enterprise accounts.
| Leading Market Players |
|---|
| Axis Communications |
| Hangzhou Hikvision Digital Technology |
| Bosch Security Systems |
| FLIR Systems |
| Zhejiang Dahua Technology |
| Honeywell Security Group |
| Panasonic Holdings Corporation |
| Sony Corporation |
| Hanwha Vision |
| Others |
Value Chain & Pricing Dynamics
Captive production of image sensors by Hangzhou Hikvision Digital Technology and Zhejiang Dahua Technology anchors both supply security and pricing power for these integrated electronics conglomerates, while pure-play assemblers without upstream sensor access face margin compression during allocation cycles.
Pricing Analysis
Margin tightening in the mid-tier standard segment reflects silicon carbide substrate premiums and DIN-certified cybersecurity validation costs. Three-tier pricing structure across premium certified, standard IP, and economy analog levels separates vendors by compliance grade and integration depth. Cost-down pressure on municipal and education bids accelerates because India's PLI scheme incentives attract domestic assemblers competing on landed cost. Healthcare systems in the United States exhibit lowest price sensitivity due to HIPAA audit trail mandates, while Southeast Asian municipal retrofits show highest sensitivity to per-unit equipment costs.
Supply Chain Analysis
Dual-sourcing requirements from German critical infrastructure operators and US corporate campus integrators mandate qualified secondary suppliers for image sensors and motorized actuators. Fabrication capacity clusters in China, South Korea, and Taiwan for CMOS sensors and optical components. Final assembly draws from China, Germany, and Mexico for regional market access. Single-source vulnerability concentrates in East Asian foundry capacity for advanced low-light substrates. Distribution runs through building automation system integrators and mechanical-electrical-plumbing contractors rather than standalone security channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act conformity assessment framework creates a compliance moat that favors incumbents with certified hardware portfolios, elevating cost-of-entry for unqualified competitors and compressing viable addressable market for marginal players.
For Market Incumbents: Anticipate channel consolidation toward building automation integrators by deepening BACnet and Modbus protocol compatibility investments. Defend against cloud-native video management platform displacement through recurring software tier development. Prioritize DIN-certified cybersecurity protocol maintenance for European critical infrastructure tender eligibility. Expand captive sensor fabrication capacity to reduce allocation risk exposure.
For New Entrants and Emerging Players: Launch via cloud-native subscription models targeting mid-market enterprise accounts in India and Southeast Asia where perpetual-license on-premise software still dominates. Exploit underpenetrated healthcare verticals in Japan and Germany requiring antimicrobial coatings and HIPAA-equivalent encryption. Target integrated architectural concealment configurations for luxury hospitality properties in Dubai and Singapore specifying bronze-finish aesthetic matching.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated electronics conglomerates seeking cybersecurity certification assets and open-platform developer ecosystems. Long-term viability favors vendors with dual firmware stream capabilities for China's GB/T domestic compliance and export cryptographic requirements. Monitor EU AI Act enforcement consistency as inflection indicator for certified hardware premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Inference Acceleration | On-camera processing reduces bandwidth costs for remote facility monitoring deployments. |
| Multi-Sensor Panoramic Consolidation | 360-degree units displace multiple fixed cameras in US retail aisle coverage specifications. |
| Cloud-Native Platform Migration | Subscription analytics tiers displace perpetual licenses in mid-market enterprise accounts. |
| Dual Firmware Stream Maintenance | Separate cryptographic streams satisfy China's GB/T and export market requirements simultaneously. |
| Building Automation Integration | BACnet protocol compatibility captures German MEP bundled procurement specifications. |
Study Parameters
Document review covered regulatory filings from FCC, EU AI Act implementation guidance, and China's MIIT GB/T standards, complemented by interviews with facility managers, security system integrators, building automation specification engineers, and procurement officers at corporate campuses and healthcare systems. Secondary validation drew from customs trade data, SEC 10-K disclosures, and building automation industry association reports. Bottom-up demand modeling triangulated against top-down market sizing across product type, technology, and end-user segmentation dimensions.
Unit shipment and revenue projections across the analysis window reflect penetration modeling by installation type and regional regulatory cluster. Segmentation dimensions included product architecture, connectivity protocol, end-use vertical, and building automation maturity tier. CAGRs derived from replacement cycle compression rates and smart building integration adoption curves. Forecast inputs incorporated Power-over-Ethernet installation labor cost trajectories and image sensor foundry capacity expansion announcements.
The model assumes a particular edge AI inference adoption path; alternative pathways for centralized server-based analytics would alter the bandwidth and hardware specification outlook. Forecasts reflect assumptions regarding EU AI Act enforcement timing, China GB/T certification pace, and cloud platform interoperability standardization. Deviation in geopolitical trade restrictions affecting East Asian sensor fabrication would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Functional Near-Infrared Optical Brain Imaging Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
Cinematographic Camera Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Global AI in Computer Vision Market
Imaging
Global Microbolometer Market
Imaging
Global Label-Free Array Systems Market
Imaging
Global Image Signal Processor Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
APAC Image Sensors Market
Imaging
Virtual Reality Camera Market
Imaging
Machine Vision System and Services Market
Imaging
Hybrid Imaging Systems Market
Imaging
Uncooled Infrared Camera Market
Imaging
Side View Camera System Market
Imaging
Thermal Camera Market