
 Bulb Market | 2026-2036
Bulb Market Size, Share, and Industry Trends Forecast 2026-2036
Bulb Market Analytics
Chip-on-board LED packaging is reconfiguring thermal management and lumen density in bulb manufacturing. Signify anchors European smart lighting deployment through its connected infrastructure portfolio. Cree LED specializes in silicon carbide substrates that sustain higher efficacy thresholds in commercial retrofit projects. Samsung Electronics leverages vertical integration from semiconductor fabs to finished luminaires, dominating Asia-Pacific supply chains.
A bulb is a sealed glass or polymer enclosure containing a filament, arc tube, or solid-state emitter that converts electrical energy into visible light, with LED variants typically delivering 80-150 lumens per watt and rated lifespans exceeding 25,000 hours. LED type segments lead value generation as incandescent bans propagate across jurisdictions, while halogen form factors retain niche positions in decorative and directional applications. Smart lighting technology segments are capturing margin pools through sensor-integrated controls, though motion sensing capabilities remain concentrated in industrial and outdoor deployment channels.
The EU Green Deal and Ecodesign directives are eliminating most halogen and incandescent sales across member states, while the EPA ENERGY STAR program shapes North American procurement specifications for efficacy and color rendering index thresholds. China's GB standards and NMPA-equivalent quality certifications govern export eligibility for manufacturers serving domestic and international markets. Stakeholders must monitor regulatory phase-out calendars and solid-state efficacy roadmaps to time capacity transitions and avoid stranded inventory positions.
Market Dynamics
The EU Green Deal and Ecodesign directives are systematically eliminating halogen and incandescent technologies, compressing legacy inventory cycles and forcing capacity reallocation toward solid-state emitters with efficacy thresholds above 80 lumens per watt.
Growth Catalysts
- Residential retrofit mandates:Germany's federal building efficiency programs and France's MaPrimeRénov scheme are accelerating LED replacements in single-family housing stock.
- REACH compliance deadlines:Phased mercury restrictions under EU chemical regulations are eliminating compact fluorescent lamp production lines ahead of schedule.
- Urban infrastructure renewal:Streetlight modernization programs in China and the United States are concentrating demand for high-lumen outdoor luminaires with connected control compatibility.
Market Restraints
- Rare earth supply concentration:Neodymium and europium dependency on Chinese processing facilities creates pricing volatility for phosphor formulations in warm-white LED variants.
- Technical efficacy ceiling:Quantum dot integration has stalled near 200 lumens per watt in commercial packages, limiting differentiation in premium segments.
- Regulatory fragmentation:Divergent testing protocols between EPA ENERGY STAR and China's GB standards inflate certification costs for cross-border suppliers.
Strategic Opportunities
- Human-centric lighting protocols:Circadian rhythm tuning specifications in healthcare and education facilities are opening specification-grade margins beyond commodity replacement cycles.
- Li-Fi convergence:Integration of visible light communication transceivers into commercial downlights is enabling data transmission infrastructure in electromagnetic-sensitive environments.
- Secondary market channels:Refurbished commercial luminaire programs through industrial auction platforms are capturing price-sensitive demand in Midwestern US manufacturing corridors.
Industry Challenges
- Thermal engineering talent scarcity:Chip-on-board packaging expertise resides with a narrow cohort of semiconductor veterans, constraining R&D velocity at mid-tier manufacturers.
- Legacy dimmer incompatibility:TRIAC phase-cut controls in installed residential bases create field failure rates that erode brand equity and drive warranty costs.
- IP licensing complexity:Patent thickets around remote phosphor architectures and thermal interface materials generate royalty stacking that compresses gross margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulb Market |
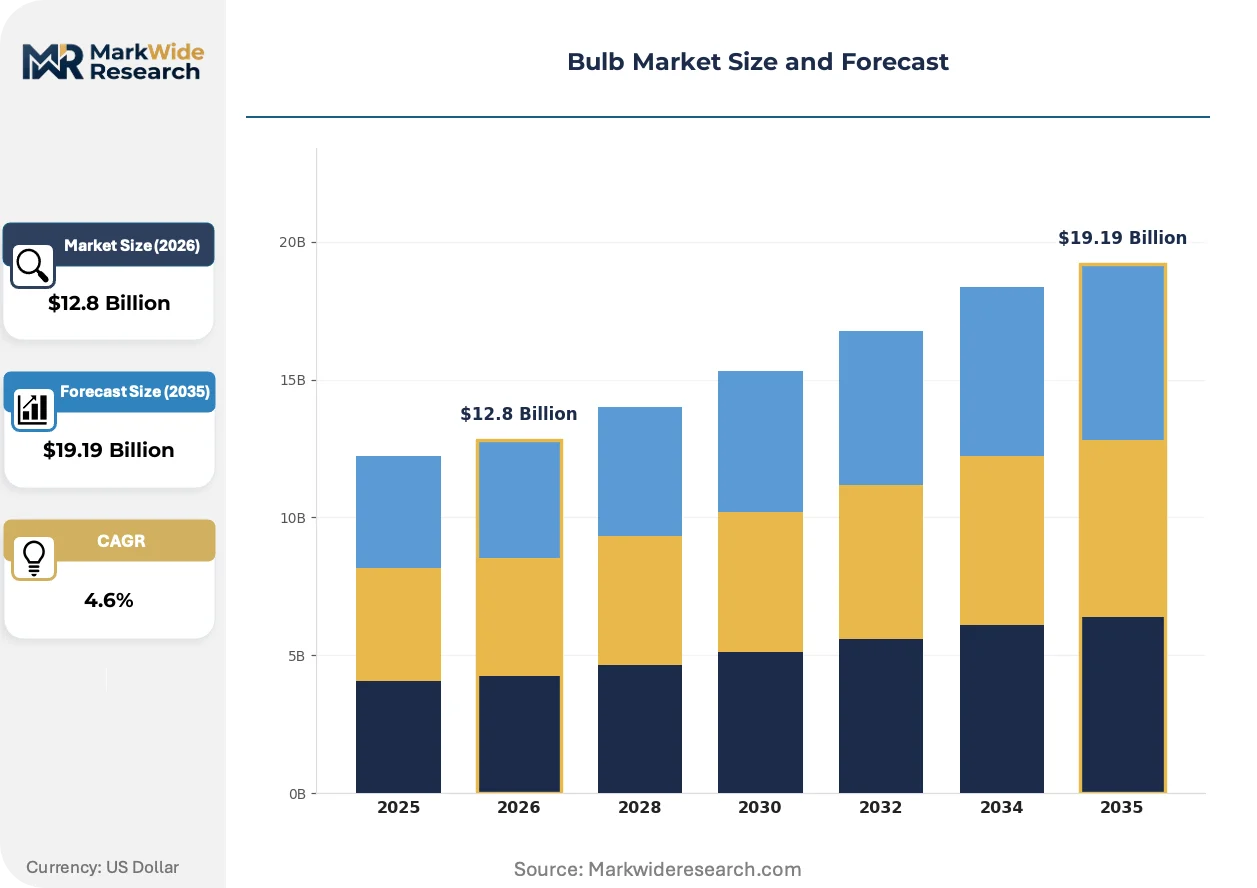
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Incandescent, LED, Halogen, Fluorescent Application: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, Dimming, Color Changing, Motion Sensing Form: Bulb Shape, Miniature, Floodlight, Decorative |
| Companies Covered | Samsung Electronics, Current (Formerly GE Current), Signify (Philips Lighting), Cree LED, Nichia Corporation, Acuity Brands, Cooper Lighting, Zumtobel Group, Osram, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulb Market Evolving Landscape
Three intersecting developments are compressing product lifecycles and redrawing competitive boundaries: solid-state virtualization of optical control, regulatory acceleration of chemical phase-outs, and procurement consolidation around specification-grade performance metrics.
Chip-on-board LED architectures are virtualizing thermal management and optical beam shaping through integrated silicone lenses that eliminate secondary reflector assemblies. Commercial retrofit contractors in Germany and the Netherlands are specifying these packages for high-bay industrial applications where lumen maintenance targets exceed 50,000 hours. This virtualization is collapsing the traditional distinction between lamp and luminaire manufacturing, forcing component suppliers to assume system-level design responsibility.
The EU F-Gas Regulation and REACH Annex XVII amendments are banning mercury-containing discharge lamps with accelerated timelines that outpace natural replacement cycles. Manufacturers serving the European market must now absorb stranded inventory costs for fluorescent tube stockpiles while retooling production lines for solid-state alternatives. The commercial office vertical is experiencing the most acute disruption, as facility managers face compressed procurement windows for T8 and T5 replacements.
Building automation integrators are consolidating lighting specification authority away from electrical distributors and toward controls-focused system houses. This channel shift concentrates procurement volume with firms capable of delivering sensor-integrated, network-addressable luminaires rather than commodity lamps. The pattern is most pronounced in California and New York, where state energy codes mandate automatic daylight harvesting and occupancy-based dimming in commercial construction.
Bulb Market Segmentation
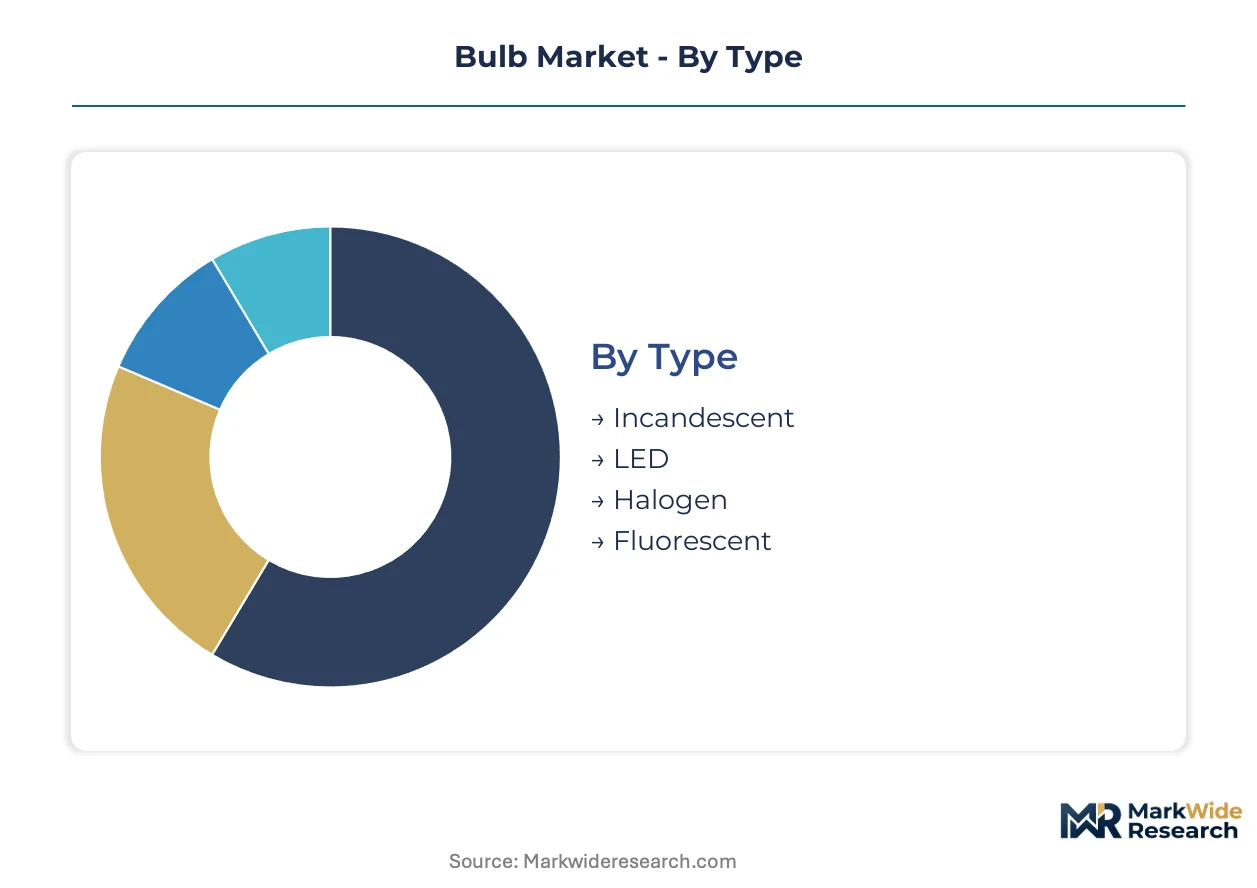
Bulb market segmentation reveals divergent replacement cycles that reshape inventory planning and channel strategy. LED variants compress turnover to 3-5 year intervals while legacy technologies face regulatory phase-outs that accelerate obsolescence.
Type:
Replacement velocity varies dramatically across emitter technologies, with solid-state packages cycling fastest and thermal filament designs approaching terminal decline.
- LED:Solid-state emitters utilizing semiconductor junctions achieve 80-150 lumens per watt with rated lifespans exceeding 25,000 hours. Residential retrofit mandates in Germany and France are concentrating demand for A-shape and globe variants as Ecodesign directives eliminate competing technologies.
- Incandescent:Tungsten filament construction delivers 10-17 lumens per watt with sub-2,000 hour lifespans. EU Green Deal prohibitions have collapsed legal sales channels across member states, relegating remaining volume to specialty exempt applications and residual inventory liquidation.
- Halogen:Tungsten-halogen regenerative cycle extends output to 15-25 lumens per watt for 2,000-4,000 hours. Decorative and directional niches in hospitality lighting retain specification authority despite broader phase-out schedules.
- Fluorescent:Mercury vapor discharge through phosphor-coated tubes achieves 50-100 lumens per watt. REACH Annex XVII mercury restrictions are eliminating compact fluorescent production ahead of natural replacement cycles, stranding commercial office inventories.
LED anchors the volume base while halogen gains share at the steepest rate among legacy categories facing regulatory compression.
Application:
Procurement authority concentrates differently across verticals, with facility managers consolidating specifications in commercial and industrial channels while residential remains fragmented across retail touchpoints.
- Residential:Single-family and multi-unit housing stock drives replacement demand through renovation incentives and efficiency mandates. Germany's federal building programs and France's MaPrimeRénov scheme are accelerating LED conversions in owner-occupied dwellings.
- Commercial:Office, retail, and hospitality verticals specify luminaire-integrated systems rather than commodity lamps. California and New York state energy codes mandate automatic daylight harvesting and occupancy-based dimming, shifting procurement toward controls-integrated packages.
- Industrial:High-bay manufacturing and warehouse facilities prioritize lumen maintenance targets exceeding 50,000 hours. German and Dutch retrofit contractors specify chip-on-board packages for thermal performance in continuous-operation environments.
- Outdoor:Streetlight modernization and area illumination programs concentrate demand for high-lumen packages with connected control compatibility. Urban infrastructure renewal in China and the United States is driving specification-grade procurement volumes.
Commercial applications command the highest specification authority while outdoor deployment expands most quickly through municipal modernization programs.
Technology:
Margin pools concentrate at the intersection of connectivity and sensor integration, though adoption velocity varies by capability complexity.
- Smart Lighting:Network-addressable luminaires with wireless protocol stacks enable centralized control and energy analytics. Building automation integrators in California and New York are consolidating specification authority away from electrical distributors toward controls-focused system houses.
- Dimming:Phase-cut and 0-10V protocols enable output modulation across operating hours. Legacy TRIAC controls in installed residential bases create field compatibility failures that erode brand equity and drive warranty cost inflation.
- Color Changing:Tunable white and RGB architectures adjust correlated color temperature for circadian or aesthetic applications. Healthcare and education facilities are opening specification-grade margins through human-centric lighting protocols.
- Motion Sensing:Passive infrared and microwave occupancy detection triggers automatic illumination. Capability deployment remains concentrated in industrial and outdoor channels where energy codes mandate automatic shutoff.
Smart Lighting captures the premium tier while motion sensing penetrates fastest through regulatory mandate expansion.
Form:
Physical configuration dictates thermal management architecture and optical control approach, with integrated luminaire designs displacing traditional lamp-replacement paradigms.
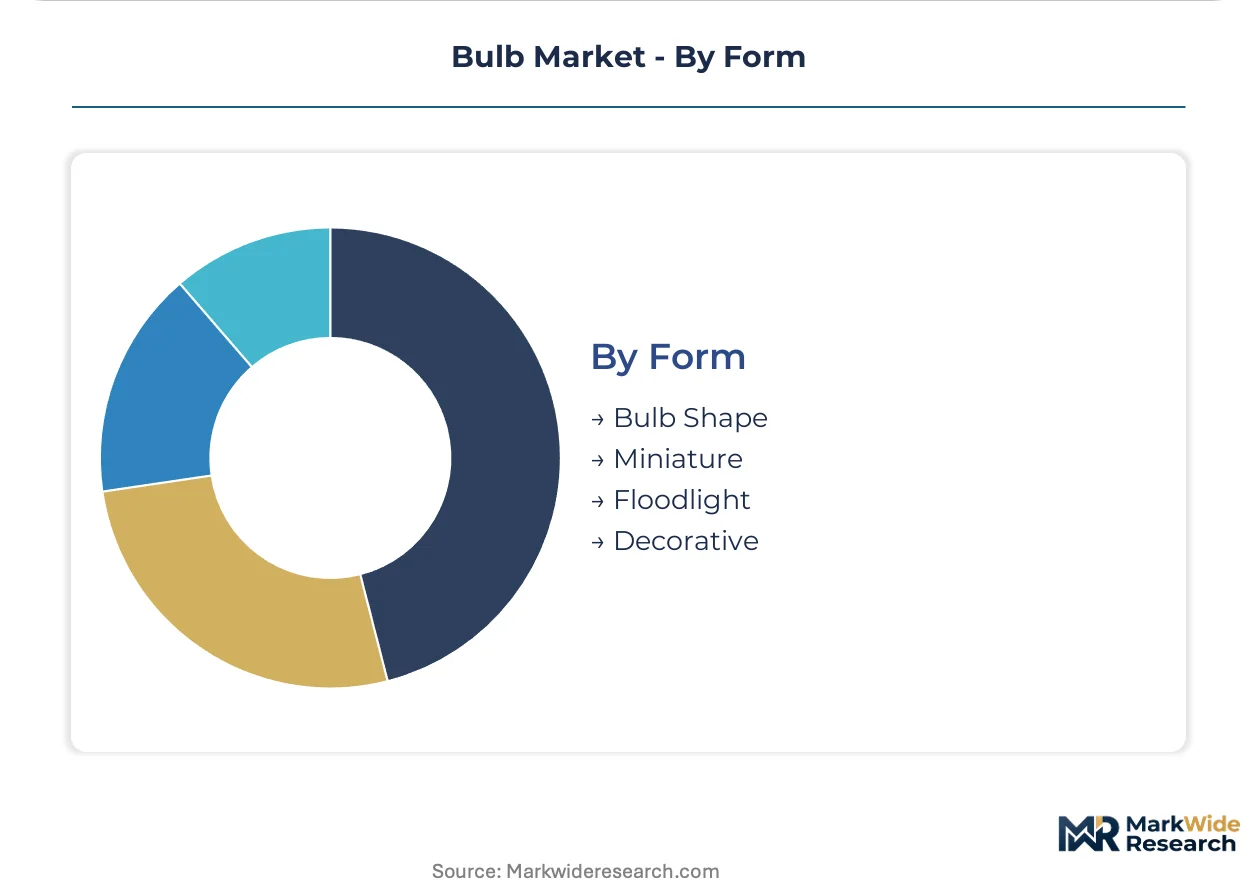
- Bulb Shape:Standardized A-series, globe, and candle geometries serve direct incandescent replacement applications. German and French residential retrofit programs concentrate demand for form-factor-compatible LED alternatives.
- Miniature:Compact footprints for appliance, automotive, and specialty fixture integration. REACH compliance deadlines for mercury-containing alternatives are accelerating solid-state substitution in compact fluorescent niches.
- Floodlight:Directional beam control for accent, security, and area illumination. Outdoor infrastructure renewal in China and the United States drives demand for high-lumen PAR and BR configurations with connected control compatibility.
- Decorative:Vintage filament, globe, and specialty geometries prioritize aesthetic output over raw efficacy. Hospitality and residential specification channels retain halogen and early-generation LED variants for ambiance applications.
Bulb Shape maintains the installed base while floodlight configurations expand most quickly through urban infrastructure renewal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics are reshaping bulb manufacturing geography. China maintains net export dominance in LED packages. Germany and the United States concentrate import demand for specification-grade luminaires.
China
Yangtze River Delta and Pearl River Delta clusters drive LED die and package production for global export markets. GB standards and NMPA-equivalent certifications govern export eligibility for manufacturers serving domestic and international demand. Shenzhen and Dongguan house vertically integrated production from semiconductor fabs through finished luminaire assembly.
Germany
Federal building efficiency programs and MaPrimeRénov-style retrofit incentives accelerate LED replacement in single-family housing stock. Ecodesign requirements under the EU Green Deal phase out inefficient technologies with accelerated timelines. Bavaria and North Rhine-Westphalia concentrate specification-grade manufacturing for commercial and industrial channels.
United States
Streetlight modernization and urban infrastructure renewal concentrate demand for high-lumen outdoor luminaires with connected control compatibility. EPA ENERGY STAR program shapes procurement specifications for efficacy and color rendering index thresholds. California and New York state energy codes mandate automatic daylight harvesting and occupancy-based dimming in commercial construction.
Japan
METI efficiency standards and JIS certification requirements drive premium-tier product development for domestic and select export markets. Kansai and Chubu regions maintain specialized manufacturing for high-efficacy chip-on-board packages. Osaka and Nagoya industrial corridors focus on thermal management innovations for continuous-operation environments.
India
Domestic LED adoption accelerates through UJALA scheme distribution and state-level energy efficiency programs. BIS certification and CEA regulations govern quality standards for residential and commercial procurement. Maharashtra and Gujarat house assembly operations serving price-sensitive replacement demand across South Asian markets.
Bulb Market Competitive Landscape
On the supply side, the industry is consolidating around semiconductor-backed conglomerates and controls-integrated system houses. Tier-one players leverage captive die production and thermal packaging expertise. Mid-tier specialists compete on retrofit compatibility and regional certification speed. Dominant competitive moves include backward integration into semiconductor fabrication and strategic partnerships with building automation integrators.
Among Asia-Pacific conglomerates, Samsung Electronics exemplifies scale-driven vertical control from semiconductor fabs through finished luminaires. Signify anchors the European smart lighting deployment archetype through connected infrastructure portfolios. Cree LED represents the specialized substrate tier with silicon carbide thermal management capabilities for commercial retrofit specifications.
| Leading Market Players |
|---|
| Samsung Electronics |
| Current (Formerly GE Current) |
| Signify (Philips Lighting) |
| Cree LED |
| Nichia Corporation |
| Acuity Brands |
| Cooper Lighting |
| Zumtobel Group |
| Osram |
| Others |
Value Network & Pricing Analysis
Rare earth supply concentration in Chinese processing facilities for neodymium and europium determines both the spread between warm-white premium tiers and economy phosphor formulations and the geographic clustering of die packaging capacity in the Yangtze and Pearl River Delta manufacturing corridors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the bulb market. Price differentiation stems from certification grade attainment under EPA ENERGY STAR or EU Ecodesign tiers and from volume scale commitments in municipal procurement programs. Cost compression in economy phosphor formulations is intensifying because of rare earth pricing volatility. Residential retrofit contractors exhibit the highest price sensitivity, while healthcare and education facility managers prioritize human-centric lighting specifications over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with vertically integrated electronics manufacturing services in Shenzhen and Dongguan that control LED die bonding and luminaire final assembly. Geographic supply concentration centers on China for die and package production, Germany for specification-grade commercial luminaires, and the United States for connected control integration. Raw material dependencies draw from silicon carbide substrates, rare earth phosphors, and aluminum thermal interface materials. Single-source vulnerability in Chinese rare earth processing creates exposure to export restriction shocks. Distribution runs through building automation integrators in California and New York, electrical distributors in Midwestern manufacturing corridors, and industrial auction platforms for refurbished commercial luminaires.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bulb market sits in early-cycle expansion as residential retrofit mandates across Germany and France accelerate LED penetration in single-family housing stock still operating legacy incandescent and halogen inventories.
For Market Incumbents: Harden thermal engineering capabilities through captive chip-on-board packaging expertise to defend against mid-tier manufacturers constrained by semiconductor talent scarcity. Deepen backward integration into silicon carbide substrate production to secure efficacy thresholds above 150 lumens per watt for commercial retrofit specifications. Consolidate specification authority with building automation integrators before channel control shifts permanently toward controls-focused system houses.
For New Entrants and Emerging Players: Establish a beachhead in secondary market channels for refurbished commercial luminaires across Midwestern US manufacturing corridors where price-sensitive demand concentrates. Target human-centric lighting protocols in healthcare and education facilities where circadian rhythm tuning specifications open specification-grade margins beyond commodity replacement cycles. Pursue a go-to-market angle through Li-Fi convergence partnerships for electromagnetic-sensitive environments requiring data transmission infrastructure.
For Investors and Strategic Acquirers: EU REACH Annex XVII mercury restrictions reshape the acquisition landscape by eliminating compact fluorescent production lines and stranding commercial office inventories ahead of natural replacement cycles. Long-term viability favors targets with chip-on-board thermal packaging expertise and established certification pathways under EPA ENERGY STAR and EU Ecodesign directives. The acquisition target archetype is mid-tier manufacturers with retrofit compatibility libraries but lacking semiconductor fabrication depth. Monitor regulatory phase-out calendars for halogen and incandescent technologies as the signal to time capacity transitions and avoid stranded inventory positions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Fabrication | Captive LED die production secures thermal management expertise and insulates against rare earth phosphor volatility. |
| Human-Centric Lighting Certification Investment | Circadian rhythm tuning specifications in healthcare and education facilities unlock specification-grade margin pools. |
| Building Automation Integrator Partnership | Channel consolidation in California and New York shifts procurement authority toward controls-focused system houses. |
| Li-Fi Communication Module Integration | Visible light communication transceivers enable data transmission infrastructure in electromagnetic-sensitive environments. |
| Secondary Market Channel Development | Refurbished commercial luminaire programs capture price-sensitive demand in Midwestern US manufacturing corridors. |
Research Methodology
The analysis maps LED type segments, application verticals, and technology capability tiers, each validated through primary interviews with thermal packaging engineers, building automation integrators, commercial facility managers, and electrical distributor procurement leads. Secondary sources include EPA ENERGY STAR certification databases, EU Ecodesign directive implementation reports, customs and trade flow data for LED package exports, and SEC filings from semiconductor-backed lighting conglomerates. Bottom-up demand modeling triangulates against top-down regulatory phase-out calendar impacts.
Assumptions held fixed across the projection horizon include EU Green Deal Ecodesign enforcement timelines and Chinese rare earth export quota stability, while variables tested include municipal streetlight modernization funding levels and residential retrofit incentive program expansion rates. Segmentation dimensions modeled span emitter technology type, application vertical, smart lighting capability tier, and regional regulatory cluster. CAGRs derive from replacement cycle compression analysis and regulatory mandate acceleration effects. Industry-specific forecast inputs include lumen maintenance degradation curves and connected control protocol adoption rates.
Stress conditions across rare earth pricing volatility, REACH compliance deadline acceleration, and TRIAC dimmer compatibility failure rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that regulatory fragmentation between EPA ENERGY STAR and China's GB standards could revise cross-border supplier volume projections. Quarterly review of municipal procurement award announcements and phosphor formulation cost indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Illuminating Signs Market
Lighting
Architectural Lighting Market
Lighting
Dimmers Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Softbox Lighting Kit Market
Lighting
Digital Light Processing Technology Market
Lighting
EV Lighting Market
Lighting
OLED Lightening Panels Market
Lighting
Ultraviolet Lamps Market
Lighting
LED Solar Lighting Market
Lighting
Smart Lamp Market
Lighting
Bacteriological Light Market
Lighting
India Lighting Market
Lighting
Industrial Lighting Cybersecurity Market
Lighting
Hazardous Location LED Lighting Market