
 Type-C Bulk Bags Market | 2026-2036
Type-C Bulk Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Type-C Bulk Bags Market Outlook
China is rewriting capacity dynamics for Type-C bulk bags as domestic woven polypropylene output scales to serve Asia-Pacific chemical processing. Berry Global Inc. leverages integrated film extrusion capabilities to control resin costs across its manufacturing footprint. Mondi Group anchors European supply through certified conductive bag production for pharmaceutical clients. National Bulk Bag competes on custom sizing and rapid turnaround for North American agricultural distributors.
Type-C bulk bags are woven polypropylene containers with interwoven conductive threads or insulating coatings designed to safely dissipate static electricity during filling and discharge of flammable powders. These bags typically incorporate polyethylene liners and must meet IEC 61340-4-4 standards for electrostatic protective properties, serving primarily to prevent combustible dust incidents in chemical and pharmaceutical handling. The conductive segment leads value generation due to stringent hazardous material protocols in European and North American chemical processing, while insulated variants represent the fastest-growing category as pharmaceutical cold-chain requirements expand. Composite constructions blending conductive threads with barrier films command premium positioning where multi-hazard protection is required.
REACH in Europe mandates full material disclosure for chemical-contact packaging, compelling reformulation of conductive coatings to eliminate restricted substances. FDA guidelines for pharmaceutical contact materials require extractables and leachables testing that extends certification timelines for new bag constructions. ISO 21898 provides the foundational design and testing framework that most national regulators reference for flexible intermediate bulk container safety. Stakeholders must monitor evolving static safety standards and regional chemical restriction lists to maintain product access across jurisdictions.
Market Dynamics
REACH compliance deadlines in Europe are compressing certification timelines for conductive coating reformulations, forcing manufacturers to accelerate extractables testing while maintaining IEC 61340-4-4 electrostatic safety performance across multi-layer constructions.
Growth Catalysts
- REACH material disclosure mandates:European chemical handlers must document every substance in packaging-contact layers, creating captive demand for certified Type-C bags with full formulation transparency.
- Pharmaceutical cold-chain expansion:Insulated Type-C variants with static-dissipative properties are capturing share in temperature-sensitive active pharmaceutical ingredient transport.
- German industrial chemical clustering:Dense concentrations of flammable powder processors around Ludwigshafen and Leverkusen sustain specialized bulk containment procurement at scale.
Market Restraints
- Polypropylene resin volatility:Woven fabric costs fluctuate with propylene feedstock prices, squeezing margin stability for mid-tier converters without captive resin supply.
- Chinese woven fabric concentration:Over half of global polypropylene tape extrusion capacity sits in Zhejiang and Shandong provinces, creating single-source vulnerability for European and North American bag finishers.
- Biodegradable substitute emergence:Starch-based flexible bulk containers for non-hazardous agricultural applications are capturing share in price-sensitive grain handling.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO requirements for static-safe active ingredient export packaging are opening demand for IEC-certified Type-C constructions among Mumbai and Hyderabad formulation hubs.
- Dual carbon compliance in China:MEE emissions tracking for chemical logistics is favoring reusable bulk container systems with documented lifecycle carbon footprints.
- Barrier film convergence:Combining conductive thread grids with ethylene vinyl alcohol oxygen barriers is hybridizing Type-C bags for moisture-sensitive explosive powder handling.
Industry Challenges
- IEC 61340-4-4 testing bottleneck:Limited accredited laboratories in Europe and North America extend certification queues to six months, delaying new product launches.
- Conductive thread integration precision:Automated weaving systems require recalibration for static-dissipative yarn placement, demanding capital investment that smaller converters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Type-C Bulk Bags Market |
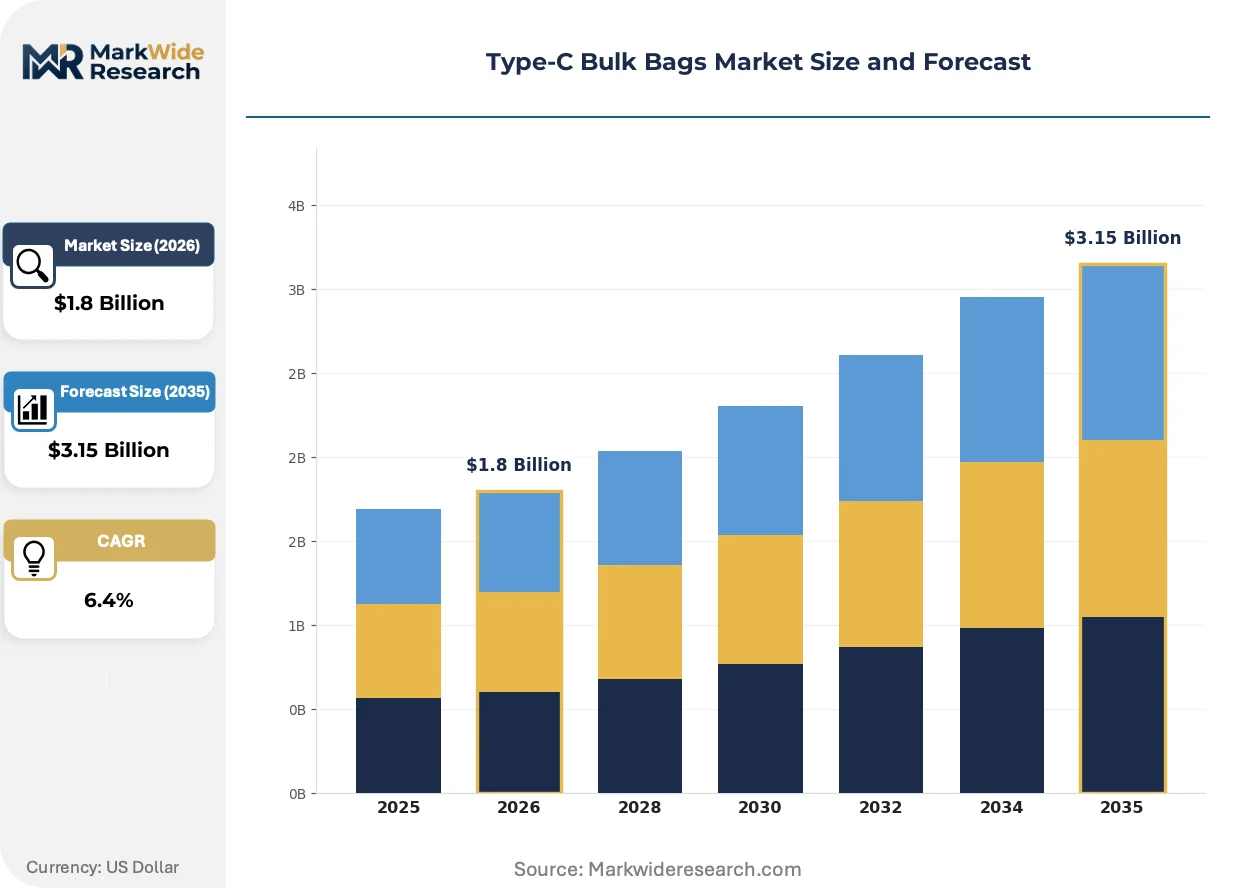
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Conductive, Conductive, Insulated, Composite Industry Vertical: Aerospace, Pharmaceuticals, Chemicals, Agriculture End User: Manufacturers, Distributors, Retailers, Suppliers Capacity: 500 kg, 1000 kg, 1500 kg, 2000 kg |
| Companies Covered | Berry Global Inc., Global-Pak Inc., National Bulk Bag, Atlantis Products Private Limited, AmeriGlobe LLC, Big Bulk Bags International Pvt. Ltd., Corman Bag Co., United Bulk Bags Inc., Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Type-C Bulk Bags Market Strategic Shifts
Material science advances are compressing the performance gap between conductive and insulated Type-C constructions while regulatory pressure on chemical-contact substances intensifies formulation complexity.
Multilayer barrier film technology is hybridizing with conductive thread matrices to create single-bag solutions for moisture-sensitive and electrostatically hazardous powders simultaneously. Pharmaceutical contract manufacturers in Switzerland and Germany are adopting these constructions for hygroscopic active ingredient handling. The convergence is compressing demand for separate liner systems and reducing total cost of ownership in high-value chemical logistics.
REACH restriction list expansions by ECHA are compelling reformulation of carbon-black conductive coatings to eliminate polycyclic aromatic hydrocarbons. Bag finishers must retest entire product lines against updated substance restrictions, extending recertification cycles. The pharmaceutical segment bears the heaviest compliance burden as FDA extractables requirements layer atop European chemical safety mandates.
Long-term rental and pooling models for Type-C bulk containers are displacing outright purchase in European chemical distribution. Third-party logistics providers in the Netherlands and Belgium now offer certified bag fleets with traceability documentation and maintenance included. This shift concentrates procurement authority among fewer buyers with sophisticated compliance requirements, favoring manufacturers with integrated testing and fleet management capabilities.
Type-C Bulk Bags Market Segmentation
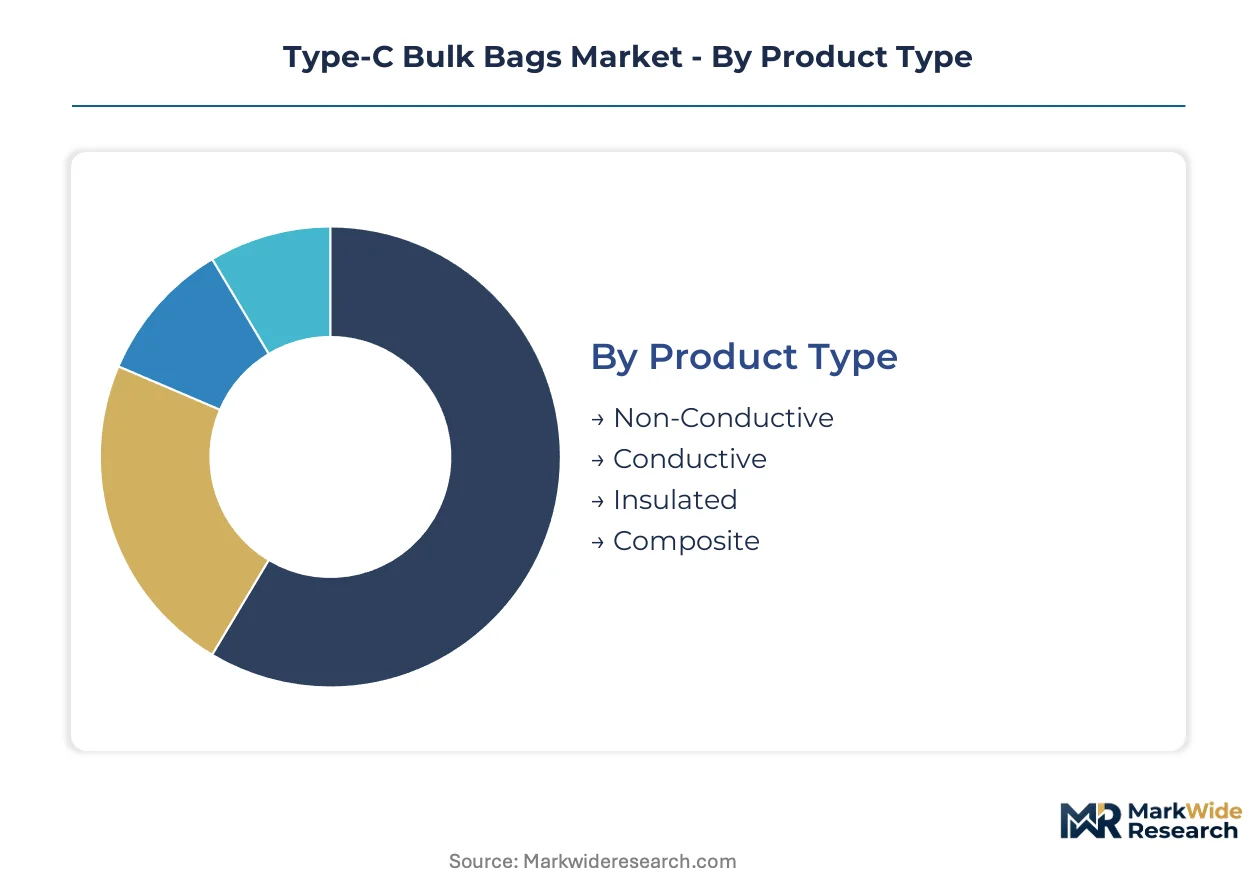
Type-C bulk bag segmentation reflects divergent technical requirements across hazardous material handling workflows. Cycle times vary dramatically by product category, with pharmaceutical procurement extending eighteen months for certified constructions while agricultural distributors rotate inventory quarterly.
Product Type:
Conductive variants turn inventory fastest in European chemical clusters, while insulated constructions sit longer in pharmaceutical qualification queues. Non-conductive standard bags move rapidly through agricultural channels with minimal certification overhead.
- Conductive:Interwoven carbon-thread grids dissipate static electricity per IEC 61340-4-4 during flammable powder handling. Demand clusters around Ludwigshafen and Leverkusen chemical processors facing REACH substance disclosure mandates for hazardous material packaging.
- Insulated:Multi-layer constructions with thermal barriers and static-dissipative coatings protect temperature-sensitive active pharmaceutical ingredients. Swiss and German contract manufacturers are adopting these for hygroscopic compound transport amid expanding cold-chain requirements.
- Non-Conductive:Standard woven polypropylene without conductive elements serves non-hazardous agricultural and mineral applications where electrostatic risk is absent.
- Composite:Hybrid constructions blending conductive thread matrices with ethylene vinyl alcohol oxygen barriers address multi-hazard scenarios in explosive powder logistics.
Conductive bags dominate installed base across chemical processing. Insulated variants are where expansion concentrates as pharmaceutical cold-chain requirements multiply.
Industry Vertical:
Margin structures stratify sharply across verticals, with pharmaceutical procurement absorbing premium pricing for certified constructions while agricultural buyers pressure converters on standard specifications.
- Chemicals:Flammable powder processors in Germany and the Netherlands require REACH-compliant conductive bags with full formulation transparency, creating captive demand for certified suppliers.
- Pharmaceuticals:Active ingredient manufacturers face layered FDA extractables requirements atop European chemical safety mandates, extending certification timelines and concentrating procurement among integrated testing providers.
- Aerospace:Propellant and pyrotechnic material handlers specify composite barrier-conductive constructions for moisture-sensitive explosive compounds.
- Agriculture:Grain and fertilizer distributors prioritize rapid turnaround and custom sizing over electrostatic certification, driving price competition among regional converters.
Chemical processing commands the deepest supplier relationships. Pharmaceuticals are climbing the fastest as CDSCO requirements in India and FDA guidelines tighten compliance burdens.
End User:
Procurement authority is shifting toward sophisticated buyers with integrated compliance capabilities as rental and pooling models displace outright purchase in European distribution.
- Manufacturers:Chemical and pharmaceutical producers directly specify certified Type-C constructions with traceability documentation for hazardous material handling.
- Distributors:Third-party logistics providers in Belgium and the Netherlands now offer certified bag fleets with maintenance included, concentrating buying power.
- Retailers:Agricultural supply chains purchase standard non-conductive bags on price-sensitive terms with minimal technical specification.
- Suppliers:Raw material vendors to chemical processors increasingly face downstream pressure to provide REACH-compliant packaging.
Manufacturers retain the largest direct procurement volumes. Distributors are gaining share fastest as fleet-based models reshape European chemical logistics.
Capacity:
Volume concentration follows end-use density patterns, with 1000 kg and 1500 kg specifications dominating chemical processing while lighter capacities serve specialized pharmaceutical batches.
- 1000 kg:The workhorse specification for European chemical cluster operations, balancing handling efficiency with forklift compatibility across flammable powder processing.
- 1500 kg:Preferred by German automotive supplier networks for resin and compound transport where single-fill efficiency reduces handling costs.
- 500 kg:Serves pharmaceutical active ingredient batches where lot segregation and traceability requirements override fill efficiency.
- 2000 kg:Heavy-duty construction for mineral and agricultural bulk where material density and non-hazardous classification permit maximum fill weights.
1000 kg specifications anchor the installed base. 1500 kg capacities are expanding most quickly as automotive chemical logistics scale in Germany.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes Type-C bulk bags primarily for hazardous chemical handling under REACH mandates, while India sources them for pharmaceutical export compliance and China deploys them for dual carbon tracking in chemical logistics.
Germany
Ludwigshafen and Leverkusen chemical clusters drive conductive bag procurement for flammable powder processing. ECHA's REACH substance disclosure requirements mandate full formulation transparency for packaging-contact layers. BASF supplier networks around these cities sustain specialized bulk containment procurement at scale.
United States
FDA extractables testing requirements for pharmaceutical contact materials extend certification timelines for new bag constructions. EPA hazardous material handling protocols reinforce demand for IEC-certified conductive constructions. Houston and Gulf Coast petrochemical corridors anchor regional procurement volumes.
China
MEE emissions tracking for chemical logistics favors reusable bulk container systems with documented lifecycle footprints. Zhejiang and Shandong provinces concentrate woven polypropylene tape extrusion capacity. Domestic output scales to serve Asia-Pacific chemical processing demand.
India
CDSCO requirements for static-safe active ingredient export packaging open demand among Mumbai and Hyderabad formulation hubs. Pharmaceutical contract manufacturers face layered compliance burdens from both domestic and destination-market regulators. Western India chemical belts concentrate early adoption.
Switzerland
Swissmedic pharmaceutical packaging standards intersect with European chemical safety mandates for multi-layer barrier constructions. Basel-area contract manufacturers adopt hybrid conductive-thermal bags for hygroscopic compound transport. Alpine logistics corridors require cold-chain-compatible static protection.
Type-C Bulk Bags Market Competitive Environment
Capability concentration sits with integrated testing and certification providers; scale advantage sits with high-volume woven fabric converters. The vendor base stratifies across three tiers: multinational packaging conglomerates with captive resin supply, regional specialists in custom sizing and rapid turnaround, and emerging Asian fabricators leveraging domestic polypropylene output. Dominant competitive moves include backward integration into film extrusion and strategic partnerships with third-party logistics providers for fleet-based rental models.
Among North American distributors, National Bulk Bag and AmeriGlobe LLC occupy positions emphasizing custom sizing and rapid turnaround for agricultural and chemical handlers. Mondi Group anchors European supply through certified conductive production serving pharmaceutical clients. Berry Global Inc. represents the integrated multinational tier, leveraging in-house film extrusion capabilities to control resin costs across manufacturing footprints.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Global-Pak Inc. |
| National Bulk Bag |
| Atlantis Products Private Limited |
| AmeriGlobe LLC |
| Big Bulk Bags International Pvt. Ltd. |
| Corman Bag Co. |
| United Bulk Bags Inc. |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Zhejiang and Shandong polypropylene tape extrusion compresses margin capture for European and North American bag finishers while amplifying pricing leverage for integrated multinational converters with captive resin supply.
Pricing Analysis
Long-term offtake contracts dominate procurement between German chemical clusters and certified suppliers, insulating premium-tier producers from spot-market volatility in polypropylene feedstock. Price differentiation hinges on IEC 61340-4-4 certification grade and REACH formulation transparency, with pharmaceutical buyers absorbing premiums for extractables-tested constructions while agricultural distributors drive cost compression in standard specifications. Pricing pressure stems from Chinese woven fabric oversupply eroding mid-tier converter margins. Chemical processors exhibit lowest price sensitivity due to regulatory non-substitutability; grain handlers show highest sensitivity, rotating suppliers quarterly on unit economics.
Supply Chain Analysis
Propylene feedstock draws from Gulf Coast petrochemical complexes, Saudi Arabian crackers, and Chinese coal-to-olefins facilities, with resin costs fluctuating on naphtha-cracker margins and OPEC+ supply decisions. Woven polypropylene tape production concentrates in China, Turkey, and India, while bag finishing and conductive coating application clusters in Germany, the Netherlands, and the United States. Single-source vulnerability runs through Zhejiang province extrusion capacity, where regional power rationing or environmental enforcement could disrupt global fabric supply. Distribution runs through third-party logistics fleet operators in Belgium and the Netherlands offering certified rental pools with traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, FDA, and CDSCO jurisdictions fragments procurement authority, creating specialized niches for converters with integrated certification capabilities and geographic proximity to chemical clusters.
For Market Incumbents: Insulate margin position by deepening backward integration into film extrusion and conductive coating formulation, countering resin cost volatility that threatens mid-tier competitors. Accelerate extractables testing infrastructure investment to compress pharmaceutical certification queues, defending against emerging Asian fabricators seeking European pharmaceutical market entry through price undercutting.
For New Entrants and Emerging Players: Pursue Indian pharmaceutical export packaging demand where CDSCO static-safety mandates and limited domestic IEC-certified supply create penetrable white space. Target Mumbai and Hyderabad formulation hubs with rapid-turnaround custom sizing and regional logistics partnerships, bypassing entrenched European suppliers on lead time rather than price.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-based rental operators with third-party logistics partnerships, offering contracted visibility superior to transactional bag sales. Long-term viability favors converters with integrated testing laboratories and multi-jurisdiction certification portfolios. Watch for ECHA REACH restriction list expansions as inflection indicators forcing industry-wide reformulation and consolidation among sub-scale players lacking R&D absorption capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Berry Global's captive resin supply insulates margin stability against propylene feedstock volatility. |
| IEC 61340-4-4 Certification Investment | Mondi Group's accredited testing infrastructure compresses pharmaceutical client onboarding timelines. |
| Fleet-Based Rental Model Expansion | Third-party logistics operators in Belgium consolidate procurement authority through traceability documentation. |
| Barrier Film Convergence R&D | Hybrid conductive-thermal constructions capture pharmaceutical cold-chain demand from Swiss contract manufacturers. |
| Indian Pharmaceutical Market Entry | CDSCO export packaging requirements open demand among Mumbai formulation hubs seeking IEC-certified supply. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from packaging conglomerates, ECHA substance restriction updates, and IEC certification registries. Primary interviews engaged plant managers at German chemical processors, procurement leads at pharmaceutical contract manufacturers, technical R&D directors at woven fabric converters, and fleet operations heads at third-party logistics providers. Bottom-up triangulation validated volume estimates against polypropylene resin consumption patterns and top-down cross-checks against flexible intermediate bulk container trade flows.
Forecast inputs incorporate product type segmentation across conductive, insulated, and composite constructions; industry vertical stratification spanning chemicals, pharmaceuticals, aerospace, and agriculture; capacity tier distribution; and regional regulatory cluster differentiation. CAGRs were derived from regression analysis of historical procurement patterns and elasticity modeling against feedstock cost movements. Industry-specific inputs include REACH compliance timeline acceleration, pharmaceutical cold-chain infrastructure buildout rates, and Chinese woven fabric capacity utilization signals.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed fabricators or accelerated biodegradable substitute adoption by European grain handlers would shift outcomes. Material shifts in ECHA substance restriction scope, FDA extractables testing protocol revisions, or MEE emissions tracking enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Packaging Nets Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Crates Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Wooden Boxes Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Zipper Bags Market
Bags and Containers
Liner Bags Market