
 Global Non-Conductive Water Blocking Tape Market | 2026-2036
Global Non-Conductive Water Blocking Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Conductive Water Blocking Tape Market Foresight
Aftermarket service revenue for cable system maintenance is narrowing as manufacturers push integrated material warranties. 3M Company leverages its polymer science depth to sustain premium positioning in harsh-environment tapes. Nitto Denko Corporation anchors Asian supply chains through captive resin compounding capabilities. Chase Corporation competes on specialized bituminous formulations for utility-grade power cable protection.
Non-conductive water blocking tape consists of a swellable polymer core—typically sodium polyacrylate superabsorbent laminated to polyester or nonwoven substrates—that expands upon water contact to seal cable interstices and prevent longitudinal moisture ingress. The material functions primarily as a passive barrier in fiber optic, telecom, and power cable constructions where metallic armor or conductive moisture barriers would interfere with signal integrity. Butyl rubber tape commands the largest product share due to proven adhesion and chemical stability across temperature extremes. Polyethylene tape segments are gaining share in data cable applications where low dielectric loss matters. Submarine deployment installations carry the highest performance specifications and corresponding margin premiums among installation categories.
FDA material contact rules, IEC 60794 optical fiber cable standards, and ECHA REACH substance restrictions collectively govern tape chemistry, flame retardancy, and environmental release profiles. These frameworks compel reformulation cycles as legacy plasticizers face authorization pressure. Stakeholders must track evolving EU F-Gas Regulation impacts on blowing agents and assess dual carbon compliance timelines in China before committing capacity expansion decisions.
Market Dynamics
Submarine cable buildouts across the Atlantic and Pacific corridors are compressing qualification timelines and forcing tape suppliers to synchronize R&D cycles with cable-lay vessel schedules. This demand pulse is restructuring how manufacturers allocate polymer compounding capacity and certification resources.
Growth Catalysts
- IEC 60794 cable standards:Optical fiber cable specifications are tightening water ingress resistance thresholds, forcing cable OEMs to specify higher-performance swellable tapes in terrestrial and submarine deployments.
- Submarine cable investments:Transoceanic fiber projects linking China, Germany, and the United States are consuming specialized tape grades with extended salt-water stability profiles.
- Sodium polyacrylate formulation advances:Next-generation superabsorbent polymers are achieving faster gel-blocking response times, enabling thinner tape constructions without sacrificing protection margins.
Market Restraints
- Petrochemical input volatility:Polyester substrate and butyl rubber feedstock costs fluctuate with crude oil derivatives, compressing margin predictability for tape converters.
- Asian supply concentration:Captive resin compounding capabilities in East Asia create dependency risks for European and North American cable manufacturers seeking qualified second sources.
- Bituminous tape substitution:Specialized bituminous formulations for utility-grade power cables compete on cost in applications where dielectric performance requirements are less stringent.
Strategic Opportunities
- Data center interconnect cables:Hyperscale cloud infrastructure expansion is creating demand for low-dielectric-loss polyethylene tape constructions in high-density fiber deployments.
- EU F-Gas Regulation compliance:Blowing agent reformulation mandates are opening technical partnerships between tape producers and chemical suppliers developing halogen-free expansion technologies.
- Integrated material warranties:Cable manufacturers are bundling tape performance guarantees with system-level contracts, creating aftermarket service revenue streams for qualified suppliers.
Industry Challenges
- ECHA REACH authorization timelines:Legacy plasticizer substances face sunset dates, forcing reformulation cycles that must maintain swellable polymer performance while securing chemical safety approvals.
- Dual carbon compliance in China:Tape producers must align capacity expansion decisions with provincial emissions trading schemes and national carbon intensity targets.
- Submarine qualification protocols:Cable-lay contractors demand extended accelerated aging test data that extends product development cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Conductive Water Blocking Tape Market |
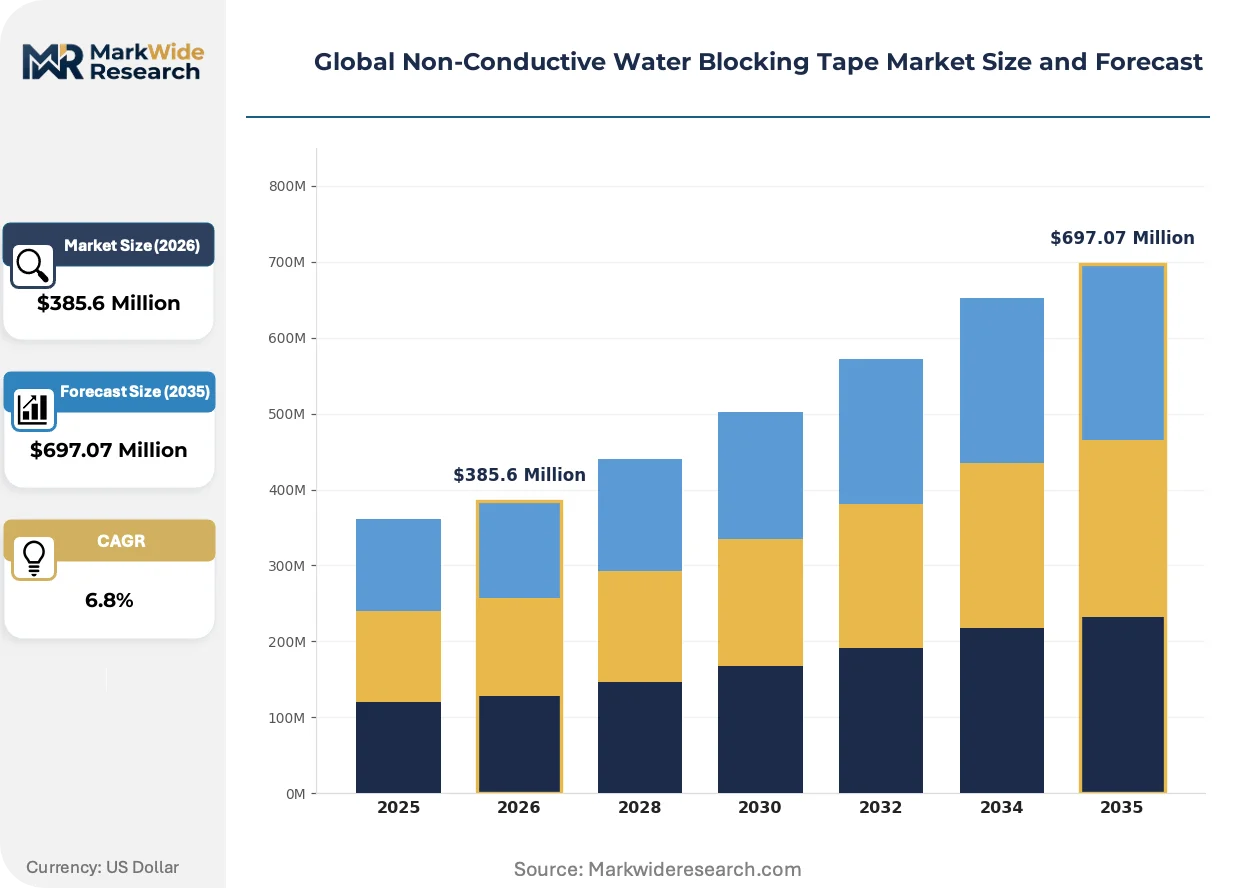
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyl Rubber Tape, Polyethylene Tape, Bituminous Tape, Acrylic Tape, Silicone Tape Application: Fiber Optic Cables, Telecom Cables, Power Cables, Data Cables, Automotive Wiring End User: Cable Manufacturers, Telecommunications Firms, Electrical Contractors, Infrastructure Developers, Equipment Assemblers Installation Type: Indoor Installation, Outdoor Installation, Underground Deployment, Aerial Deployment, Submarine Application |
| Companies Covered | Nitto Denko Corporation, Chengdu Centran Industrial, Chase Corporation, Ekstel, Chhaperia International Company, 3M Company, Berry Global Group, Inc., Geca Tapes, Scapa Group Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Conductive Water Blocking Tape Market Shifts & Advancements
Tape chemistry and cable construction standards are converging around passive barrier performance metrics that prioritize signal integrity over metallic armor alternatives. This technical pivot is redrawing supplier qualification hierarchies.
Multi-layer swellable constructions are migrating from conventional sodium polyacrylate monolayers toward laminated substrates combining nonwoven cores with precision-coated superabsorbent films. Submarine cable OEMs in Germany and the United States are piloting these architectures for transatlantic routes. The shift is migrating from niche deep-water applications toward mainstream terrestrial fiber deployments as cable designers seek thinner overall diameters.
ECHA REACH substance restrictions are compelling systematic replacement of phthalate-based plasticizers in butyl rubber tape formulations. Industrial consequence includes accelerated supplier audits and raw material traceability investments across European cable manufacturing chains. Fiber optic cable segments are most affected, with German and French OEMs front-loading reformulation costs to secure authorization continuity.
Specification-driven procurement is consolidating vendor pools around tape suppliers with in-house polymer synthesis capabilities and IEC-certified testing infrastructure. Distribution through specialized cable component distributors is yielding to direct technical partnerships with cable system integrators. This pattern is most visible in China, where state-backed submarine cable projects mandate domestic qualification certificates and local manufacturing presence.
Global Non-Conductive Water Blocking Tape Market Segmentation
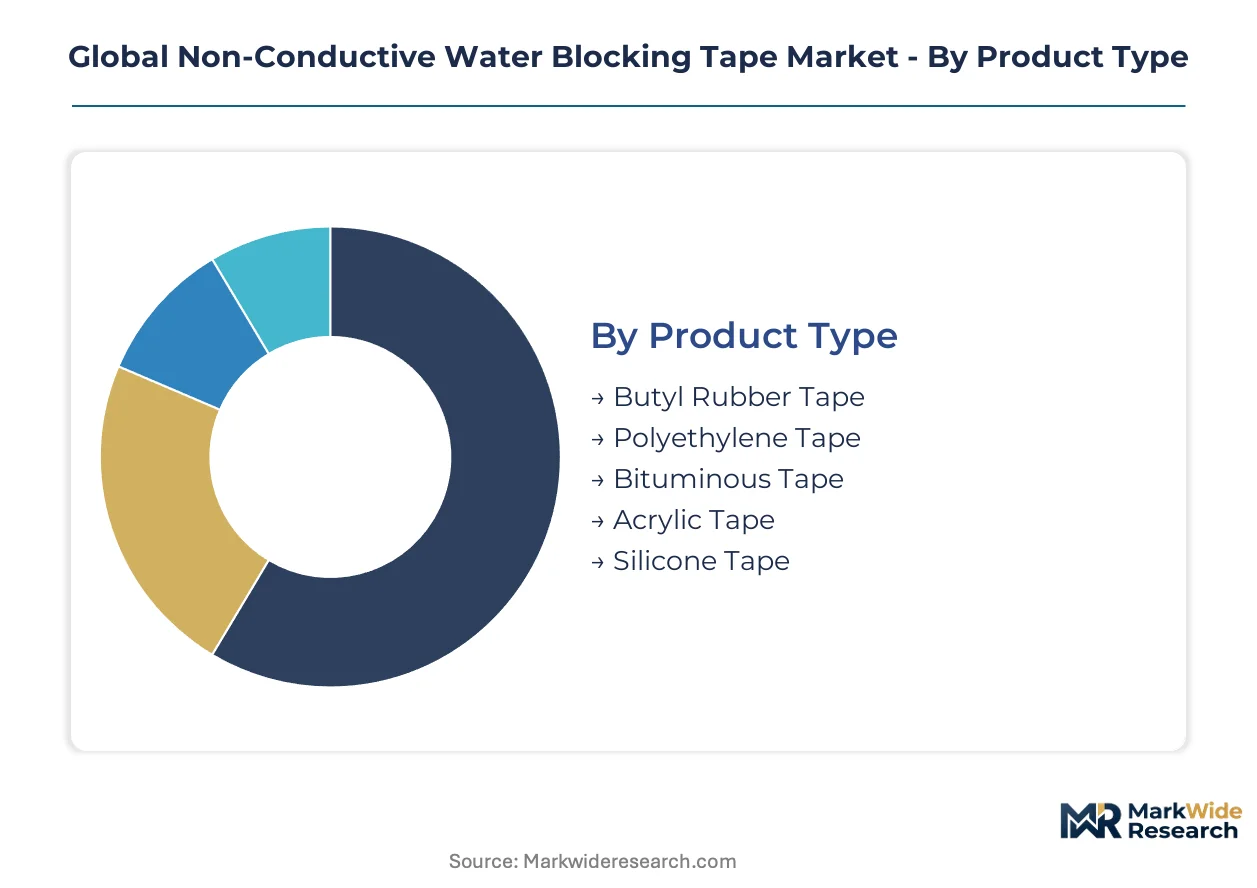
Segmentation in the non-conductive water blocking tape market reveals how material specifications diverge across cable construction requirements. Each dimension—product chemistry, deployment environment, and procurement channel—carries distinct margin structures and qualification barriers that reshape supplier positioning.
Product Type:
Cost tier separation across polymer chemistries determines which tape constructions penetrate premium submarine contracts versus utility-grade power cable bids.
- Butyl Rubber Tape:Synthetic rubber formulations laminated with sodium polyacrylate superabsorbent deliver proven adhesion across temperature extremes from -40°C to 90°C. Demand concentrates in submarine cable projects linking China and Germany, where salt-water stability requirements compress vendor pools to qualified incumbents with IEC-certified testing infrastructure.
- Polyethylene Tape:Low-density polyethylene substrates with precision-coated swellable films achieve dielectric constants below 2.3, critical for signal integrity in high-frequency data transmission. Data center interconnect deployments in the United States and hyperscale cloud infrastructure expansion are rotating procurement toward thinner, lower-loss constructions.
- Bituminous Tape:Specialized asphalt-polymer blends compete on material cost for utility-grade power cable protection where metallic armor alternatives remain viable.
- Acrylic Tape:UV-cured acrylic adhesives with moderate swell rates serve indoor fiber optic installations requiring clean-room compatible outgassing profiles.
- Silicone Tape:High-temperature silicone elastomers withstand continuous 150°C operation in automotive wiring harnesses and industrial motor leads.
Butyl rubber tape holds installed capacity. Polyethylene tape is rotating up the share rankings.
Application:
Application focus determines whether tape specifications prioritize optical signal preservation, electrical insulation integrity, or mechanical abrasion resistance.
- Fiber Optic Cables:Single-mode and multimode fiber constructions demand swellable tapes with minimal ionic content to prevent hydrogen darkening of silica cores. Transoceanic cable projects across the Atlantic and Pacific corridors are consuming specialized grades with accelerated gel-blocking response times.
- Telecom Cables:Copper-pair and hybrid fiber-copper deployments in Germany and France require flame-retardant tape laminates meeting IEC 60332-3-24 vertical tray burn tests. ECHA REACH plasticizer restrictions are forcing reformulation cycles among European cable OEMs.
- Power Cables:Medium-voltage distribution networks specify bituminous or rubber-based moisture barriers where semiconducting layers manage electrical stress distribution.
- Data Cables:Category 8 and beyond high-speed Ethernet constructions prioritize low-smoke zero-halogen tape substrates for data center plenum ratings.
- Automotive Wiring:Electric vehicle high-voltage harnesses specify silicone or acrylic tapes with thermal endurance matching motor controller operating temperatures.
Telecom cables retain volume leadership. Fiber optic cables are climbing the fastest.
End User:
Customer type shapes procurement sophistication, with cable manufacturers demanding technical partnerships while electrical contractors prioritize distributor availability and lot-to-lot consistency.
- Cable Manufacturers:Integrated cable system producers in China, Germany, and the United States specify tape performance through direct material qualification protocols. Submarine cable OEMs mandate extended accelerated aging test data that extends supplier development cycles.
- Telecommunications Firms:State-backed operators and private carriers bundle tape performance guarantees with system-level deployment contracts, creating aftermarket service revenue streams.
- Electrical Contractors:Utility and commercial construction installers source through specialized cable component distributors with regional stocking points.
- Infrastructure Developers:Rail, airport, and smart city project sponsors specify tape flame retardancy through consultant-engineered material schedules.
- Equipment Assemblers:Industrial machinery and medical device manufacturers consume narrow-width tape formats for internal wiring harness protection.
Cable manufacturers command specification authority. Telecommunications firms are consolidating vendor relationships.
Installation Type:
Deployment environment dictates the severity of moisture exposure, mechanical load, and chemical degradation factors that tape constructions must survive.
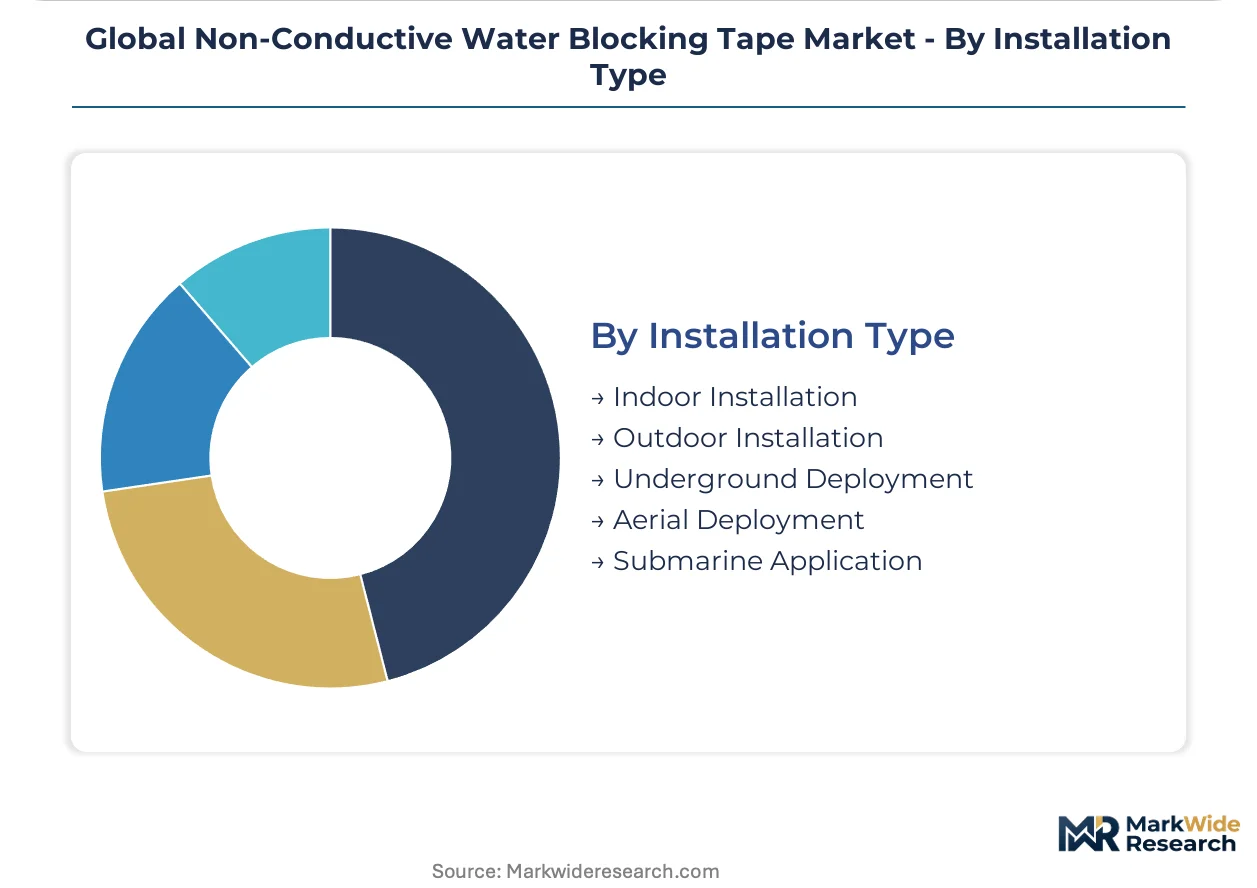
- Submarine Application:Deep-water and beach-landing cable sections face hydrostatic pressures exceeding 10 MPa and decades-long service life requirements. Transoceanic projects linking China, Germany, and the United States carry the highest performance specifications and corresponding margin premiums.
- Underground Deployment:Direct-buried and duct-installed cables encounter groundwater inundation and rodent abrasion across temperate and tropical climates.
- Outdoor Installation:Aerial and pole-mounted cables require UV-stabilized tape substrates resisting photodegradation across diurnal thermal cycling.
- Indoor Installation:Controlled-environment data centers and central offices specify low-outgassing tapes compatible with precision optical connector cleanliness.
- Aerial Deployment:Self-supporting and messenger-wire cable constructions impose tensile load sharing and wind-induced vibration fatigue on tape laminates.
Submarine application commands premium positioning. Underground deployment anchors volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding capacity clusters in East Asia and Western Europe, with qualified tape suppliers synchronizing certification cycles to submarine cable-lay schedules in the Atlantic and Pacific corridors.
China
State-backed submarine cable projects drive specialized tape procurement with domestic qualification mandates. MIIT enforces GB standards for optical fiber cable materials while dual carbon targets from MEE reshape provincial capacity decisions. Yangtze River Delta manufacturers dominate swellable polymer substrate production for transoceanic deployments.
Germany
Transatlantic fiber projects and terrestrial network upgrades sustain premium tape specifications. ECHA REACH authorization timelines force plasticizer reformulation cycles among cable OEMs. Industrial clusters in North Rhine-Westphalia host IEC-certified testing infrastructure serving submarine cable contractors.
United States
Hyperscale data center interconnect buildouts rotate procurement toward low-dielectric-loss polyethylene constructions. FDA material contact rules govern tape chemistry for specialized applications alongside FCC telecommunications infrastructure guidelines. Southeast cable manufacturing corridors concentrate demand for utility-grade moisture barrier materials.
Japan
High-reliability fiber optic and automotive wiring specifications sustain demand for thermal-endurance tape grades. METI industrial standards and JIS certification requirements structure supplier qualification protocols. Kanto region manufacturers integrate precision coating capabilities for multi-layer swellable constructions.
South Korea
Domestic cable system exports and electric vehicle wiring harness expansion drive specialized tape consumption. MFDS chemical safety assessments and MIIT-equivalent industrial standards govern material compliance. Busan-Ulsan manufacturing zones concentrate polymer lamination capacity for marine-grade applications.
Global Non-Conductive Water Blocking Tape Market Competitive Landscape
Diversified industrial conglomerates and specialized tape fabricators split the market across premium submarine qualifications and utility-grade volume segments. Supplier tiers separate around IEC-certified testing infrastructure ownership, captive resin compounding capabilities, and direct cable OEM technical partnerships. Three archetypes dominate: integrated materials science conglomerates with polymer synthesis depth, regional specialists with substrate lamination expertise, and diversified industrial tape producers with cross-sector formulation libraries. Competitive positioning hinges on qualification timeline compression and backward integration into superabsorbent polymer supply.
Among diversified industrial materials groups, 3M Company and Nitto Denko Corporation exemplify the integrated science archetype with polymer compounding depth. Chase Corporation occupies a position within specialized industrial tape segments. These anchors demonstrate how supplier positioning varies across submarine certification intensity, regional manufacturing presence, and formulation specialization breadth.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| Chengdu Centran Industrial |
| Chase Corporation |
| Ekstel |
| Chhaperia International Company |
| 3M Company |
| Berry Global Group, Inc. |
| Geca Tapes |
| Scapa Group Ltd |
| Others |
Supply & Pricing Matrix
Petrochemical input volatility determines both pricing tier spreads and supply chain shape across the non-conductive water blocking tape market. Crude oil derivative fluctuations compress margin predictability for tape converters while forcing buyers into longer-term contract structures that lock in qualified supplier relationships.
Pricing Analysis
ECHA REACH authorization timelines dictate the pricing tier structure across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified submarine grades from terrestrial fiber constructions and utility-grade bituminous alternatives. Price differentiation hinges on certification level and volume scale, with cable OEMs absorbing premium positioning for deep-water qualifications. Cost compression in standard-grade polyethylene tapes is intensifying because hyperscale data center buyers are consolidating purchase volumes. Electrical contractors exhibit highest price sensitivity, while submarine cable OEMs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Captive resin compounding capabilities in China, Japan, and South Korea concentrate swellable polymer substrate production for qualified tape suppliers. Raw material dependencies center on sodium polyacrylate superabsorbent, polyester nonwoven substrates, and butyl rubber feedstocks sourced from regional petrochemical complexes. Single-source vulnerability runs through East Asian superabsorbent polymer synthesis capacity, where qualified second sources remain scarce for European and North American cable manufacturers. Distribution runs through direct technical partnerships with cable system integrators rather than specialized component distributors, particularly for submarine qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across submarine, data center, and automotive wiring applications creates niche entry points for differentiated suppliers. Submarine cable investments are accelerating qualification timeline compression, opening windows for technical specialists.
For Market Incumbents:Insulate premium positioning by deepening backward integration into sodium polyacrylate polymer synthesis and securing IEC-certified testing infrastructure ownership. Accelerated gel-blocking response times from emerging superabsorbent formulations threaten technical differentiation; incumbents should lock cable OEMs into integrated material warranties that bundle tape performance with system-level service contracts. Capacity expansion in the Yangtze River Delta reinforces proximity to state-backed submarine projects.
For New Entrants and Emerging Players:Pursue data center interconnect cable segments where low-dielectric-loss polyethylene constructions face supply constraints from incumbent focus on submarine qualifications. The penetrable white-space sits in hyperscale cloud infrastructure buildouts across the United States, where procurement prioritizes thinner tape geometries over deep-water aging protocols. A go-to-market angle targeting direct partnerships with cable system integrators—bypassing legacy distributor relationships—accelerates technical qualification timelines.
For Investors and Strategic Acquirers:ECHA REACH sunset dates for phthalate-based plasticizers reshape the acquisition landscape toward targets with reformulation-ready butyl rubber capabilities. Long-term viability across the projection horizon favors suppliers with in-house polymer compounding and multi-regional manufacturing footprints that navigate dual carbon compliance in China. The acquisition target archetype combines captive resin synthesis with IEC-certified testing infrastructure. The signal to watch is cable-lay vessel contracting activity across Atlantic and Pacific corridors, which precedes tape procurement pulses by 12-18 months.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superabsorbent Polymer Synthesis | Captive sodium polyacrylate production secures margin control against petrochemical volatility. |
| IEC-Certified Testing Infrastructure Investment | Accelerated qualification timelines align R&D cycles with submarine cable-lay schedules. |
| Integrated Material Warranty Programs | System-level performance bundling locks cable OEMs into long-term service relationships. |
| Halogen-Free Blowing Agent Reformulation Partnerships | EU F-Gas Regulation compliance opens technical collaboration with chemical suppliers. |
| Multi-Regional Manufacturing Footprint Expansion | Provincial emissions trading scheme navigation enables capacity decisions aligned with dual carbon targets. |
Research Methodology
Initial hypotheses were tested against primary input from cable system procurement directors, polymer compounding plant managers, submarine cable OEM technical qualification leads, and specialized cable component distributors and refined through secondary validation. Cable OEM technical specification databases, ECHA REACH substance restriction filings, IEC standards documentation, and customs trade data for swellable polymer substrates anchored quantitative triangulation. Bottom-up segment sizing and top-down market reconciliation cross-checked volume assumptions across product chemistry, deployment environment, and procurement channel dimensions.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include polymer chemistry tier, cable construction type, installation environment severity, and regional regulatory cluster. CAGRs were derived from installed base growth, replacement cycle dynamics, and penetration rate assumptions for next-generation superabsorbent formulations. Submarine cable project pipelines, hyperscale data center capex disclosures, and electric vehicle wiring harness production schedules fed industry-specific forecast inputs.
Sensitivities concentrate around ECHA REACH authorization timeline delays, crude oil derivative price spikes, and cable-lay vessel schedule slippage that compress tape qualification windows. Forecasts reflect assumptions on regulatory compliance cost pass-through and superabsorbent polymer capacity expansion cadence. Quarterly review of submarine cable contract awards, provincial dual carbon target announcements in China, and REACH candidate list substance additions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Kraft Paper Tapes Market
Tapes
Custom Printed Tape Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Global Printed Tape Market
Tapes
Wing Walk Tapes Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Tape Unwinder Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Pucker Free Tapes Market
Tapes
Mastic Tapes Market
Tapes
Foam Tape Market
Tapes
Unidirectional Tapes Market
Tapes
Sterilization Tape Market
Tapes
Lacing Tape Market