
 Zipper Bags Market | 2026-2036
Zipper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Zipper Bags Market Analytics
Food service operators is redrawing demand patterns across the zipper bags landscape as commercial kitchens and meal-kit distributors expand procurement volumes. SC Johnson & Son, Inc. leverages its retail brand strength and household channel dominance to sustain premium positioning. Berry Global Group Inc. anchors North American supply through its broad extrusion and converting footprint. Reynolds Consumer Products competes aggressively on value-tier positioning and private-label partnerships.
Zipper bags are flexible pouches incorporating interlocking closure mechanisms, typically extruded from polyethylene or polypropylene films with thicknesses ranging from 1.5 to 4 mils, designed for repeated opening and sealing to preserve contents against moisture and contamination. Polyethylene formulations dominate volume due to cost efficiency and heat-seal compatibility, while slider zipper closures command higher margins in premium household and retail segments. Industrial end users favor large-format press-seal configurations for parts protection and inventory management.
FDA food-contact regulations govern resin approvals and migration limits for zipper bags sold into U.S. food applications, while EPA guidelines on plastic waste influence recycler certification requirements and post-consumer content claims. State-level extended producer responsibility frameworks in California and New York are tightening accountability for single-use flexible packaging. Stakeholders must monitor regulatory divergence across jurisdictions to align material substitution timelines with compliance deadlines.
Market Dynamics
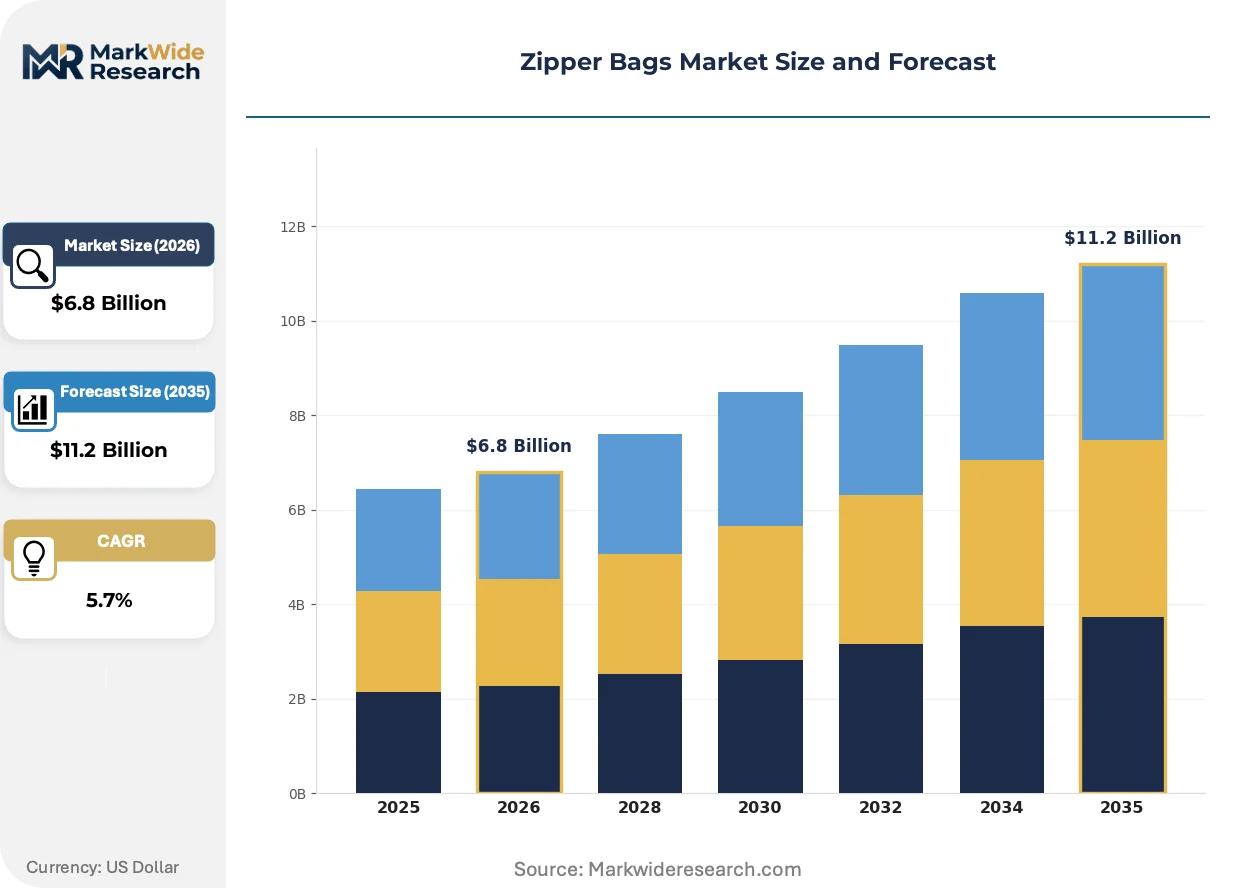
Food service procurement expansion and state-level plastic restrictions in the United States are forcing material substitution timelines while concentrating demand among extrusion-capable suppliers. The collision of regulatory compliance and commercial kitchen volume growth is restructuring supplier-buyer relationships.
Growth Catalysts
- Prepared meal packaging surge:Commercial kitchens and meal-kit distributors are scaling zipper bag volumes for portion-controlled packaging. This end-use segment is absorbing larger format bags with enhanced barrier properties.
- FDA food-contact compliance:Resin approval pathways for polyethylene formulations are streamlining market entry for compliant suppliers. Migration limit adherence is becoming a procurement gate.
- China domestic consumption:Urban household refrigerator penetration and organized retail expansion are driving retail-format zipper bag adoption. Export manufacturing capacity is co-locating with domestic demand growth.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin costs fluctuate with naphtha and natural gas liquid pricing. Margins compress during input cost spikes without immediate pass-through mechanisms.
- California extended producer responsibility:State-level accountability frameworks for single-use flexible packaging are raising compliance overhead. Small converters face disproportionate administrative burden.
- Paper-based flexible packaging substitution:Fiber-based alternatives with heat-seal coatings are capturing shelf-stable food segments. Moisture-sensitive applications remain protected but face long-term displacement risk.
Strategic Opportunities
- India organized retail penetration:Modern trade expansion in tier-two and tier-three cities is creating first-time zipper bag demand. Local extrusion investment is lagging, opening import windows.
- Post-consumer recycled content mandates:European Union packaging waste directives are creating certified recycled polyethylene demand. Early compliance positions suppliers for premium tier access.
- E-commerce fulfillment packaging:Direct-to-consumer food brands are specifying resealable pouches for shipping durability. This channel bypasses traditional retail shelf constraints.
Industry Challenges
- Extrusion technician scarcity:Blown film line operation and die adjustment expertise is concentrated among aging workforces. Training pipeline gaps constrain capacity expansion timelines.
- Multi-state regulatory fragmentation:Divergent plastic restriction timelines across New York, California, and emerging state adopters complicate national product portfolio planning. SKU proliferation raises inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zipper Bags Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Nylon, PVC Closure Type: Standard Zipper, Slider Zipper, Press Seal, Resealable Bag Size: Small, Medium, Large, Extra Large End User: Household, Food Service, Retail, Industrial |
| Companies Covered | SC Johnson & Son, Inc., Berry Global Group Inc., Reynolds Consumer Products, Amcor plc, Mondi Group, Pactiv Evergreen, Novolex, Zip-Pak, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zipper Bags Market Evolving Landscape
Slider zipper mechanisms and bio-based polyethylene formulations are compressing traditional press-seal dominance while regulatory pressure accelerates material innovation cycles. Technology convergence is redefining performance benchmarks across household and industrial segments.
Mono-material polyethylene structures with enhanced heat-seal layers are miniaturizing multilayer barrier complexity while maintaining moisture protection. Food service operators are specifying these simplified constructions for recycling stream compatibility. The reduction in material layers is compressing converter technical requirements and opening supply to mid-scale extruders.
REACH restrictions on persistent organic pollutants in food-contact materials are accelerating fluorinated compound phase-outs in European zipper bag applications. Suppliers are reformulating barrier coatings to maintain grease resistance without per- and polyfluoroalkyl substances. Premium household segments in Germany and France are absorbing reformulation costs faster than value-tier channels.
Direct sourcing relationships between meal-kit distributors and extrusion converters are displacing traditional distributor intermediaries in North American supply chains. Volume commitments and specification co-development are replacing spot purchasing. This pattern is most visible in the northeastern United States where distributor consolidation has reduced competitive options.
Zipper Bags Market Segmentation
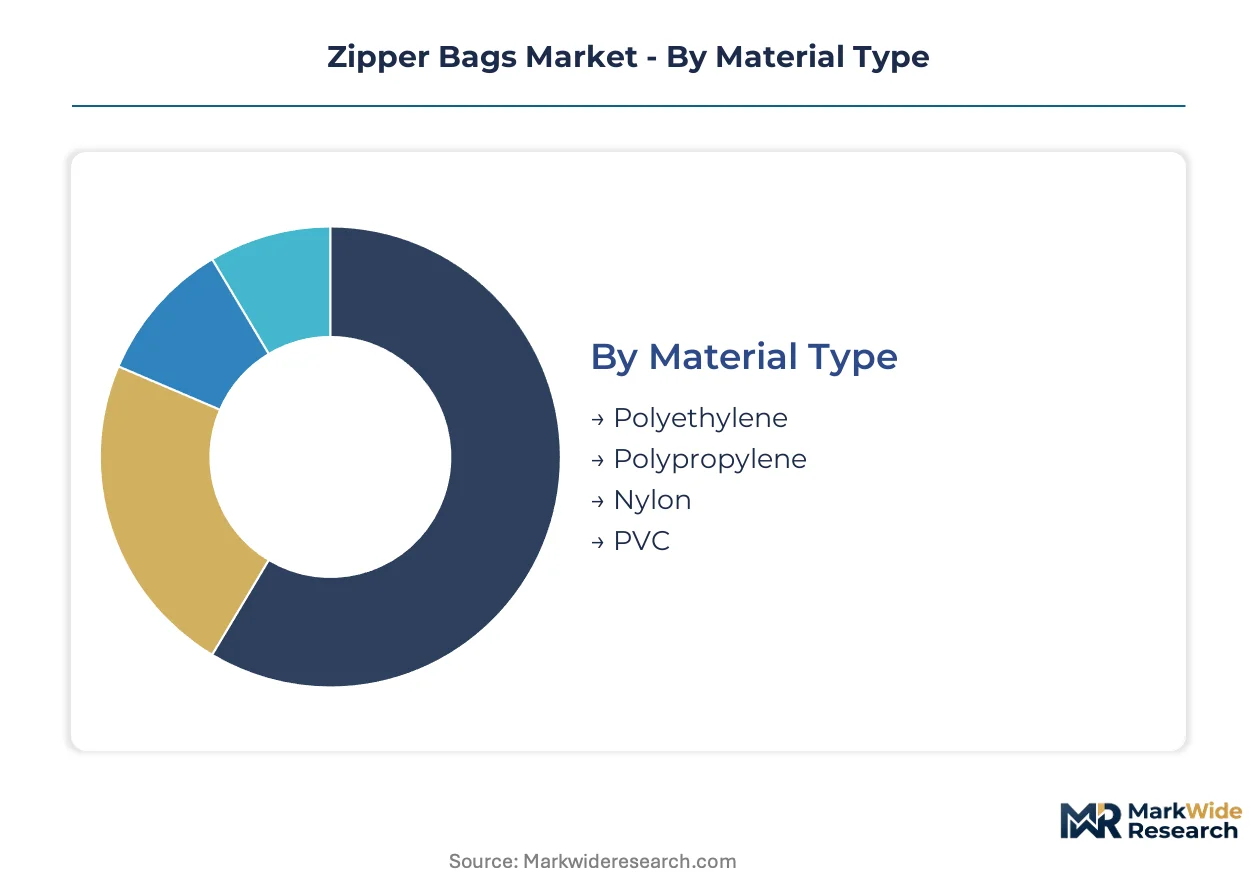
Zipper bag segmentation reveals divergent supply chain configurations across material chemistry and closure engineering. Each dimension carries distinct regulatory exposure and margin architecture that shapes supplier positioning strategies.
Material Type:
Polyethylene formulations dominate domestic consumption volumes across North America and Europe, while polypropylene and specialty polymers concentrate in export manufacturing corridors serving Asia-Pacific demand.
- Polyethylene:Low-density and linear low-density formulations extrude at 1.5 to 4 mil thicknesses with superior heat-seal compatibility. Food service operators in the United States specify this resin for FDA-compliant prepared meal packaging as migration limit adherence becomes non-negotiable.
- Polypropylene:Cast and oriented films deliver higher temperature resistance and clarity for premium retail display applications. German and French household segments absorb reformulation costs for fluorinated compound phase-outs faster than value-tier channels under REACH restrictions.
- Nylon:Polyamide structures provide puncture resistance and oxygen barrier properties for industrial parts protection and medical device packaging.
- PVC:Plasticized vinyl formulations retain niche positioning in heavy-duty industrial configurations despite regulatory pressure on plasticizer migration.
Polyethylene holds the largest share; momentum sits with polypropylene as barrier specifications tighten.
Closure Type:
Slider mechanisms command premium pricing in household retail channels, while press-seal and standard zipper configurations scale through food service procurement at volume-driven margin structures.
- Standard Zipper:Interlocking polyethylene or polypropylene tracks formed during co-extrusion provide repeated opening cycles at lowest unit cost. Meal-kit distributors in the northeastern United States specify these for portion-controlled packaging with direct converter relationships displacing traditional distributors.
- Slider Zipper:Molded plastic sliders riding on dual-track profiles enable one-handed operation for premium consumer convenience. Urban households in China absorb these formats as refrigerator penetration and organized retail expansion accelerate.
- Press Seal:Groove-and-ridge profiles without interlocking mechanisms serve industrial end users for large-format parts protection and inventory management.
- Resealable:Adhesive-based and mechanical hybrid closures target e-commerce fulfillment where shipping durability requirements bypass traditional shelf constraints.
Standard zipper dominates procurement tonnage; slider zipper climbs the fastest on premium tier access.
Bag Size:
Medium and large formats concentrate in commercial kitchen and meal-kit channels, while small sizes fragment across household retail SKUs with significant geographic variation in preferred dimensions.
- Small:Sub-quart capacities target snack portioning and pharmaceutical unit-dose packaging with high SKU proliferation.
- Medium:One to four quart volumes absorb the majority of food service prepared meal packaging demand.
- Large:Gallon-plus formats serve bulk ingredient storage and industrial component organization with enhanced gauge requirements.
- Extra Large:Oversized configurations address commercial linen, textile, and seasonal storage applications.
Medium formats capture the greatest volume concentration; extra large formats expand most quickly on industrial adoption.
End User:
Household and food service segments drive divergent product development priorities, with retail private-label and industrial specification channels operating on distinct procurement cadences and technical requirements.
- Household:Brand-sensitive consumers in premium segments prioritize slider mechanisms and stand-up pouch formats. SC Johnson & Son retail brand strength sustains premium positioning through shelf space dominance and household channel penetration.
- Food Service:Commercial kitchens and meal-kit distributors specify larger formats with enhanced barrier properties for portion control and extended shelf life. Berry Global anchors North American supply through extrusion and converting footprint proximity to major food processing clusters.
- Retail:Private-label partnerships and value-tier positioning characterize this channel with Reynolds Consumer Products competing aggressively on cost structures.
- Industrial:Parts protection, inventory management, and moisture-sensitive component storage drive specifications for heavy-gauge press-seal configurations.
Food service holds the largest share; household retains the steepest expansion trajectory on emerging market retail format adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific supply chain connectivity for polyethylene resin imports and finished zipper bag exports. Container throughput at this hub directly influences raw material availability for extrusion converters across the Yangtze River Delta manufacturing corridor.
United States
Commercial kitchen expansion in the Northeast and meal-kit distributor consolidation drive prepared meal packaging procurement. FDA food-contact regulations govern resin approvals and migration limits for polyethylene formulations. Chicago and Dallas-Fort Worth extrusion clusters concentrate capacity near major food processing operations.
China
Urban household refrigerator penetration and organized retail expansion accelerate retail-format zipper bag adoption. SAMR market supervision and GB standards regulate food-contact plastic safety. The Yangtze River Delta co-locates export manufacturing capacity with surging domestic consumption in Shanghai and Hangzhou.
Germany
REACH restrictions on fluorinated compounds force barrier coating reformulation for grease-resistant applications. ECHA chemical safety protocols accelerate per- and polyfluoroalkyl substance phase-outs. The Rhine-Ruhr industrial corridor hosts converters serving premium household segments in Düsseldorf and Cologne metropolitan areas.
India
Modern trade expansion in tier-two and tier-three cities creates first-time zipper bag demand among organized retail consumers. FSSAI food safety standards and BIS certification requirements shape import and local production compliance. Maharashtra and Gujarat industrial zones concentrate extrusion investment lagging behind consumption growth.
Brazil
Supermarket chain expansion in São Paulo and Rio de Janeiro metropolitan areas drives private-label zipper bag procurement. ANVISA sanitary surveillance regulates food-contact plastic materials for retail applications. The São Paulo state manufacturing belt anchors South American flexible packaging production for regional distribution.
Zipper Bags Market Competitive Landscape
Listed leaders compete with private specialists across extrusion capacity and retail channel access. The supplier base concentrates among multi-national conglomerates with integrated resin-to-film operations and regional converters serving food service procurement. Three archetypes dominate: integrated resin producers with captive film extrusion, brand-anchored household product companies, and private-label specialists competing on cost structures. Capacity expansion and direct sourcing relationship formation constitute the primary competitive moves as meal-kit distributors bypass traditional distribution intermediaries.
Within the brand-anchored tier, SC Johnson & Son, Inc. and Reynolds Consumer Products exemplify household channel dominance through retail shelf space control. Berry Global Group Inc. occupies a position among integrated suppliers with broad North American extrusion and converting footprint. These three entities represent divergent strategic postures: premium brand positioning, value-tier private-label partnership, and supply chain proximity to food processing clusters.
| Leading Market Players |
|---|
| SC Johnson & Son, Inc. |
| Berry Global Group Inc. |
| Reynolds Consumer Products |
| Amcor plc |
| Mondi Group |
| Pactiv Evergreen |
| Novolex |
| Zip-Pak |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
Post-consumer recycled polyethylene mandates in the European Union are displacing virgin resin specifications while simultaneously shifting supply geography toward certified recycler networks and compressing pricing premiums for sustainable grades. This substitution dynamic concentrates procurement power among extrusion converters with backward integration into recycler certification pathways.
Pricing Analysis
Volume-discount tiering structures separate national food service contracts from spot purchases by regional meal-kit distributors, with FDA-compliant resin grades commanding certification premiums over industrial specifications. Price differentiation hinges on migration limit documentation and slider mechanism inclusion, with commercial kitchen buyers exhibiting highest price sensitivity due to portion-control standardization pressures. Pricing pressure stems from ethylene feedstock volatility as naphtha-linked resin costs transmit unevenly through converter margins.
Supply Chain Analysis
Inventory lead times stretch across polyethylene resin import cycles from Saudi Arabia and South Korea, with Yangtze River Delta converters maintaining four-to-six-week safety stocks against ocean freight variability. Raw material dependencies center on ethylene feedstocks, calcium carbonate fillers, and color masterbatches, with supply chain risk concentrated in single-source slider mechanism imports from Chinese molders. Distribution runs through direct converter relationships with meal-kit distributors in the Northeastern United States, displacing traditional packaging distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The zipper bags market sits at a platform-economics inflection where direct sourcing interoperability between meal-kit distributors and extrusion converters is collapsing traditional distribution layers into specification-co-development partnerships.
For Market Incumbents: Consolidate extrusion capacity in Chicago and Dallas-Fort Worth clusters to defend proximity advantages against food processing concentration, while capturing post-consumer recycled content certification early to preempt European Union packaging waste directive compliance deadlines. Backward integration into recycler networks represents the priority lever against feedstock cost volatility. For New Entrants and Emerging Players: E-commerce fulfillment packaging specifications for direct-to-consumer food brands represent a service-layer gap where incumbents under-serve shipping durability requirements with traditional retail-format constructions. Target resealable pouch development for this channel with mono-material polyethylene structures that bypass multi-layer converter complexity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale extruders with captive recycler relationships and FDA compliance documentation. Acquisition targets should demonstrate verified post-consumer content supply agreements and direct sourcing relationships with meal-kit distributors. The signal to watch is California extended producer responsibility enforcement timing as a capacity rationalization catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Recycled Content Certification | European Union packaging waste directives create premium tier access for early-compliant suppliers with verified recycler partnerships. |
| Direct Sourcing Relationship Formation | Meal-kit distributors in the Northeastern United States are bypassing traditional distribution intermediaries for specification co-development. |
| Mono-Material Structure Miniaturization | Simplified polyethylene constructions with enhanced heat-seal layers open supply to mid-scale extruders while maintaining recycling stream compatibility. |
| Slider Mechanism Manufacturing Integration | Captive production of molded plastic sliders reduces import dependency from Chinese single-source suppliers and compresses lead times. |
| Food Service Format Expansion | Commercial kitchen procurement for portion-controlled packaging absorbs larger formats with enhanced barrier properties at volume-driven margins. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with extrusion plant managers, procurement leads at meal-kit distributors, food service operators, and FDA regulatory consultants; and secondary validation against customs trade records, SEC filings from listed packaging conglomerates, and state-level extended producer responsibility regulatory filings. Bottom-up capacity estimates from blown film line counts triangulated against top-down consumption projections from food service operator procurement surveys.
Across the projection horizon, the analytical framework modeled zipper bag demand through segmentation by material chemistry, closure engineering, bag size format, and end-user channel. CAGRs derived from extrusion capacity expansion timelines, refrigerator penetration curves in emerging markets, and regulatory compliance deadline clustering. Industry-specific forecast inputs included ethylene feedstock price elasticity coefficients and direct sourcing relationship formation rates among meal-kit distributors.
Forecasts assume regulatory continuity in FDA food-contact regimes and European Union REACH restrictions; material policy shifts on fluorinated compound phase-outs or state-level plastic restrictions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Side Weld Bags Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Breather Bags Market
Bags and Containers
Baffle Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Insulated Delivery Bag Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Bag-In-Tube Market
Bags and Containers
Compression Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market