
 Wooden Boxes Market | 2026-2036
Wooden Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Boxes Market Outlook
ISPM 15-certified grade is bifurcating the wooden boxes landscape into compliant export-ready suppliers and purely domestic producers. Nefab Group leverages its global certification network to serve automotive and aerospace shippers across multiple continents. GreenPack Industries anchors its position in sustainable packaging through FSC-certified material sourcing and closed-loop pallet programs.
Wooden boxes are rigid containers fabricated from solid timber or engineered wood panels, typically joined by nails, screws, or dovetail joints, with load-bearing capacities ranging from light gift packaging to industrial shipping crates exceeding two metric tons. Their primary purpose spans protective transport, stackable storage, and branded retail presentation across supply chains. Pallet and crate segments dominate volume throughput in logistics corridors, while gift box and decorative categories command higher margin pools in artisan and premium retail channels. Pine material grades sustain cost leadership in bulk shipping applications, whereas oak and cedar concentrates in furniture-grade storage and aromatic retail packaging where durability and aesthetic properties justify premium positioning.
ISPM 15 standards enforced by national plant protection organizations govern heat treatment and marking requirements for international wood packaging movement, directly shaping supplier certification investments and export market access. EPA and OSHA frameworks in the United States regulate wood dust exposure and finishing chemical emissions in manufacturing facilities, influencing capital allocation toward enclosed sanding systems and water-based coatings. Stakeholders must monitor evolving phytosanitary protocols and regional deforestation regulations to anticipate compliance cost shifts and sourcing zone reallocations.
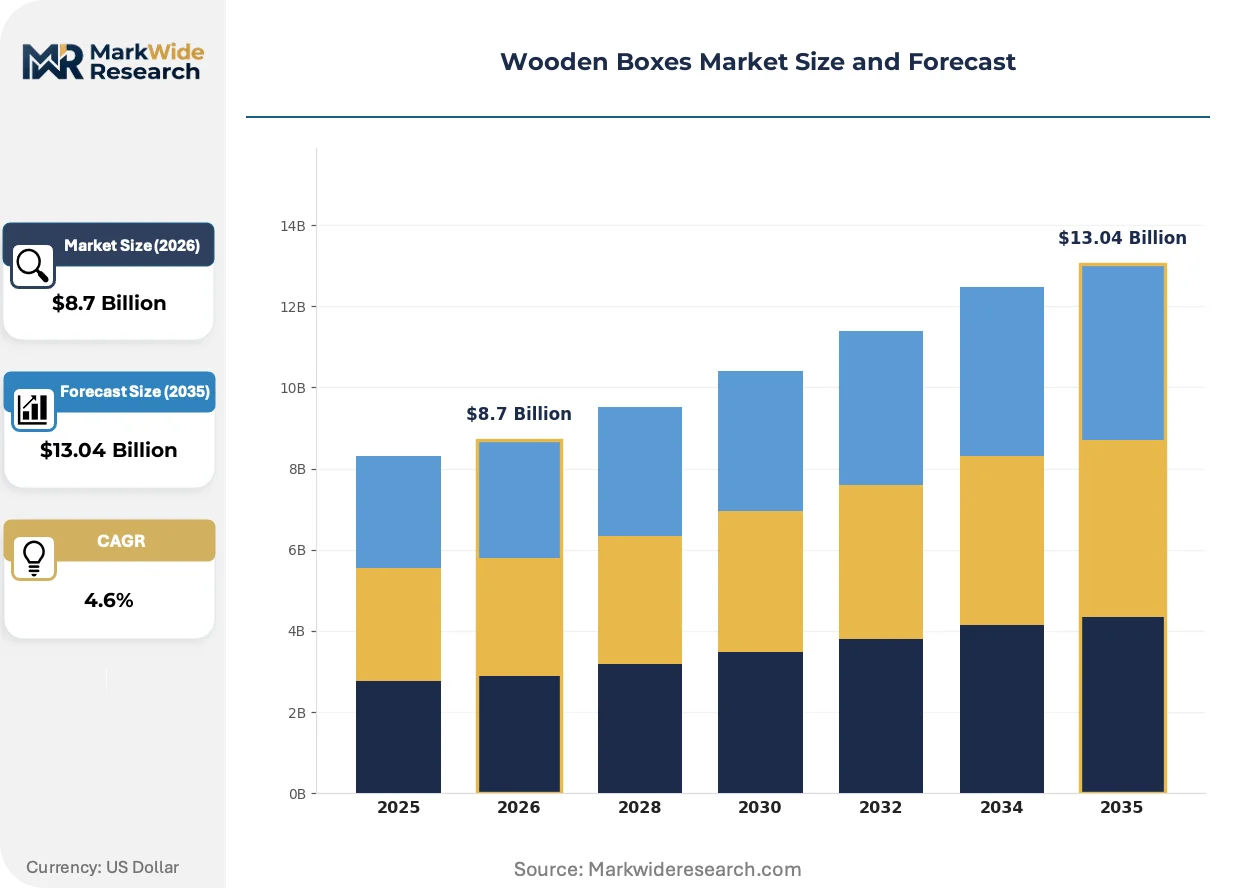
Market Dynamics
ISPM 15 phytosanitary mandates are bifurcating supplier capabilities into certified export-ready and purely domestic tiers, forcing capital reallocation toward heat-treatment infrastructure and traceability systems.
Growth Catalysts
- E-commerce fulfillment expansion:Heavy-goods shipping networks are scaling wooden crate and pallet deployment for durable protection in last-mile and long-haul corridors.
- ISPM 15 compliance mandates:Cross-border wood packaging regulations are tightening worldwide, creating captive demand for certified treatment capacity and marked containers.
- India manufacturing concentration:Domestic production and export channel growth in Indian industrial clusters is absorbing regional timber supply and driving box fabrication scale.
Market Restraints
- Timber input cost volatility:Pine and hardwood lumber prices fluctuate with construction sector demand cycles and regional harvest quotas, compressing margin predictability for bulk shippers.
- Plastic pallet substitution:Injection-molded and composite alternatives are capturing closed-loop logistics contracts where hygiene and weight reduction outweigh initial capex premiums.
- Certification capital intensity:Heat-treatment kiln investments and ISPM 15 audit compliance impose fixed-cost barriers that exclude small fabricators from export-qualified supply pools.
Strategic Opportunities
- FSC-certified sustainable sourcing:Forest Stewardship Council chain-of-custody certification opens premium retail and brand-conscious industrial procurement channels.
- Closed-loop pallet pooling programs:Asset-tracking technology and reverse logistics networks enable per-use pricing models that displace single-trip wooden container purchases.
- Artisan gift box premiumization:Oak, cedar, and dovetail construction techniques command margin multiples in direct-to-consumer and corporate gifting segments.
Industry Challenges
- Heat-treatment technician scarcity:ISPM 15 kiln operation and phytosanitary marking protocols require specialized training that outpaces vocational program output in manufacturing regions.
- Multi-standard compliance complexity:Divergent national plant protection organization interpretations of IPPC guidelines create documentation friction for shippers serving multiple destination markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Boxes Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crate, Pallet, Gift Box, Storage Box Application: Packaging, Storage, Decorative, Shipping Material: Pine, Oak, Birch, Cedar End User: Retail, Food Industry, E-commerce, Artisans |
| Companies Covered | Napa Wooden Box, DNA Packaging System, GreenPack Industries, Raghavendra Wood Industries, V.R. Wooden Industries, Nefab Group, SK Packaging, Kinjal Industries, EMBALEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Boxes Market Strategic Shifts
Digital traceability and automated fabrication are compressing production timelines while regulatory harmonization efforts reshape cross-border qualification requirements across supplier networks.
Radio-frequency identification (RFID) and QR-code embedding in wooden pallets and crates is fragmenting asset management into real-time trackable and untraceable tiers. Third-party logistics providers and automotive OEMs are adopting tagged containers for inventory visibility. This bifurcation is fragmenting procurement decisions between premium connected assets and commodity unmarked boxes.
EPA wood dust exposure limits and OSHA permissible exposure standards are tightening enclosure requirements for sanding and cutting operations in US fabrication facilities. Capital is flowing toward vacuum extraction systems and automated material handling that reduce airborne particulate. Small and mid-sized mills without upgrade capacity are exiting the certified supplier pool or selling to consolidated operators.
Direct sourcing from certified sawmills is displacing multi-layer distributor networks for volume buyers seeking chain-of-custody documentation. Large retail and industrial purchasers are auditing upstream timber origins to satisfy ESG disclosure requirements. This pattern concentrates procurement leverage with integrated suppliers in the Pacific Northwest, Baltic states, and certified plantation zones in Southeast Asia.
Wooden Boxes Market Segmentation
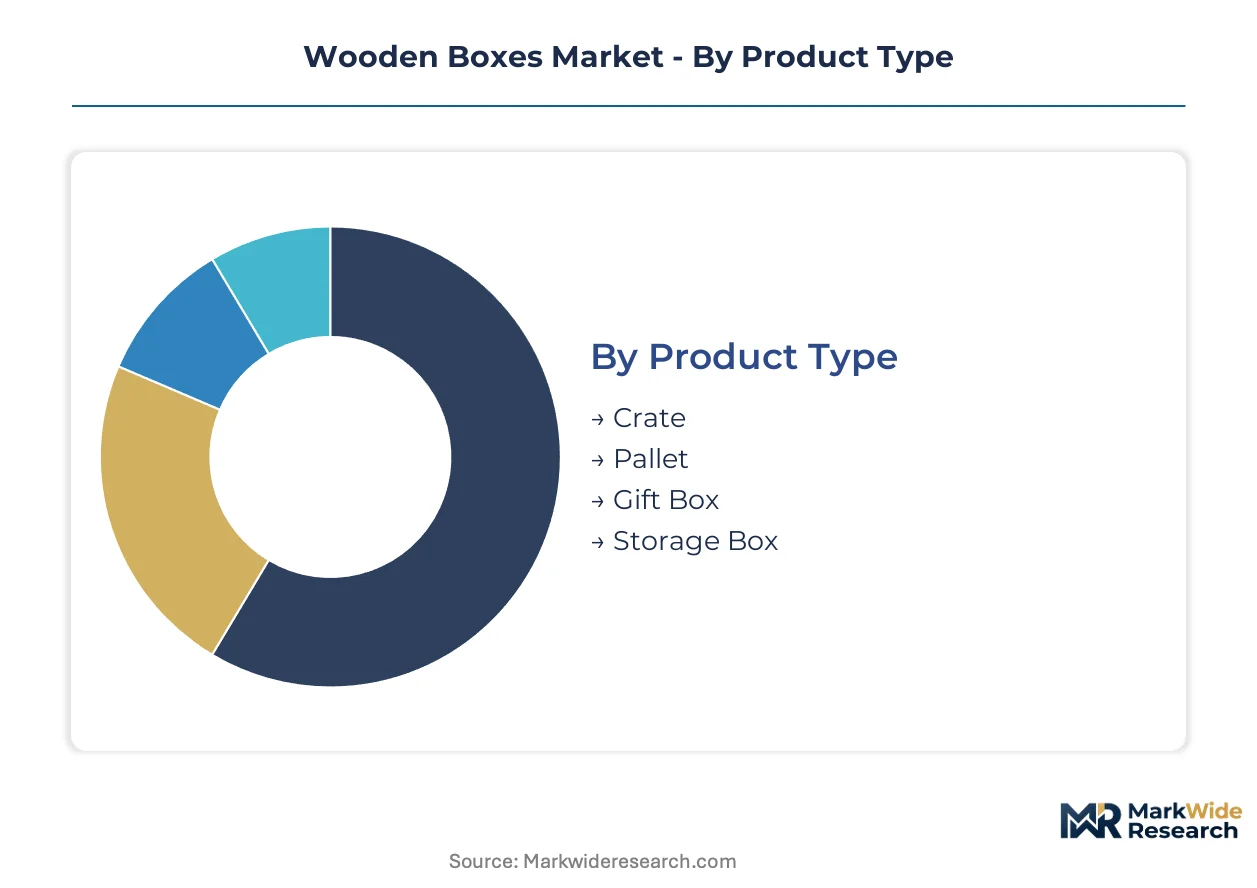
Wooden box segmentation reveals distinct margin profiles across industrial logistics and consumer-facing channels. ISPM 15 certification requirements and e-commerce fulfillment scale create divergent investment priorities for fabricators serving export versus domestic demand pools.
Product Type:
Export-led segments cluster in crate and pallet categories where ISPM 15 heat-treatment mandates dominate procurement specifications, while gift and storage boxes concentrate in domestic retail channels with lighter compliance burdens.
- Crate:Heavy-duty containers built from solid timber or plywood with reinforced corners, designed for loads exceeding 500 kilograms in industrial shipping corridors. Automotive and aerospace shippers in Germany, Japan, and the United States specify crate dimensions to millimeter tolerances for precision component protection.
- Pallet:Flat transport structures with bottom deck boards and stringers, standardized to 1200x800mm Euro dimensions or 48x40 inch North American formats. ISPM 15 marking requirements have bifurcated pallet supply pools into certified export-ready and untreated domestic tiers, with pooling programs capturing closed-loop logistics contracts in France and the Netherlands.
- Gift Box:Decorative containers featuring dovetail joints, hinged lids, and interior lining materials for premium retail presentation. Oak and cedar grades command margin multiples in direct-to-consumer channels and corporate gifting segments across domestic markets.
- Storage Box:Stackable containers with drop-front or lift-top access, often incorporating finger-joint construction for furniture-grade durability. Cedar aromatic properties drive demand in textile and document preservation applications.
Crate holds the largest share; momentum sits with pallet pooling programs.
Application:
Cost tier differentiation separates commodity shipping applications from value-added decorative and storage functions where material grade and finish quality determine pricing power.
- Packaging:Protective enclosures for product presentation and transit, ranging from plain corrugated inserts to branded retail boxes with foil stamping and lacquer finishes. Food industry buyers in India specify pine packaging for spice and dry goods export.
- Storage:Long-term containment solutions emphasizing stackability, moisture resistance, and pest deterrence. Cedar-lined storage boxes concentrate in household organizing and archival applications where aromatic properties justify premium positioning.
- Decorative:Aesthetic-focused containers prioritizing visible grain patterns, joinery craftsmanship, and surface treatments over structural load capacity. Artisan producers in Italy and Japan supply decorative boxes to museum retail and hospitality design channels.
- Shipping:Industrial-grade containers engineered for multi-modal transport stress, including forklift entry points, sling lifting hardware, and moisture-barrier lining. ISPM 15 compliance is mandatory for cross-border shipping applications.
Shipping commands volume leadership; decorative applications capture the steepest margin expansion trajectory.
Material:
Volume concentration in pine grades sustains cost leadership for bulk logistics, while hardwood alternatives penetrate premium positioning channels where durability and aesthetic properties outweigh unit economics.
- Pine:Softwood species harvested from plantation forests, offering favorable strength-to-weight ratios and machinability for high-throughput fabrication. Pallet and crate manufacturers in the Pacific Northwest and Baltic states rely on pine for ISPM 15-certified export production.
- Oak:Dense hardwood with prominent grain patterns and natural tannin content resisting insect infestation. Furniture-grade storage boxes and gift packaging in France and the United Kingdom specify white and red oak for heirloom-quality positioning.
- Birch:Fine-grained hardwood with uniform texture suitable for painted finishes and laser engraving applications. Decorative box producers in Finland and Russia favor birch for premium retail packaging with printed branding.
- Cedar:Aromatic softwood containing natural oils that repel moths and moisture, traditionally deployed in clothing storage and humidor construction. Cedar concentrates in artisan gift box segments where scent properties differentiate commodity alternatives.
Pine dominates tonnage throughput; oak gains share fastest in branded retail channels.
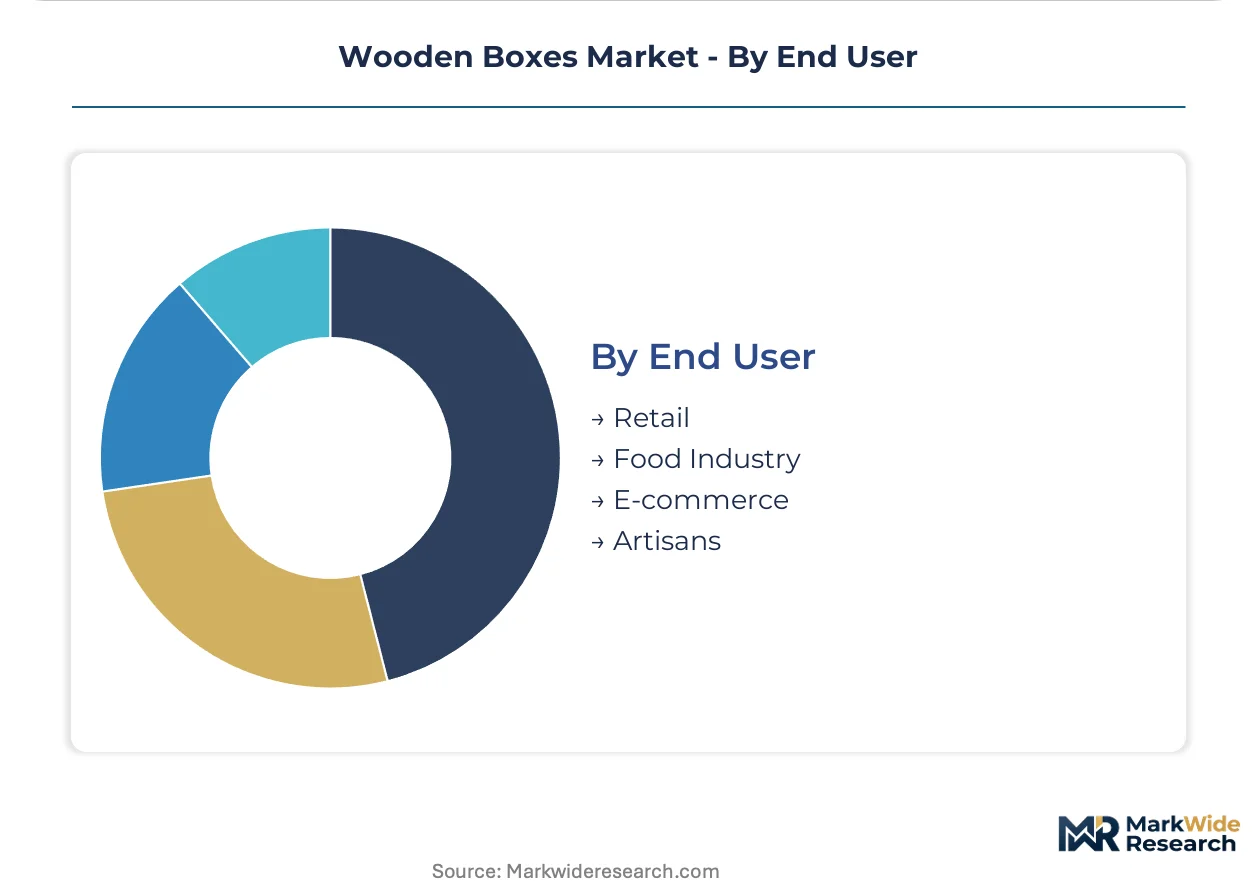
End User:
Customer type fragmentation splits procurement between industrial volume buyers with standardized specifications and fragmented artisan producers with customized batch requirements.
- Retail:Brick-and-mortar and e-commerce merchants sourcing gift boxes, display crates, and branded packaging for consumer sale. FSC chain-of-custody documentation opens premium shelf placement in European and North American retail networks.
- Food Industry:Processors and distributors requiring hygienic, pest-resistant containers for ingredient storage and finished goods shipment. Spice exporters in India and dried fruit shippers in Turkey specify heat-treated pine crates for ISPM 15-compliant export.
- E-commerce:Fulfillment networks scaling wooden pallet and crate deployment for heavy-goods categories where corrugated alternatives fail under load stress. Last-mile durability requirements favor nailed construction over stapled or glued joints.
- Artisans:Small-batch producers and craft cooperatives purchasing unfinished boxes for hand-decoration, pyrography, and mixed-media applications. Cedar and birch blanks concentrate in hobbyist supply channels.
Food industry absorbs the largest certified export volume; e-commerce fulfillment networks are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters in Germany, India, and the United States, with heat-treatment certification networks determining cross-border market access. National plant protection organizations enforce divergent ISPM 15 interpretations that shape supplier qualification requirements.
Germany
Automotive OEMs in Stuttgart and Munich specify millimeter-tolerance wooden crates for precision component protection. KBA vehicle safety standards intersect with packaging durability requirements for heavy machinery export. The Baden-Württemberg industrial corridor hosts certified treatment facilities serving aerospace and automotive shippers.
India
Spice exporters in Kerala and Tamil Nadu drive demand for ISPM 15-certified pine crates in food industry channels. DGFT export promotion schemes incentivize heat-treatment infrastructure investment in manufacturing zones. Raghavendra Wood Industries and Kinjal Industries anchor fabrication scale in domestic production clusters serving both local and export markets.
United States
EPA wood dust exposure limits and OSHA permissible exposure standards tighten enclosure requirements for sanding and cutting operations. Pacific Northwest timber supply feeds certified pallet and crate production for cross-border shipment to Canada and Mexico. Midwest fabrication facilities face capital pressure to upgrade vacuum extraction systems or exit certified supplier pools.
France
White and red oak grades command premium positioning in furniture-grade storage boxes for heirloom-quality retail channels. ECHA chemical regulations govern finishing treatments in decorative box production. The Auvergne-Rhône-Alpes region concentrates artisan producers supplying museum retail and hospitality design networks.
Japan
METI industrial standards shape precision packaging specifications for electronics and machinery export. Cedar and birch decorative boxes concentrate in craft cooperatives serving domestic gift markets. The Kansai region around Osaka maintains traditional joinery techniques for premium retail presentation channels.
Wooden Boxes Market Competitive Environment
Concentration sits with diversified packaging conglomerates and regional specialists. The supplier base fragments across certified export-ready and purely domestic tiers, with ISPM 15 heat-treatment capacity determining market access. Three archetypes dominate: integrated timber-to-box operators with captive sawmill supply, specialist heat-treatment service providers leasing kiln capacity to fabricators, and artisan craft producers serving premium gift channels. Competitive moves center on backward integration into certified timber sourcing and geographic expansion of treatment network coverage.
Among India-based fabricators, Raghavendra Wood Industries and Kinjal Industries exemplify regional scale players serving domestic manufacturing and export channels. GreenPack Industries occupies a position within the sustainable sourcing tier, anchoring FSC-certified material procurement. Nefab Group represents the multinational archetype with global certification networks spanning automotive and aerospace shipper relationships across multiple continents.
| Leading Market Players |
|---|
| Napa Wooden Box |
| DNA Packaging System |
| GreenPack Industries |
| Raghavendra Wood Industries |
| V.R. Wooden Industries |
| Nefab Group |
| SK Packaging |
| Kinjal Industries |
| EMBALEX |
| Others |
Value Chain & Pricing Dynamics
Sixty-day kiln-curing lead times for ISPM 15-certified inventory concentrate pricing power with integrated operators holding captive heat-treatment capacity, while spot-market buyers absorb volatility from untreated lumber spot markets.
Pricing Analysis
ISPM 15 mandates dictate the pricing tier structure across the wooden boxes landscape, separating certified export-ready suppliers from untreated domestic fabricators. Three-tier pricing structure across certified export, compliant domestic, and untreated commodity levels captures quality grade and certification level as primary differentiation drivers. Pricing pressure stems from plastic pallet substitution in closed-loop logistics contracts where hygiene requirements override first-cost considerations. Food industry exporters in India exhibit highest price sensitivity due to thin spice trade margins, while aerospace OEMs in Germany demonstrate lowest sensitivity given precision packaging specifications.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes expose Baltic and Southeast Asian sawmill dependencies for volume pallet producers. Raw material flows draw from pine plantations in the Pacific Northwest, certified hardwood forests in the Baltic states, and plantation timber in Indonesia and Malaysia. Single-source vulnerability concentrates in heat-treatment kiln networks where technician scarcity limits capacity expansion. Distribution runs through third-party logistics providers and direct mill relationships, with large retail purchasers bypassing distributor tiers for chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wooden box incumbents face substitution defense imperatives as injection-molded plastic pallets capture closed-loop logistics contracts through hygiene and weight advantages.
For Market Incumbents: Fortify heat-treatment certification networks against plastic pallet substitution by embedding RFID traceability into pooled pallet programs. Secure captive pine supply through backward integration into certified plantation zones in the Baltic states and Pacific Northwest. ISPM 15 compliance investments remain the priority lever for export market access retention. For New Entrants and Emerging Players: Differentiate on FSC-certified sustainable sourcing to penetrate premium retail and brand-conscious industrial procurement channels. Target artisan gift box segments in domestic markets where oak and cedar craftsmanship commands margin multiples unavailable in commodity shipping tiers. Direct-to-consumer digital channels offer the most penetrable go-to-market angle for small-batch producers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core wooden container operations amid plastic substitution pressures. Long-term viability hinges on certification network density and sustainable sourcing credentials rather than pure manufacturing scale. Watch for ISPM 15 regulatory harmonization efforts across national plant protection organizations as inflection indicator for cross-border market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Treatment Capacity Expansion | ISPM 15 kiln investments secure export qualification for cross-border automotive and aerospace shipments. |
| FSC Chain-of-Custody Certification | Forest Stewardship Council documentation opens premium retail shelf placement in European and North American networks. |
| Closed-Loop Pallet Pooling Programs | Asset-tracking technology enables per-use pricing models that displace single-trip container purchases. |
| Direct Sawmill Sourcing Relationships | Bypassing distributor tiers satisfies ESG disclosure requirements for large retail and industrial purchasers. |
| Artisan Craft Capability Acquisition | Dovetail joinery and cedar finishing skills penetrate premium gift and decorative box margin pools. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with pallet pool operators, food industry export coordinators, automotive packaging engineers, and ISPM 15 certification auditors. Secondary validation drew from customs trade databases, national plant protection organization regulatory filings, Forest Stewardship Council chain-of-custody registries, and timber industry association production surveys. Bottom-up fabrication capacity estimates triangulated against top-down end-use demand segmentation.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, material grade, certification tier, end-use industry, and regional production cluster. CAGRs were derived from regression analysis of historical shipment data against e-commerce fulfillment expansion and regulatory compliance mandate intensity. Forecast inputs incorporated heat-treatment capacity buildout pipelines and plastic substitution elasticity parameters.
Material uncertainties — timber price volatility from construction sector demand cycles, divergent ISPM 15 interpretation shifts by national regulators, and accelerated plastic pallet adoption in hygiene-sensitive logistics — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification network expansion and sustainable sourcing penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bags and Containers Market
Bags and Containers
Net Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Air Bubble Bags Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Flat Bottom Bags Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Vacuum Shrink Bags Market