
 Global Bag Filling Machines Market | 2026-2036
Global Bag Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bag Filling Machines Market Analysis
The shift from single-source to multi-source equipment procurement is hardening among pharmaceutical and chemical processors. Harro Höfliger leverages its cleanroom engineering heritage to anchor high-containment filling contracts. Bausch Advanced Technology Group sustains differentiation through specialized barrier isolation technology for potent compounds. PLÜMAT competes on modular platform designs that reduce validation timelines for multi-product facilities.
Bag filling machines are automated or semi-automated systems that dispense measured quantities of powder, granule, liquid, or paste into pre-formed bags, pouches, or sacks, typically achieving fill accuracies within 0.5-1.0% for pharmaceutical applications and operating at speeds from 10 to 200 cycles per minute depending on product characteristics and bag format. These systems serve primary packaging operations across food processing, pharmaceutical manufacturing, and agricultural chemical blending where precise dosing, contamination control, and seal integrity determine product shelf life and regulatory compliance. Automatic technology leads installed capacity in high-volume food and beverage plants where line integration with upstream weighing and downstream palletizing maximizes throughput. Auger fillers occupy the fastest-growing product position as fine powder formulations expand in specialty nutrition and active pharmaceutical ingredient packaging where volumetric consistency proves critical.
FDA cGMP guidelines and EMA Annex 1 revision on sterile manufacturing shape equipment validation requirements and barrier design specifications for pharmaceutical applications. EPA emissions standards and OSHA dust exposure limits influence enclosed filling system architecture in chemical and agricultural processing environments. REACH substance restrictions constrain polymer selection for product-contact surfaces in European pharmaceutical installations. Stakeholders must monitor evolving cleanroom classification harmonization between FDA, EMA, and China's NMPA as this determines capital equipment specification standards and retrofit obligations across multinational manufacturing networks.
Market Dynamics
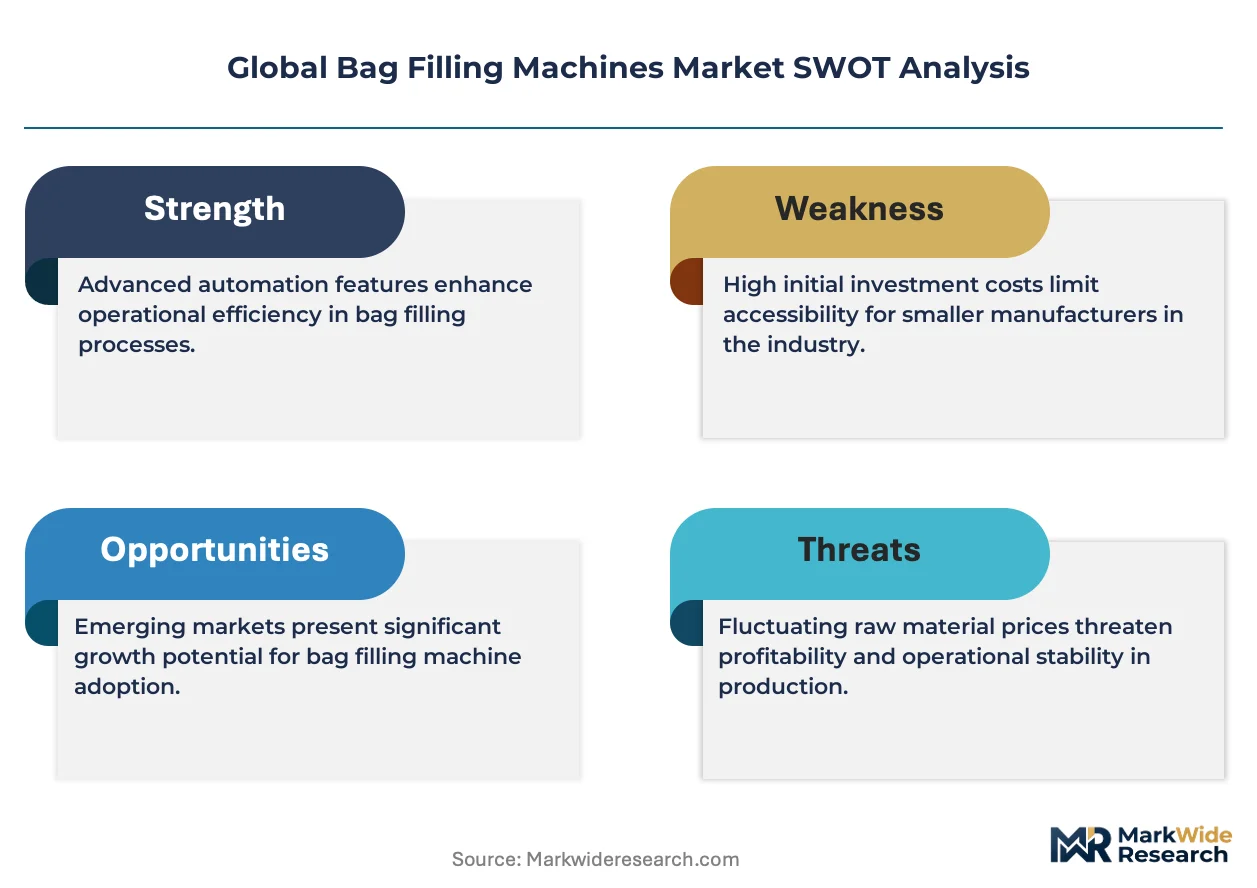
Pharmaceutical manufacturers are consolidating filling line procurement around multi-product capable platforms to reduce validation overhead and facility footprint across their global manufacturing networks.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:Updated barrier isolation requirements are compelling European pharmaceutical facilities to replace legacy open-filling systems with closed-loop alternatives.
- Specialty nutrition powder formulations:Protein fortification and probiotic blends are expanding auger filler deployments in contract packaging operations serving direct-to-consumer brands.
- China's NMPA GMP harmonization:Alignment with FDA and EMA standards is accelerating equipment upgrades at domestic pharmaceutical manufacturers targeting export markets.
Market Restraints
- Stainless steel alloy cost volatility:Grade 316L price fluctuations compress margins for equipment builders sourcing pharmaceutical-grade contact surfaces.
- High-containment component supply concentration:Isolator glove ports and HEPA filtration units depend on a limited supplier base concentrated in Germany and Switzerland.
- Cleanroom classification misalignment:Divergent ISO 14644 interpretations between FDA, EMA, and NMPA extend validation timelines for multinational deployments.
Strategic Opportunities
- India's CDSCO manufacturing incentives:Production-linked incentive schemes for active pharmaceutical ingredients are driving greenfield filling line investments at domestic and multinational facilities.
- Biologic single-use integration:Pre-sterilized disposable product-contact paths are converging with traditional stainless steel architectures in multi-product facilities.
- Remote validation protocols:FAT and SAT execution via augmented reality guidance is reducing travel-dependent commissioning for geographically dispersed installations.
Industry Challenges
- Containment engineering talent scarcity:Qualified specialists capable of integrating barrier isolation with powder handling systems command premium compensation and extended recruitment cycles.
- Legacy control system integration:Proprietary PLC architectures from 1990s-era installations resist seamless connectivity with modern MES and batch tracking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bag Filling Machines Market |
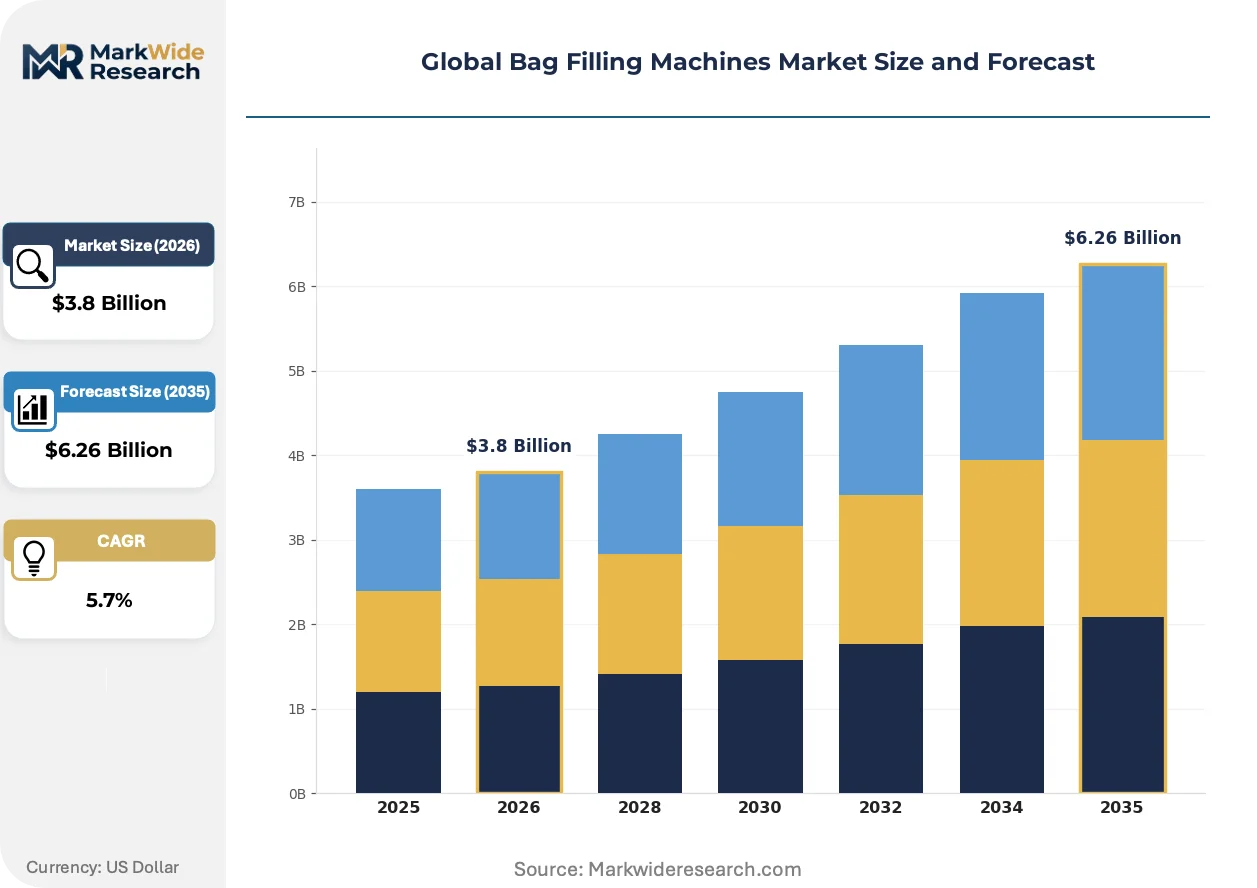
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Fillers, Horizontal Fillers, Auger Fillers, Cup Fillers End User: Food & Beverage, Pharmaceuticals, Chemicals, Agriculture Technology: Automatic, Semi-Automatic, Manual, Robotics Material: Plastic, Metal, Glass, Others |
| Companies Covered | PLÜMAT, Dara Pharma, Bausch Advanced Technology Group, Kiefel Technologies, Harro Höfliger, Comecer, NJM, WICK Machinery, GF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bag Filling Machines Market Emerging Trajectories
Equipment architectures are pivoting from fixed-purpose lines toward reconfigurable platforms that accommodate multiple product formats without mechanical changeover. This shift compresses capital deployment timelines and reduces redundant installed capacity.
Machine vision inspection systems are converging with robotic pick-and-place modules to enable real-time rejection of defective seals and foreign particle detection at line speeds exceeding 150 cycles per minute. Pharmaceutical contract manufacturers in Germany and Switzerland are piloting these integrated cells for high-potency compound packaging. The convergence is collapsing the traditional separation between filling and inspection stations, reducing cleanroom footprint requirements by 30-40 percent in greenfield designs.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing European equipment builders to qualify alternative polymer formulations for product-contact seals and gaskets. Fluoropolymer replacements must demonstrate equivalent chemical resistance and extractables profiles under EMA guidance. Pharmaceutical-grade equipment destined for European markets is experiencing extended material qualification timelines as suppliers validate compliant elastomer compounds.
Multi-year service contracts with performance-based uptime guarantees are displacing transactional spare parts and break-fix arrangements among large pharmaceutical processors. Equipment vendors are embedding predictive maintenance sensors and remote diagnostics capabilities to underwrite availability commitments. This model is most advanced in North American and Western European installations where processor consolidation has concentrated buyer negotiating leverage.
Global Bag Filling Machines Market Segmentation
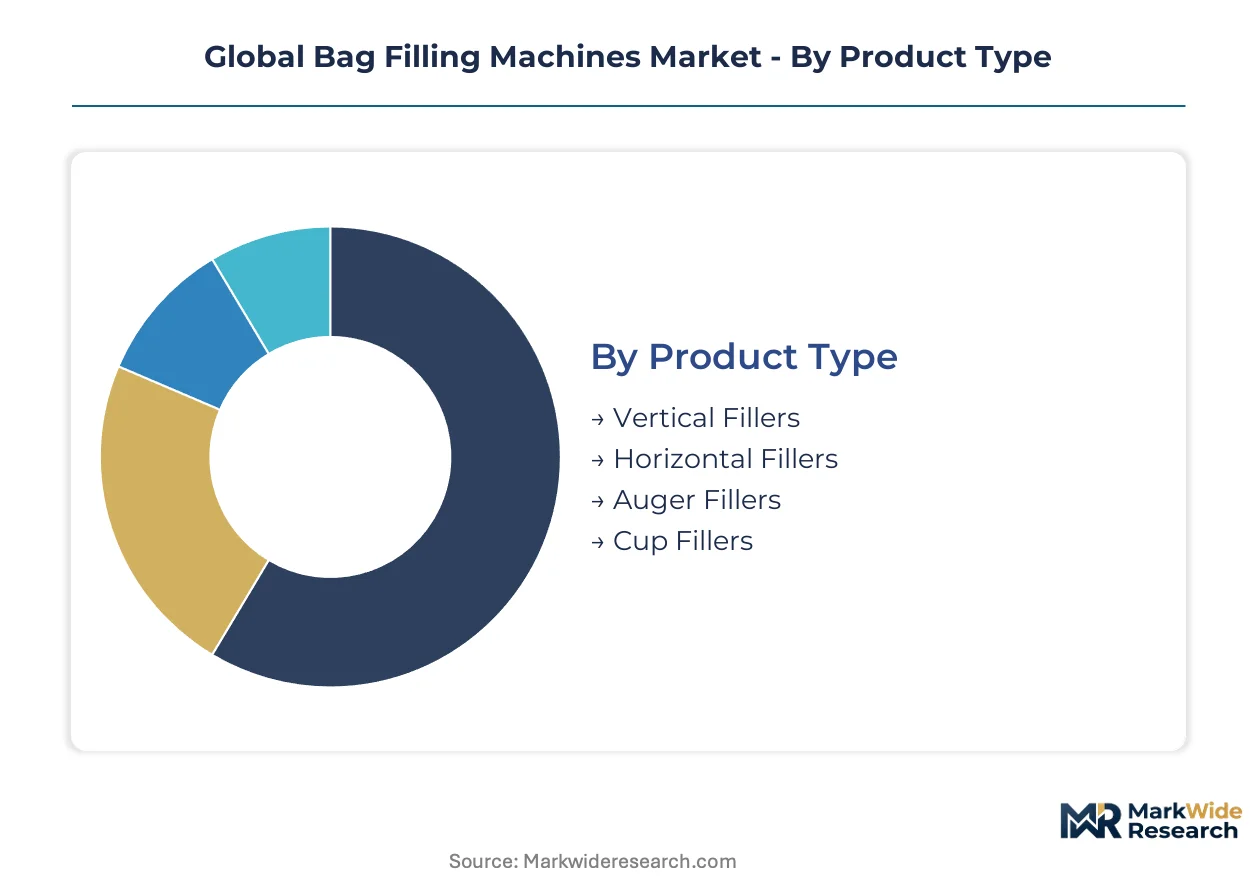
Segmentation in bag filling machines determines integration complexity with upstream weighing systems and downstream palletizing equipment. Equipment specification varies sharply between standalone installations for contract packagers and embedded lines at integrated manufacturing facilities.
Product Type:
Vertical fillers dominate standalone deployments where floor space constraints limit line extension, while horizontal architectures embed more naturally into continuous flow systems.
- Vertical Fillers:Gravity-fed or pneumatic systems drop product through a vertical filling tube into bags held by clamping jaws, achieving compact footprints under three meters in height. Food and beverage plants in Germany favor these for retrofit installations where ceiling clearance restricts horizontal line expansion. EMA Annex 1 revisions on sterile manufacturing are accelerating isolator-integrated vertical designs for pharmaceutical applications.
- Auger Fillers:Screw-based volumetric dispensing mechanisms handle cohesive powders and fine granules with fill accuracies meeting pharmaceutical cGMP requirements. Specialty nutrition contract packagers in the United States deploy these for protein and probiotic formulations where density variation demands precise screw geometry calibration. REACH compliance timelines for fluoropolymer seal alternatives extend qualification cycles for European-bound equipment.
- Horizontal Fillers:Linear transport systems move bags through filling stations arranged in horizontal planes, enabling longer dwell times for viscous products.
- Cup Fillers:Intermittent volumetric chambers scoop and deposit free-flowing granules at speeds up to 120 cycles per minute.
Volume placements concentrate in vertical fillers; the faster expansion belongs to auger fillers.
End User:
End-user segmentation tracks regulatory burden intensity, with pharmaceutical and chemical processors facing containment engineering requirements that food and beverage installations rarely encounter.
- Food & Beverage:High-speed lines integrate with upstream multi-head weighers and downstream metal detectors in continuous operation modes. Bakery and snack producers in China deploy these for pillow pouch formats at throughputs exceeding 200 units per minute. FDA food safety modernization rules drive clean-in-place system specifications.
- Pharmaceuticals:Barrier isolation and HEPA filtration dominate equipment architecture for potent compound handling. CDSCO production-linked incentives in India are catalyzing greenfield investments at API manufacturers seeking export certification. Containment engineering talent scarcity extends commissioning timelines for high-potency installations.
- Chemicals:EPA emissions standards and OSHA dust exposure limits mandate enclosed system designs for agricultural and industrial chemical blending.
- Agriculture:Bulk sack filling for seeds and fertilizers prioritizes throughput over precision, with semi-automatic modes common in seasonal operations.
Food and beverage accounts for the largest installed base; pharmaceuticals are climbing the fastest as containment requirements intensify.
Technology:
Technology tiers separate capital-intensive automatic lines from labor-dependent manual systems, with robotics emerging as a hybrid category bridging flexibility and throughput.
- Automatic:Servo-driven filling heads synchronize with conveyor pacing and reject stations without operator intervention. Integrated dairy and beverage plants in Switzerland run these 24-hour cycles with predictive maintenance underwriting uptime guarantees. Remote validation protocols via augmented reality are reducing FAT execution costs.
- Robotics:Articulated arms handle bag presentation and sealing with vision-guided pick-and-place precision. German pharmaceutical contract manufacturers pilot these for high-potency compound packaging where human exposure must approach zero. Machine vision convergence collapses traditional filling-inspection station separation.
- Semi-Automatic:Operator-fed bag loading with automated filling and discharge sequences suits mid-volume processors with SKU variability.
- Manual:Foot-pedal or hand-triggered dispensers serve micro-batch operations and regulatory sample preparation.
Automatic systems hold the dominant share; robotics are gaining share fastest in high-containment pharmaceutical applications.
Material:
Material selection for product-contact surfaces responds to chemical compatibility requirements and regulatory extractables testing protocols.
- Metal:Grade 316L stainless steel dominates pharmaceutical and food-grade installations for corrosion resistance and cleanability validation. Stainless steel alloy cost volatility compresses equipment builder margins during nickel price spikes. Surface finish specifications per ASME BPE govern Ra values for biologic product contact.
- Plastic:UHMW polyethylene and PTFE-lined components reduce friction in abrasive powder handling. REACH substance restrictions on per- and polyfluoroalkyl substances force European builders to qualify alternative polymer formulations for seals and gaskets.
- Glass:Borosilicate sight glasses and gauge covers provide visual process monitoring in corrosive chemical environments.
- Others:Ceramic linings and elastomer composites address niche abrasion and temperature extremes.
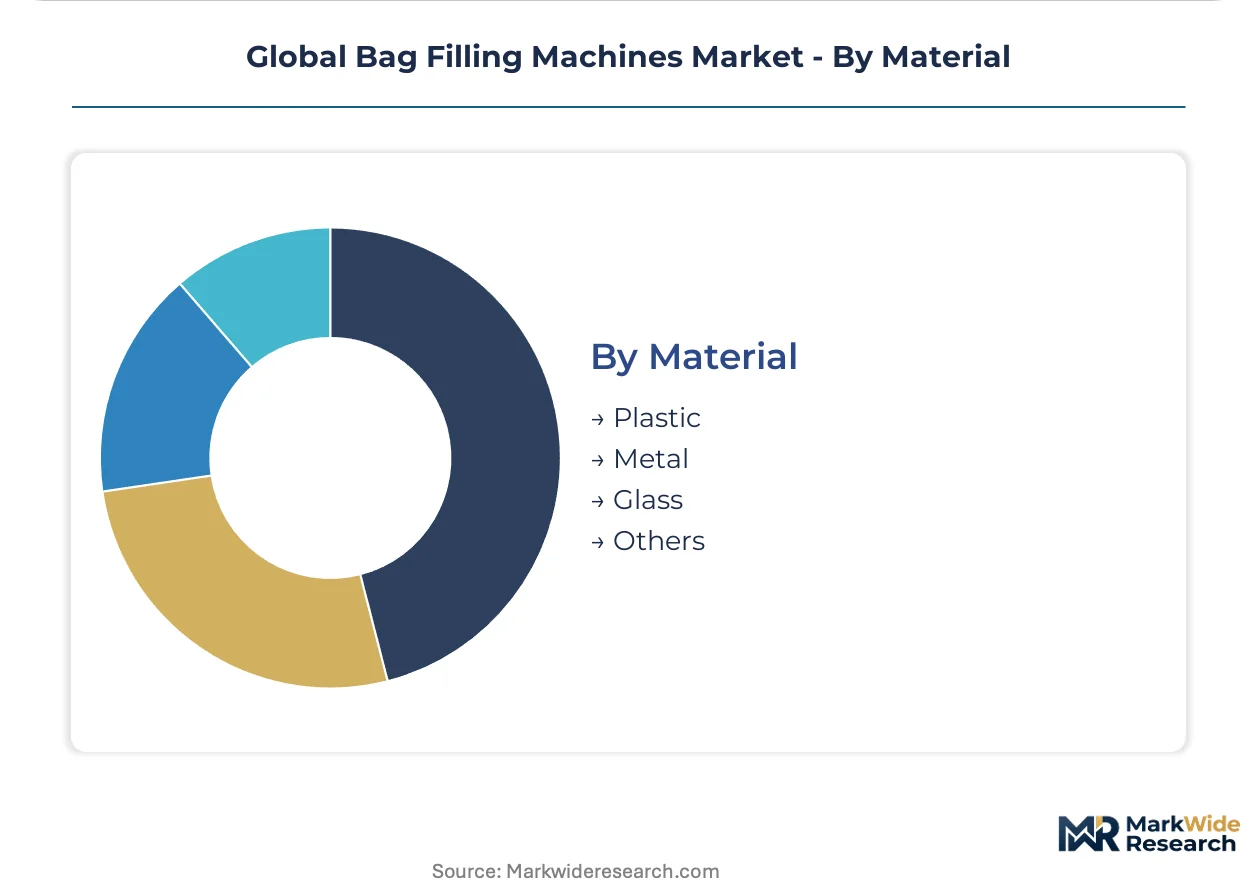
Metal constructions command the premium tier; plastic components are expanding most quickly as fluoropolymer alternatives reach qualification maturity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for bag filling machines concentrates in pharmaceutical manufacturing clusters and food processing hubs across Germany, China, and the United States, with regulatory harmonization pressures accelerating equipment replacement cycles in export-oriented facilities.
Germany
EMA Annex 1 sterile manufacturing revisions are compelling pharmaceutical facilities in Baden-Württemberg and Bavaria to replace legacy open-filling systems with closed-loop barrier isolator designs. The country's national pharmaceutical regulator enforces strict cleanroom classification standards that extend validation timelines for multinational deployments. Stuttgart and Karlsruhe host concentrated engineering talent pools where containment specialists command premium compensation for high-potency compound integration projects.
China
NMPA GMP harmonization with FDA and EMA standards is accelerating equipment upgrades at domestic pharmaceutical manufacturers targeting export markets. The country's national medical products administration mandates alignment with international sterile manufacturing protocols for API facilities seeking overseas certification. Yangtze River Delta pharmaceutical clusters in Shanghai and Suzhou are deploying automated filling lines to meet contract manufacturing demand from European and North American sponsors.
United States
FDA cGMP guidelines and food safety modernization rules drive clean-in-place system specifications across dairy, beverage, and pharmaceutical processing plants. The national food and drug administration maintains rigorous extractables testing protocols for product-contact surfaces in biologic manufacturing. New Jersey and Massachusetts pharmaceutical corridors are consolidating procurement around multi-product capable platforms to reduce validation overhead across global manufacturing networks.
India
CDSCO production-linked incentive schemes for active pharmaceutical ingredients are catalyzing greenfield filling line investments at domestic and multinational facilities. The national pharmaceutical regulator's manufacturing incentives target export certification for API producers supplying regulated markets. Maharashtra and Gujarat pharmaceutical manufacturing zones are experiencing accelerated capital deployment as contract manufacturers expand capacity for international sponsors.
Switzerland
Swissmedic pharmaceutical regulations and high-containment manufacturing traditions sustain demand for barrier isolation engineering in Basel and Zurich pharmaceutical clusters. The national pharmaceutical regulator maintains stringent standards for potent compound handling that exceed baseline EMA requirements. Swiss contract manufacturers are piloting machine vision-integrated robotic cells for high-potency packaging where human exposure must approach zero.
Global Bag Filling Machines Market Vendor Landscape
Multi-product platform development dominates the current landscape as pharmaceutical processors consolidate procurement around flexible architectures. The vendor base separates into three distinct tiers: integrated pharmaceutical equipment conglomerates with cleanroom engineering heritage, specialized barrier isolation technology providers, and modular platform designers focused on validation compression. Strategic archetypes include high-containment engineering specialists, multi-format reconfigurable platform builders, and predictive maintenance service contract underwriters. Geographic expansion through regional assembly partnerships and technology licensing for isolator component supply are displacing pure equipment sales as primary growth vectors.
Among German-based engineering specialists, Harro Höfliger and PLÜMAT occupy positions representing contrasting strategic approaches to pharmaceutical-grade equipment supply. Harro Höfliger exemplifies the cleanroom engineering heritage archetype with deep institutional knowledge of barrier isolation integration. PLÜMAT sits within the modular platform design tier where standardized subsystems reduce customer validation timelines. Bausch Advanced Technology Group anchors the specialized barrier isolation technology segment, representing the concentrated expertise required for potent compound manufacturing environments. These three fabricators collectively illustrate the competitive segmentation between integrated system provision and component-level specialization that defines current procurement patterns.
| Leading Market Players |
|---|
| PLÜMAT |
| Dara Pharma |
| Bausch Advanced Technology Group |
| Kiefel Technologies |
| Harro Höfliger |
| Comecer |
| NJM |
| WICK Machinery |
| GF |
| Others |
Supply Flow & Price Mechanics
Family-owned German engineering specialists anchor the mid-tier equipment segment, sustaining pricing discipline through captive fabrication capabilities while private-equity-rolled-up pharmaceutical automation conglomerates compress margins via volume bundling. Stainless steel alloy cost volatility and REACH compliance timelines for fluoropolymer alternatives create asymmetric pressure across ownership structures, forcing family-owned builders to absorb input spikes or cede share to better-capitalized competitors with hedging programs.
Pricing Analysis
Volume placements concentrate in standard vertical fillers where price competition runs intense among Chinese and Indian fabricators; margin capture concentrates in isolator-integrated auger systems for high-potency pharmaceutical applications. Three-tier pricing structure across premium isolator-integrated, standard automated, and semi-automatic economy levels separates buyers by containment requirement and validation burden. Pricing pressure stems from stainless steel alloy cost volatility and compressed qualification timelines for REACH-compliant polymer alternatives. Contract packaging operations serving direct-to-consumer nutrition brands exhibit highest price sensitivity; multinational pharmaceutical processors consolidating global procurement show lowest sensitivity due to total-cost-of-ownership framing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale pharmaceutical processor demand with embedded service contracts, while specialized distributors serve mid-tier food and beverage retrofit installations across fragmented plant footprints. Component supply concentrates in Germany for precision servo drives, Switzerland for HEPA filtration units and isolator glove ports, and China for structural frames and pneumatic subassemblies. Raw material dependencies rest on nickel-priced 316L stainless steel, fluoropolymer seal compounds, and rare-earth magnet materials for servo motors. Single-source vulnerability in high-containment component supply extends lead times for pharmaceutical-grade equipment. Distribution runs through regional assembly partnerships in India and Southeast Asia for tariff-advantaged access to export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA Annex 1 sterile manufacturing revisions erect formidable barrier-to-entry moats for equipment builders with validated isolator integration capabilities, marginalizing generalist fabricators lacking cleanroom engineering heritage.
For Market Incumbents: Deploy predictive maintenance sensor embedding to underwrite performance-based uptime guarantees and lock in multi-year service contract renewals. Consolidate procurement of HEPA filtration units and glove port components through captive supply arrangements with Swiss and German specialists to mitigate single-source vulnerability. Counter emerging Chinese automation conglomerates seeking share through price-aggressive standard filler offerings by emphasizing containment engineering differentiation in pharmaceutical verticals. For New Entrants and Emerging Players: Launch via technology licensing partnerships with established isolator component suppliers to bypass multi-year validation timelines for barrier isolation integration. Target India's CDSCO production-linked incentive-driven API manufacturing zones where greenfield filling line demand outstrips qualified local supply. Penetrate through modular platform architectures that compress customer validation timelines versus integrated system incumbents, capturing contract manufacturers managing multi-product facilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized barrier isolation technology providers with Swissmedic-validated containment engineering credentials in Switzerland and Germany. Long-term viability hinges on regulatory harmonization trajectory across FDA, EMA, and NMPA standards, favoring equipment builders with multi-jurisdiction validation experience over regional specialists. Watch for CDSCO manufacturing incentive scheme extensions as inflection signal for sustained Indian capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Integrated Platform Development | EMA Annex 1 compliance mandates accelerate replacement of legacy open-filling architectures. |
| Predictive Maintenance Sensor Embedding | Performance-based uptime guarantees displace transactional break-fix service arrangements. |
| Regional Assembly Partnership Expansion | India and Southeast Asia hubs enable tariff-advantaged access to export-oriented pharmaceutical facilities. |
| REACH-Compliant Polymer Qualification | Fluoropolymer alternatives for seals and gaskets extend material validation timelines for European-bound equipment. |
| Remote Validation Protocol Deployment | Augmented reality-guided FAT and SAT execution reduces travel-dependent commissioning costs. |
Methodological Framework
Document review covered FDA cGMP guidance documents, EMA Annex 1 sterile manufacturing revisions, and REACH substance restriction registers, complemented by interviews with plant engineers at pharmaceutical manufacturing facilities, procurement leads at contract packaging operations, aftermarket service heads at equipment vendors, and containment engineering specialists. Secondary validation drew from customs trade data, SEC filings of publicly traded automation conglomerates, and industry association technical standards. Bottom-up equipment shipment estimates triangulated against top-down pharmaceutical capital expenditure disclosures.
Unit and value projections across the analysis window reflect segmentation by product type, end-user industry, automation technology tier, and regional regulatory cluster. Modeled dimensions incorporated fill accuracy requirements, containment classification levels, and cleanroom integration complexity. CAGRs derived from historical shipment trajectories adjusted for regulatory-driven replacement cycle acceleration and greenfield facility commissioning patterns. Forecast inputs included stainless steel alloy price indices and pharmaceutical manufacturing incentive scheme announcements.
The model assumes a particular technology adoption path for single-use disposable product-contact path integration; alternative pathways for hybrid stainless steel-disposable architectures would alter the outlook for traditional equipment builders. Forecasts reflect assumptions regarding regulatory harmonization timing and raw material cost stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Cross Bottom Bags Market
Bags and Containers
Padding Bags Market
Bags and Containers
Octabin Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Laser Scored Bags Market