
 Anti-Static Polyethylene Bag Market | 2026-2036
Anti-Static Polyethylene Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Polyethylene Bag Market Outlook
The capital-intensity divergence between automated film extrusion lines and manual bag-conversion operations is reorganizing competitive tiers in the anti-static polyethylene bag landscape. 3M Company leverages its materials science heritage to sustain premium positioning in static-dissipative additive formulations. Protective Packaging Corporation anchors North American supply through vertically integrated blown-film and bag-conversion assets. Daklapack Group competes across European pharmaceutical corridors with cleanroom-certified conversion capabilities.
Anti-static polyethylene bags are engineered from low-density or linear low-density polyethylene resins compounded with migratory or permanent anti-static agents such as glycerol monostearate or carbon black, then extruded into monolayer or coextruded films with surface resistivity typically ranging from 10^9 to 10^11 ohms per square to prevent electrostatic discharge damage to sensitive components. The product type dimension shows flat bags occupying the volume baseline for commodity electronics bundling while custom bags capture margin pools from semiconductor wafer shippers requiring dimensional precision and lot-traceability printing. End user concentration in electronics manufacturing drives specification stringency, with pharmaceutical applications expanding fastest as biologics packaging adopts static-controlled primary containment.
FDA regulations govern pharmaceutical contact applications through USP Class VI and 21 CFR 177.1520 compliance for olefin polymers, while EPA oversight of per- and polyfluoroalkyl substances pressures reformulation away from certain fluorinated anti-static coatings. The EU REACH framework restricts specific phthalate plasticizers and mandates SCIP database registration for articles containing substances of very high concern, directly shaping additive selection and supplier qualification protocols. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that will redefine post-consumer recycling obligations for single-use polyethylene packaging.
Market Dynamics
Semiconductor fabrication facilities in Taiwan and South Korea are driving procurement concentration for static-dissipative containment, while EU REACH and RoHS compliance costs restructure additive formulation economics across the supply base.
Growth Catalysts
- Wafer-level packaging expansion:Advanced semiconductor packaging operations in East Asian manufacturing clusters require precision-engineered static-dissipative containment with lot-traceability printing capabilities.
- REACH SVHC registration mandates:The EU SCIP database requirement for substances of very high concern is forcing additive transparency and qualifying compliant suppliers for European electronics corridors.
- Biologics cold-chain proliferation:Pharmaceutical primary containment for temperature-sensitive biologics is adopting static-controlled polyethylene solutions to prevent electrostatic discharge damage to active pharmaceutical ingredients.
Market Restraints
- Ethylene feedstock volatility:Crude oil price fluctuations directly compress margins for low-density polyethylene resin converters without long-term supply contracts.
- East Asian supply concentration:Blown-film extrusion capacity clusters in Taiwan, South Korea, and coastal China create geographic vulnerability to regional logistics disruptions.
- Fluorinated coating phase-out:EPA oversight of per- and polyfluoroalkyl substances pressures reformulation away from certain high-performance anti-static surface treatments.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO regulatory alignment with USP Class VI standards creates entry pathways for cleanroom-certified converters serving domestic biologics manufacturers.
- Carbon black additive innovation:Permanent anti-static formulations using conductive fillers are converging with thin-gauge film extrusion to enable downsized packaging footprints.
- Extended producer responsibility tailwinds:California and New York state-level recycling mandates will reshape post-consumer polyethylene collection infrastructure, favoring early compliance investments.
Industry Challenges
- Cleanroom certification timelines:ISO 14644-1 Class 7 and Class 8 qualification protocols for bag-conversion facilities extend customer onboarding cycles by 12-18 months.
- Multi-layer coextrusion capex barriers:Automated film lines with static-dissipative layer control require capital outlays that mid-tier converters cannot finance internally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Polyethylene Bag Market |
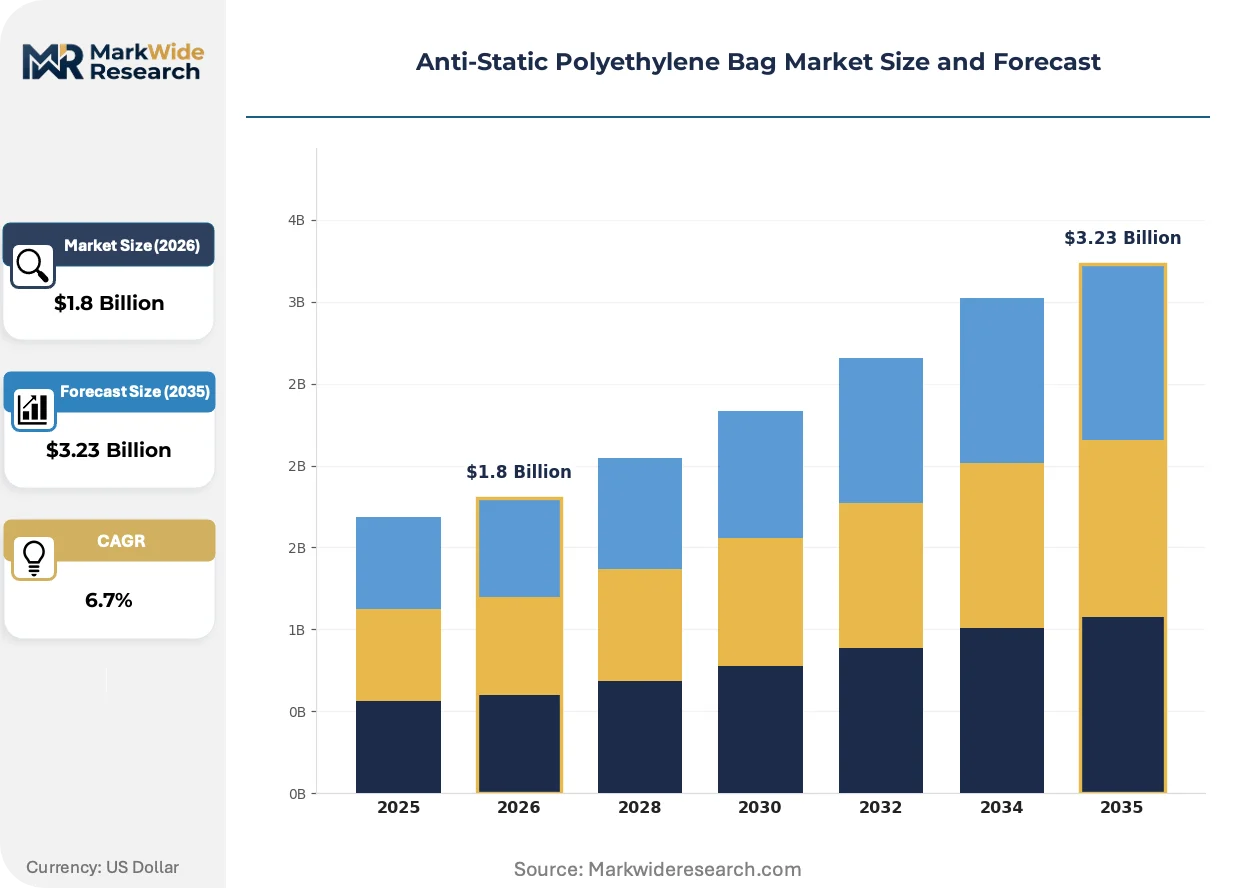
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Zip Lock Bags, Custom Bags Dimension: Small, Medium, Large, Extra Large End User: Electronics, Pharmaceuticals, Automotive, Retail Packaging Type: Rolls, Bundles, Pallets, Boxes |
| Companies Covered | Protective Packaging Corporation, 3M Company, Daklapack Group, Teknis Limited, Dou Yee Enterprises Singapore, Automated Packaging Systems, Pregis LLC, IMPAK Corporation, Polyplus Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Polyethylene Bag Market Strategic Shifts
Additive formulation science and regulatory compliance frameworks are restructuring competitive advantage in static-dissipative polyethylene, with technology differentiation separating premium converters from commodity suppliers.
Permanent anti-static agent technology is bifurcating the market between migratory glycerol monostearate formulations and carbon black conductive compounds. Semiconductor wafer shippers are adopting carbon black systems for humidity-independent performance. This technology is bifurcating pricing tiers between precision-grade and commodity electronics bundling applications.
EU REACH restrictions on phthalate plasticizers and mandated SCIP database registration are reshaping supplier qualification protocols. Electronics manufacturers now require full additive disclosure across the supply chain. European pharmaceutical corridors are most affected, with converters accelerating permanent anti-static formulation shifts to avoid migratory agent regulatory scrutiny.
Direct procurement relationships between semiconductor fabs and certified converters are displacing distributor intermediaries in high-specification segments. Tier-one electronics manufacturers are consolidating vendor bases to reduce qualification overhead. Taiwan and South Korean fabrication clusters exhibit this pattern most visibly, with cleanroom-certified converters capturing multi-year supply agreements.
Anti-Static Polyethylene Bag Market Segmentation
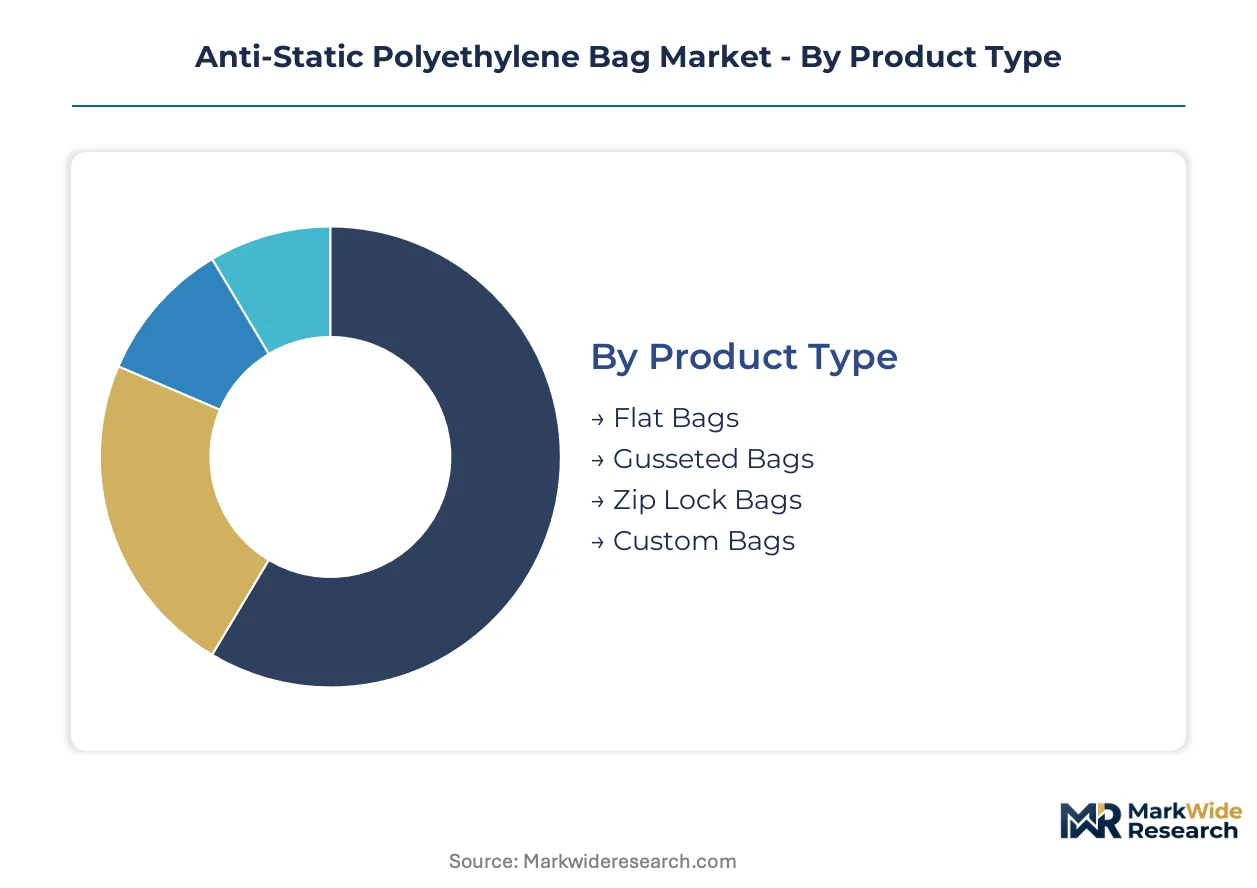
Segmentation in anti-static polyethylene bags reveals how specification intensity varies dramatically across end-use applications. Electronics manufacturers demand precision-engineered solutions with lot-traceability printing, while pharmaceutical cold-chain applications prioritize USP Class VI compliance over dimensional complexity.
Product Type:
Substitute pressure from flexible laminated pouches and rigid clamshell packaging varies sharply across bag architectures, with commodity formats facing the strongest displacement risk from lower-cost alternatives.
- Flat Bags:Monolayer or coextruded films with surface resistivity of 10^9 to 10^11 ohms per square serve commodity electronics bundling and component kitting operations. Taiwan and South Korean semiconductor fabs specify flat bags for wafer cassette interleaving, though carbon black formulations are displacing glycerol monostearate systems in humidity-controlled cleanrooms.
- Custom Bags:Precision-dimensioned containment with printed lot codes and electrostatic discharge shielding layers captures specification-intensive semiconductor wafer shipping applications. Wafer-level packaging expansion in East Asian manufacturing clusters drives demand for dimensional tolerances within millimeter-grade precision, with REACH-compliant additive disclosure now mandatory for European electronics corridors.
- Gusseted Bags:Side-folded architectures expand cubic capacity for irregular component geometries in automotive electronics distribution.
- Zip Lock Bags:Reclosable static-dissipative formats serve field service kitting and prototype handling where repeated access is required.
Flat bags anchor the volume base while custom bags gain share at the steepest rate.
Dimension:
Film gauge and bag sizing correlate directly with resin throughput economics, where larger formats amortize additive costs across greater surface area but face steeper freight penalties.
- Small:Sub-150mm widths target discrete component packaging for surface-mount device reels and memory chip trays.
- Medium:150-400mm formats balance handling efficiency with material yield, dominating pharmaceutical vial and syringe containment where USP Class VI compliance is non-negotiable.
- Large:Expanded formats for printed circuit board panel shipping face competition from corrugated static-shielding boxes in automotive supply chains.
- Extra Large:Pallet-scale containment for bulk component distribution encounters substitution pressure from reusable conductive totes in closed-loop electronics manufacturing.
Medium dimensions dominate pharmaceutical procurement volumes while small formats expand most quickly in semiconductor component handling.
End User:
Regulatory stringency and qualification overhead create divergent margin structures across customer verticals, with pharmaceutical applications commanding premium positioning despite lower unit volumes.
- Electronics:Semiconductor fabrication facilities in Taiwan and South Korea specify static-dissipative containment with ISO 14644-1 cleanroom certification, driving the most intensive supplier qualification protocols. Wafer-level packaging operations require carbon black permanent anti-static systems for humidity-independent performance, with direct procurement relationships displacing distributor intermediaries in high-specification segments.
- Pharmaceuticals:Biologics cold-chain proliferation is accelerating static-controlled polyethylene adoption for temperature-sensitive active pharmaceutical ingredients. FDA 21 CFR 177.1520 compliance and USP Class VI certification create entry barriers that favor established cleanroom converters, with EU REACH SCIP database registration now required for European market access.
- Automotive:Electric vehicle electronics modules and battery management systems are expanding specification-grade demand, though cost pressure from tier-one suppliers limits margin capture.
- Retail:Consumer electronics accessories and point-of-sale display packaging represent commoditized volume with minimal anti-static performance differentiation.
Electronics anchors the volume base while pharmaceuticals climbs the fastest on biologics packaging expansion.
Packaging Type:
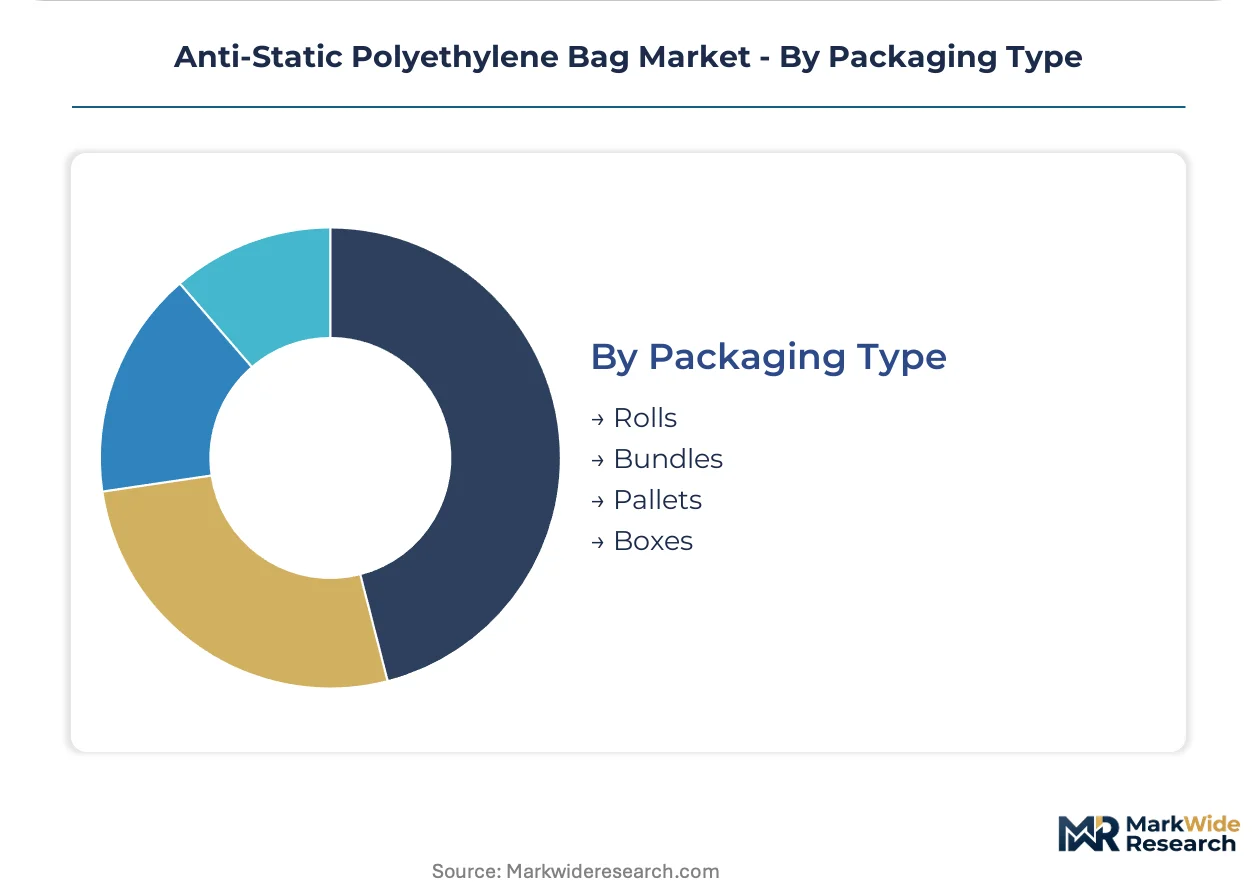
Downstream handling efficiency and automated unpacking compatibility shape format selection, with roll-fed systems gaining traction in high-volume electronics assembly operations.
- Rolls:Continuous film formats enable automated bagging lines in electronics contract manufacturing, where throughput speed outweighs individual bag handling convenience.
- Bundles:Pre-counted stacks facilitate kanban replenishment in semiconductor fabrication facility consumables management.
- Pallets:Unitized shipment formats for cleanroom-certified converters serving East Asian electronics clusters minimize freight damage and customs inspection disruption.
- Boxes:Corrugated outer containment with static-dissipative inner liners serves pharmaceutical distribution where temperature monitoring devices require rigid protection.
Rolls dominate electronics manufacturing procurement while boxes expand most quickly in pharmaceutical cold-chain distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in anti-static polyethylene bags tilt heavily toward East Asian manufacturing clusters, with Taiwan and South Korea running structural surpluses in cleanroom-certified formats while the United States and Germany absorb premium volumes for semiconductor and pharmaceutical applications.
United States
FDA 21 CFR 177.1520 compliance requirements govern pharmaceutical contact applications, while EPA oversight of per- and polyfluoroalkyl substances pressures reformulation away from fluorinated anti-static coatings. California's extended producer responsibility legislation is reshaping post-consumer recycling obligations for single-use polyethylene packaging.
Taiwan
Wafer-level packaging operations at Hsinchu Science Park and Tainan Technology Industrial Park drive procurement concentration for static-dissipative containment with lot-traceability printing. The island's semiconductor fabs are consolidating vendor bases to reduce qualification overhead.
South Korea
Samsung Electronics and SK Hynix fabrication facilities in Giheung and Icheon specify carbon black permanent anti-static systems for humidity-independent performance. MFDS alignment with USP Class VI standards creates dual-use pathways for pharmaceutical packaging exports.
Germany
EU REACH SCIP database registration mandates for substances of very high concern are forcing additive transparency across electronics supply chains. Bavarian automotive electronics clusters are expanding specification-grade demand for electric vehicle battery management systems.
India
CDSCO regulatory alignment with USP Class VI standards creates entry pathways for cleanroom-certified converters serving domestic biologics manufacturers. Telangana's Genome Valley and Maharashtra's Pune pharmaceutical corridors are accelerating static-controlled polyethylene adoption for temperature-sensitive active pharmaceutical ingredients.
Anti-Static Polyethylene Bag Market Competitive Environment
Concentration sits with materials science conglomerates and vertically integrated film converters. The competitive terrain splits between premium additive formulators, regional blown-film specialists, and cleanroom-certified conversion operators. Three archetypes dominate: multinational materials companies leveraging polymer science heritage, mid-cap converters with captive extrusion assets, and niche cleanroom specialists serving semiconductor corridors. Capacity expansion and direct procurement relationships with fabrication facilities constitute the dominant competitive moves.
Within the multinational tier, 3M Company exemplifies premium positioning through materials science capabilities. Protective Packaging Corporation anchors North American supply through vertically integrated blown-film and bag-conversion assets. Daklapack Group occupies a position across European pharmaceutical corridors with cleanroom-certified conversion capabilities.
| Leading Market Players |
|---|
| Protective Packaging Corporation |
| 3M Company |
| Daklapack Group |
| Teknis Limited |
| Dou Yee Enterprises Singapore |
| Automated Packaging Systems |
| Pregis LLC |
| IMPAK Corporation |
| Polyplus Packaging |
| Others |
Value Chain & Pricing Dynamics
ISO 14644-1 cleanroom certification gates both supplier qualification and price differentiation, separating carbon black permanent anti-static formulations from commodity glycerol monostearate systems while semiconductor fabs in Taiwan and South Korea consolidate vendor bases to reduce procurement overhead.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Carbon black permanent anti-static systems command certification-grade premiums from semiconductor wafer shippers, while migratory agent formulations face cost compression from ethylene feedstock volatility and REACH compliance overhead. Pharmaceutical cold-chain applications exhibit lowest price sensitivity due to USP Class VI compliance requirements, whereas retail electronics accessories absorb maximum pressure.
Supply Chain Analysis
Strait of Malacca transit underwrites resin feedstock flows to Taiwan, South Korea, and coastal China where blown-film extrusion capacity clusters. Low-density polyethylene resin draws from naphtha crackers and ethane feedstock, with carbon black conductive fillers sourced from specialty chemical suppliers. Single-source vulnerability concentrates in East Asian cleanroom-certified conversion assets. Distribution runs through direct procurement relationships displacing distributor intermediaries in high-specification segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible laminated pouches and rigid clamshell packaging threaten substitution in commodity electronics bundling, forcing incumbent polyethylene bag converters to defend specification-intensive semiconductor and pharmaceutical applications where static-dissipative performance remains non-negotiable.
For Market Incumbents: Consolidate vendor qualification relationships with Taiwan and South Korean fabrication facilities through multi-year supply agreements embedding lot-traceability printing capabilities. Deepen backward integration into carbon black additive compounding to secure humidity-independent performance margins against glycerol monostearate commodity erosion. Prioritize cleanroom certification maintenance at ISO 14644-1 Class 7 and Class 8 facilities to sustain barrier to mid-tier entrants.
For New Entrants and Emerging Players: CDSCO USP Class VI certification fast-track creates entry pathways into Indian pharmaceutical corridors serving Telangana's Genome Valley and Maharashtra's Pune biologics clusters. Target temperature-sensitive active pharmaceutical ingredient containment where static-controlled polyethylene adoption accelerates fastest. Pursue white-label conversion partnerships with established cleanroom-certified operators to bypass 12-18 month qualification timelines.
For Investors and Strategic Acquirers: EU REACH SCIP database registration reshapes the acquisition landscape by mandating additive transparency and qualifying compliant suppliers for European electronics corridors. Position for 5-10 year viability around converters with permanent anti-static formulation capabilities and East Asian fabrication facility relationships. Monitor California and New York extended producer responsibility implementation as signal for post-consumer recycling infrastructure investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Investment | ISO 14644-1 Class 7 qualification enables Taiwan semiconductor fab supply agreements. |
| Carbon Black Formulation Shift | Permanent anti-static systems capture humidity-independent performance premiums from wafer shippers. |
| Backward Integration into Additive Compounding | In-house glycerol monostearate and conductive filler control secures margin against resin volatility. |
| Direct Procurement Relationship Development | Bypassing distributor intermediaries locks multi-year supply agreements with Samsung and SK Hynix. |
| REACH Compliance Infrastructure | SCIP database registration capability qualifies suppliers for European pharmaceutical corridor access. |
Study Parameters
A standing panel of cleanroom facility managers, semiconductor procurement directors, pharmaceutical packaging engineers, and blown-film extrusion operators provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 21 CFR 177.1520 filings, ECHA REACH substance registrations, SEC 10-K disclosures of materials science conglomerates, and customs trade data for polyethylene resin flows. Bottom-up segment sizing triangulated against top-down market reconstruction across product type, dimension, end user, and packaging type dimensions.
Consistency checks validated volume and value outputs against external benchmarks throughout the projection horizon. The analytical framework modeled pricing stratification across premium, standard, and economy tiers; geographic production concentration in East Asian electronics clusters; and regulatory compliance segmentation between REACH-governed European corridors and FDA-regulated North American pharmaceutical markets. CAGRs derived from segment-level growth rate synthesis with ethylene feedstock cost trajectories and wafer-level packaging capacity expansion schedules as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable crude oil price assumptions and continued East Asian semiconductor fabrication facility expansion; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as EU REACH SVHC list evolution and EPA per- and polyfluoroalkyl substance enforcement posture develop.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bags and Containers Market
Bags and Containers
Bag Dump Stations Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Slider Bags Market
Bags and Containers
Bag-In-Bottle Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Bulk Bag Conditioners Market