
 Woven Sacks Market | 2026-2036
Woven Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Woven Sacks Market Outlook
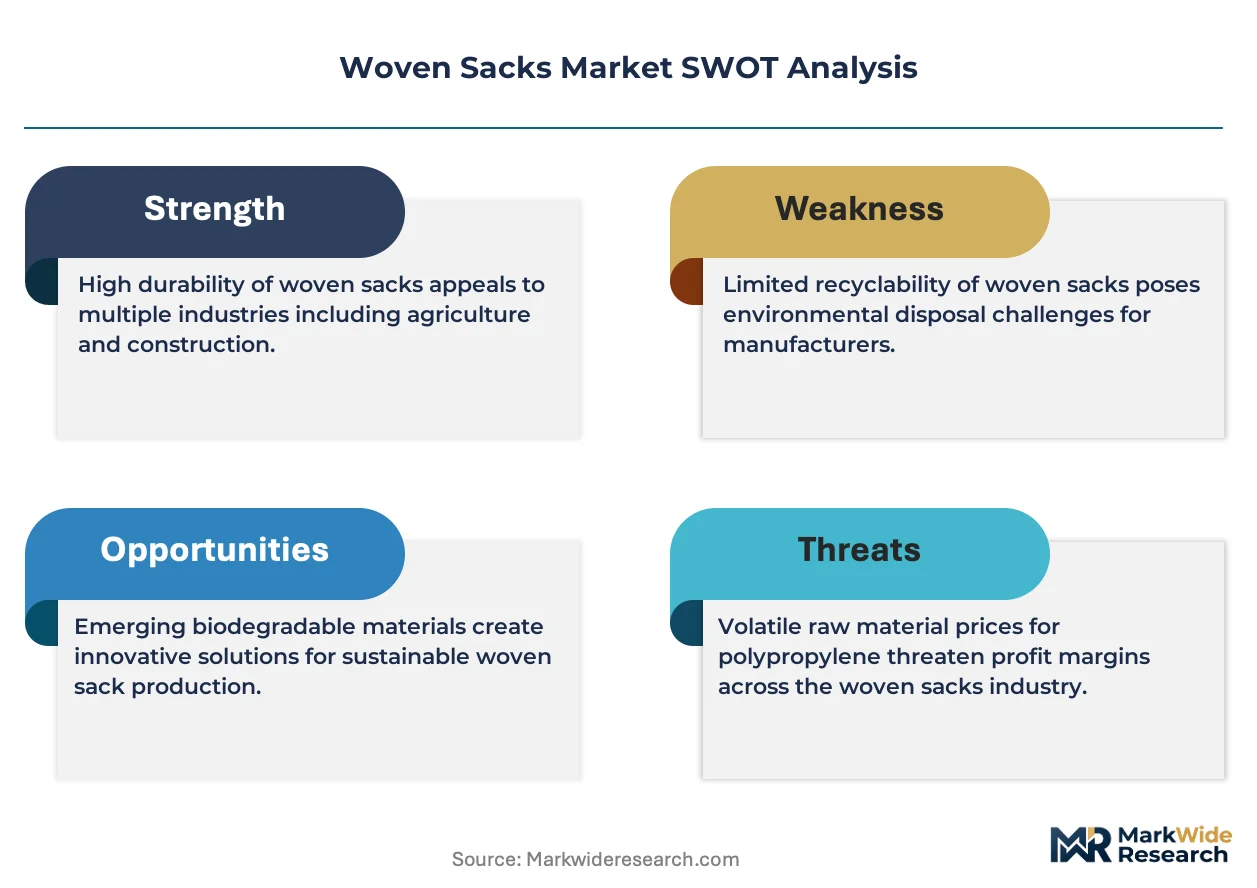
Modular lamination with PE liners and valve closures is restructuring buyer choice across bulk packaging procurement. Mondi Group leverages integrated film extrusion capabilities to supply coated woven structures for chemical containment. Berry Global Inc. anchors North American production through multi-site manufacturing of UV-stabilized agricultural sacks. LC Packaging International BV competes via certified food-grade operations serving European grain traders.
Woven sacks are multi-wall fabric containers engineered from extruded polypropylene tapes woven into tubular or flat configurations, typically rated for 25–80 kg loads with tear strengths exceeding 15 N. These units protect dry bulk commodities against moisture ingress and mechanical stress during palletized transport and extended outdoor storage. Polypropylene sacks dominate volume owing to chemical resistance and cost efficiency in fertilizer handling, while jute sacks retain structural relevance in food packaging segments where biodegradability commands procurement preference. Medium and large sizes capture the majority of agricultural demand as mechanized filling equipment standardizes on 50 kg and 100 kg capacities across grain handling operations.
ISO 21898 governs flexible intermediate bulk container construction and testing protocols that many woven sack manufacturers adopt for quality benchmarking. India's BIS mandates tensile strength and dimensional stability certification for domestic distribution, while REACH compliance in Europe restricts certain additive chemistries in food-contact woven materials. Stakeholders must monitor evolving extended producer responsibility frameworks that increasingly assign collection and recycling obligations to packaging suppliers.
Market Dynamics
Mechanized filling operations across grain handling facilities are forcing standardization of sack dimensions and valve configurations, compressing supplier margins while rewarding manufacturers with certified load-bearing capacity.
Growth Catalysts
- REACH compliance in Europe:Restrictions on additive chemistries in food-contact materials are accelerating demand for certified polypropylene grades that meet migration limits.
- Punjab and Haryana mechanization:India's northern agricultural belt is concentrating procurement of 50 kg and 100 kg standardized sacks compatible with automated filling lines.
- Laminated PE liners:Moisture protection requirements in fertilizer handling are pulling buyers toward coated woven structures with heat-sealed inner barriers.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings tied to naphtha cracking economics compress margin visibility for converters without backward integration into polymer supply.
- Supplier concentration in Gujarat:India's woven tape extrusion capacity clusters in a single coastal state, exposing buyers to monsoon logistics disruptions and port congestion.
- Jute substitution ceiling:Biodegradable fiber sacks face tensile strength limitations below 25 kg loads, blocking penetration in bulk grain logistics.
Strategic Opportunities
- India's PLI scheme for technical textiles:Production-linked incentives for geotextiles and agro-textiles extend to high-performance woven packaging with BIS certification.
- Valve closure automation:Convergence of ultrasonic sealing with block-bottom forming creates white space in 25 kg chemical packaging for European specialty distributors.
- Extended producer responsibility frameworks:Collection and recycling mandates in Germany and France are creating service-revenue streams for sack suppliers with reverse logistics capability.
Industry Challenges
- BIS certification timelines:Tensile strength and dimensional stability testing protocols in India create 12-16 week approval windows that delay contract execution.
- UV stabilization formulation:Agricultural buyers in equatorial zones demand 12-month outdoor durability, requiring masterbatch expertise that concentrates among specialized compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woven Sacks Market |
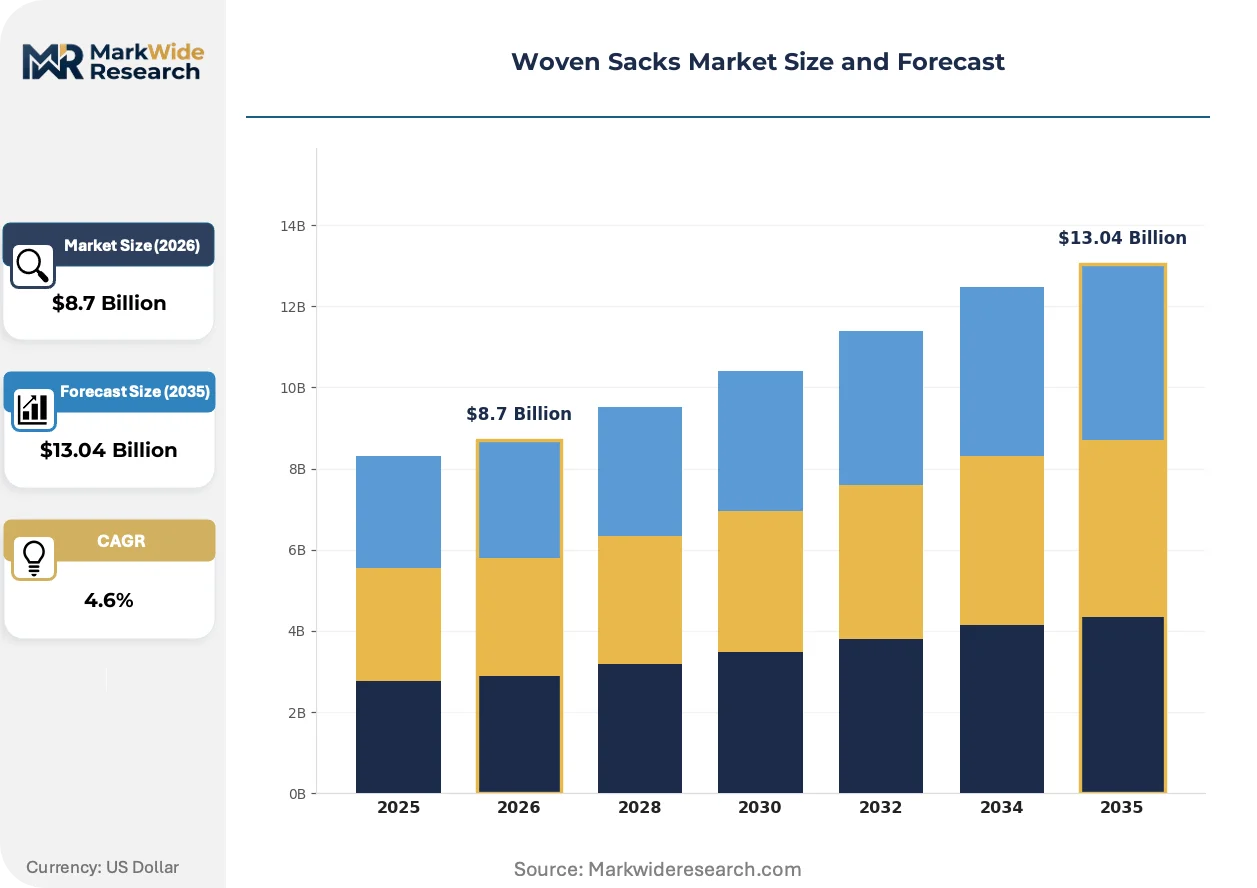
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene Sacks, Cotton Sacks, Jute Sacks, Paper Sacks End Use Industry: Agriculture, Food Packaging, Chemicals, Retail Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Mondi Group, Berry Global Inc., Uflex Limited, Muscat Polymers Pvt. Ltd., Emmbi Industries Limited, Al-Tawfiq Company, Mansarovar Agro Sacks Private Limited, LC Packaging International BV, Anduro Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woven Sacks Market Strategic Shifts
Digital printing and track-and-trace integration are reshaping how agricultural cooperatives and chemical distributors specify woven packaging, moving identification from woven-in stripes to variable-data surfaces.
Co-extruded barrier films with ethylene vinyl alcohol layers are converging with conventional woven substrates to create hybrid structures for hygroscopic fertilizer containment. Major grain traders in Argentina and Ukraine are piloting these configurations for soybean meal exports. The technology is converging with automated palletizing systems that require slip-resistant outer surfaces.
China's GB standards for food-contact safety are tightening migration limits for heavy metals and primary aromatic amines in polypropylene tapes. Domestic manufacturers in Shandong and Jiangsu provinces are retrofitting extrusion lines with purified resin handling. Food-grade certification is becoming a procurement gate for rice and flour distributors supplying state reserve systems.
Cooperative buying consortia among Midwest US agricultural elevators are consolidating sack procurement into multi-year framework agreements with volume-tier pricing. Individual elevator operators lose negotiating leverage as procurement authority migrates to regional grain handling networks. This concentration is most visible in Illinois and Iowa, where three cooperatives now control 40% of woven sack demand in their service territories.
Woven Sacks Market Segmentation
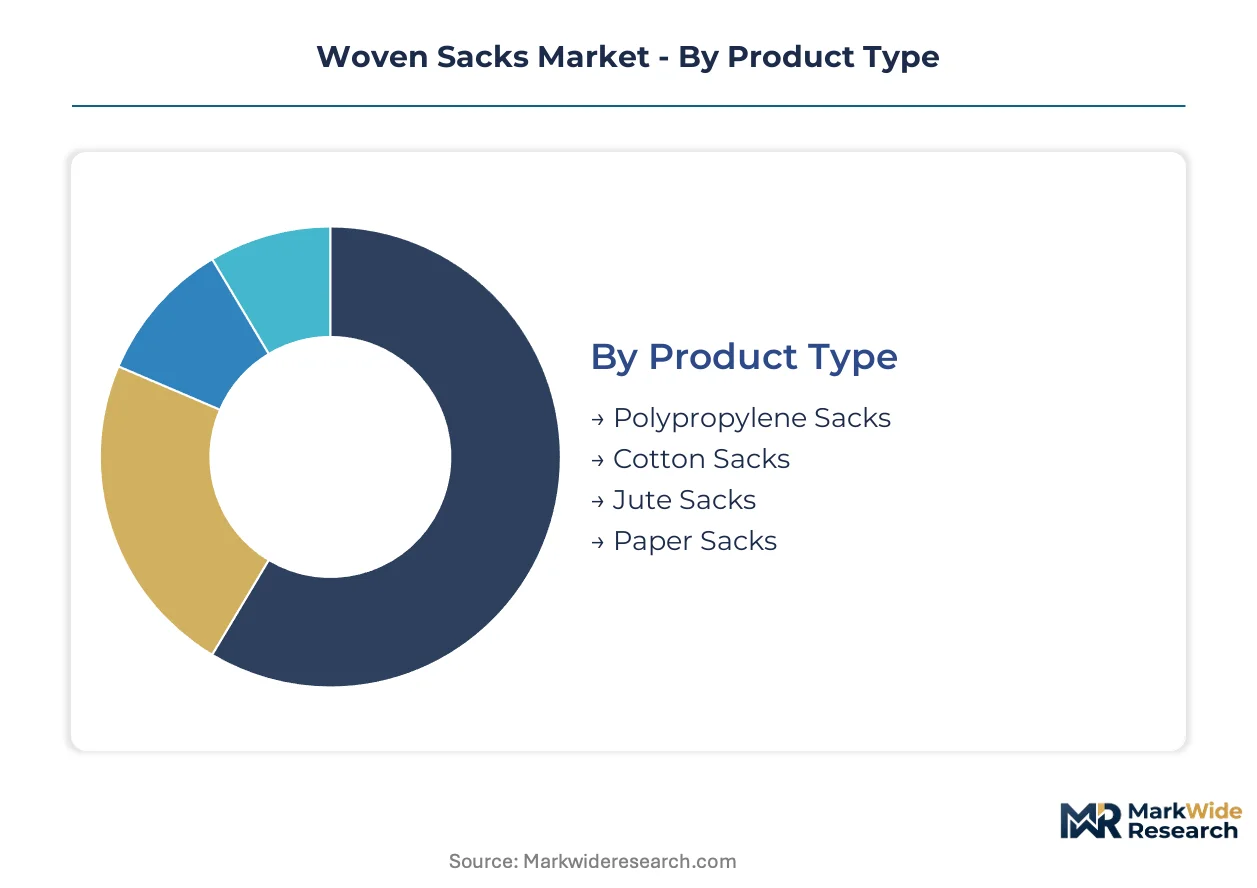
Woven sack procurement patterns diverge sharply across material chemistry, load capacity, and channel access. Buyers in grain handling and chemical containment prioritize distinct performance specifications that reshape supplier specialization and margin structure.
Product Type:
Supply of woven tape extrusion capacity clusters around polymer chemistry expertise, with polypropylene dominating converter investments in India and China.
- Polypropylene Sacks:Extruded polypropylene tapes woven into tubular configurations deliver tear strengths exceeding 15 N and chemical resistance for fertilizer handling. Demand concentrates in India's Punjab and Haryana agricultural belt where mechanized filling operations require standardized 50 kg and 100 kg capacities with BIS-certified load-bearing performance.
- Jute Sacks:Biodegradable fiber structures retain procurement preference in food packaging segments where environmental compliance commands buyer attention. Tensile strength limitations below 25 kg loads block penetration in bulk grain logistics, constraining volume to specialty rice and flour applications.
- Cotton Sacks:Natural fiber construction serves premium food-grade applications requiring breathability and moisture absorption control.
- Paper Sacks:Multi-wall kraft constructions compete in retail and specialty chemical segments demanding printability and stack stability.
Today's leader: Polypropylene Sacks. Tomorrow's challenger: Jute Sacks.
End Use Industry:
Application-driven specification requirements create divergent margin profiles, with agricultural buyers demanding certified durability while chemical handlers prioritize barrier performance.
- Agriculture:Grain and fertilizer handling drives standardized procurement of laminated configurations with PE liners and valve closures. India's northern belt mechanization pulls volume toward 50 kg and 100 kg sack formats compatible with automated filling lines.
- Chemicals:Hygroscopic fertilizer containment requires co-extruded barrier films with ethylene vinyl alcohol layers converging with woven substrates. REACH compliance in Europe restricts additive chemistries, accelerating demand for certified polypropylene grades meeting migration limits.
- Food Packaging:China's GB standards for food-contact safety tighten heavy metal and primary aromatic amine limits in polypropylene tapes. Rice and flour distributors supplying state reserve systems now require food-grade certification as a procurement gate.
- Retail:Consumer-facing applications prioritize print quality and shelf presentation over load-bearing specifications.
Agriculture commands current volume leadership. Chemicals present the steepest expansion trajectory as barrier technology matures.
Size:
Mechanized filling standardization across grain elevators compresses supplier flexibility while concentrating procurement authority.
- Medium:50 kg rated capacities align with automated filling equipment deployed across Midwest US cooperative elevators and India's mechanized agricultural belt. Illinois and Iowa grain handling networks consolidate procurement into multi-year framework agreements with volume-tier pricing.
- Large:100 kg formats serve bulk grain logistics and chemical distribution requiring palletized transport efficiency. Block-bottom forming with ultrasonic sealing creates white space in specialty chemical packaging for European distributors.
- Small:25 kg and below configurations address retail and specialty agricultural applications with manual handling requirements.
- Extra Large:Bulk configurations exceed standard mechanized filling parameters, serving niche industrial applications.
Medium sizes anchor procurement volume today. Large formats gain share fastest as elevator consolidation accelerates.
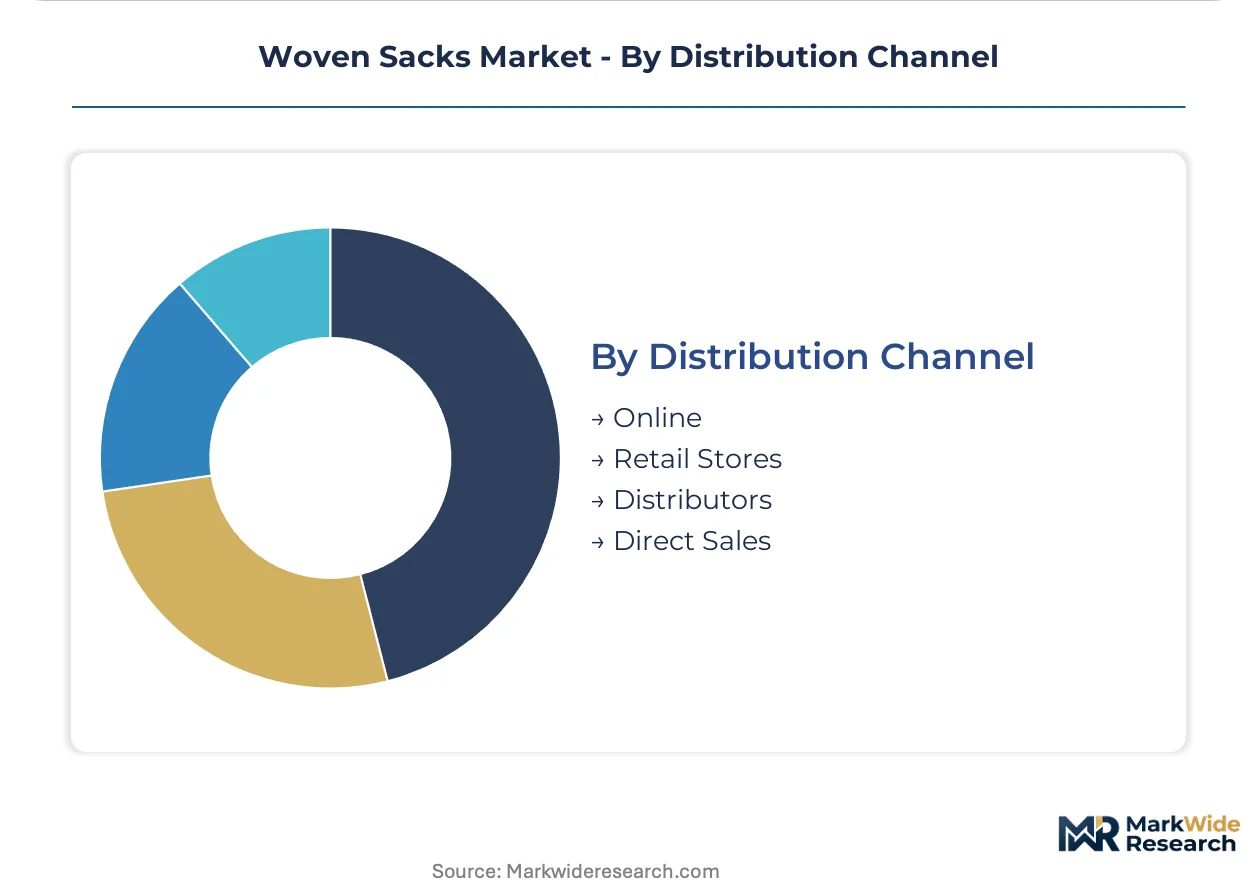
Distribution Channel:
Channel selection reflects buyer scale and certification complexity, with large agricultural networks bypassing intermediaries while smaller operators rely on distributor technical support.
- Distributors:Technical intermediaries dominate procurement for chemical and food packaging buyers requiring BIS certification navigation and formulation guidance. India's 12-16 week approval windows for tensile strength testing create demand for distributor-managed compliance support.
- Direct Sales:Cooperative buying consortia among Midwest US agricultural elevators consolidate procurement into framework agreements with manufacturers. Three Illinois and Iowa cooperatives now control substantial regional demand, extracting volume-tier pricing through concentrated negotiation.
- Online:Digital platforms serve smaller agricultural operators and retail buyers with standardized specifications and shorter lead times.
- Retail Stores:Local agricultural supply points address immediate replacement needs for small-scale farming operations.
Distributors currently mediate the majority of certified product flows. Direct sales channels expand most quickly as buyer consolidation progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Woven sack manufacturing originated in European jute mills during the nineteenth century before polypropylene extrusion technology shifted production gravity toward Asian petrochemical corridors. Today's capacity clusters reflect polymer feedstock access, agricultural mechanization patterns, and certification infrastructure density.
India
Punjab and Haryana's grain elevators drive mechanized demand for 50 kg and 100 kg BIS-certified sacks with valve closures. The national standards body mandates tensile strength and dimensional stability testing that creates 12-16 week approval windows. Gujarat's coastal tape extrusion belt concentrates converter capacity, exposing supply chains to monsoon logistics disruptions.
China
Shandong and Jiangsu provinces retrofit extrusion lines to meet GB standards tightening migration limits for heavy metals and aromatic amines in food-contact tapes. State reserve system procurement for rice and flour distributors now requires food-grade certification as a mandatory gate. Yangtze River Delta manufacturers supply hybrid barrier structures for soybean meal exports.
United States
Midwest cooperative elevators in Illinois and Iowa consolidate procurement into multi-year framework agreements with volume-tier pricing, with three networks controlling substantial regional demand. The USDA oversees agricultural packaging specifications while FDA regulates food-contact materials. Domestic converters maintain UV-stabilized capacity for equatorial grain export logistics.
Germany
REACH compliance restricts additive chemistries in food-contact woven materials, accelerating demand for certified polypropylene grades meeting migration limits. Extended producer responsibility frameworks assign collection and recycling obligations to packaging suppliers, creating service-revenue streams for operators with reverse logistics capability. Bavarian chemical distributors pilot ultrasonic-sealed block-bottom configurations.
Brazil
São Paulo-based grain traders drive laminated PE liner specifications for fertilizer handling in the Cerrado agricultural frontier. ANVISA regulates food-contact packaging materials while the central bank's monetary policy influences agricultural credit cycles affecting sack procurement timing. Domestic converters face import competition from Asian suppliers on standard commodity grades.
Woven Sacks Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity and barrier technology depth. The supplier base fragments between integrated film extruders, specialized tape converters, and regional fabricators lacking backward polymer integration. Three archetypes dominate: multinational packaging conglomerates with integrated coating capabilities, mid-scale regional specialists with BIS or GB certification expertise, and commodity converters competing on resin pass-through pricing. Capacity expansion and certification portfolio diversification represent the dominant competitive moves as buyers consolidate procurement authority.
Within the multinational tier, Mondi Group and Berry Global Inc. exemplify integrated film-to-fabric capabilities that support coated woven structures for chemical containment. LC Packaging International BV anchors the European food-grade certification specialist position serving grain traders with REACH-compliant operations. Uflex Limited represents the Indian subcontinent's vertically integrated converter archetype with domestic tape extrusion and BIS certification infrastructure.
| Leading Market Players |
|---|
| Mondi Group |
| Berry Global Inc. |
| Uflex Limited |
| Muscat Polymers Pvt. Ltd. |
| Emmbi Industries Limited |
| Al-Tawfiq Company |
| Mansarovar Agro Sacks Private Limited |
| LC Packaging International BV |
| Anduro Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Mechanized filling standardization across Punjab and Haryana grain elevators is compressing supplier flexibility and forcing converters to absorb certification costs or lose contract eligibility, which stratifies pricing power around BIS-approved manufacturers while squeezing commodity-grade competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified barrier laminates from BIS-standard agricultural grades and uncertified commodity sacks. Price differentiation hinges on certification tier and volume scale, with cooperative buyers in Illinois and Iowa extracting steepest discounts through consolidated procurement. Cost compression in standard-grade polypropylene runs through resin pass-through volatility and margin pressure from Asian imports. Small-scale agricultural operators in retail channels show highest price sensitivity, while chemical distributors prioritize barrier performance over unit cost.
Supply Chain Analysis
Freight cost exposure concentrates around Gujarat's coastal tape extrusion belt, where monsoon port congestion and inland logistics disruptions ripple through northern Indian agricultural supply chains. Manufacturing capacity clusters in India, China, and Germany, with raw material supply anchored in naphtha-cracking corridors of the Middle East and Southeast Asia. Polypropylene resin, masterbatch additives, and PE liner films constitute the critical input trinity. Single-state concentration in Gujarat creates structural vulnerability to weather-related logistics chokepoints. Distribution runs through certified distributor networks for regulated segments and direct manufacturer relationships for consolidated cooperative buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities in woven sacks rest on two vectors: cost-down through backward integration into tape extrusion, and premium-tier capture via food-grade and barrier-laminate certification portfolios that command pricing power from regulated buyers.
For Market Incumbents: Lock in cooperative procurement relationships across Midwest US elevator networks before regional consolidation completes, while investing in BIS and GB certification infrastructure to defend against Asian competitors with lower resin costs. Threat of commoditization from uncertified Indian and Chinese imports demands captive supply of purified resins for food-contact grades. Priority lever: ultrasonic sealing and block-bottom automation for European chemical distributors. For New Entrants and Emerging Players: The price-point gap between REACH-certified premium laminates and economy-grade agricultural sacks creates white-space for mid-tier players offering BIS-certified standard grades with shorter lead times. Most penetrable target: India's northern belt small-to-medium grain traders bypassed by large cooperative networks. Go-to-market angle: distributor-managed compliance support to navigate 12-16 week certification windows. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated converters possessing in-house tape extrusion and multi-jurisdiction certification portfolios. Long-term viability favors operators with reverse logistics capability for extended producer responsibility frameworks in Germany and France. Acquisition target archetype: mid-scale regional specialists with BIS or GB expertise and underutilized lamination capacity. Signal to watch: consolidation of Illinois and Iowa cooperative procurement into single-source framework agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tape Extrusion | Captive polypropylene supply insulates margins from naphtha volatility and Gujarat logistics disruptions. |
| Multi-Jurisdiction Certification Investment | Simultaneous BIS, GB, and REACH approval unlocks agricultural, food-grade, and chemical containment demand pools. |
| Ultrasonic Sealing Automation | Block-bottom valve closure technology penetrates European specialty chemical packaging specifications. |
| Reverse Logistics Capability Buildout | Collection and recycling infrastructure captures service-revenue streams from German and French EPR mandates. |
| Cooperative Procurement Consolidation | Multi-year framework agreements with volume-tier pricing lock in demand from Illinois and Iowa elevator networks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant managers at Indian and Chinese tape extrusion facilities, procurement leads at Midwest US agricultural cooperatives, distribution channel partners navigating BIS certification timelines, and technical R&D directors at barrier film compounders. Secondary validation drew from customs and trade data, BIS and GB standards documentation, SEC filings of listed packaging converters, and agricultural machinery deployment statistics. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Segment-weighting approaches distributed value and volume across material chemistry, load capacity tier, end-use application, and geographic production cluster dimensions throughout the forecast period. CAGRs derived from regression analysis of historical shipment data and forward projection of mechanization penetration rates in target agricultural belts. Industry-specific forecast inputs included polypropylene resin price indices and BIS certification approval timeline distributions.
Caveats apply where feedstock price volatility, regulatory timeline extensions, or logistics disruptions could materially shift the outlook. Forecasts reflect assumptions about cooperative procurement consolidation pace and barrier technology adoption curves in chemical distribution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Baffle Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Wooden Boxes Market