
 Packaging Nets Market | 2026-2036
Packaging Nets Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Nets Market Outlook
Fresh produce distributors is collapsing toward standardized mesh formats for stone fruit and citrus protection. Intermas Nets leverages its Mediterranean manufacturing footprint to serve European agricultural cooperatives with high-volume polyethylene net output. Lenzing anchors the premium tier through cellulosic net variants that target compostability-minded food retailers. GSH Group competes on custom extrusion capabilities, supplying tailored sleeve configurations to pharmaceutical serialization lines.
Packaging nets are open-mesh synthetic or natural fiber structures, typically extruded in polyethylene or knitted in nylon with aperture sizes ranging from 2 mm to 50 mm, designed to unitize, ventilate, and protect products during handling and transit. Their primary purpose spans agricultural field packing, retail produce display, and industrial component separation where airflow and visibility reduce spoilage or damage. Polyethylene nets dominate volume due to low resin cost and extrusion efficiency, though agro-fabric segments are gaining traction where biodegradability commands shelf-space premiums. Food and beverage end use leads absolute consumption, while e-commerce represents the fastest-growing application as mesh bags replace corrugated inserts for irregular-shaped goods. Rolls remain the standard form for automated packing lines, but custom shapes capture margin pools in pharmaceutical vial netting and precision electronics.
FDA food-contact material regulations govern polyethylene and nylon net compositions entering US fresh produce channels, while REACH restricts certain phthalate plasticizers in European extrusion grades, compelling reformulation toward compliant catalyst systems. The EU Green Deal's packaging waste directive is accelerating mono-material net designs that simplify mechanical recycling streams. Stakeholders must monitor evolving extended producer responsibility schemes across Germany, France, and Italy, as these frameworks will determine whether compostable agro-fabric nets achieve cost parity with conventional polymers.
Market Dynamics
The EU Green Deal's plastics circularity mandates are forcing converters to abandon multi-layer net constructions in favor of recyclable mono-material designs, compressing formulation flexibility while opening premium positioning for compliant suppliers.
Growth Catalysts
- REACH-compliant catalyst systems:European extruders are reformulating polyethylene grades to eliminate restricted phthalate plasticizers, unlocking continued access to fresh produce distribution channels across Germany, France, and Italy.
- E-commerce fulfillment acceleration:Mesh bag configurations are replacing corrugated inserts for irregular-shaped goods in automated packing lines, driven by dimensional weight reduction and damage rate improvement.
- Agro-fabric biodegradability premiums:Cellulosic net variants command shelf-space advantages with compostability-minded food retailers in Northern European markets where extended producer responsibility schemes reward circular packaging.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin costs fluctuate with naphtha cracking margins and regional energy pricing, squeezing converter margins on standard agricultural netting contracts.
- Mechanical recycling contamination thresholds:Post-consumer net collection streams face sorting complexity due to mixed polymer contamination, limiting closed-loop feedstock availability for circular production claims.
- Rigid container substitution:Reusable plastic crates and corrugated fiberboard trays compete for stone fruit and citrus protection in centralized packing operations where return logistics are viable.
Strategic Opportunities
- Pharmaceutical serialization integration:Custom extrusion capabilities for tailored sleeve configurations serve vial netting and precision electronics where traceability requirements create specification stickiness.
- Compostable agro-fabric cost parity:Extended producer responsibility frameworks in Germany, France, and Italy may rebalance economics between conventional polymers and certified biodegradable alternatives.
- Automated packing line retrofit:Roll-fed net systems compatible with existing flow-wrap and form-fill-seal equipment create upgrade pathways for fresh produce processors seeking throughput gains.
Industry Challenges
- Mono-material performance engineering:Maintaining tensile strength and abrasion resistance in single-polymer net structures requires reformulation expertise that concentrates among specialized compounders.
- Food-contact certification timelines:FDA migration testing and EU plastic food contact compliance documentation extend new product introduction cycles for converters serving multinational produce distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Nets Market |
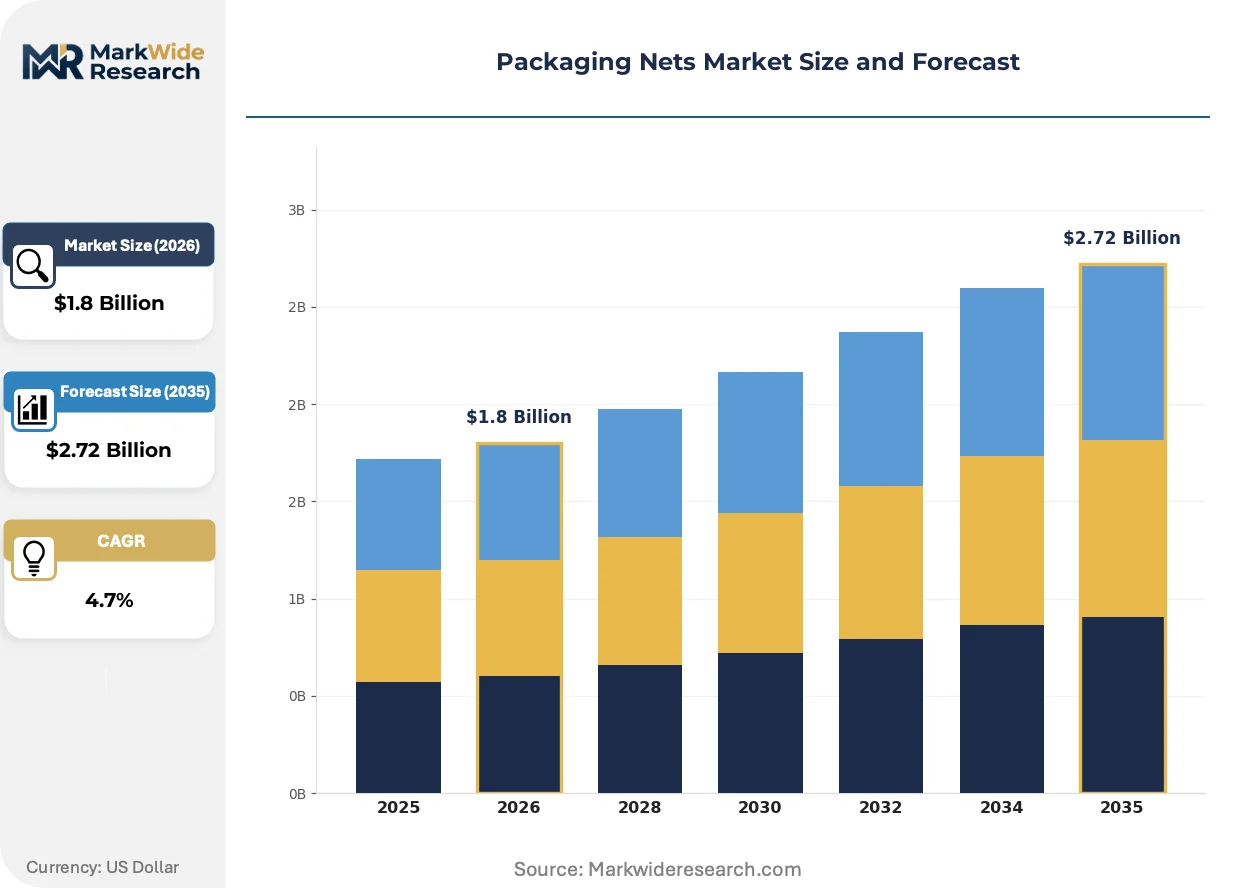
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Nylon, Polyester, Agro-Fabric End Use Industry: Agriculture, Food & Beverage, Pharmaceuticals, E-commerce Product Form: Rolls, Bags, Sleeves, Custom Shapes Distribution Channel: Online, Supermarkets, Wholesalers, Direct Sales |
| Companies Covered | Intermas Nets, Lenzing, GSH Group, SKAPS Industries, EXPO-NET, Chemco Group, Grup Giró, Packnatur GmbH, LC Packaging International BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Nets Market Strategic Shifts
Material science advances and regulatory pressure on circularity are converging to reshape net construction methods, with extrusion and fiber technologies diverging toward distinct performance and sustainability positioning.
High-density polyethylene mono-filament extrusion with optimized draw ratios is supplanting multi-layer co-extruded structures in European fresh produce applications. German agricultural cooperatives and Dutch greenhouse operators are specifying these simplified constructions to satisfy EU Green Deal mechanical recycling requirements. The shift compresses formulation flexibility for converters but enables closed-loop feedstock claims that secure contract renewals with sustainability-mandated retail chains.
REACH restrictions on phthalate plasticizers in European extrusion grades are compelling catalyst system transitions toward Ziegler-Natta and metallocene alternatives. This regulatory friction extends qualification timelines for new net formulations entering food-contact applications. French and Italian fresh produce distributors are prioritizing suppliers with pre-validated compliant material libraries to de-risk supply continuity.
Consolidated produce retail procurement is compressing supplier rosters toward standardized mesh formats for stone fruit and citrus protection. Mediterranean agricultural cooperatives are consolidating volume commitments with fewer converters capable of consistent aperture tolerance and color matching across seasonal campaigns. This concentration is most visible in Spanish and Italian citrus export corridors where logistics standardization reduces downstream handling complexity.
Packaging Nets Market Segmentation
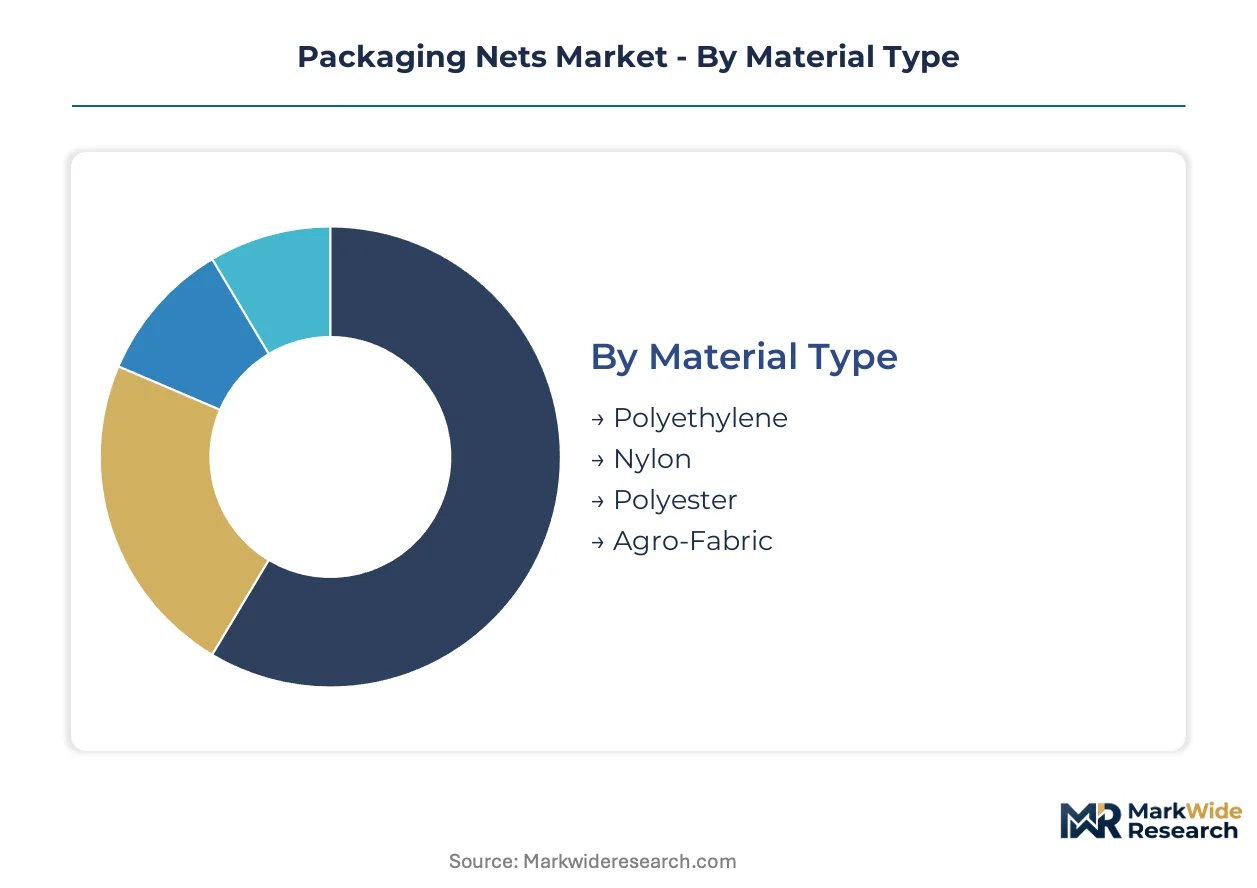
Packaging nets serve divergent performance requirements across material grades and end-use environments. Segmentation reveals where substitution pressure from rigid containers and alternative flexible formats concentrates competitive risk.
Material Type:
Polyethylene faces the most acute substitution threat from compostable agro-fabrics where extended producer responsibility schemes reweight procurement criteria.
- Polyethylene:Extruded high-density mono-filament structures dominate fresh produce field packing with aperture tolerances of 2-50 mm. German agricultural cooperatives and Dutch greenhouse operators specify these constructions to satisfy EU Green Deal mechanical recycling requirements.
- Nylon:Knitted multifilament configurations deliver superior tensile strength for industrial component separation and precision electronics protection. Pharmaceutical serialization lines in France and Italy specify nylon sleeve configurations where abrasion resistance determines specification stickiness.
- Polyester:Thermoplastic variants serve high-temperature sterilization environments in medical device packaging. The material commands niche positioning where thermal stability outweighs cost considerations.
- Agro-Fabric:Cellulosic net structures target compostability-minded food retailers in Northern European markets. Certification under extended producer responsibility frameworks determines shelf-space access.
Polyethylene retains volume leadership; agro-fabric holds the steepest expansion curve.
End Use Industry:
Application concentration varies sharply by margin structure and regulatory exposure across customer verticals.
- Agriculture:Field packing for stone fruit and citrus protection drives standardized mesh procurement by Mediterranean agricultural cooperatives. Spanish and Italian citrus export corridors consolidate volume commitments toward fewer suppliers capable of consistent color matching.
- Food & Beverage:Retail produce display applications demand FDA food-contact compliance documentation and REACH-compliant catalyst systems. French fresh produce distributors prioritize suppliers with pre-validated material libraries to de-risk supply continuity.
- Pharmaceuticals:Custom extrusion capabilities for vial netting and precision electronics serve traceability requirements. Custom sleeve configurations create specification stickiness in serialization lines.
- E-commerce:Mesh bag configurations replace corrugated inserts for irregular-shaped goods in automated packing lines. Dimensional weight reduction and damage rate improvement drive specification.
Food & Beverage retains volume leadership; e-commerce holds the steepest expansion curve.
Product Form:
Form factor selection tracks automation compatibility and handling efficiency across packing line configurations.
- Rolls:Standard feedstock for flow-wrap and form-fill-seal equipment in high-throughput fresh produce operations. Roll-fed systems create upgrade pathways for processors seeking throughput gains without line replacement.
- Bags:Pre-formed mesh configurations serve irregular-shaped goods in e-commerce fulfillment where dimensional weight reduction matters. Automated packing lines increasingly specify bag formats for damage rate improvement.
- Sleeves:Tubular extrusions protect pharmaceutical vials and precision electronics where traceability requirements dominate. Custom extrusion capabilities concentrate margin pools in specification-driven applications.
- Custom Shapes:Engineered net structures for specialized industrial component separation. Die-cut configurations capture premium positioning where standard aperture geometries fail.
Rolls retain volume leadership; custom shapes hold the steepest expansion curve.
Distribution Channel:
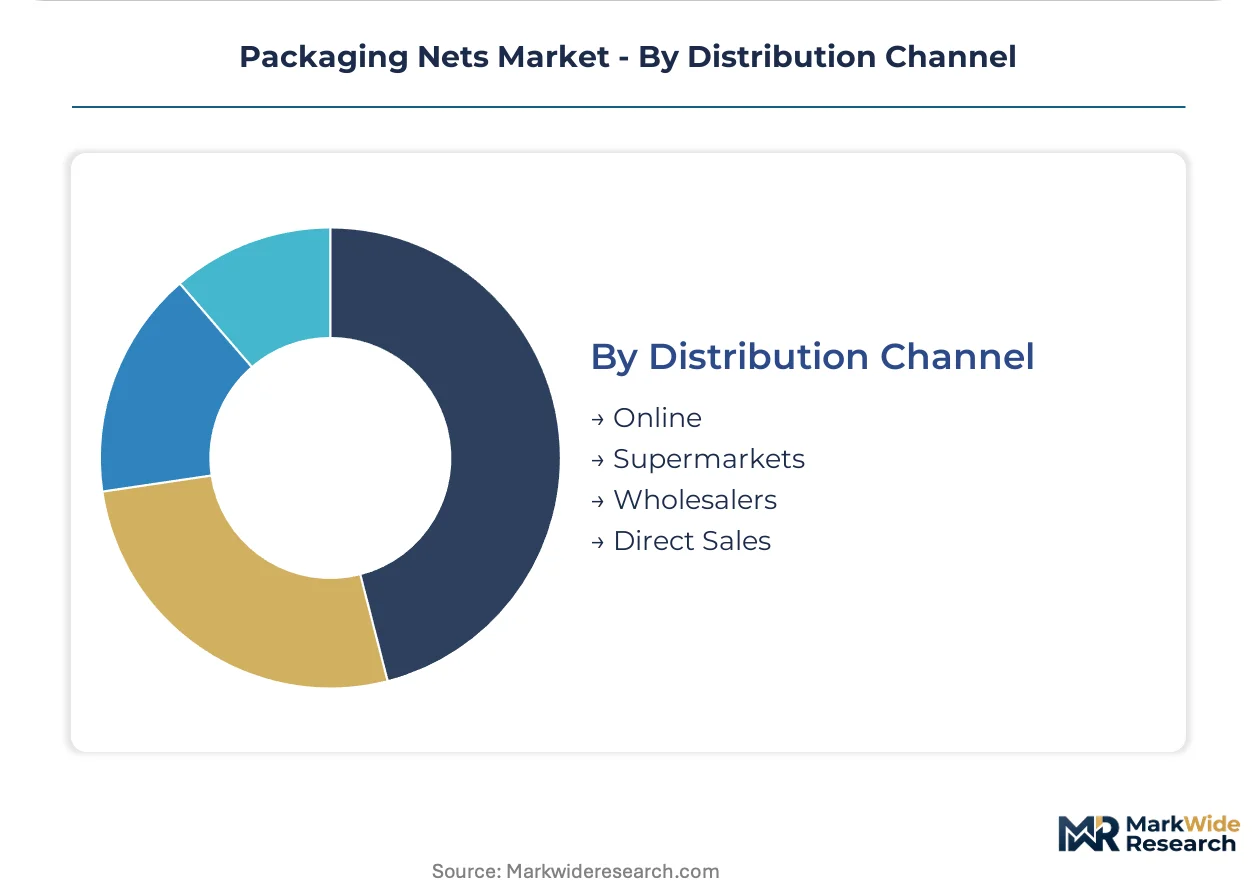
Channel selection reflects order scale, customization requirements, and technical service intensity across buyer segments.
- Online:Digital procurement platforms serve small-to-mid volume buyers with standardized mesh specifications. E-commerce channels expand access for agricultural cooperatives seeking spot purchases outside consolidated supplier rosters.
- Supermarkets:Retail chains with sustainability mandates drive specification toward mono-material and certified compostable alternatives. Private-label produce programs concentrate procurement through preferred converter relationships.
- Wholesalers:Regional distributors aggregate demand from fragmented agricultural operations. Inventory holding and technical consultation services justify margin capture in dispersed customer bases.
- Direct Sales:Converter-to-processor relationships dominate high-volume fresh produce and pharmaceutical applications. Custom extrusion capabilities and food-contact certification documentation require direct technical engagement.
Direct sales retain volume leadership; online channels hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, Spain, and Italy where fresh produce logistics networks and EU Green Deal compliance requirements concentrate specialized net demand. Mediterranean agricultural cooperatives and Northern European retail chains drive divergent specification patterns across the continent.
Germany
Fresh produce logistics networks in Bavaria and Lower Saxony drive specialized polyethylene net consumption for stone fruit protection. REACH-compliant catalyst systems from ECHA-mandated reformulation timelines dominate procurement specifications. The Rhine-Ruhr industrial corridor hosts extrusion compounders supplying mono-material net structures to Dutch greenhouse operators and domestic agricultural cooperatives.
Spain
Mediterranean citrus export corridors consolidate volume commitments toward fewer converters capable of consistent aperture tolerance. EU Green Deal packaging waste directives accelerate mechanical recycling requirements for field packing applications. Valencia and Murcia agricultural clusters specify standardized mesh formats that reduce downstream handling complexity for international shipments.
Italy
Fresh produce distributors in Emilia-Romagna and Sicily prioritize suppliers with pre-validated REACH-compliant material libraries to de-risk supply continuity. Phthalate plasticizer restrictions compel reformulation toward Ziegler-Natta catalyst alternatives. The Po Valley greenhouse belt generates concentrated demand for retail display netting serving compostability-minded Northern European buyers.
France
Pharmaceutical serialization lines in the Île-de-France biotech cluster specify custom nylon sleeve configurations where abrasion resistance determines specification stickiness. Extended producer responsibility frameworks under the EU Green Deal reweight procurement criteria toward certified biodegradable alternatives. The Lyon-Avignon agricultural corridor drives agro-fabric trials for stone fruit field packing.
Netherlands
Dutch greenhouse operators in Westland and Noord-Brabant specify high-density polyethylene mono-filament extrusion with optimized draw ratios for mechanical recycling compliance. The country's centralized produce auction system standardizes mesh procurement across cooperative networks. Rotterdam logistics hubs distribute compliant netting to German and Belgian retail chains under sustainability-mandated contracts.
Packaging Nets Market Competitive Environment
Concentration sits with specialized extrusion houses and fiber technology specialists that command specification stickiness through food-contact certification libraries and custom tooling capabilities. The vendor base stratifies across three tiers: multinational resin converters with integrated extrusion operations, regional specialists in agricultural mesh formats, and niche players in pharmaceutical-grade sleeve configurations. Two dominant competitive moves define current positioning: backward integration into resin compounding to secure REACH-compliant catalyst supply, and geographic expansion through Mediterranean manufacturing footprints to serve Spanish and Italian citrus export corridors.
Within the fiber technology specialist tier, Lenzing anchors premium positioning through cellulosic net variants, while Intermas Nets exemplifies scale-driven supply to European agricultural cooperatives. GSH Group occupies a position in custom extrusion capabilities for pharmaceutical applications. These three entities represent the archetype spectrum spanning biodegradable innovation, high-volume agricultural supply, and specification-driven industrial protection.
| Leading Market Players |
|---|
| Intermas Nets |
| Lenzing |
| GSH Group |
| SKAPS Industries |
| EXPO-NET |
| Chemco Group |
| Grup Giró |
| Packnatur GmbH |
| LC Packaging International BV |
| Others |
Value Chain & Pricing Dynamics
Agro-fabric substitution for conventional polyethylene nets in Northern European retail channels simultaneously redraws supply geography toward certified compostable feedstock producers and compresses pricing premiums for REACH-compliant mono-material structures. This input shift forces converters to rebalance resin sourcing strategies against extended producer responsibility incentives that reward circular packaging claims.
Pricing Analysis
REACH-compliant catalyst system mandates dictate the pricing tier structure across European fresh produce netting, separating Ziegler-Natta validated premium grades from legacy phthalate-containing standard tiers and uncompounded economy resin. Price differentiation hinges on food-contact certification documentation and volume commitment scale, with French distributors showing lowest sensitivity due to supply continuity prioritization. Cost compression in standard polyethylene grades is intensifying because ethylene feedstock volatility squeezes converter margins on agricultural contracts. Mediterranean agricultural cooperatives exhibit highest price sensitivity, consolidating volume toward fewer suppliers capable of consistent aperture tolerance.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes complicate catalyst system and specialty resin inbound logistics for European extrusion compounders. Converter capacity concentrates in Germany, Spain, and Italy where fresh produce logistics networks anchor regional supply. Raw material sourcing draws from Saudi ethylene crackers, Belgian catalyst suppliers, and Austrian cellulosic fiber producers. Single-source vulnerability sits with metallocene catalyst supply qualified for FDA food-contact applications. Distribution runs through direct converter-to-processor relationships in high-volume agricultural and pharmaceutical segments, supplemented by regional wholesalers serving fragmented cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated produce retail procurement across German and Dutch supermarket chains has shifted buyer power toward sustainability-mandated private-label programs, compressing supplier rosters and amplifying specification leverage for compliant converters.
For Market Incumbents: Shield market position through backward integration into REACH-compliant catalyst compounding and captive resin qualification libraries that lock out reformulation-lagged competitors. Prioritize capacity expansion in Valencia and Murcia corridors to capture Spanish citrus export consolidation. Defend against agro-fabric substitution by accelerating mono-material mechanical recycling certifications ahead of extended producer responsibility deadline tightening. For New Entrants and Emerging Players: FDA food-contact certification fast-track programs offer entry pathways into pharmaceutical vial netting where specification stickiness concentrates margin pools. Target e-commerce fulfillment mesh bag applications as the most penetrable segment, where automated packing line retrofit demand outpaces incumbent technical service capacity. Pursue direct technical engagement with Dutch greenhouse operators through roll-fed system compatibility demonstrations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional agricultural mesh specialists lacking EU Green Deal compliance infrastructure. Five-to-ten year viability favors converters with pre-validated material libraries and Mediterranean manufacturing footprints. Watch for inflection when extended producer responsibility frameworks in France and Italy achieve cost parity between certified biodegradable and conventional polymer alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Compounding | REACH-compliant Ziegler-Nata catalyst supply secures food-contact certification continuity for European extruders. |
| Mediterranean Manufacturing Footprint Expansion | Valencia and Murcia proximity reduces logistics complexity for Spanish citrus export corridor consolidation. |
| Mono-Material Mechanical Recycling Certification | EU Green Deal compliance unlocks contract renewals with sustainability-mandated German retail chains. |
| Pharmaceutical Serialization Sleeve Development | Custom extrusion capabilities for French and Italian vial netting create specification stickiness in traceability-driven lines. |
| Agro-Fabric Cost Parity Acceleration | Extended producer responsibility framework positioning captures Northern European compostability-minded retailer shelf space. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with extrusion compounders, fresh produce procurement directors, pharmaceutical packaging engineers, and agricultural cooperative managers; and secondary validation against ECHA regulatory filings, EU customs trade data, FDA food-contact substance inventories, and SEC disclosures from resin converters. Bottom-up volume modeling triangulated against top-down value estimates derived from industry association reports and distributor channel audits.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning material grade tier, end-use industry vertical, product form factor, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume movements adjusted for regulatory inflection timing and substitution elasticity parameters. Forecast inputs incorporated ethylene feedstock cost trajectories, extended producer responsibility scheme implementation schedules, and e-commerce fulfillment automation penetration curves.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and REACH compliance timeline adherence; material deviation would warrant model refresh. Specific risk factors include abrupt ethylene price spikes, accelerated agro-fabric certification cost reductions, and pharmaceutical serialization requirement delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Refuse Bags Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Padding Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Leno Bags Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Net Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Quad Seal Bag Market