
 Global PP Jumbo Bags Market | 2026-2036
Global PP Jumbo Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Global PP Jumbo Bags Market Outlook
Skilled weaving-machine operator availability is rotating toward Southeast Asian manufacturing clusters, unlocking capacity expansion for exporters serving European chemical buyers. Greif Inc. sustains integrated tape-extrusion and weaving operations across multiple continents. Berry Global Inc. leverages its resin procurement scale to control input cost volatility. Rishi FIBC Solutions Pvt. Ltd. specializes in customized four-loop and U-panel designs for agricultural clients.
Polypropylene jumbo bags, also called flexible intermediate bulk containers (FIBCs), are woven from polypropylene tapes typically rated for 500 kg to 2000 kg loads and constructed with lifting loops for forklift handling; their primary purpose is to store and transport dry flowable commodities in granular, powder, or flake form. Laminated bags command premium positioning due to moisture-barrier requirements in hygroscopic chemical and food-grade applications, while ventilated bags serve a narrower niche in agricultural produce where breathability prevents spoilage. The 1000 kg and 1500 kg capacity tiers dominate volume throughput across construction aggregates and fertilizer distribution.
REACH in Europe governs chemical migration limits and recyclate traceability, while FDA food-contact regulations in the United States mandate specific resin grades and manufacturing cleanliness protocols for edible-product handling. India's BIS certification requirements for FIBC safe working loads create compliance thresholds for domestic producers and importers alike. Stakeholders must monitor evolving extended-producer-responsibility frameworks in major economies and align capital allocation between virgin-resin capacity and post-industrial recycling streams.
Market Dynamics
REACH chemical migration limits and FDA food-contact resin grade mandates are compressing supplier qualification timelines while concentrating procurement among certified producers capable of dual-continent compliance documentation.
Growth Catalysts
- Construction sector scaling:India's infrastructure buildout and China's cement distribution networks are expanding 1000 kg and 1500 kg FIBC procurement for aggregates and pre-mix materials handling.
- REACH recyclate traceability:European chemical buyers now require documented post-industrial polypropylene content, pulling certified woven bag producers into circular supply chains.
- Brazil-ASEAN export corridors:Agricultural commodity handlers in São Paulo state and Vietnam's Mekong Delta are increasing bulk packaging orders as soybean and rice export volumes climb.
Market Restraints
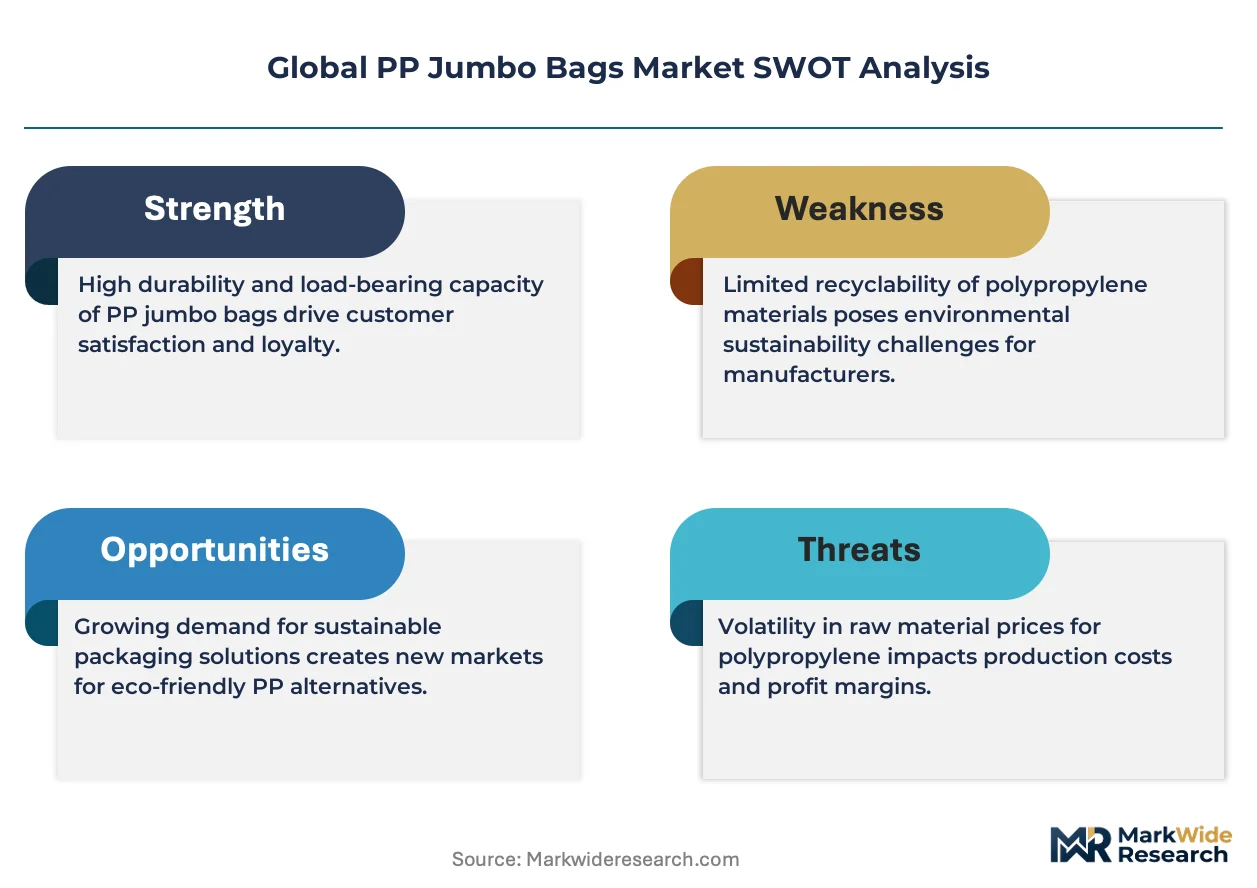
- Propylene feedstock volatility:Polypropylene resin prices swing with naphtha and propane cracking economics, compressing woven fabric converters' margin visibility.
- Skilled loom operator scarcity:Southeast Asian manufacturing clusters face recruitment gaps for circular loom technicians, capping output expansion despite order backlogs.
- Alternative rigid packaging:Intermediate bulk containers and steel drums retain share in liquid chemical handling where FIBC liners add cost complexity.
Strategic Opportunities
- Indian domestic chemical sector:BIS-certified safe working load requirements create compliance barriers that favor established domestic producers over importers.
- Ventilated agricultural designs:Breathable woven constructions for fresh produce handlers in Indonesia and Thailand address spoilage reduction needs in humid climates.
- EU Green Deal alignment:Extended producer responsibility frameworks reward producers with verified recycled content streams and closed-loop collection systems.
Industry Challenges
- Dual certification timelines:Simultaneous FDA and REACH compliance documentation stretches quality assurance departments at mid-scale weaving operations.
- Laminated film integration:Moisture-barrier coextrusion requires capital investment in extrusion coating lines that smaller producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PP Jumbo Bags Market |
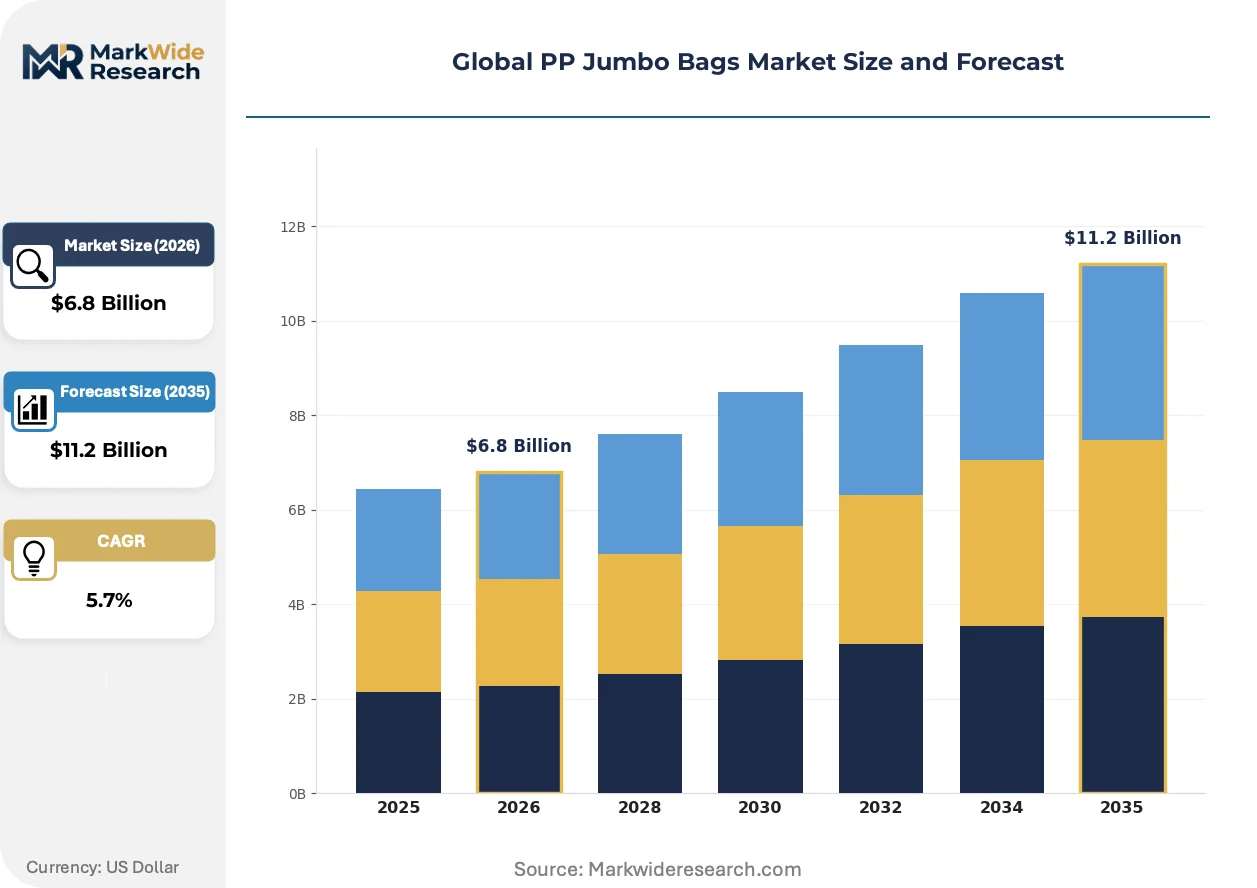
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Bags, Printed Bags, Laminated Bags, Ventilated Bags End User: Agriculture, Chemicals, Food & Beverages, Construction Capacity: 500 kg, 1000 kg, 1500 kg, 2000 kg Distribution Channel: Online, Direct Sales, Retail, Distributors |
| Companies Covered | Berry Global Inc., Greif Inc., Conitex Sonoco, AmeriGlobe LLC, LC Packaging, Bulk Corp International, Rishi FIBC Solutions Pvt. Ltd., Emmbi Industries Limited, Global-Pak Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PP Jumbo Bags Market Strategic Shifts
Digital printing and RFID-enabled inventory tracking are compressing batch customization economics while regulatory pressure on material traceability accelerates investment in automated quality verification systems.
Ultrasonic loop welding is miniaturizing quality variance in four-loop and U-panel FIBC construction. European chemical distributors are specifying ultrasonic-sealed lifting points to eliminate stitch failure modes in automated handling environments. This technology is compressing defect rates and extending certified safe working life cycles for multi-trip container programs.
REACH SVHC candidate list expansion is tightening substance disclosure obligations for polypropylene additive packages. Woven bag producers serving EU chemical handlers must now document antioxidant and UV stabilizer compositions down to 0.1% concentration thresholds. Food-grade FIBC lines are responding by migrating to single-additive masterbatch systems that simplify compliance documentation.
Buyers in Germany and the Netherlands are consolidating vendor lists around full-service suppliers capable of in-house tape extrusion, weaving, and cut-and-sew finishing. This concentration is displacing fragmented sourcing models that previously split component procurement across specialized converters. Chemical distributors with pan-European coverage are driving this preference for single-source accountability in quality incidents.
Global PP Jumbo Bags Market Segmentation
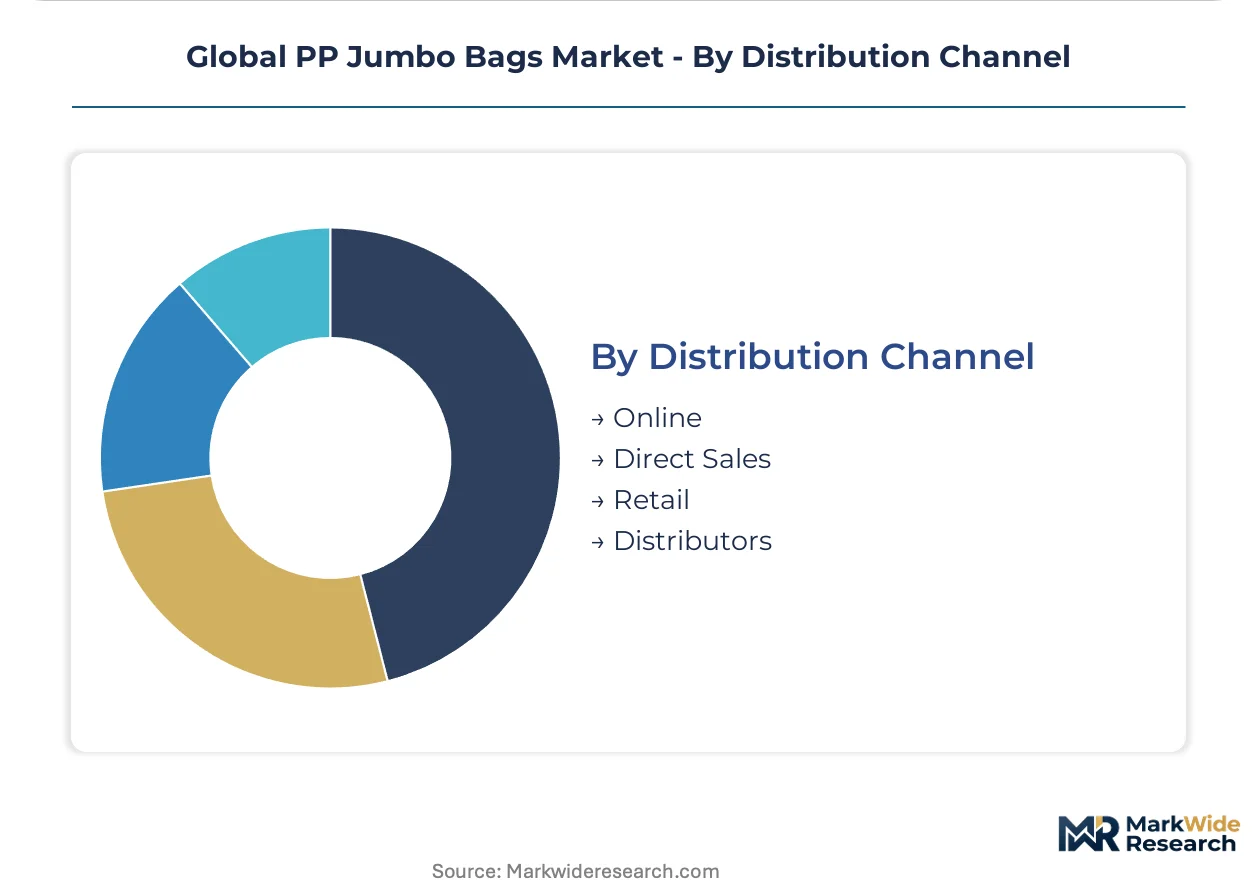
PP jumbo bag procurement channels diverge sharply by buyer sophistication and order scale. Agricultural cooperatives favor distributor networks for spot purchasing flexibility, while chemical majors negotiate direct supply agreements with certified weavers capable of REACH and FDA dual documentation.
Product Type:
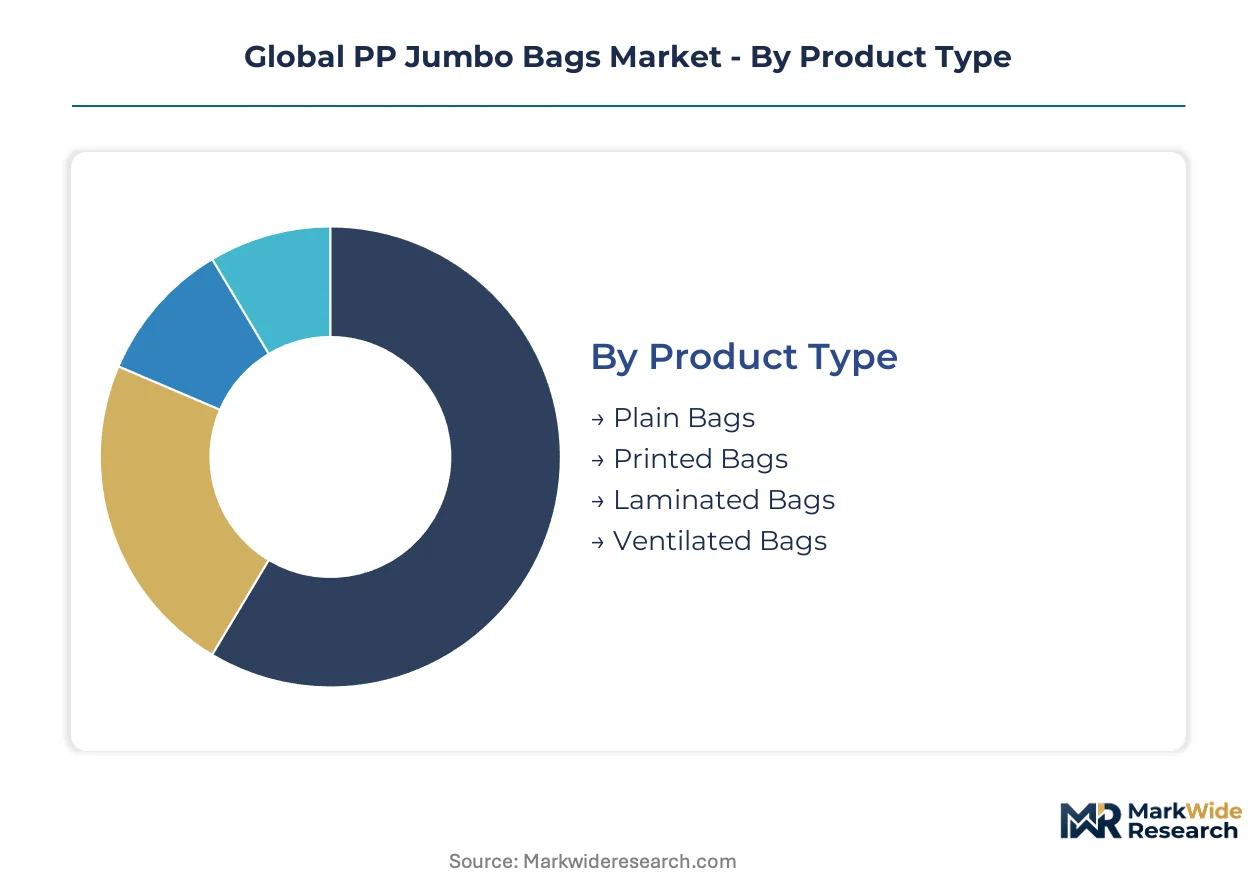
Channel mix varies dramatically across product categories, with laminated and ventilated constructions commanding dedicated sales teams while plain bags flow through commodity distributors.
- Plain Bags:Unlaminated woven polypropylene fabric serves bulk mineral and construction aggregate handlers seeking lowest unit cost. Demand concentrates in India's cement distribution networks and China's pre-mix material suppliers where price sensitivity outweighs moisture protection needs.
- Printed Bags:Flexographic and digital surface branding enables agricultural commodity exporters in Brazil and Vietnam to meet supermarket chain traceability requirements. Brand owners specify four-color process printing for rice and soybean shipments destined for European retail consolidation.
- Laminated Bags:Coextruded polyethylene or polypropylene film barriers block moisture ingress for hygroscopic chemical powders and food-grade ingredients. European chemical distributors specify laminated constructions for multi-trip container programs involving automated handling systems.
- Ventilated Bags:Perforated woven panels allow air circulation around fresh produce in Indonesia and Thailand's humid tropical supply chains, reducing spoilage in onion and potato export consignments.
Plain bags dominate installed base tonnage. Laminated bags are where margin expansion concentrates.
End User:
Cost tier stratification separates premium certified supply for food and chemicals from economy-grade procurement in construction.
- Agriculture:Grain, seed, and fertilizer handlers in Brazil's São Paulo state and Vietnam's Mekong Delta drive volume for breathable and standard woven designs. Export-oriented operations specify UN-certified constructions for international bulk shipping compliance.
- Chemicals:European REACH documentation requirements and FDA food-contact mandates compress supplier qualification to certified producers with in-house tape extrusion and automated quality verification. Safe working load certification to ISO 21898 standards is non-negotiable.
- Food & Beverages:Edible ingredient handlers mandate specific polypropylene resin grades and manufacturing cleanliness protocols. Single-additive masterbatch systems simplify compliance documentation for antioxidant and UV stabilizer disclosure thresholds.
- Construction:India's infrastructure buildout and China's cement distribution networks expand 1000 kg and 1500 kg procurement for aggregates and pre-mix materials. Price competition is intense, favoring domestic producers with resin procurement scale.
Chemical and food-grade segments command premium pricing tiers. Construction volume is climbing the fastest.
Capacity:
Volume concentration in mid-range tiers reflects forklift handling standardization and pallet dimension optimization across regional logistics networks.
- 500 kg:Compact dimensions suit specialty chemical batches and high-value agricultural seeds where partial container utilization reduces cross-contamination risk. Niche positioning in custom four-loop designs.
- 1000 kg:Standardized European pallet footprint drives procurement concentration among chemical distributors and construction material suppliers. Automated filling lines in Germany and the Netherlands specify this tier for handling equipment compatibility.
- 1500 kg:India's BIS-certified safe working load requirements and China's domestic chemical sector scaling favor this capacity for cement and fertilizer distribution. Dual-loop and U-panel constructions address regional handling preferences.
- 2000 kg:Maximum rated loads serve mining concentrates and dense mineral aggregates where single-lift efficiency outweighs per-bag material cost. Limited to heavy-duty circular loom constructions with reinforced lifting points.
1000 kg dominates European chemical procurement. 1500 kg is where Asian expansion concentrates.
Distribution Channel:
Customer type and order scale determine channel selection, with multinational chemical majors bypassing intermediaries while fragmented agricultural buyers rely on distributor inventory buffers.
- Online:Digital procurement platforms aggregate spot demand from small-scale agricultural handlers and regional construction contractors. Standard specifications and rapid fulfillment compete with traditional distributor relationships.
- Direct Sales:Greif Inc. and Berry Global Inc. maintain dedicated account teams for pan-European chemical distributors and multinational food manufacturers requiring coordinated multi-site supply contracts.
- Retail:Limited to small-capacity consumer-oriented packaging through agricultural supply cooperatives and construction material outlets. Margins compress against distributor-sourced alternatives.
- Distributors:Inventory-holding intermediaries in Brazil and Southeast Asia provide credit terms and technical specification guidance to agricultural commodity handlers lacking in-house packaging engineering resources.
Distributors dominate fragmented agricultural procurement. Direct sales channels are where chemical sector consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance in Europe anchors the most stringent procurement standards, while Asian manufacturing clusters absorb capacity migration from high-cost regions. Chemical distributors in Germany and the Netherlands consolidate vendor lists around certified suppliers capable of dual-continent documentation.
China
Cement distribution networks and domestic chemical sector scaling drive 1500 kg FIBC procurement concentration. MIIT industrial standards and dual carbon goals pressure producers toward energy-efficient circular loom operations. Manufacturing gravity centers on Shandong Peninsula fabricators serving construction aggregate handlers.
Germany
Pan-European chemical distributors specify ultrasonic-sealed lifting points and REACH-documented additive packages. ECHA substance disclosure obligations compress supplier qualification timelines to certified weavers. Industrial concentration in North Rhine-Westphalia hosts integrated tape-extrusion and weaving operations.
India
BIS-certified safe working load requirements create compliance barriers favoring established domestic producers over importers. Infrastructure buildout expands 1000 kg and 1500 kg procurement for pre-mix materials. Gujarat and Maharashtra manufacturing clusters scale capacity to serve fertilizer distribution networks.
United States
FDA food-contact resin grade mandates and manufacturing cleanliness protocols concentrate procurement among certified producers. Agricultural commodity handlers in grain belt states specify UN-certified constructions for export compliance. Midwest fabricators serve chemical and food-grade segments with dual-certification capability.
Brazil
Soybean export volume growth drives bulk packaging procurement from São Paulo state agricultural cooperatives. ANVISA regulatory frameworks govern food-contact applications for edible product shipments. Southeast Asian manufacturing clusters compete for export-oriented orders from Brazilian commodity handlers.
Global PP Jumbo Bags Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with tape-extrusion and weaving consolidation separating full-service suppliers from component-dependent converters. The upper tier commands premium positioning through captive resin procurement and automated quality verification systems. Mid-scale specialists compete on customized four-loop and U-panel designs for agricultural clients. Dominant competitive moves include backward integration into resin procurement and geographic expansion into Southeast Asian manufacturing clusters.
Among integrated packaging conglomerates, Greif Inc. and Berry Global Inc. represent the scale-driven archetype with multi-continent manufacturing footprints. Rishi FIBC Solutions Pvt. Ltd. exemplifies the specialist tier, occupying a position within customized agricultural packaging. These three anchors illustrate the market's bifurcation between volume-scale chemical supply and tailored commodity handling solutions.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Greif Inc. |
| Conitex Sonoco |
| AmeriGlobe LLC |
| LC Packaging |
| Bulk Corp International |
| Rishi FIBC Solutions Pvt. Ltd. |
| Emmbi Industries Limited |
| Global-Pak Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between European chemical distributors and certified weavers lock in polypropylene resin access while compressing price volatility exposure across REACH compliance cycles. These agreements tether margin visibility to naphtha cracking economics and skilled loom operator wage trajectories in Southeast Asian manufacturing clusters.
Pricing Analysis
Price spreads between European REACH-certified laminated bags and Indian plain-weave construction aggregate tiers exceed raw material differentials alone. Three-tier pricing structure across premium, standard, and economy levels separates FDA food-contact certified lines from BIS-compliant domestic Indian supply and unbranded commodity plain bags. Pricing pressure stems from propylene feedstock volatility squeezing converter margins, particularly in construction-grade procurement where Indian cement distributors exhibit acute price sensitivity. Chemical and food-grade buyers demonstrate lowest price elasticity, prioritizing dual-certification documentation over unit cost.
Supply Chain Analysis
Inventory buffers at distributor nodes in Brazil and Southeast Asia extend lead times for agricultural spot procurement while direct-sale chemical contracts compress fulfillment cycles through integrated tape-extrusion operations. Manufacturing gravity centers on China, India, and Vietnam, with Shandong Peninsula and Gujarat clusters serving regional construction and chemical demand. Raw material sourcing draws from Saudi and US Gulf Coast propylene supply, woven tape extrusion equipment, and laminated film coextrusion lines. Single-source vulnerability concentrates in circular loom technician pools across Vietnamese and Indonesian manufacturing zones. Distribution runs through inventory-holding intermediaries for fragmented agricultural buyers and dedicated account teams for pan-European chemical majors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks construction and agricultural export cycles, with India's infrastructure buildout and Brazil-ASEAN soybean corridors providing cyclical recovery momentum through the forecast window.
For Market Incumbents: Fortify backward integration into resin procurement to offset propylene feedstock volatility compressing converter margins. Expand ultrasonic welding and automated quality verification capacity to defend against mid-scale specialists encroaching on chemical sector procurement. Prioritize REACH-FDA dual-certification documentation as regulatory timelines stretch quality assurance departments at smaller competitors. For New Entrants and Emerging Players: Differentiate on ventilated agricultural designs for Indonesia and Thailand's humid climate produce handlers, where spoilage reduction needs outpace commoditized plain-bag supply. Target BIS-certified domestic production for India's fertilizer distribution networks, where compliance barriers displace import competition. Pursue digital printing and RFID-enabled inventory tracking as a go-to-market wedge against distributor-dependent agricultural cooperatives. For Investors and Strategic Acquirers: Capital is best deployed toward integrated tape-extrusion and weaving operations with captive resin procurement and automated quality systems, positioned for extended producer responsibility framework alignment. Long-term viability hinges on circular supply chain documentation and post-industrial recyclate traceability capabilities. Watch REACH SVHC candidate list expansion velocity as an inflection indicator for compliance cost concentration among certified producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Procurement | Greif Inc. and Berry Global Inc. control input cost volatility through captive polypropylene sourcing. |
| Ultrasonic Welding Technology Deployment | European chemical distributors specify sealed lifting points to eliminate stitch failure in automated handling. |
| REACH-FDA Dual Certification Investment | Documentation capabilities compress supplier qualification timelines to certified weavers with in-house extrusion. |
| Ventilated Design Specialization | Perforated woven panels address spoilage reduction needs in Indonesia and Thailand's humid tropical supply chains. |
| Extended Producer Responsibility Alignment | EU Green Deal frameworks reward producers with verified recycled content streams and closed-loop collection systems. |
Study Parameters
Desk research of customs and trade flow databases, SEC and BSE filings from packaging conglomerates, and REACH regulatory disclosure records preceded structured interviews with circular loom operations managers, chemical distributor procurement leads, agricultural cooperative supply chain directors, and BIS certification auditors. Primary fieldwork across Shandong Peninsula, Gujarat, and North Rhine-Westphalia manufacturing clusters combined with secondary validation from MIIT industrial standards and ECHA substance databases. Bottom-up capacity and utilization estimates triangulated against top-down trade value reconstructions.
Variance decomposition across product type, capacity tier, end-use industry, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and value-per-unit assumptions across the projection horizon. Forecast inputs incorporated propylene cracking margin cycles, skilled loom operator wage inflation in Southeast Asian manufacturing zones, and REACH recyclate traceability adoption curves among European chemical buyers.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure investment in India and China, or abrupt propylene supply disruptions, would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and agricultural export volume continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Refuse Bags Market
Bags and Containers
MSW Bag Opener Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Octabin Market
Bags and Containers
Desiccant Bags Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Flip-Up Vacuum Pack Market