
 Cross Corner Industrial Bags Market | 2026-2036
Cross Corner Industrial Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Cross Corner Industrial Bags Market Outlook
ISO 21898 certification for FIBC performance testing is reorganizing supplier eligibility across the Cross Corner Industrial Bags Market, forcing smaller weavers toward third-party lab partnerships. LC Packaging International BV leverages its captive testing infrastructure to sustain European retail and agrochemical contracts. Sinopack anchors Asian volume through integrated PP tape extrusion and circular loom operations in Zhejiang province. Storsack Group competes on UN-certified dangerous-goods designs for chemical handlers in Northern Europe.
Cross corner industrial bags are large-format woven polypropylene containers with corner lift loops sewn at 90-degree angles to the body, typically rated for 500 kg to 2,000 kg safe working loads and constructed from coated or uncoated PP flat tape fabric. These bags transport granular chemicals, construction aggregates, and agricultural commodities in bulk rail, truck, and vessel loading. FIBC and bulk bag categories capture the dominant margin pool due to higher unit values and custom UN certification requirements for hazardous cargo. Woven bags in standard 50 kg formats remain a mature volume segment with thinner margins, while ventilated bags for produce and eco-friendly packaging types with recycled PP content represent the fastest-growing structural category as brand owners face Scope 3 emissions scrutiny.
REACH in Europe and China's GB/T 8946 standard for plastic woven sacks govern resin composition, UV stabilization additives, and migration limits for food-contact applications. The US EPA and OSHA frame workplace handling rules that influence bag design for dust containment and operator safety in chemical plants. India's BIS certification for woven sacks is tightening under revised quality control orders that now cover PP and HDPE industrial packaging. Stakeholders must monitor how extended producer responsibility frameworks for flexible intermediate bulk containers reshape material recovery economics and regional sourcing decisions.
Market Dynamics
ISO 21898 certification requirements are restructuring supplier eligibility across the Cross Corner Industrial Bags Market, forcing smaller weavers toward third-party laboratory partnerships while rewarding integrated manufacturers with captive testing infrastructure.
Growth Catalysts
- Construction sector expansion:Asia-Pacific manufacturing hubs are scaling FIBC procurement for cement, aggregates, and sand transport, with China's infrastructure stimulus and India's smart cities initiative driving bulk container demand.
- REACH compliance tightening:Europe's chemical registration framework is mandating enhanced UV stabilization and migration testing for food-contact woven sacks, creating specification premiums for certified suppliers.
- Recycled PP technology maturation:Post-consumer polypropylene washing and re-extrusion lines are achieving food-grade purity thresholds, enabling circular content claims that satisfy Scope 3 emissions scrutiny from multinational brand owners.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking margins and regional refinery maintenance schedules inject raw material cost instability that compresses converter margins and complicates contract pricing.
- Weaving concentration in Zhejiang:Tape extrusion and circular loom capacity clusters in China's eastern province create geographic supply risk and logistical vulnerability to port congestion or regional power rationing.
- Flexible tank and silo substitution:Bulk liquid and powder handlers are adopting reusable stainless-steel intermediate bulk containers for closed-loop chemical logistics, displacing single-trip FIBC demand in certain process industries.
Strategic Opportunities
- Underpenetrated Indian chemicals corridor:Gujarat's petrochemical belt and Maharashtra's specialty chemical parks remain underserved by UN-certified dangerous-goods bag suppliers, offering first-mover positioning for certified converters.
- Extended producer responsibility frameworks:EU packaging waste directives and emerging state-level mandates in the United States are creating closed-loop collection infrastructure that rewards producers with established recycling partnerships.
- Digital printing convergence:UV-cured inkjet systems on woven substrates are enabling short-run customization and anti-counterfeiting serialization that commands premium positioning in agrochemical and seed markets.
Industry Challenges
- ISO 21898 certification timelines:Third-party performance testing for cyclic top lift, drop, and tear propagation consumes six to nine months, delaying market entry for new product specifications and retrofit designs.
- Skilled loom technician scarcity:Circular weaving machine calibration and tape tension optimization require experienced operators whose retirement wave outpaces vocational training program output in traditional manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross Corner Industrial Bags Market |
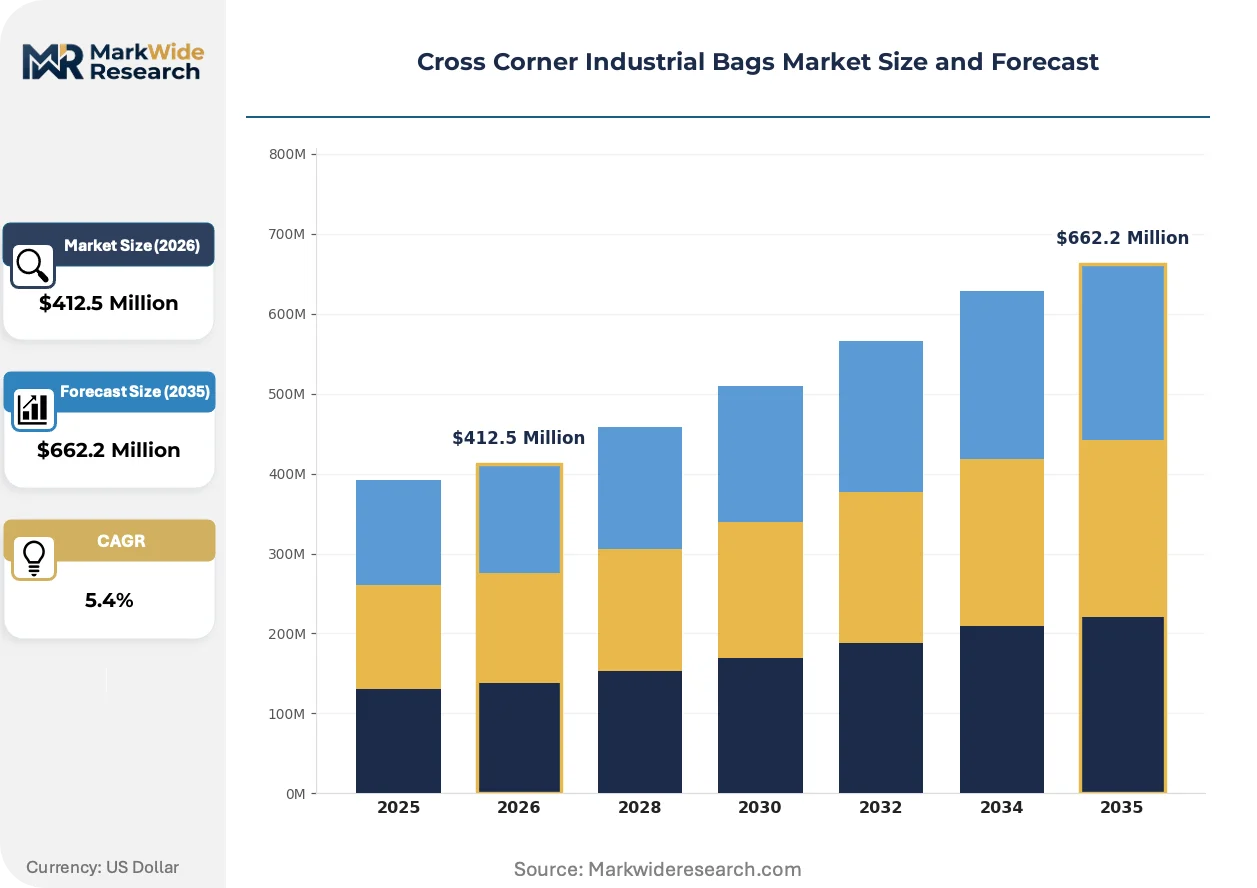
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Bags, FIBC, Ventilated Bags, Bulk Bags Material: PP, HDPE, LDPE, Coated Fabrics End User: Agriculture, Construction, Chemicals, Food & Beverage Packaging Type: Standard, Custom, Printed, Eco-friendly |
| Companies Covered | Sack Industrials Inc., Interjute, Sinopack, Aditya Timpack Pvt Ltd., Storsack Group, Bonus Bags, Accon, Years Sentetik, LC Packaging International BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross Corner Industrial Bags Market Strategic Shifts
Active developments in material science, regulatory enforcement, and buyer procurement protocols are compressing product lifecycles and redefining competitive differentiation in woven bulk packaging.
Co-extruded multilayer barrier films laminated to woven PP substrates are fragmenting the traditional coated-fabric segment by delivering superior moisture and oxygen ingress protection for hygroscopic chemicals and food ingredients. Specialty chemical handlers in Northern Europe and North American pharmaceutical ingredient distributors are specifying these constructions for sensitive powder transport. The technology is fragmenting margin pools as converters with lamination capabilities capture specification premiums while basic weavers face commoditization pressure.
REACH authorization and restriction procedures are tightening scrutiny on phthalate plasticizers and heavy-metal-based colorants in woven sack production, forcing reformulation of masterbatch additives across European supply chains. Chemical registrants face downstream notification obligations that cascade through converter tiers. Food-contact and pharmaceutical-grade bag specifications are absorbing disproportionate compliance cost as ECHA evaluations extend substance evaluation timelines.
Direct mill-to-plant procurement contracts are displacing distributor-mediated supply for high-volume chemical and agricultural buyers, compressing channel margins and rewarding converters with logistics integration capabilities. Large agrochemical multinationals and construction material consortia are consolidating vendor lists to capture volume pricing and simplify audit compliance. This concentration is most visible in Germany's Rhine-Ruhr chemical cluster and the US Gulf Coast petrochemical corridor, where integrated suppliers are establishing dedicated warehouse and just-in-time replenishment agreements.
Cross Corner Industrial Bags Market Segmentation
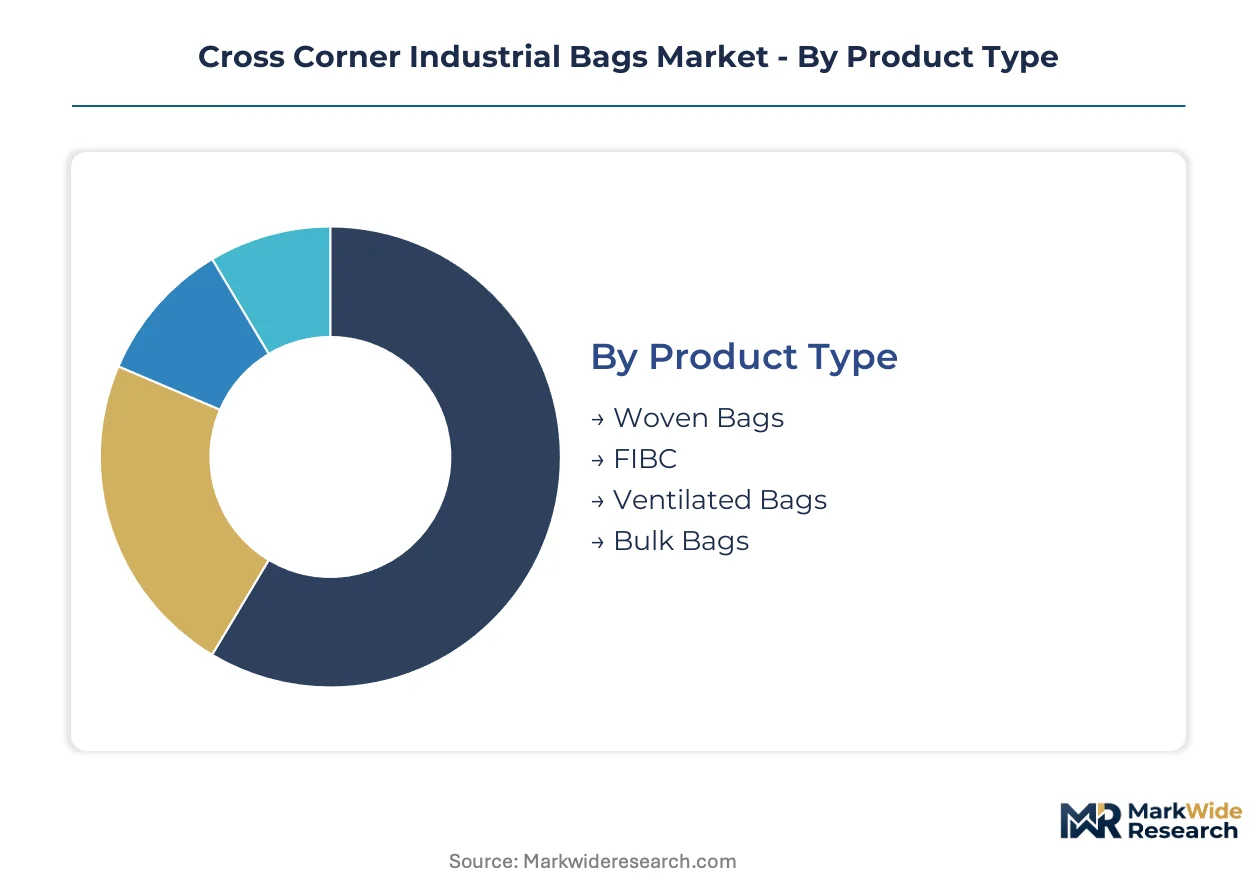
Segmentation in woven bulk packaging determines specification premiums, certification requirements, and vulnerability to substitute formats. Buyers in chemicals and food sectors impose distinct performance thresholds that fragment supplier eligibility across product tiers.
Product Type:
Flexible tank and silo substitution pressures FIBC and bulk bag segments most acutely, while woven bags in standard formats face margin compression from reusable IBC systems.
- FIBC:Large-format woven containers with corner lift loops rated for 500 kg to 2,000 kg safe working loads, constructed from coated or uncoated PP flat tape fabric. Chemical handlers in Germany's Rhine-Ruhr cluster and construction material distributors in India's smart cities corridors drive procurement volume. UN certification requirements for dangerous goods create specification premiums that reward converters with captive testing infrastructure.
- Bulk Bags:Heavy-duty woven polypropylene containers designed for granular chemicals, construction aggregates, and agricultural commodities in bulk rail, truck, and vessel loading. Demand concentrates in Gujarat's petrochemical belt and Maharashtra's specialty chemical parks where first-mover positioning remains available for certified suppliers.
- Woven Bags:Standard 50 kg format containers serving mature volume segments with thinner margins.
- Ventilated Bags:Perforated woven constructions for produce applications requiring airflow management.
FIBC anchors the volume base while ventilated bags gain share at the steepest rate as fresh produce exporters face extended supply chain scrutiny.
Material:
Cost tier stratification separates commodity resin grades from specialty formulations commanding certification premiums in food-contact and pharmaceutical applications.
- PP:Dominant polypropylene flat tape substrate for woven bulk containers, available in virgin and post-consumer recycled grades. REACH compliance in Europe and China's GB standards for plastic woven goods tighten material specifications for UV stabilization additives and migration limits.
- Coated Fabrics:Laminated or extrusion-coated PP substrates delivering superior moisture and oxygen barrier protection for hygroscopic chemicals and pharmaceutical ingredients. Specialty chemical handlers in Northern Europe specify these constructions, fragmenting margin pools as converters with lamination capabilities capture premiums.
- HDPE:Higher-density polyethylene alternative for chemical resistance applications.
- LDPE:Lower-density polyethylene for flexible liner applications and moisture barriers.
PP commands the dominant volume position while coated fabrics expand most quickly as barrier specifications tighten for sensitive powder transport.
End User:
Application-driven procurement patterns separate hazardous cargo handlers requiring UN certification from commodity buyers prioritizing unit economics.
- Chemicals:Specialty and commodity chemical handlers specifying UN-certified dangerous-goods designs with cyclic top lift, drop, and tear propagation testing. Storsack Group competes in Northern Europe on these certifications while India's chemicals corridor remains underserved by qualified suppliers.
- Construction:Cement, aggregates, and sand transport applications scaling across Asia-Pacific manufacturing hubs. China's infrastructure stimulus and India's smart cities initiative drive bulk container demand with direct mill-to-plant procurement contracts displacing distributor channels.
- Agriculture:Granular fertilizer and seed packaging with digital printing convergence for anti-counterfeiting serialization.
- Food & Beverage:Food-contact woven sacks absorbing disproportionate compliance cost as ECHA evaluations extend substance assessment timelines for phthalate plasticizers and heavy-metal-based colorants.
Construction anchors current procurement volume while chemicals climbs the fastest as hazardous cargo certification requirements intensify.
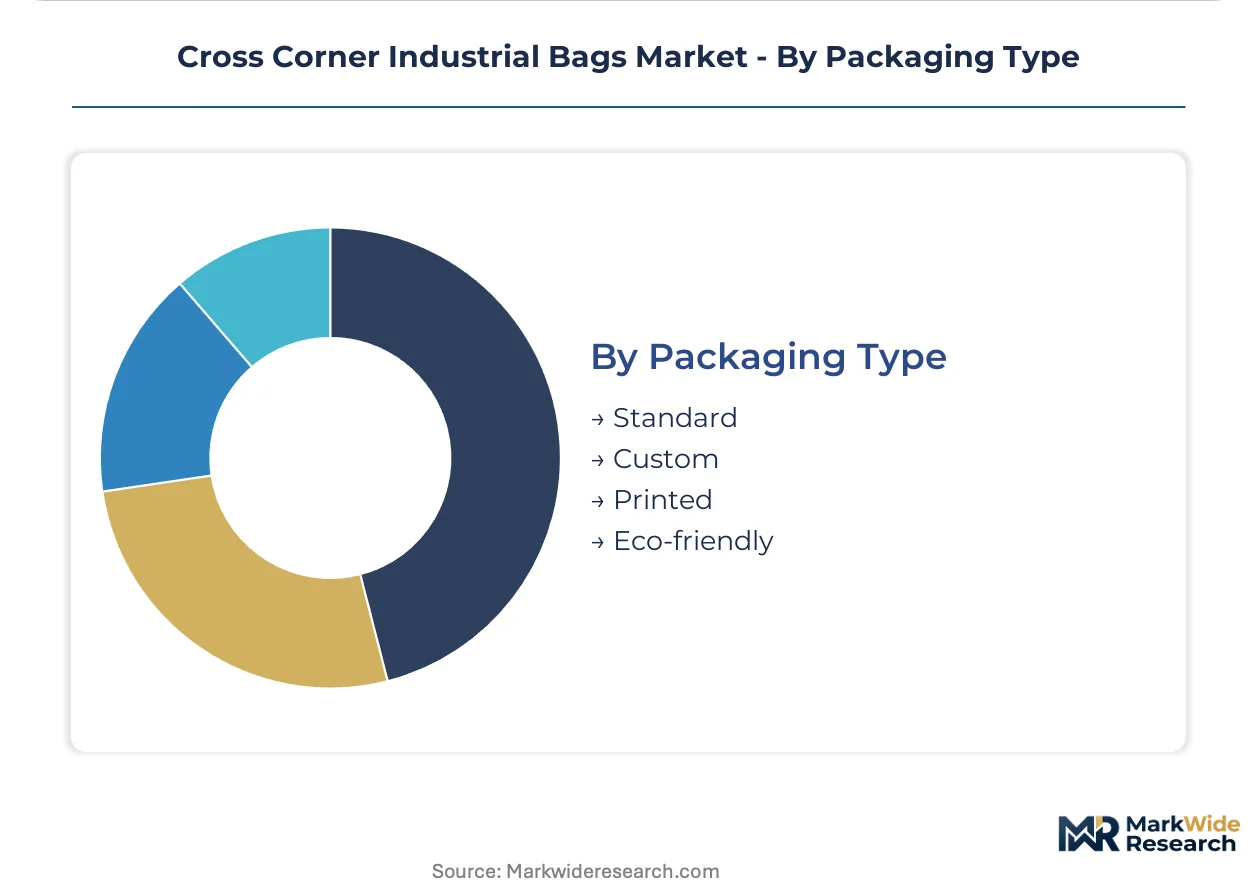
Packaging Type:
Customer type stratification separates high-volume contract buyers from short-run customization seekers, with sustainability mandates reshaping specification priorities.
- Eco-friendly:Woven containers incorporating post-consumer polypropylene content achieving food-grade purity thresholds through washing and re-extrusion lines. Brand owners facing Scope 3 emissions scrutiny drive specification adoption, with EU packaging waste directives creating closed-loop collection infrastructure rewards.
- Printed:UV-cured inkjet systems on woven substrates enabling short-run customization and serialization for agrochemical and seed markets.
- Standard:Unprinted, uncoated woven bags for commodity bulk transport with minimal specification overhead.
- Custom:Engineered designs for specific dimensional, barrier, or handling requirements.
Standard formats retain the dominant shipment volume while eco-friendly packaging gains share at the steepest rate as extended producer responsibility frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical handlers and construction material distributors concentrate procurement authority in industrial corridors where UN certification requirements and infrastructure stimulus programs intersect. Buyers in Germany's Rhine-Ruhr cluster, India's Gujarat belt, and China's Yangtze Delta dominate contract volumes.
Germany
Rhine-Ruhr chemical handlers specify UN-certified dangerous-goods designs for hygroscopic powder transport. REACH authorization procedures mandate reformulation of phthalate plasticizers and heavy-metal colorants in woven sack production. Düsseldorf-based converters capture specification premiums through captive ISO 21898 testing infrastructure.
China
Zhejiang province clusters tape extrusion and circular loom capacity serving construction aggregate and cement distributors. GB/T 8946 standards for plastic woven sacks tighten UV stabilization additive specifications and migration limits for food-contact applications. Ningbo-Shaoxing manufacturing hubs face power rationing vulnerability that disrupts just-in-time replenishment contracts.
India
Gujarat's petrochemical belt and Maharashtra's specialty chemical parks drive procurement of FIBC bulk containers for granular fertilizer and seed packaging. BIS certification for woven sacks tightens under revised quality control orders covering PP and HDPE industrial packaging. Mundra port logistics corridors concentrate converter capacity for Middle East export contracts.
United States
Gulf Coast petrochemical handlers and agricultural distributors in the Midwest consolidate vendor lists for volume pricing and simplified audit compliance. EPA and OSHA workplace handling rules influence bag design for dust containment and operator safety in chemical plants. Houston-area warehouse and just-in-time replenishment agreements reward converters with logistics integration capabilities.
Netherlands
Rotterdam port logistics and European distribution hubs service agrochemical multinationals requiring REACH-compliant woven containers. EU packaging waste directives create closed-loop collection infrastructure that rewards producers with established recycling partnerships. Venlo-based converters leverage digital printing convergence for anti-counterfeiting serialization in seed markets.
Cross Corner Industrial Bags Market Competitive Environment
Player mix skews toward mid-cap integrated weavers with captive testing infrastructure and regional specialists serving single-country chemical corridors. Market structure fragments across certification tiers rather than consolidating around scale leaders. Three archetypes dominate: European converters with UN-certified dangerous-goods capabilities, Chinese manufacturers with backward integration into PP tape extrusion, and Indian regional players capturing domestic chemicals corridor demand. Competitive moves concentrate on ISO 21898 certification acquisition and direct mill-to-plant procurement contract displacement of distributor channels.
Among European converters with captive testing infrastructure, LC Packaging International BV and Storsack Group exemplify the certification-premium archetype. Sinopack anchors the Asian volume position through integrated manufacturing operations in Zhejiang province. These three companies represent distinct strategic postures: European compliance specialization, Chinese scale integration, and regional corridor capture.
| Leading Market Players |
|---|
| Sack Industrials Inc. |
| Interjute |
| Sinopack |
| Aditya Timpack Pvt Ltd. |
| Storsack Group |
| Bonus Bags |
| Accon |
| Years Sentetik |
| LC Packaging International BV |
| Others |
Value Chain & Pricing Dynamics
Ninety-day order-to-delivery cycles for UN-certified FIBC specifications concentrate pricing power with converters possessing captive ISO 21898 testing infrastructure, while standard woven bag buyers exploit Zhejiang's weaving overcapacity to extract volume discounts. This lead-time stratification rewards integrated manufacturers with backward control over PP tape extrusion and punishes distributor-dependent weavers facing raw material volatility.
Pricing Analysis
Cost-plus contracts indexed to propylene monomer benchmarks dominate chemical sector procurement, with UN-certified dangerous-goods bags commanding three-tier pricing separation across premium certification, standard performance, and economy grades. Price differentiation hinges on ISO 21898 compliance tier and captive testing infrastructure ownership. Margins are tightening in standard 50 kg woven formats due to Zhejiang overcapacity and reusable IBC substitution. Construction material distributors in India and agricultural buyers in the US Midwest exhibit highest price sensitivity, while pharmaceutical and specialty chemical handlers in Northern Europe accept specification premiums.
Supply Chain Analysis
Port congestion on the Ningbo-Shanghai corridor and container availability swings on Asia-Europe trade lanes amplify inbound logistics costs for European converters dependent on Chinese woven fabric. Tape extrusion and circular loom capacity clusters in China, India, and Turkey, with raw material flows drawing from Saudi Arabian and US Gulf Coast propylene supply. Single-source vulnerability concentrates in Zhejiang's power-rationing exposure. Distribution runs through direct mill-to-plant contracts for high-volume chemical and construction buyers, compressing traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Testing-as-a-service and certification management offerings expand faster than base bag manufacturing, creating attach-rate opportunities for converters with captive laboratory infrastructure. Recurring revenue from annual re-certification and compliance auditing outpaces hardware shipment growth.
For Market Incumbents: Fortify ISO 21898 testing infrastructure against third-party laboratory competition while deepening backward integration into food-grade recycled PP washing lines. Flexible tank substitution in chemical logistics threatens single-trip FIBC volumes; defend position through dangerous-goods certification moats and just-in-time replenishment contracts with Rhine-Ruhr handlers. For New Entrants and Emerging Players: Accelerated BIS certification pathways for Gujarat's petrochemical belt offer first-mover positioning in India's underserved chemicals corridor. Target Maharashtra specialty chemical parks with UN-certified bag supply currently dependent on European imports. Go-to-market through direct technical sales to plant engineers bypassing established distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underutilized woven bag divisions lacking hazardous-goods certification capabilities. Five-to-ten year viability favors converters with integrated testing labs and established recycling partnerships under EU extended producer responsibility frameworks. Watch for REACH substance evaluation timelines accelerating compliance cost absorption as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PP Tape Extrusion | Captive supply of virgin and recycled flat tape insulates margins from propylene volatility. |
| ISO 21898 Certification Investment | In-house cyclic top lift and drop testing accelerates product qualification for chemical handlers. |
| Recycled PP Food-Grade Purity Achievement | Post-consumer washing lines satisfying Scope 3 emissions claims attract multinational brand owners. |
| Direct Mill-to-Plant Contracting | Bypassing distributor channels captures volume pricing and locks in Rhine-Ruhr chemical cluster demand. |
| Digital Printing Convergence | UV-cured inkjet serialization commands premium positioning in agrochemical and seed anti-counterfeiting markets. |
Study Parameters
Desk research of customs trade databases, BIS quality control orders, and ECHA substance evaluation precedents preceded structured interviews with FIBC plant managers, chemical procurement leads at downstream handlers, circular loom technicians, and recycling partnership coordinators. Bottom-up shipment estimates from converter capacity utilization triangulated against top-down chemical sector packaging spend analysis.
Variance decomposition across product type, material grade, end-use industry, and regional production hub shaped analytical framework throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by UN certification intensity and recycled content adoption curves. Modeled inputs included propylene feedstock cost bands, REACH authorization timelines, and infrastructure stimulus disbursement patterns.
Underlying assumptions cover sustained construction sector procurement in Asia-Pacific manufacturing hubs, with deviation risk concentrated in Zhejiang power rationing recurrence and flexible tank substitution acceleration in closed-loop chemical logistics. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Trash Bags Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Clay Desiccant Bag Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Textile Bags Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Mylar Bags Market
Bags and Containers
Zipper Bags Market
Bags and Containers
FIBC Market
Bags and Containers
Europe Bulk Bags Market
Bags and Containers
Conical Top Bulk Bag Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Low Melt Point Bags Market