
 Bag-In-Bottle Market | 2026-2036
Bag-In-Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Bag-In-Bottle Market Outlook
Aftermarket service revenue for dispenser refurbishment and replacement bag assemblies is tilting margin pools away from virgin packaging sales. AptarGroup, Inc. leverages its pump engineering heritage to dominate precision valve integration for cosmetic applications. Berry Global sustains manufacturing scale across multi-layer film extrusion, anchoring its position in high-volume food and beverage contracts. Amcor plc competes through global footprint density, while ALPLA Group specializes in custom blow-molding configurations that accommodate proprietary bag geometries.
A bag-in-bottle system consists of a flexible collapsible liner welded to a dispensing fitment, housed within a rigid outer shell that maintains structural integrity while the inner bag evacuates contents without air ingress; typical constructions employ ethylene vinyl alcohol coextrusion barriers measuring 80-250 microns to achieve oxygen transmission rates below 0.5 cc per square meter per day. The cosmetics application segment leads value contribution due to formulation protection requirements and premium positioning, while the biodegradable material category represents the fastest-growing structural pocket as brand owners face EPR compliance deadlines. Rigid containers retain volume dominance in household products where stackability and shelf presence determine retail placement.
FDA regulates bag-in-bottle assemblies for pharmaceutical applications through container closure system guidelines, while REACH restricts phthalate plasticizers and perfluorinated substances in European-sourced films. The EU Packaging and Packaging Waste Regulation is forcing converters to validate mono-material or certified compostable alternatives before enforcement phases activate. Stakeholders must monitor how FDA draft guidance on leachable studies and the EU Green Deal's carbon border adjustments will simultaneously reshape material qualification protocols and geographic sourcing decisions.
Market Dynamics
EPR compliance deadlines in Europe are compressing qualification timelines for mono-material and compostable bag-in-bottle constructions, forcing converters to validate alternative barrier films ahead of enforcement phases.
Growth Catalysts
- REACH Phase-Out Mandates:Restrictions on phthalate plasticizers and perfluorinated substances in European-sourced films are accelerating migration toward EVOH and bio-based barrier layers that maintain sub-0.5 cc oxygen transmission rates.
- Cosmetic Formulation Protection:Airless dispensing requirements for vitamin C, retinol, and probiotic formulations are pulling precision valve integration into premium skincare packaging specifications.
- German Converter Clustering:Precision dispensing technology concentrates around specialized converters in Baden-Württemberg and Bavaria, creating localized supply density that reduces lead times for cosmetic brand owners.
Market Restraints
- EVOH Resin Supply Concentration:Multi-layer film extrusion depends on ethylene vinyl alcohol supply chains concentrated in East Asian petrochemical complexes, exposing converters to input cost volatility and shipping disruptions.
- Biodegradable Barrier Performance Gap:Certified compostable alternatives struggle to match the 80-250 micron EVOH coextrusion specifications required for oxygen-sensitive pharmaceutical and cosmetic applications.
- FDA Leachable Study Burden:Draft guidance on container closure system testing for pharmaceutical bag-in-bottle assemblies is extending material qualification timelines by 12-18 months for novel film compositions.
Strategic Opportunities
- Aftermarket Service Unbundling:Dispenser refurbishment and replacement bag assembly programs are creating recurring revenue streams that decouple margin pools from virgin packaging unit sales.
- Household Product Stackability:Rigid outer shell configurations for cleaning and laundry applications remain underpenetrated relative to cosmetics, offering volume expansion where shelf presence and retail placement drive procurement decisions.
- EU Green Deal Carbon Border Adjustments:Import levies on carbon-intensive packaging materials are incentivizing regional production of bio-based films and localized blow-molding capacity.
Industry Challenges
- Multi-Material Separation Infrastructure:Post-consumer collection systems lack the optical sorting capability to separate welded bag-fitment assemblies from rigid outer shells, complicating closed-loop recycling claims.
- Welding Process Control:Hermetic seal integrity between collapsible liners and dispensing fitments requires precision heat and pressure calibration that strains quality assurance teams during scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bag-In-Bottle Market |
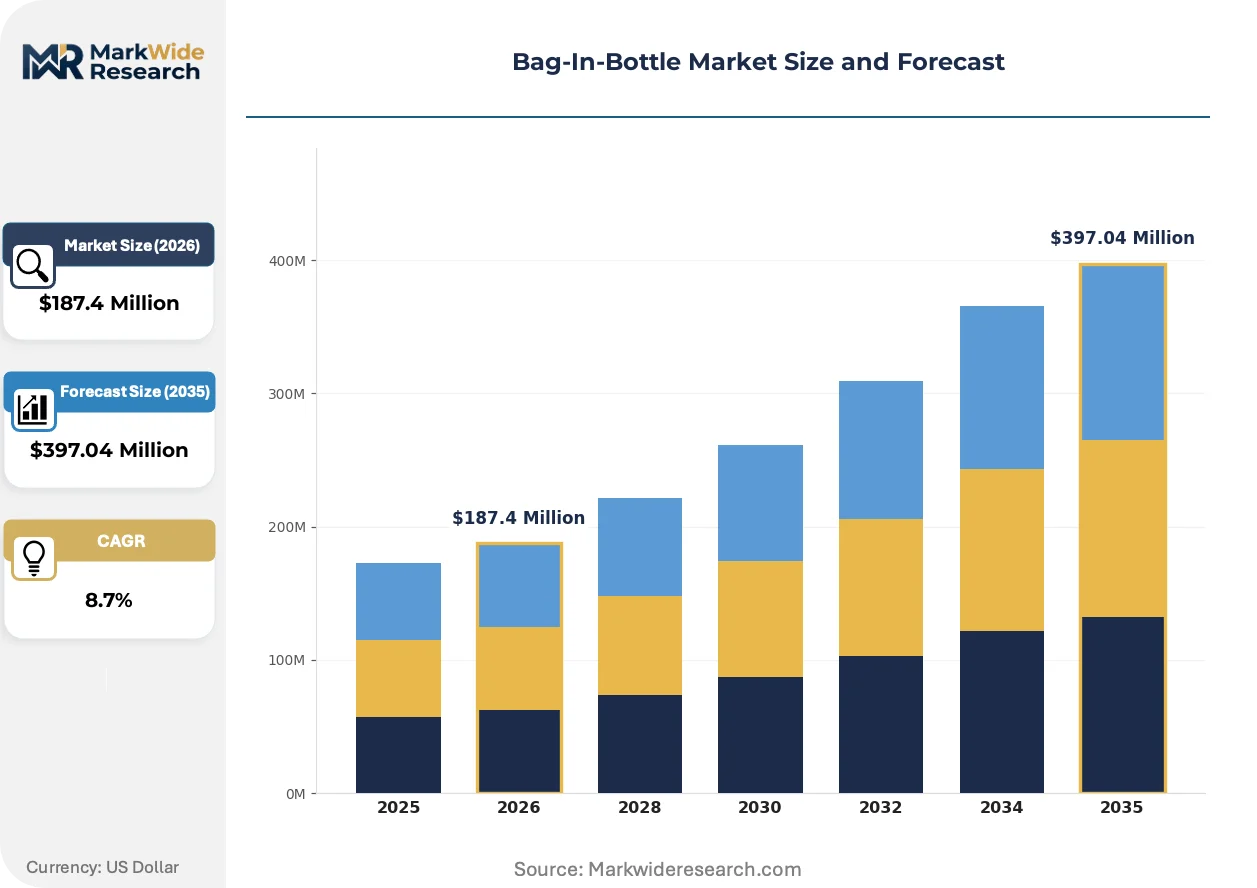
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouch, Rigid Container, Flexible Pouch, Custom Shapes Material: Plastic, Glass, Aluminum, Biodegradable Application: Cosmetics, Food & Beverage, Pharmaceuticals, Household Products End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | Gaplast GmbH, Eastar Cosmetic Packaging, Yuyao Longway Commodity Co., Ltd., RPC Group, AptarGroup, Inc., AFA Dispensing Group BV, Berry Global, Amcor plc, ALPLA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bag-In-Bottle Market Strategic Shifts
Active barrier technologies and regulatory material phase-outs are compressing incumbent film specifications while aftermarket service models are restructuring how value is captured across the packaging lifecycle.
Mono-material polyethylene constructions with plasma-deposited silicon oxide coatings are achieving oxygen barrier performance comparable to EVOH coextrusions. Cosmetic brand owners in France and Switzerland are piloting these constructions for mid-tier skincare lines. The elimination of adhesive lamination layers is rendering obsolete conventional multi-material welding processes that complicate mechanical recycling streams.
EU Packaging and Packaging Waste Regulation enforcement phases are mandating recyclability-by-design validation for all primary packaging placed on European markets. Converters must submit technical documentation demonstrating mono-material compatibility or certified compostability before 2030 deadlines. Pharmaceutical and cosmetic applications face the steepest compliance burden due to stringent barrier requirements that conflict with simplified material constructions.
Brand owner technical sourcing teams are consolidating supplier relationships around converters offering integrated valve engineering and aftermarket logistics. Direct procurement of replacement bag assemblies through e-commerce portals is displacing traditional distributor channels for institutional cleaning product buyers. This pattern is most visible in German and Austrian household product markets where facility managers prioritize inventory reduction over unit price minimization.
Bag-In-Bottle Market Segmentation
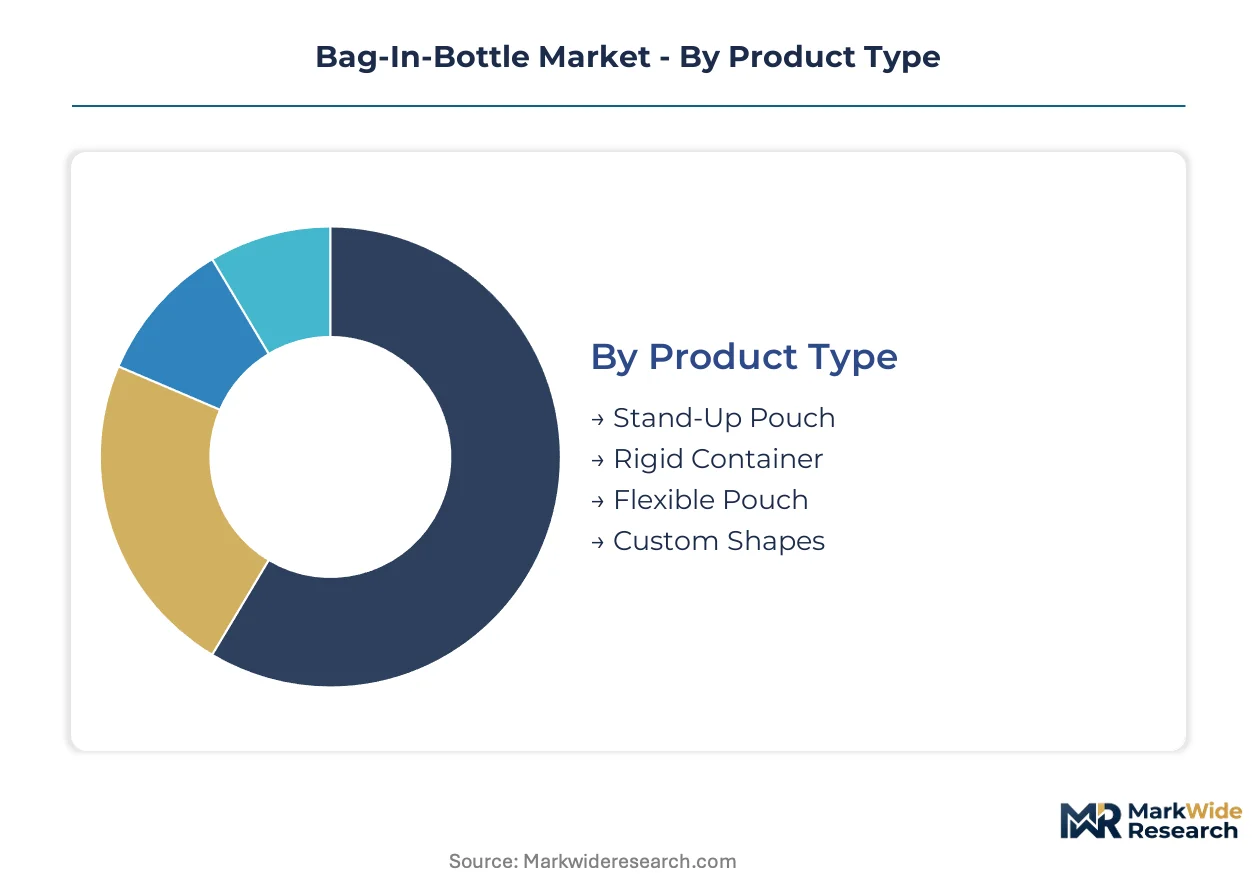
Segmentation in bag-in-bottle packaging reveals how technical specifications, material choices, and end-use requirements create distinct margin profiles and qualification timelines. Each dimension carries different regulatory burdens and aftermarket potential that reshape supplier relationships.
Product Type:
Replacement cycles stretch from single-use flexible pouches to multi-year rigid shell deployments, with refurbishment economics favoring formats that support component separation.
- Stand-Up Pouch:Self-supporting flexible construction with welded base gusset enables shelf display without rigid outer shell. German cosmetic brands specify this format for travel-size skincare lines where airless dispensing meets portability requirements.
- Rigid Container:Structural outer shell maintains dimensional stability through full bag evacuation, supporting stackability and retail shelf presence. Household cleaning product buyers in Bavaria prioritize this format for institutional procurement contracts.
- Flexible Pouch:Minimal material construction collapses completely during dispensing, reducing shipping cube and disposal mass. Suited for single-use pharmaceutical sampling and food service portions.
- Custom Shapes:Proprietary blow-molded outer shells accommodate brand-specific geometries for premium positioning. Extended design validation timelines restrict adoption to high-margin cosmetic applications.
Rigid containers dominate installed base. Stand-up pouches are where expansion concentrates.
Material:
Cost tiers separate commodity plastics from barrier-engineered constructions, with compliance deadlines compressing qualification windows for bio-based alternatives.
- Plastic:Multi-layer EVOH coextrusions measuring 80-250 microns achieve sub-0.5 cc oxygen transmission rates required for retinol and vitamin C formulations. REACH phase-outs of phthalate plasticizers are accelerating migration toward bio-based barrier layers.
- Biodegradable:Certified compostable films face performance gaps against EVOH specifications but gain traction where EPR compliance deadlines override barrier requirements. French and Swiss cosmetic pilots are validating plasma-deposited silicon oxide coatings on mono-material polyethylene.
- Glass:Inert barrier properties suit pharmaceutical applications with stringent leachable study requirements. Weight and fragility limit adoption to premium cosmetic segments.
- Aluminum:Zero oxygen transmission supports ultra-sensitive probiotic and pharmaceutical formulations. Higher material cost and welding complexity restrict volume deployment.
Plastic constructions anchor current volume. Biodegradable materials are climbing the fastest.
Application:
Application segmentation tracks how formulation sensitivity and regulatory classification determine valve precision requirements and barrier investment levels.
- Cosmetics:Airless dispensing for vitamin C, retinol, and probiotic formulations pulls precision valve integration into premium skincare specifications. REACH and FDA guidance on container closure systems impose extended qualification timelines.
- Food & Beverage:Oxygen-sensitive products like wine and cooking oils drive EVOH barrier adoption, though cost pressure favors simpler constructions for commodity liquids.
- Pharmaceuticals:FDA container closure system guidelines and draft leachable study requirements extend material qualification by 12-18 months for novel film compositions.
- Household Products:Rigid shell configurations for cleaning and laundry remain underpenetrated relative to cosmetics, offering volume expansion where shelf presence drives procurement.
Cosmetics commands premium positioning. Household products represent the steepest expansion trajectory.
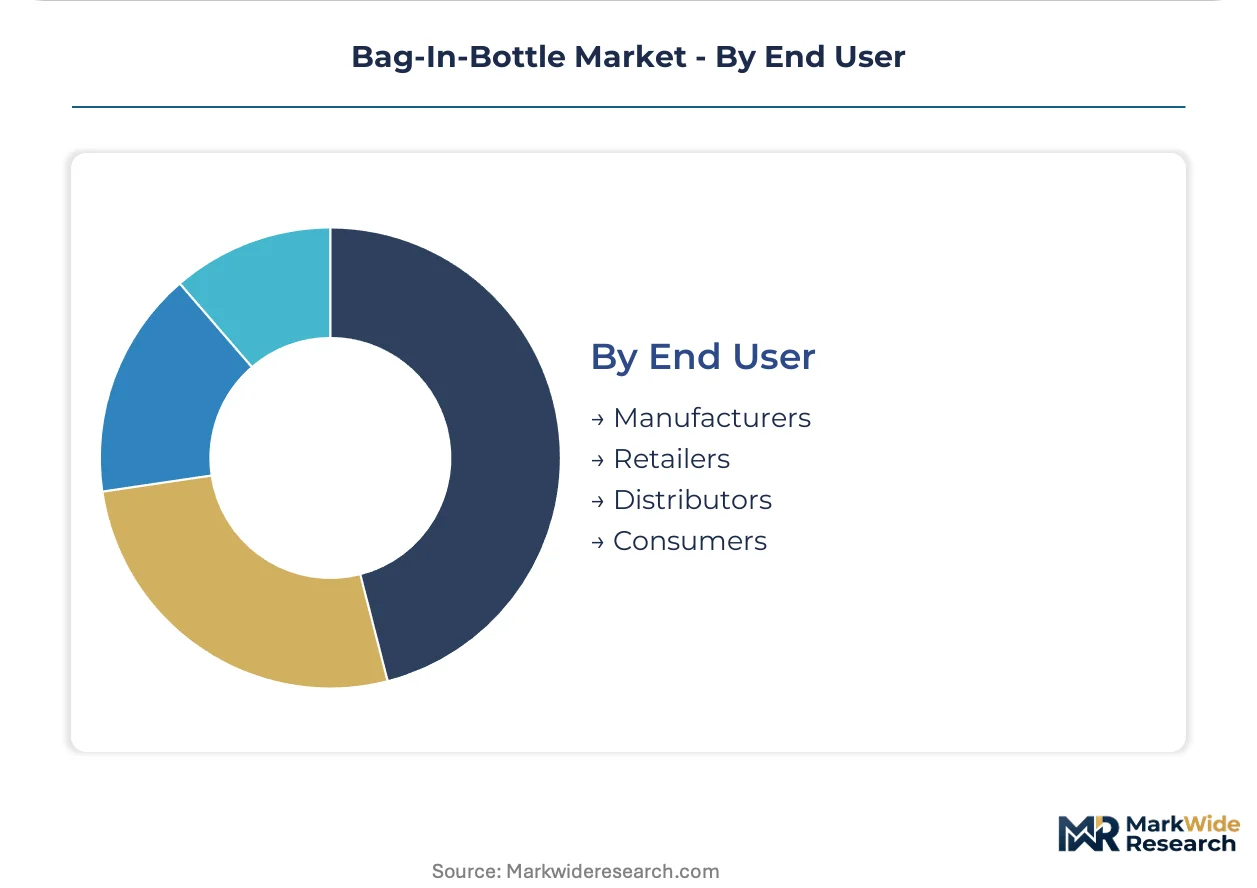
End User:
Customer type segmentation reveals how procurement authority and inventory management priorities reshape distribution channel economics.
- Manufacturers:Brand owners consolidate supplier relationships around converters offering integrated valve engineering and aftermarket logistics. Direct procurement of replacement bag assemblies through e-commerce portals is displacing traditional distributor channels.
- Retailers:Private label programs demand flexible minimum order quantities and rapid format switching that favors regional converter partnerships.
- Distributors:Traditional channel role erodes as institutional buyers prioritize inventory reduction over unit price minimization.
- Consumers:Refill and replacement bag purchases concentrate in German and Austrian household markets where facility managers drive procurement decisions.
Manufacturers control specification authority. Consumers are gaining direct procurement share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German procurement patterns diverge sharply from French and Swiss approaches, with precision dispensing technology clustering around Baden-Württemberg while French cosmetic brands pilot mono-material alternatives and Swiss regulators enforce stricter leachable study protocols.
Germany
Cosmetic formulation protection drives demand for airless dispensing systems, particularly for vitamin C and retinol products. REACH phase-outs of phthalate plasticizers and perfluorinated substances are accelerating migration toward EVOH barrier layers. Precision dispensing technology concentrates in Baden-Württemberg and Bavaria, where specialized converters reduce lead times for brand owners.
France
Mid-tier skincare lines are piloting mono-material polyethylene constructions with plasma-deposited silicon oxide coatings. EU Packaging and Packaging Waste Regulation enforcement phases mandate recyclability-by-design validation before 2030 deadlines. Cosmetic brand owners in Paris and Lyon are consolidating supplier relationships around converters offering integrated valve engineering.
Switzerland
Swissmedic maintains stringent container closure system requirements for pharmaceutical bag-in-bottle assemblies. Draft FDA guidance on leachable studies influences Swiss regulatory alignment, extending qualification timelines for novel film compositions. Precision valve integration for probiotic formulations concentrates around Basel's pharmaceutical packaging cluster.
United States
FDA container closure system guidelines govern pharmaceutical applications, with draft leachable study requirements extending material qualification timelines. EPA regulations on perfluorinated substances intersect with state-level packaging extended producer responsibility laws. Cosmetic and pharmaceutical brand owners in New Jersey and California prioritize precision dispensing technology for sensitive formulations.
China
SAMR and NMPA oversight of pharmaceutical packaging materials is tightening qualification requirements for imported barrier films. Dual carbon goals are pressuring converters to validate bio-based alternatives. EVOH resin supply chains concentrated in East Asian petrochemical complexes expose converters to input cost volatility and shipping disruptions.
Bag-In-Bottle Market Competitive Environment
Capability concentration sits with precision valve engineering specialists; scale advantage sits with multi-layer film extruders and global footprint operators. The market structures around three tiers: integrated pump-and-bag system providers, standalone film converters, and rigid shell blow-molding specialists. Dominant competitive moves include backward integration into barrier film production and geographic expansion of aftermarket service networks.
Within the integrated system tier, AptarGroup, Inc. and AFA Dispensing Group BV exemplify precision valve engineering heritage applied to cosmetic airless dispensing. Berry Global and Amcor plc anchor the scale-driven segment through multi-layer extrusion capacity and global manufacturing density. ALPLA Group occupies a position in custom blow-molding configurations that accommodate proprietary bag geometries for premium positioning.
| Leading Market Players |
|---|
| Gaplast GmbH |
| Eastar Cosmetic Packaging |
| Yuyao Longway Commodity Co., Ltd. |
| RPC Group |
| AptarGroup, Inc. |
| AFA Dispensing Group BV |
| Berry Global |
| Amcor plc |
| ALPLA Group |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's precision converter cluster concentrates EVOH barrier film capacity and valve integration expertise, granting incumbent suppliers leverage over cosmetic brand owners facing compressed qualification timelines. REACH-mandated material transitions and FDA leachable study requirements are amplifying pricing power for qualified converters while squeezing margins on legacy multi-layer constructions.
Pricing Analysis
Long-term offtake agreements dominate high-volume food and beverage contracts, locking in EVOH resin costs against East Asian petrochemical volatility. Three-tier pricing structure across premium, standard, and economy levels separates precision valve-integrated cosmetic systems from commodity household product configurations. Cost compression in standard-tier rigid containers is intensifying because German institutional buyers prioritize inventory reduction over unit price minimization. Household product procurement teams exhibit highest price sensitivity; cosmetic formulation protection requirements render premium skincare buyers least elastic.
Supply Chain Analysis
Extended payment terms from German cosmetic brand owners are straining converter working capital, accelerating supply-chain finance facility adoption among Bavarian film extruders. EVOH resin production concentrates in Japan, South Korea, and China; precision valve engineering clusters in Germany and Switzerland. Multi-layer film extrusion draws from ethylene vinyl alcohol, phthalate-free plasticizers, and plasma-deposition equipment. Single-source vulnerability in East Asian barrier resin exposes converters to shipping disruption. Distribution runs through direct e-commerce portals for replacement bag assemblies, displacing traditional distributor channels in German and Austrian institutional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cosmetic brand owner consolidation around integrated valve-and-bag suppliers is shifting procurement leverage toward specification authorities and away from fragmented converter bases.
For Market Incumbents: Build switching-cost moats through captive aftermarket service networks and replacement bag assembly logistics. Deepen backward integration into EVOH coextrusion capacity to offset East Asian resin supply concentration. Anchor long-term offtake agreements with German household product institutional buyers before REACH enforcement phases activate. Certification investment in mono-material polyethylene with silicon oxide barrier coatings defends against biodegradable substitute threats. For New Entrants and Emerging Players: Build out household product rigid shell configurations where shelf presence requirements remain underpenetrated relative to cosmetics. Target French mid-tier skincare pilots validating plasma-deposited barrier coatings as the most penetrable entry point. Pursue regional converter partnerships in Baden-Württemberg to access precision dispensing technology clusters without proprietary valve engineering investment. Direct-to-facility-manager e-commerce positioning bypasses entrenched distributor relationships in German-speaking markets. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because EPR deadlines and FDA guidance extensions are extending qualification timelines for novel material compositions. Acquisition targets should display integrated valve engineering capability plus aftermarket logistics infrastructure. Monitor Swissmedic alignment with FDA draft leachable study protocols as the inflection signal for pharmaceutical qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Film Production | Captive EVOH coextrusion capacity insulates AptarGroup and Berry Global from East Asian resin volatility. |
| Aftermarket Service Network Expansion | Dispenser refurbishment programs in Germany decouple recurring revenue from virgin packaging unit sales. |
| Mono-Material Certification Investment | Plasma-deposited silicon oxide validation positions French cosmetic pilots ahead of EU Packaging and Packaging Waste Regulation deadlines. |
| Precision Valve Engineering Acquisition | ALPLA Group's custom blow-molding configurations leverage proprietary bag geometries for premium cosmetic positioning. |
| Regional Production Footprint Densification | Localized blow-molding in Bavaria reduces lead times for German cosmetic brand owners clustered around Baden-Württemberg. |
Study Parameters
Cross-validation between primary interviews with packaging procurement directors and secondary regulatory filings anchors the qualitative findings on REACH phase-out timelines and FDA container closure system guidance. Technical sourcing managers at cosmetic and pharmaceutical brand owners, plant managers at multi-layer film extrusion facilities, aftermarket logistics coordinators, and regulatory affairs specialists at ECHA and FDA provided structured input. Trade data from German Federal Statistical Office, SEC 10-K disclosures from listed packaging converters, EU Packaging and Packaging Waste Regulation technical documentation, and clinical packaging qualification databases supplied secondary validation. Bottom-up unit economics and top-down market sizing were triangulated against converter capacity announcements.
Calibration against historical EVOH resin price volatility and cosmetic formulation launch cycles refined the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material construction, application sensitivity, and end-user procurement authority. CAGRs were derived from installed base replacement cycles and greenfield adoption curves in household products. Pharmaceutical leachable study duration assumptions and EPR compliance phase schedules served as industry-specific forecast inputs.
Stress conditions across EVOH supply disruption severity, REACH enforcement acceleration, and FDA guidance finalization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on barrier film performance evolution and aftermarket service penetration. Macroeconomic contraction, regulatory timeline deviation, or breakthrough biodegradable barrier technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Bag Making Machine Market
Bags and Containers
Padding Bags Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
Portion Bags Market
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Desiccant Bags Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Ventilated FIBC Market