
 Liner Bags Market | 2026-2036
Liner Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Liner Bags Market Foresight
Southeast Asian capacity expansion is reshaping liner bag supply dynamics as Vietnam and Indonesia add polyethylene film manufacturing lines. Mondi Group leverages integrated pulp-to-paper operations to anchor European food-grade liner supply. Greif sustains industrial drum and intermediate bulk container adjacencies that extend its liner bag distribution reach. National Bulk Bag specializes in custom-fitted bulk bag liners for agricultural commodity handlers across North American grain corridors.
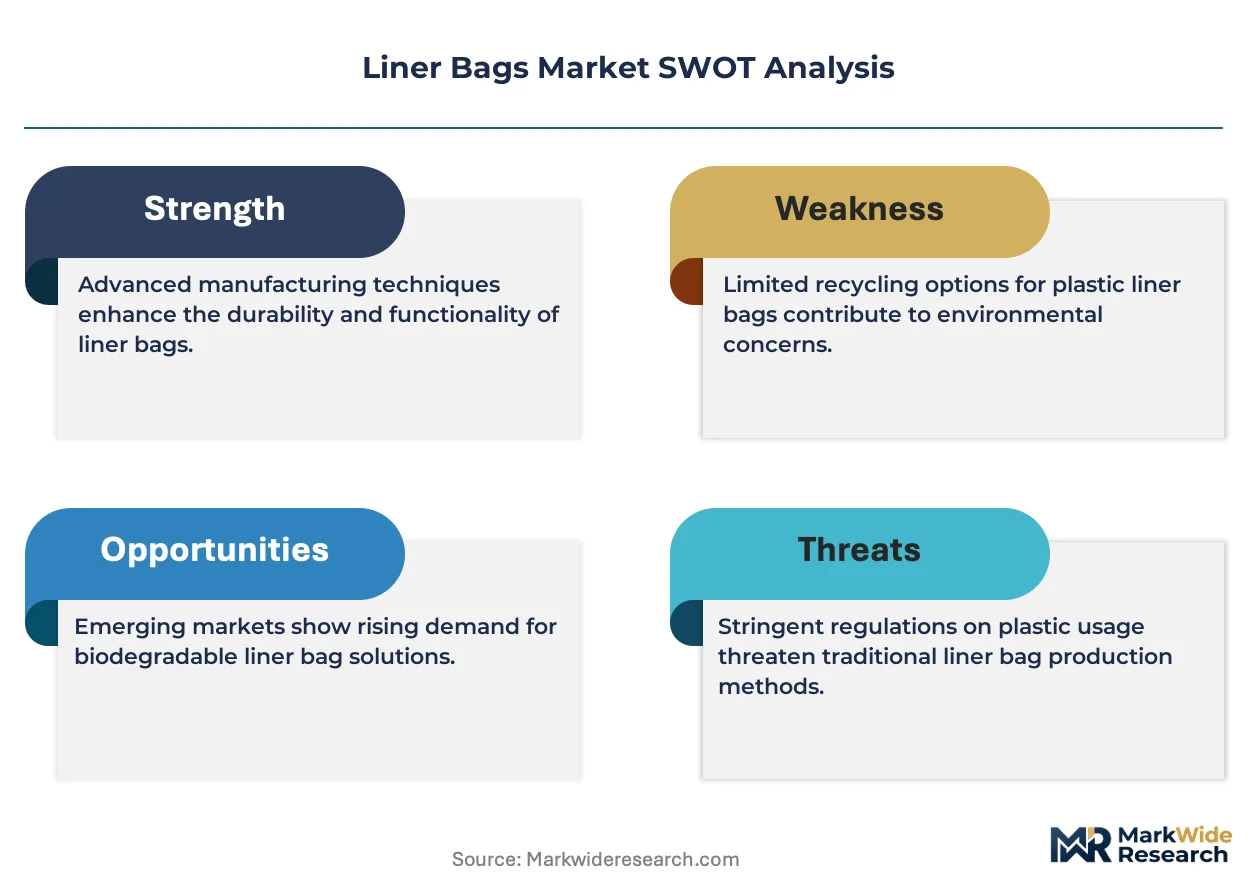
Liner bags are flexible containment vessels manufactured from polyethylene, polypropylene, nylon, or paper substrates, typically ranging from 2 mil to 6 mil in thickness, designed to line the interior of rigid containers or flexible intermediate bulk containers to prevent product contamination, moisture ingress, and cross-contact during storage and transport. Gusseted bags accommodate irregular bulk geometries in chemical transportation, while biodegradable variants face structural cost premiums against conventional polyethylene despite tightening landfill diversion mandates. Heavy-duty bags capture margin pools in industrial mineral and construction aggregate applications where puncture resistance commands specification premiums.
US FDA food contact substance regulations govern polyethylene and polypropylene liner compositions for direct food packaging applications, while EPA hazardous waste container standards dictate liner integrity requirements for chemical transportation. The EU REACH framework restricts certain phthalate plasticizers in flexible polymer liners, compelling material reformulation across import supply chains. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that will reshape liner collection and recycling infrastructure obligations.
Market Dynamics
EU Packaging and Packaging Waste Regulation compliance deadlines are forcing polyethylene and polypropylene liner manufacturers to accelerate material reformulation timelines. Food-grade certification requirements now dominate specification discussions across chemical and pharmaceutical logistics clusters.
Growth Catalysts
- REACH phthalate restrictions:ECHA-mandated plasticizer bans in flexible polymer liners compel supply chain restructuring toward bio-based alternatives. German chemical handlers drive demand for certified barrier specifications.
- Food packaging contamination resistance:FDA food contact substance regulations tighten polyethylene liner composition standards. Retailers specify multi-layer barrier solutions for bulk ingredient transport.
- Vietnam and Indonesia film capacity:Southeast Asian polyethylene manufacturing expansion reduces import dependency for regional agricultural commodity handlers. New extrusion lines target gusseted bag specifications.
Market Restraints
- Biodegradable structural cost premiums:Bio-based liner substrates face 40-60% manufacturing cost disadvantages against conventional polyethylene despite landfill diversion mandates tightening across OECD markets.
- Resin supply concentration:Polyethylene feedstock production clusters along US Gulf Coast and Middle Eastern petrochemical corridors expose liner manufacturers to hurricane and geopolitical disruption risks.
- Thickness-performance tradeoffs:2 mil to 6 mil specification ranges force compromises between puncture resistance and material efficiency in construction aggregate applications.
Strategic Opportunities
- California extended producer responsibility:State-level liner collection and recycling infrastructure obligations create first-mover advantages for integrated waste management partnerships.
- Agricultural commodity digital traceability:Blockchain-enabled provenance tracking converges with smart liner tagging for North American grain corridor handlers seeking contamination liability reduction.
- Industrial mineral heavy-duty specifications:Unmet demand exists for 6 mil+ puncture-resistant liners in copper concentrate and rare earth bulk transport where standard bags fail.
Industry Challenges
- Food-grade certification timeline compression:FDA submission backlogs for new polyethylene copolymer formulations extend commercialization windows beyond agricultural commodity seasonal procurement cycles.
- Legacy drum-liner integration friction:Intermediate bulk container retrofit programs require custom gusseted geometry engineering that strains technical service capacity at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liner Bags Market |
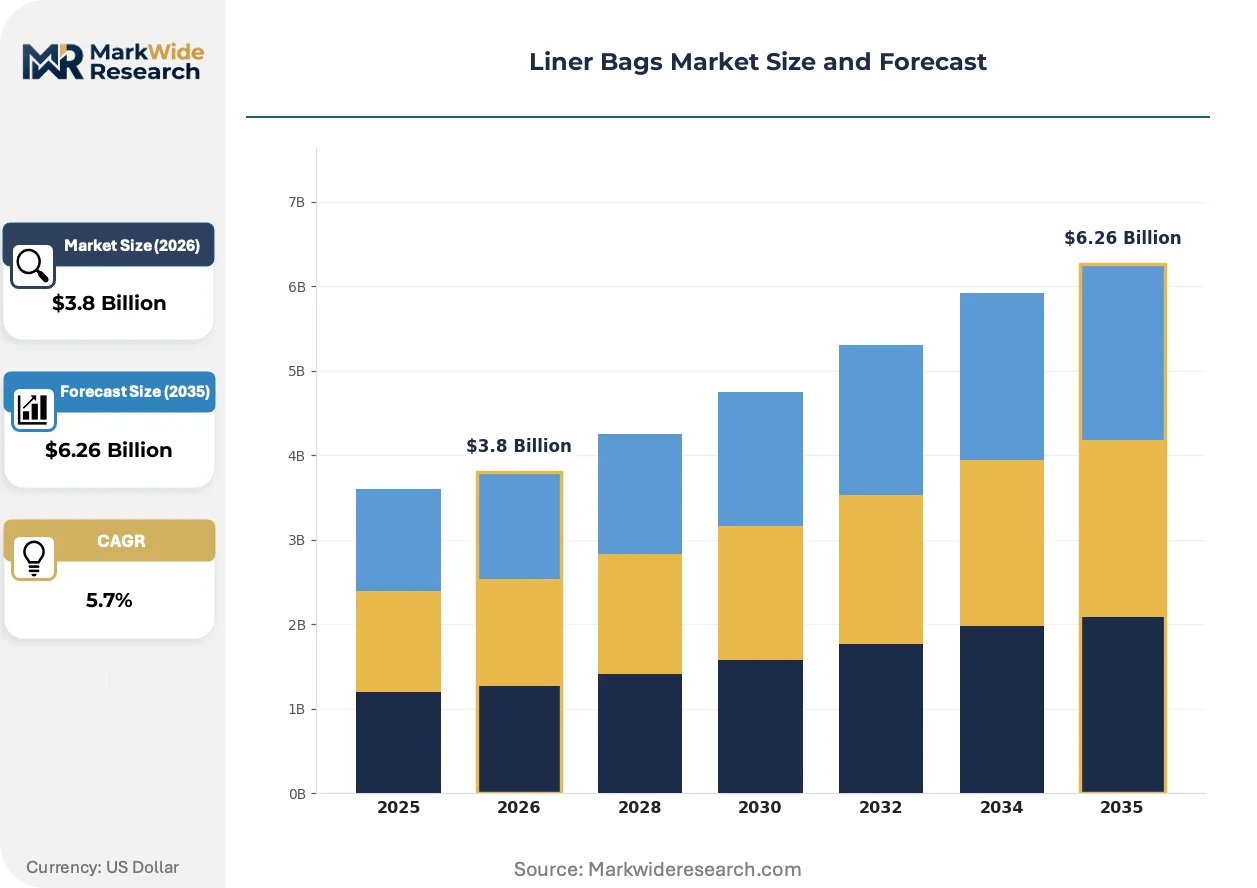
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Biodegradable Bags, Heavy-Duty Bags Material: Polyethylene, Polypropylene, Nylon, Paper End Use: Food Packaging, Chemical Transportation, Agriculture, Industrial Applications Size: Small, Medium, Large, Custom Sizes |
| Companies Covered | A-Pac Manufacturing, Winpak Ltd., National Bulk Bag, GLOBAL-PAK, Plascon Group, Southern Packaging, Greif, Mondi Group, Allied Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liner Bags Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are converging to transform liner bag substrate selection. Manufacturers must now validate performance claims through accelerated migration testing protocols while scaling production of compliant alternatives.
Multi-layer coextrusion barrier films incorporating ethylene vinyl alcohol and nylon are rendering obsolete single-layer polyethylene liners in pharmaceutical active ingredient transport. German and Swiss chemical logistics operators now specify oxygen transmission rates below 0.5 cc/m²/day for hygroscopic powder containment. This performance tier commands specification premiums that compress commodity-grade margin pools.
ECHA REACH Annex XVII phthalate restrictions now cover four additional plasticizer categories in flexible polymer liners. The industrial consequence is forced reformulation of polypropylene flex-crack additives across Asian import supply chains. Food-contact and pediatric pharmaceutical applications face the steepest compliance timelines with 2025-2026 sunset dates.
Direct mill-to-processor procurement contracts are displacing distributor-mediated liner sourcing for North American agricultural commodity handlers. Grain elevator cooperatives now negotiate annual volume commitments with integrated film manufacturers, bypassing traditional packaging distributors. This channel compression is most visible across Iowa, Illinois, and Nebraska grain corridors where handler consolidation has reduced buyer fragmentation.
Liner Bags Market Segmentation
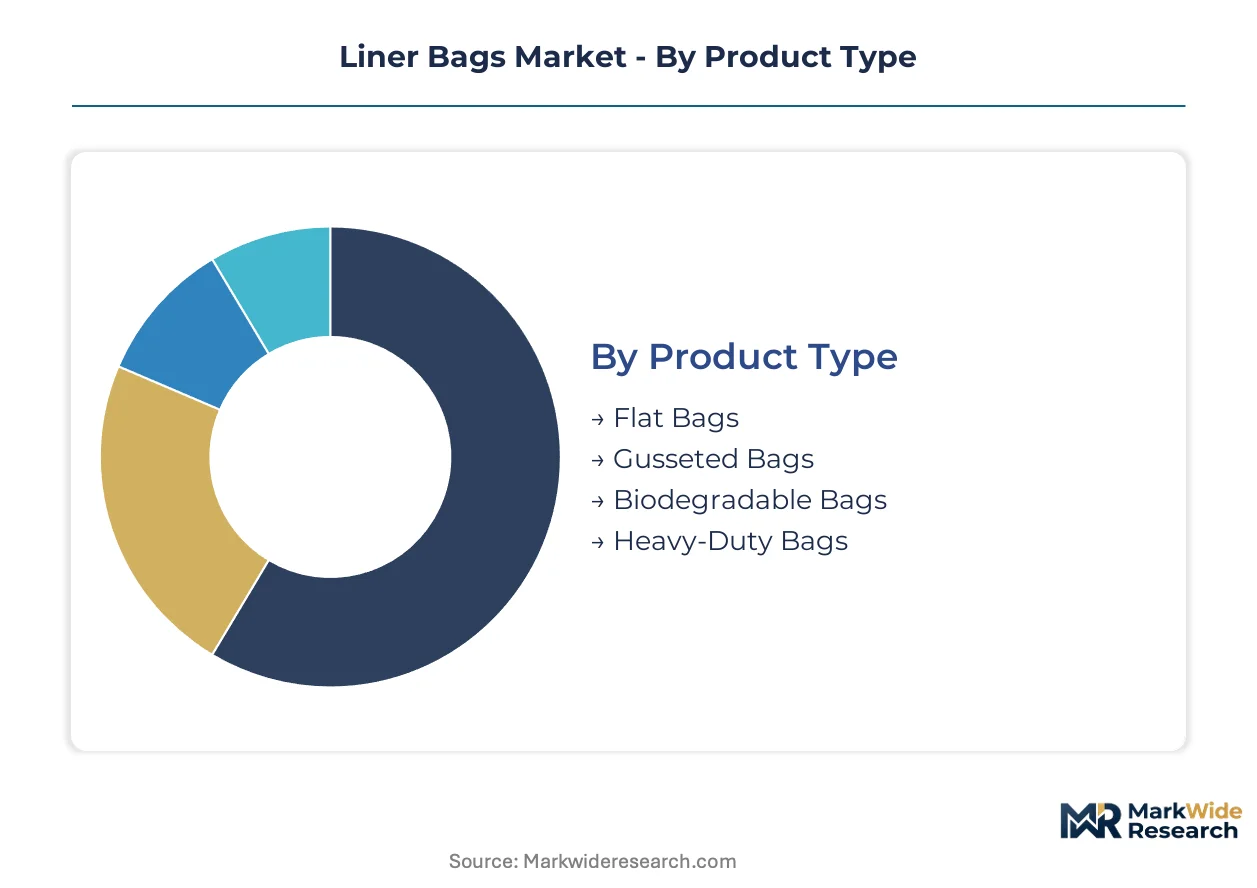
Liner bag specifications diverge sharply across transport modes and contamination sensitivity requirements. Material selection and geometry design determine compliance eligibility for regulated cargo categories.
Product Type:
Geometry configurations span from simple flat containment to engineered gusseted structures for irregular bulk loads.
- Gusseted Bags:Side-pleated construction expands to accommodate powder settling and irregular bulk geometries during chemical transport. German pharmaceutical logistics operators specify these for hygroscopic active ingredient containment where dimensional stability prevents stress fractures at fold points.
- Heavy-Duty Bags:6 mil+ polyethylene or nylon laminates deliver puncture resistance for construction aggregate and industrial mineral applications. Copper concentrate handlers in Arizona and Chilean mining corridors pay specification premiums for bags that withstand abrasive loading cycles without breach.
- Flat Bags:Standard 2-4 mil polyethylene construction serves low-stress food ingredient and dry chemical applications where uniform geometry permits simple sleeve insertion.
- Biodegradable Bags:PLA and starch-based substrates face structural cost premiums against conventional polymers despite tightening landfill diversion mandates across OECD markets.
Established volume favors flat bag simplicity; emerging adoption favors gusseted engineering for chemical logistics precision.
Material:
Substrate chemistry determines barrier performance, regulatory compliance eligibility, and end-of-life processing pathways.
- Polyethylene:LDPE and LLDPE formulations dominate food-contact applications through FDA-validated migration profiles. Multi-layer coextrusion with ethylene vinyl alcohol is displacing single-layer construction in oxygen-sensitive pharmaceutical transport.
- Polypropylene:Higher melt strength and flex-crack resistance suit industrial chemical containment with repeated handling cycles. ECHA REACH Annex XVII phthalate restrictions are forcing reformulation of flex-crack additives across Asian supply chains.
- Nylon:Polyamide substrates deliver puncture resistance and oxygen barrier for active pharmaceutical ingredient transport where moisture and oxidation sensitivity converge.
- Paper:Kraft and glassine liners serve dry food and agricultural commodity segments where breathability outweighs moisture barrier requirements.
Polyethylene retains volume leadership; polypropylene climbs fastest on chemical logistics specification upgrades.
End Use:
Regulatory chemistry and contamination liability exposure create divergent specification tiers across cargo categories.
- Food Packaging:FDA food contact substance regulations govern polyethylene and polypropylene compositions for direct ingredient contact. Retailers specify multi-layer barrier solutions for bulk transport of oils, sweeteners, and dairy powders.
- Chemical Transportation:EPA hazardous waste container standards and EU CLP classification rules dictate liner integrity documentation for corrosive and toxic cargo. German and Swiss logistics clusters drive oxygen transmission rate specifications below 0.5 cc/m²/day.
- Agriculture:Grain elevator cooperatives in Iowa and Illinois negotiate direct mill procurement contracts, bypassing traditional packaging distributors for annual volume commitments.
- Industrial Applications:Construction aggregate and mineral concentrate handlers require puncture-resistant specifications where standard 4 mil constructions fail under abrasive loading.
Food packaging commands specification premiums; chemical transportation shows steepest barrier-performance escalation.
Size:
Dimensional standardization versus customization reflects handler automation levels and cargo heterogeneity.
- Large:Intermediate bulk container liners ranging 1000-1500 liters serve chemical and pharmaceutical bulk transport with standardized filling equipment interfaces.
- Custom Sizes:Engineered dimensions accommodate retrofit drum programs and irregular container geometries that strain technical service capacity at mid-tier suppliers.
- Medium:200-500 liter specifications bridge drum and intermediate bulk container formats for agricultural commodity handlers with mixed fleet requirements.
- Small:Sub-50 liter liners serve laboratory chemical containment and specialty food ingredient portions where batch traceability demands individual unit isolation.
Large format dominates chemical logistics volume; custom sizing expands fastest on retrofit program demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput infrastructure underwrites European liner bag import distribution, while the Panama Canal expansion reshapes trans-Pacific supply routing for polyethylene film substrates.
United States
Gulf Coast petrochemical corridors feed domestic polyethylene resin supply for food-grade liner production. FDA food contact substance regulations govern migration testing protocols for bulk ingredient transport applications. Iowa and Illinois grain elevator cooperatives negotiate direct mill procurement contracts, bypassing traditional packaging distributors across the Corn Belt.
Germany
Chemical and pharmaceutical logistics clusters in the Rhine-Ruhr metropolitan region drive oxygen transmission rate specifications below 0.5 cc/m²/day. ECHA REACH Annex XVII phthalate restrictions compel polypropylene flex-crack additive reformulation across flexible polymer supply chains. BASF's Ludwigshafen complex anchors industrial demand for certified barrier specifications in hygroscopic powder containment.
China
Yangtze River Delta polyethylene film extrusion capacity expansion reduces import dependency for regional agricultural commodity handlers. NMPA pharmaceutical packaging regulations align with EU barrier performance standards for active ingredient transport. Zhejiang and Jiangsu province manufacturing clusters target gusseted bag specifications for chemical export logistics.
Vietnam
Haiphong port infrastructure upgrades support Southeast Asian liner bag export capacity growth. The country's national industrial development incentives attract polyethylene film manufacturing line investments from regional packaging conglomerates. Binh Duong and Dong Nai province industrial zones host new extrusion facilities targeting agricultural commodity handler demand.
Brazil
Santos port grain terminal expansion drives bulk liner demand for soybean and corn export logistics. ANVISA pharmaceutical packaging regulations require barrier integrity documentation for active ingredient transport applications. São Paulo state chemical distribution clusters specify multi-layer coextrusion films for corrosive cargo containment.
Liner Bags Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and geometry engineering. The vendor base separates into integrated pulp-to-paper operators, flexible packaging conglomerates with film extrusion assets, and regional fabricators serving agricultural commodity handlers. Three archetypes dominate: multinational diversified packaging platforms, mid-tier custom engineering specialists, and commodity-grade volume producers. Capacity expansion and direct mill-to-processor procurement contracting represent the dominant competitive moves reshaping channel relationships.
Among North American fabricators, National Bulk Bag and A-Pac Manufacturing occupy positions within the custom engineering tier, serving agricultural commodity handlers with tailored bulk bag liner geometries. Mondi Group and Greif exemplify multinational diversified platforms with integrated substrate production and extended distribution reach across industrial drum and intermediate bulk container adjacencies. These anchors represent how scale-driven operations and specialization-focused regional players coexist within segmented demand pools.
| Leading Market Players |
|---|
| A-Pac Manufacturing |
| Winpak Ltd. |
| National Bulk Bag |
| GLOBAL-PAK |
| Plascon Group |
| Southern Packaging |
| Greif |
| Mondi Group |
| Allied Plastics |
| Others |
Supply & Pricing Matrix
US Gulf Coast polyethylene resin production clusters concentrate upstream supply leverage, pushing margin capture downstream toward food-grade certification tiers and custom-engineered geometries for chemical logistics handlers.
Pricing Analysis
ECHA REACH Annex XVII phthalate restrictions dictate the pricing tier structure across European flexible polymer liner supply chains. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated food-contact grades from industrial chemical specifications and commodity-grade agricultural applications. Price differentiation hinges on oxygen transmission rate certification and migration testing documentation, with German pharmaceutical logistics operators showing least price sensitivity while North American grain elevator cooperatives drive hardest volume negotiations. Cost compression in standard-grade polyethylene flat bags is intensifying because Vietnamese and Indonesian film capacity expansion adds supply-side pressure.
Supply Chain Analysis
Extended payment terms from integrated pulp-to-paper operators and supply-chain finance facilities at flexible packaging conglomerates shape working capital requirements for mid-tier regional fabricators. Raw material sourcing draws from US Gulf Coast and Middle Eastern petrochemical corridors for polyethylene feedstock, Yangtze River Delta extrusion capacity for polypropylene films, and European kraft pulp supply for paper liner substrates. Single-source vulnerability concentrates around hurricane exposure at Texas-Louisiana resin production hubs. Distribution runs through Port of Rotterdam container throughput infrastructure for European import consolidation and Haiphong port upgrades for Southeast Asian export routing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where technical certification support and custom geometry engineering generate recurring revenue streams expanding faster than commodity liner substrate sales.
For Market Incumbents: Harden barrier-performance specification leadership by accelerating migration testing protocol investments ahead of FDA submission backlogs. Anchor channel control through direct mill-to-processor procurement contracting with Iowa and Illinois grain elevator cooperatives, neutralizing distributor-mediated sourcing compression. Prioritize in-house production of ethylene vinyl alcohol coextrusion capacity to capture oxygen transmission rate premiums above 0.5 cc/m²/day tiers. For New Entrants and Emerging Players: Pursue unmet demand for 6 mil+ puncture-resistant heavy-duty specifications in copper concentrate and rare earth bulk transport where incumbent technical service capacity strains under retrofit program complexity. Target Arizona and Chilean mining corridors with abrasion-resistant nylon laminate offerings. Lead with blockchain-enabled provenance tagging bundled with liner supply to differentiate against commodity-grade competitors. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier custom engineering specialists with captive film extrusion assets and established agricultural commodity handler relationships across North American grain corridors. Long-term viability favors participants with backward integration into polyethylene resin supply or upstream control over multi-layer coextrusion technology. Watch for ECHA plasticizer sunset date enforcement as inflection indicator for bio-based alternative material adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polyethylene feedstock secures margin protection against Gulf Coast disruption events. |
| Multi-Layer Coextrusion Capacity Expansion | Ethylene vinyl alcohol barrier film production targets German pharmaceutical oxygen transmission specifications. |
| Direct Mill Procurement Contracting | Bypassing distributors captures grain elevator cooperative volume across Iowa and Illinois corridors. |
| Biodegradable Substrate R&D Investment | PLA and starch-based alternatives address tightening OECD landfill diversion mandates. |
| Smart Liner Tagging Development | Blockchain convergence enables contamination liability reduction for agricultural commodity handlers. |
Research Methodology
Desk research of customs and trade flow databases, ECHA regulatory filings, and FDA food contact substance notifications preceded structured interviews with flexible packaging procurement directors, chemical logistics operators, grain elevator cooperative managers, and film extrusion plant engineers. Primary fieldwork across German Rhine-Ruhr pharmaceutical clusters, US Corn Belt agricultural handling facilities, and Vietnamese Binh Duong industrial zones validated secondary estimates. Bottom-up volume triangulation against top-down resin consumption analysis anchored forecast construction.
Assumptions held ECHA REACH Annex XVII enforcement timelines and FDA submission backlog durations constant while varying Southeast Asian capacity expansion rates and North American grain handler consolidation trajectories across the analysis window. Segmentation modeling incorporated product geometry, substrate chemistry, end-use regulatory tier, and regional production hub dimensions. CAGRs derived from weighted average of historical volume trends and elasticity-adjusted demand projections, with oxygen transmission rate specification escalation and biodegradable cost premium decay as key industry-specific inputs.
Sensitivities concentrate around ECHA plasticizer ban acceleration, FDA food contact substance regulation tightening, and hurricane disruption frequency at Gulf Coast resin production clusters. Forecasts reflect documented assumptions about regulatory compliance timelines and agricultural commodity trade flow stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Baffle Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Bag-On-Valve Laminates Market
Bags and Containers
Liquid Packaging Bag Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Breathable Bags Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Flat Bottom Bags Market
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Flip-Up Vacuum Pack Market