
 Crates Market | 2026-2036
Crates Market Size, Share, and Industry Trends Forecast 2026-2036
Crates Market Outlook
Polypropylene is hardening its position against traditional wooden crate construction across temperature-sensitive supply chains. Schoeller Allibert leverages its European molding footprint to dominate reusable beverage crate contracts with major brewers. Brambles anchors its competitive stance through CHEP's pooled pallet and crate network, sustaining asset density in North American grocery distribution. IFCO Systems specializes in RPC washing and tracking infrastructure, extending its service layer beyond hardware into logistics software.
A crate is a rigid, open or partially enclosed container engineered for stacking, lifting, and protecting goods during transit and storage, typically constructed with load-bearing walls, corner posts, and standardized footprint dimensions compatible with pallet racking systems. High-Density Polyethylene dominates manufacturing material selection due to its impact resistance, chemical inertness, and suitability for injection molding at scale. Plastic crates lead product type volume because of washability and cycle life, while wooden crates retain margin pools in custom export crating for heavy machinery. Food & Beverage end users drive replacement frequency, whereas logistics operators concentrate procurement among pooled crate programs to minimize capital lockup.
The EPA regulates crate material recovery under solid waste frameworks, while ISO 8611 governs pallet and container testing protocols that indirectly shape crate structural requirements for international shipment. The EU Green Deal's packaging reuse targets are forcing fast-moving consumer goods distributors toward returnable crate systems and away from single-use corrugated alternatives. Stakeholders must decide whether to build captive crate fleets or subscribe to third-party pooling services as capital and regulatory pressures intensify.
Market Dynamics
The EU Green Deal's packaging reuse targets are compressing single-use corrugated demand and forcing distributors toward returnable plastic crate systems, reshaping capital allocation across food and beverage supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory reuse quotas across member states are accelerating pooled crate fleet deployments in German and Dutch grocery distribution networks.
- High-Density Polyethylene injection molding:Automated molding lines are cutting per-unit production costs and enabling mass customization of ventilated produce crates for temperature-sensitive logistics.
- California agricultural concentration:Central Valley fresh produce handlers are standardizing on returnable plastic containers to reduce field-to-retail damage rates and comply with state organic waste diversion mandates.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing margins for injection molders serving price-sensitive export crating segments.
- Wooden crate supply concentration:Baltic softwood lumber sourcing dominates custom heavy machinery crating, exposing buyers to freight cost spikes and harvest cycle disruptions.
- ISO 8611 testing burden:International shipment compliance requires expensive dynamic load and drop testing, creating friction for small manufacturers entering pooled fleet supply.
Strategic Opportunities
- India cold chain underpenetration:Fragmented horticulture logistics in Maharashtra and Karnataka present white space for rental crate networks serving organized retail expansion.
- RFID-embedded tracking convergence:Integration of passive RFID tags with washing infrastructure enables real-time fleet visibility and usage-based billing models.
- US Inflation Reduction Act clean logistics incentives:Tax credits for supply chain decarbonization are nudging food distributors toward reusable container pooling versus disposable alternatives.
Industry Challenges
- Washing infrastructure capex intensity:Automated crate washing lines with HACCP compliance require seven-figure capital commitments, limiting third-party pooling market entry.
- Legacy ERP integration friction:Food distributors running SAP or Oracle WMS face customization costs to track returnable assets alongside inventory, delaying pooling adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crates Market |
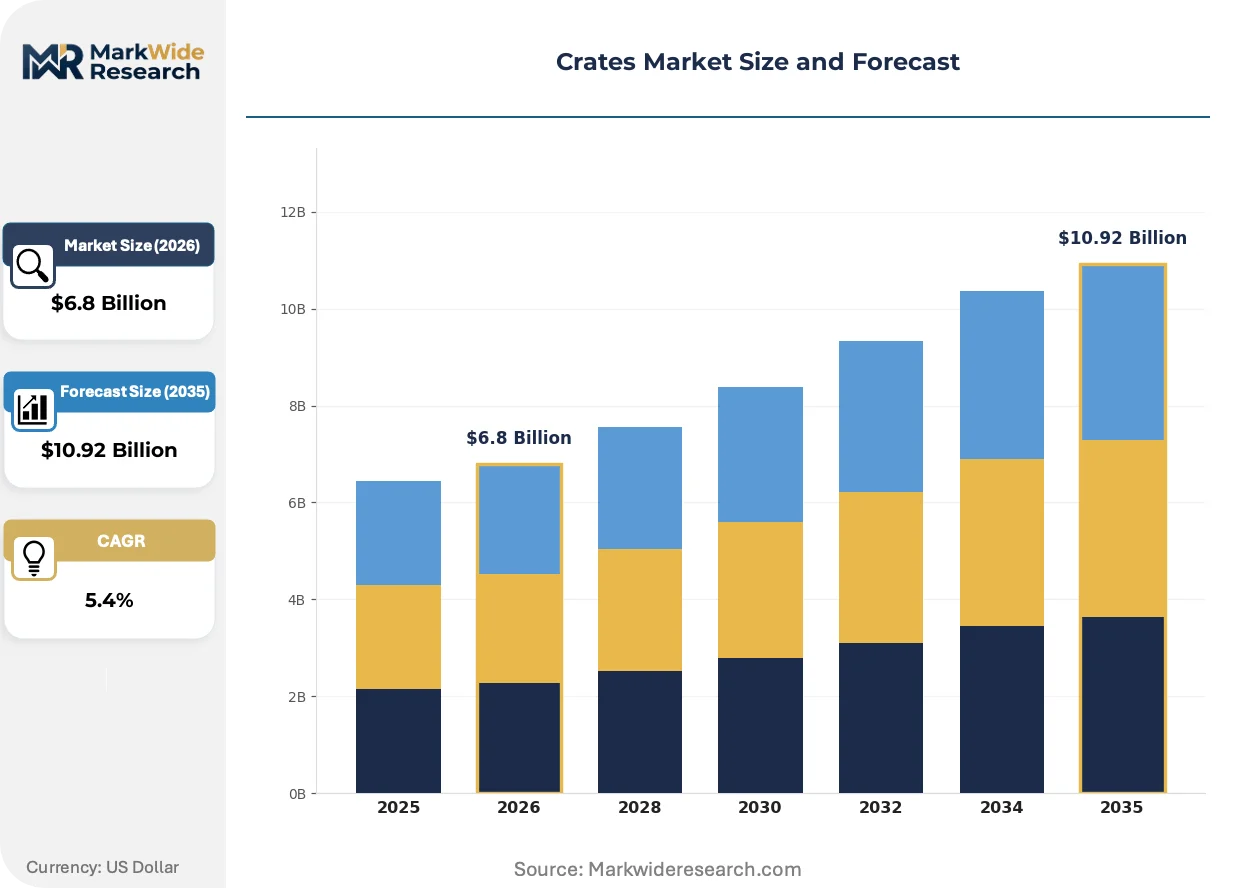
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Crates, Wooden Crates, Metal Crates, Cardboard Crates End User: Retail, Agriculture, Food & Beverage, Logistics Manufacturing Material: High-Density Polyethylene, Plywood, Steel, Recycled Material Usage Type: Transport, Storage, Display, Export |
| Companies Covered | Schoeller Allibert, IFCO Systems, Brambles (CHEP), Orbis Corporation, Rehrig Pacific Company, Myers Industries, Menasha Corporation, Craemer Group, DS Smith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crates Market Strategic Shifts
Active tracking technologies and closed-loop logistics models are displacing static asset management, while regulatory pressure on packaging waste accelerates material substitution and service-layer unbundling across crate supply chains.
RFID-tagged returnable plastic containers are expanding into pharmaceutical cold chain distribution, where temperature loggers embedded in crate walls provide shipment-level compliance documentation. Biologics manufacturers in Belgium and North Carolina are piloting these sensor-integrated crates for gene therapy shipments, compressing insurance and spoilage costs while enabling outcome-based logistics contracts with 3PL providers.
REACH chemical registration requirements in Europe are restricting certain plasticizers and flame retardants in food-contact crates, forcing compounders to reformulate polypropylene grades. Molded crate producers serving French and German beverage distributors are accelerating migration to bio-based additives, with compliance timelines compressing product development cycles and favoring larger compounders with dedicated regulatory affairs teams.
Third-party pooling subscriptions are displacing captive crate ownership among mid-sized grocery distributors, transferring asset management risk to specialized operators. Retail cooperatives in the Netherlands and regional US grocery chains are consolidating procurement through CHEP and IFCO fleet programs, concentrating volume among pooled crate providers and squeezing independent washing service margins in secondary markets.
Crates Market Segmentation
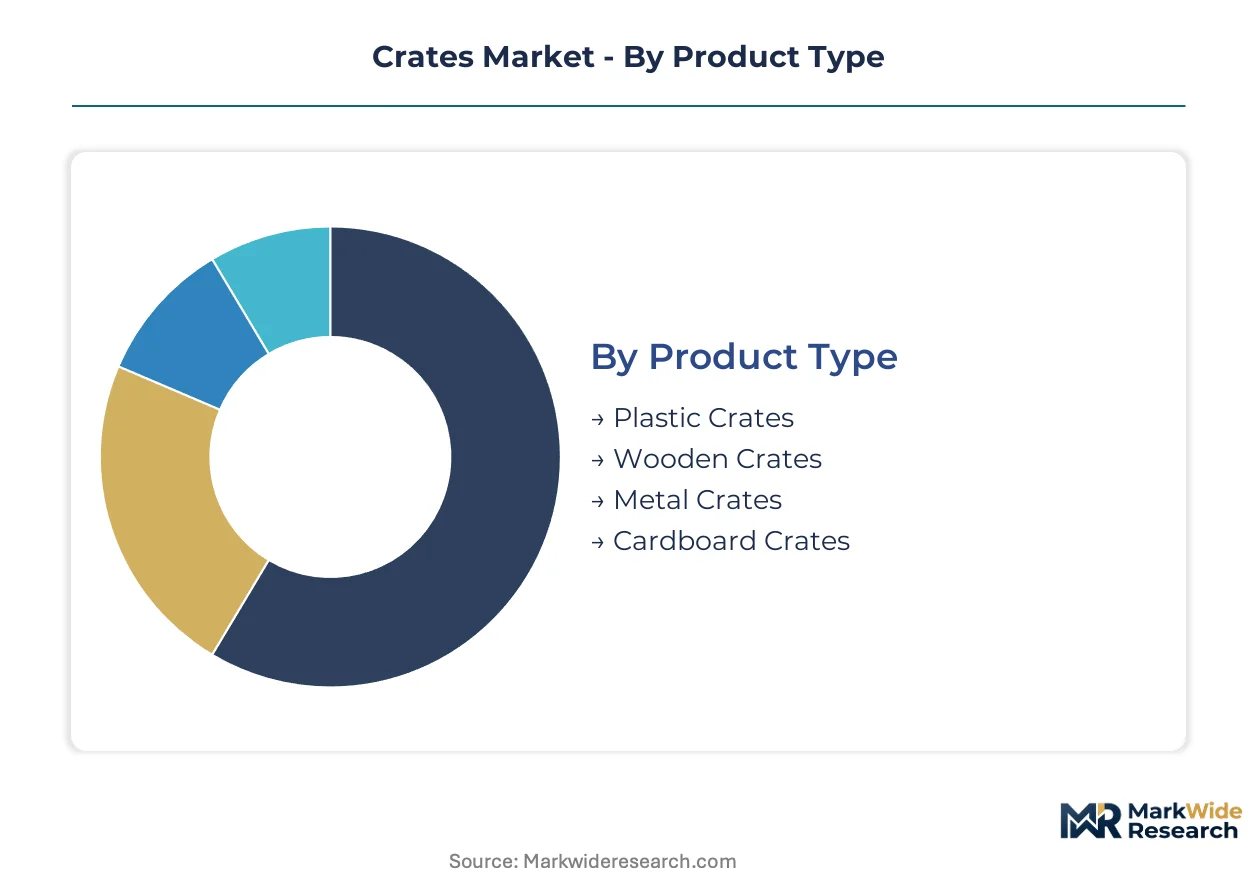
Crate procurement patterns diverge sharply across material specifications and use-case intensity. Buyers prioritize cycle life, washability, and regulatory compliance when matching container specifications to supply chain requirements.
Product Type:
Volume concentration and replacement frequency determine buyer selection across container formats.
- Plastic Crates:Injection-molded High-Density Polyethylene construction delivers impact resistance across temperature excursions from -20°C to 60°C. Food distributors in Germany's Rhine-Ruhr corridor are consolidating procurement around ventilated produce crates to comply with EU Green Deal reuse mandates.
- Wooden Crates:Baltic softwood or hardwood frames with slatted sides provide custom dimensional flexibility for irregular machinery loads. California Central Valley agricultural exporters retain wooden crating for single-use international shipments where return logistics prove uneconomical.
- Metal Crates:Steel wire mesh or sheet construction serves high-load industrial applications requiring fire resistance and extreme durability.
- Cardboard Crates:Corrugated fiberboard with laminated moisture barriers addresses lightweight, single-cycle distribution needs in e-commerce fulfillment.
Plastic Crates lead on scale; Cardboard Crates lead on momentum.
End User:
Asset ownership models and fleet management sophistication vary by downstream vertical.
- Food & Beverage:Brewers and fresh produce handlers operate the largest pooled crate fleets, with CHEP and IFCO managing wash-and-return infrastructure across North American grocery distribution networks.
- Logistics:Third-party operators concentrate procurement among standardized container programs to minimize capital lockup and maximize asset turns across multiple client accounts.
- Retail:Grocery chains in the Netherlands are consolidating through cooperative purchasing agreements for returnable plastic containers.
- Agriculture:California organic producers are shifting field-to-packhouse operations toward plastic crate systems to meet state waste diversion requirements.
Food & Beverage dominates fleet scale; Logistics is expanding most quickly.
Manufacturing Material:
Feedstock cost exposure and regulatory compliance timelines shape compounder and converter strategies.
- High-Density Polyethylene:Petroleum-derived resin with superior chemical inertness and recyclability dominates temperature-sensitive supply chains. REACH registration requirements in Europe are accelerating migration toward bio-based additives among French beverage distributors.
- Recycled Material:Post-consumer polypropylene flake integration is climbing as EFSA clears food-contact applications for specific recycling streams.
- Plywood:Engineered wood panels with ISPM-15 heat treatment certification serve custom export crating for heavy machinery.
- Steel:Galvanized or powder-coated metal construction addresses automotive and aerospace component handling requiring load ratings above 500 kg.
High-Density Polyethylene leads on scale; Recycled Material is gaining share fastest.
Usage Type:
Cycle intensity and handling automation requirements dictate structural reinforcement specifications.
- Transport:Dynamic load-rated containers with corner posts and base runners withstand forklift impacts and conveyor transitions across multi-modal networks.
- Storage:Static load-optimized designs with nesting features maximize warehouse cube utilization in automated pallet racking systems.
- Display:Retail-ready crates with branding surfaces and easy-open access panels serve direct-to-shelf replenishment in European grocery formats.
- Export:ISPM-15 compliant wooden crating or collapsible plastic systems with customs-sealable latches address international phytosanitary requirements.
Transport leads on scale; Display shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr logistics corridor anchors crate demand through automotive and food distribution networks requiring standardized container fleets. Pooled crate programs concentrate procurement among specialized operators. Regulatory pressure on packaging reuse reshapes capital allocation across supply chains.
United States
California Central Valley agricultural producers drive plastic crate adoption for fresh produce handling and state organic waste diversion compliance. The EPA regulates material recovery under solid waste frameworks. Midwest grocery distribution networks standardize on returnable container pooling to minimize capital lockup.
Germany
Beverage distributors and automotive parts handlers dominate reusable crate fleet deployment across the Rhine-Ruhr corridor. REACH chemical registration requirements restrict certain plasticizers in food-contact applications. Bavarian molding operations serve pan-European beverage crate contracts with standardized ventilated designs.
Netherlands
Retail cooperatives consolidate procurement through pooled crate programs serving dense grocery distribution networks. The EU Green Deal's packaging reuse targets compress single-use corrugated demand. Rotterdam port logistics operators integrate returnable containers into multi-modal freight corridors.
India
Fragmented horticulture logistics in Maharashtra and Karnataka present expansion opportunities for rental crate networks serving organized retail growth. FSSAI food safety standards shape container hygiene requirements for fresh produce handling. Cold chain infrastructure gaps limit penetration in secondary cities.
Belgium
Biologics manufacturers pilot sensor-integrated crates for pharmaceutical cold chain distribution with embedded temperature loggers. EMA guidelines on good distribution practice influence container validation requirements. Antwerp logistics clusters serve gene therapy shipments requiring shipment-level compliance documentation.
Crates Market Competitive Environment
Capacity expansion dominates the current landscape as injection molders scale automated lines to capture EU reuse mandate volumes. The vendor base organizes into three tiers: multinational pooling operators with wash-and-return infrastructure, regional molding specialists serving captive fleet contracts, and timber crate fabricators retaining custom export niches. Strategic archetypes include asset-light pooling platforms, vertically integrated compounder-molders, and washing service specialists. M&A activity concentrates among pooling networks acquiring regional washing facilities, while technology licensing agreements spread RFID tracking capabilities.
Among European-based pooling operators, Schoeller Allibert and Brambles occupy positions exemplifying the asset-heavy infrastructure archetype, with CHEP's pooled network representing the scale-driven model. IFCO Systems sits within the service-layer specialization tier, extending beyond hardware into logistics software and fleet tracking. These three companies anchor the competitive structure through contrasting approaches to capital deployment and customer relationships.
| Leading Market Players |
|---|
| Schoeller Allibert |
| IFCO Systems |
| Brambles (CHEP) |
| Orbis Corporation |
| Rehrig Pacific Company |
| Myers Industries |
| Menasha Corporation |
| Craemer Group |
| DS Smith |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up pooling specialists dominate the European crate landscape, concentrating washing infrastructure ownership across Germany and the Netherlands while enforcing disciplined subscription pricing that transfers asset-management risk from distributors to specialized operators.
Pricing Analysis
Polypropylene resin pass-through dominates crate pricing, with contract structures indexing to petrochemical benchmarks on quarterly resets. Three-tier pricing structure across premium ventilated produce crates, standard beverage containers, and economy-grade storage bins separates ISO 8611-certified fleets from uncertified alternatives. Pricing pressure stems from Baltic softwood lumber volatility in custom export crating, compressing margins for wooden crate fabricators serving California agricultural exporters. Logistics operators show lowest price sensitivity due to capital-avoidance benefits of pooling subscriptions, whereas independent fresh produce handlers remain most price-sensitive.
Supply Chain Analysis
High-Density Polyethylene resin supply rests on petrochemical complexes in Germany, Belgium, and the Netherlands, with compounders drawing from naphtha crackers along the Antwerp-Rotterdam-Rhine-Ruhr corridor. Injection molding equipment, automated washing lines, and RFID tracking hardware constitute critical component dependencies. Supply chain risk centers on REACH chemical registration timelines restricting plasticizer formulations for food-contact applications. Distribution runs through CHEP and IFCO pooled fleet networks, with regional molders serving captive contracts for brewers and automotive parts handlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
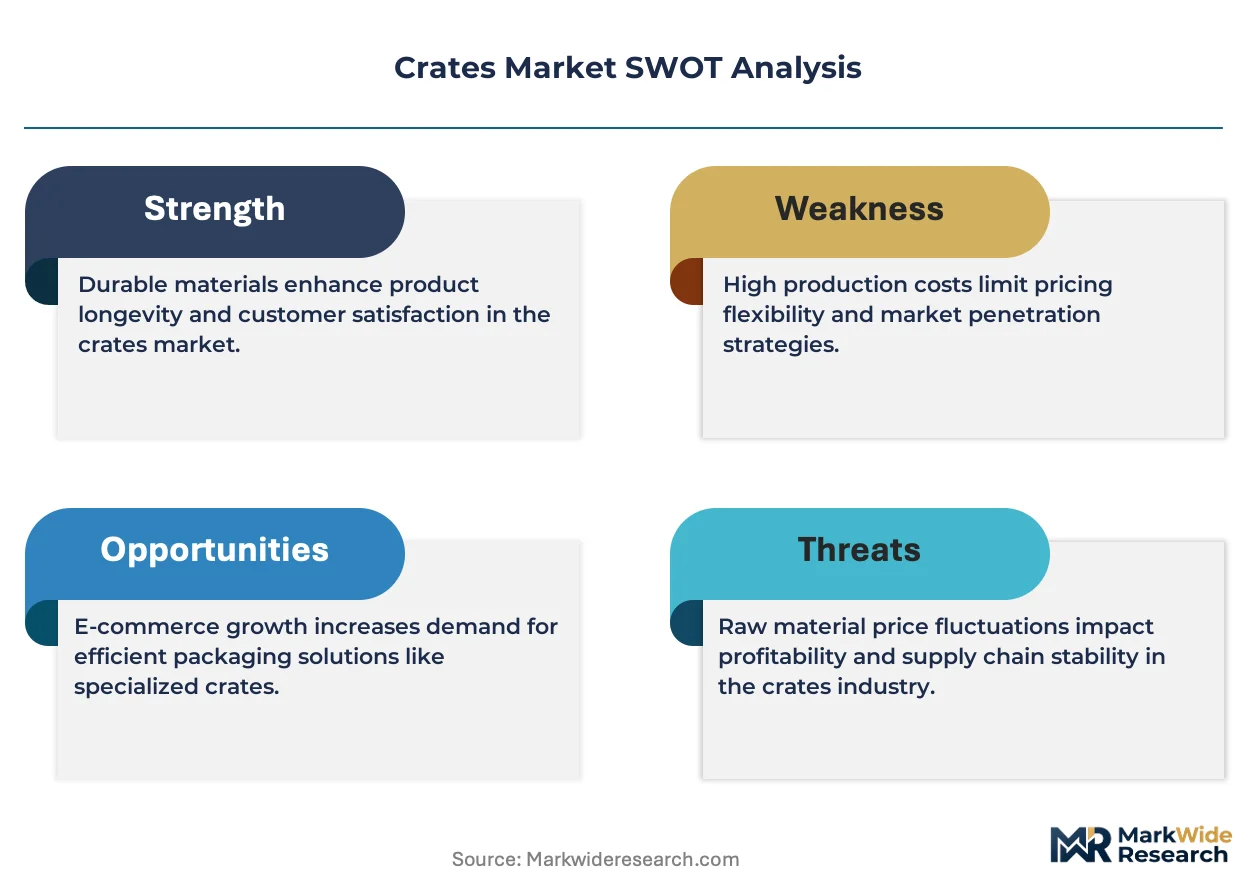
The crates market reads as a late-cycle quality story, with EU Green Deal reuse mandates forcing distributors toward premium-grade returnable container systems and away from single-use corrugated alternatives.
For Market Incumbents: Deepen backward integration into polypropylene compounding to secure feedstock cost stability against crude oil volatility. Expand automated washing capacity in the Rhine-Ruhr corridor to capture German beverage distributor consolidation. Invest in RFID-embedded tracking infrastructure before REACH compliance timelines compress product development cycles for smaller competitors. For New Entrants and Emerging Players: The mid-tier price gap between CHEP premium subscriptions and uncertified local washing services creates entry space for regional specialists. Target India's Maharashtra and Karnataka horticulture logistics, where cold chain underpenetration leaves organized retail expansion unserved by pooled crate networks. Lead with rental-model positioning that transfers capex burden from fragmented fresh produce handlers. For Investors and Strategic Acquirers: Pooling operators with pan-European washing infrastructure are the most active acquirer in this space, consolidating regional facilities to achieve route density economies. Long-term viability hinges on regulatory enforcement durability across EU member states. Watch FSSAI hygiene standard tightening in India as the inflection signal for emerging market rental network viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Secures polypropylene supply cost stability against petrochemical benchmark volatility for German molders. |
| Automated Washing Line Deployment | Enables HACCP-compliant crate fleet management at scale for pooled operators serving Dutch retail cooperatives. |
| RFID-Enabled Fleet Tracking Integration | Supports usage-based billing models and real-time asset visibility across California agricultural distribution networks. |
| REACH-Compliant Formulation Migration | Accelerates bio-based additive adoption among French beverage distributors facing compressed compliance timelines. |
| India Cold Chain Rental Network Buildout | Addresses fragmented horticulture logistics in Maharashtra and Karnataka for organized retail expansion. |
Study Parameters
Coverage spans Germany, the United States, the Netherlands, India, and Belgium, with primary inputs from each market combining interviews with pooling fleet managers, injection molding plant directors, grocery distribution procurement leads, and agricultural cooperative logistics officers alongside secondary validation through EU packaging regulation filings, EPA solid waste framework documents, customs trade data for polypropylene resin flows, and SEC disclosures from publicly listed container pooling operators. Bottom-up volume estimates triangulate against top-down market sizing across material type and end-use verticals.
Rate-of-change decomposition separates volume growth from price mix effects across the analysis window, with segmentation modeling across plastic, wooden, metal, and cardboard product types; Food and Beverage, Logistics, Retail, and Agriculture end users; High-Density Polyethylene, recycled material, plywood, and steel manufacturing inputs; and Transport, Storage, Display, and Export usage categories. CAGRs derive from trend extrapolation of pooled fleet penetration rates and regulatory mandate enforcement intensity, with petrochemical feedstock cost curves and washing infrastructure deployment schedules as industry-specific forecast inputs.
Caveats apply where EU Packaging and Packaging Waste Regulation enforcement delays, polypropylene resin price spikes, or India cold chain investment shortfalls could materially shift the outlook. A small set of named triggers—REACH chemical registration timeline compression, FSSAI hygiene standard evolution, and US Inflation Reduction Act clean logistics incentive uptake—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
MSW Bag Opener Market
Bags and Containers
Textile Bags Market
Bags and Containers
Low Melt Point Bags Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Bag-In-Tube Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
Bags and Containers Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Plastic Bags and Sacks Market