
 Tumour Ablation Devices Market | 2026-2036
Tumour Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Tumour Ablation Devices Market Analysis
Interventional radiologist workforce shortages in rural health systems is redrawing competitive dynamics across the tumour ablation landscape. Medtronic leverages its integrated surgical navigation platforms to sustain hospital loyalty in complex oncology procedures. Boston Scientific Corporation anchors its position through deep specialization in radiofrequency electrode arrays. Stryker Corporation dominates the cryoablation segment with proprietary gas-based cooling systems that occupy a defensible technology tier.
Tumour ablation devices deliver targeted thermal, cryogenic, or electrical energy to destroy malignant tissue through percutaneous, laparoscopic, or open surgical approaches, typically operating at temperatures between minus 40 and 100 degrees Celsius depending on modality. These systems serve the primary commercial purpose of offering minimally invasive alternatives to resection for patients with unresectable or poor-surgical-risk tumours. Radiofrequency ablation maintains the largest installed base among product types, though microwave platforms are capturing faster procedural growth due to larger ablation zones and reduced heat-sink effects near vasculature. Heat-based technology leads current revenue pools while cold-based systems command premium pricing in renal and prostate applications where tissue preservation matters.
The FDA regulates these devices as Class II medical devices requiring 510(k) clearance, while the EU Medical Device Regulation mandates notified body conformity assessment for active therapeutic devices with higher clinical evidence thresholds. Siemens Healthineers navigates this framework by embedding ablation planning within its imaging ecosystems, reducing regulatory friction through pre-validated software-hardware combinations. Stakeholders must monitor how CMS reimbursement determinations for percutaneous tumour ablation in lung and bone metastases reshape site-of-care economics and device procurement priorities.
Market Dynamics
Workforce scarcity among interventional radiologists is compressing procedural capacity across rural and community hospital networks, forcing device manufacturers to engineer systems operable by general surgeons and oncologists with abbreviated training protocols.
Growth Catalysts
- EU MDR streamlining:The Medical Device Regulation's consolidated conformity assessment pathways accelerate 510(k)-equivalent clearances for microwave ablation platforms, reducing time-to-market for European manufacturers.
- Japan's percutaneous liver reimbursement:METI-aligned coverage expansion for hepatocellular carcinoma ablation procedures under the national health insurance scheme drives installed base growth in Tokyo and Osaka hospital clusters.
- Thermal monitoring integration:Real-time MRI thermometry systems enable precision ablation margin control, expanding treatable patient populations previously excluded due to proximity to critical structures.
Market Restraints
- Helium supply concentration:Cryoablation system manufacturers depend on Qatar and Russia for refined helium feedstock, exposing production schedules to geopolitical supply disruptions and price volatility.
- Heat-sink limitations:Radiofrequency ablation suffers from incomplete necrosis within 5mm of large vessels exceeding 3mm diameter, restricting curative intent in perivascular hepatic and renal tumours.
- FDA 510(k) predicate drift:Substantial equivalence determinations for next-generation electrode arrays increasingly require supplemental clinical data, extending regulatory timelines beyond historical 90-day benchmarks.
Strategic Opportunities
- Brazil's underserved interior:ANVISA regulatory harmonization with FDA standards enables direct technology transfer to São Paulo and Belo Horizonte academic medical centers lacking interventional oncology infrastructure.
- Pediatric bone tumour applications:Limb-salvage cryoablation protocols for osteoid osteoma represent an unpenetrated segment with premium pricing tolerance and minimal competitive saturation.
- Artificial intelligence planning:Machine learning algorithms integrated into CT/MRI workstations automate ablation zone prediction, reducing procedural planning time and operator variability.
Industry Challenges
- Cross-training deficits:Community hospitals lack structured pathways to credential general surgeons in percutaneous probe placement, limiting device utilization despite capital investment.
- Interoperability fragmentation:Proprietary communication protocols between ablation generators and imaging systems force redundant capital expenditure during platform upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumour Ablation Devices Market |
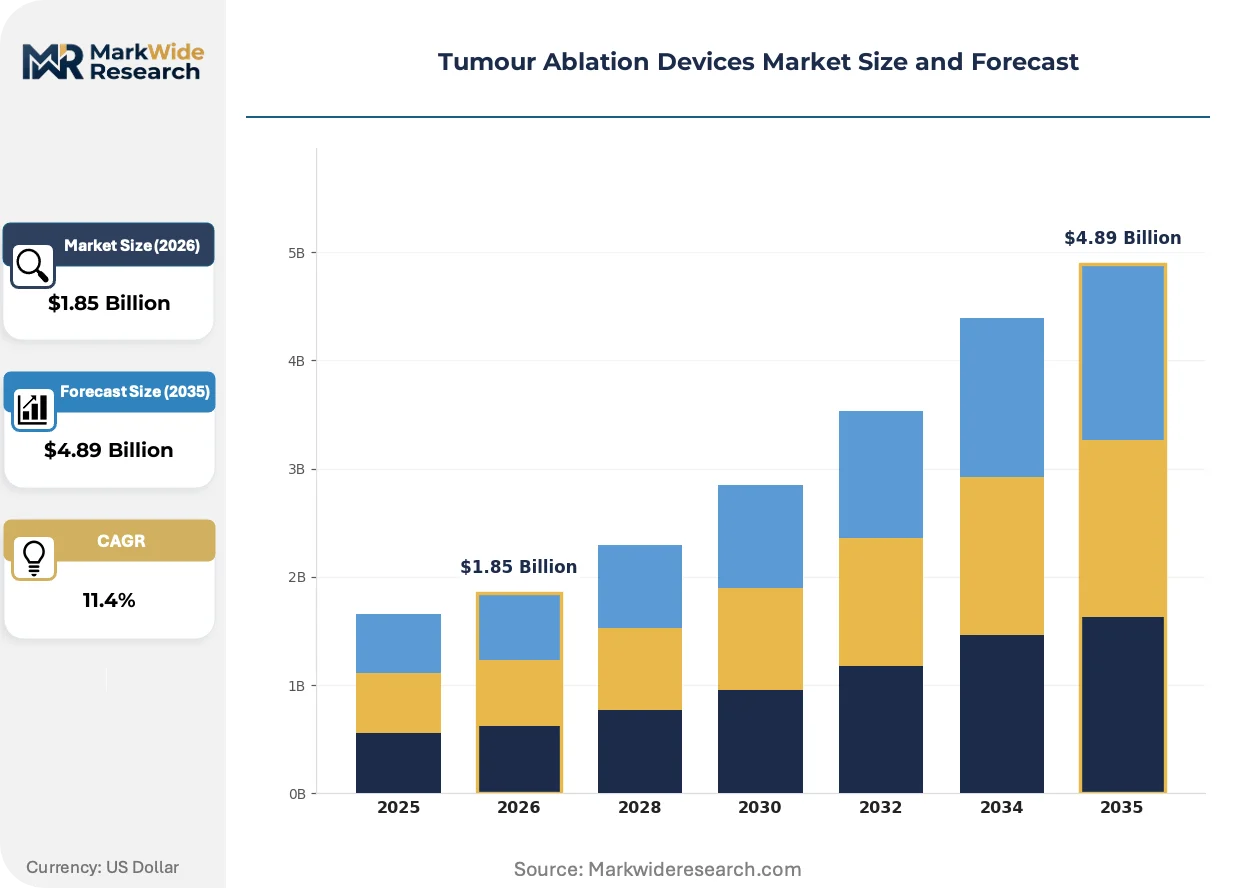
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiofrequency, Microwave, Cryoablation, Laser End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Specialty Clinics Application: Liver Cancer, Kidney Cancer, Lung Cancer, Bone Tumors Technology: Heat-based, Cold-based, Laser-based, Electrical-based |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific Corporation, Stryker Corporation, AngioDynamics, Olympus Corporation, EDAP-TMS, Merit Medical Systems, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumour Ablation Devices Market Emerging Trajectories
Energy delivery modalities and procedural planning architectures are undergoing simultaneous transformation, with computational tools and alternative thermal physics reshaping clinical workflows and capital allocation priorities.
Microwave ablation systems operating at 915 MHz and 2.45 GHz frequencies generate larger spherical ablation zones with reduced susceptibility to perfusion-mediated cooling effects. Academic medical centers in Germany and Japan are prioritizing these platforms for hepatic and pulmonary applications. Radiofrequency ablation's historical dominance in procedural volume is displacing as microwave technology captures premium positioning in complex lesion geometries.
The EU Medical Device Regulation's enhanced clinical evidence requirements for active therapeutic devices have elevated post-market surveillance obligations. Manufacturers must now maintain periodic safety update reports and vigilance databases across notified body jurisdictions. Microwave ablation platforms with predicate device lineages face compressed regulatory friction compared to novel cryogenic or irreversible electroporation systems.
Hospital procurement committees are unbundling capital equipment acquisition from disposable electrode contracts, forcing generator manufacturers to compete on per-procedure economics rather than upfront hardware pricing. This purchasing pattern shift concentrates negotiating leverage within integrated delivery networks managing multiple sites. The transformation is most pronounced in United States metropolitan markets where health system consolidation has reduced independent community hospital purchasing autonomy.
Tumour Ablation Devices Market Segmentation
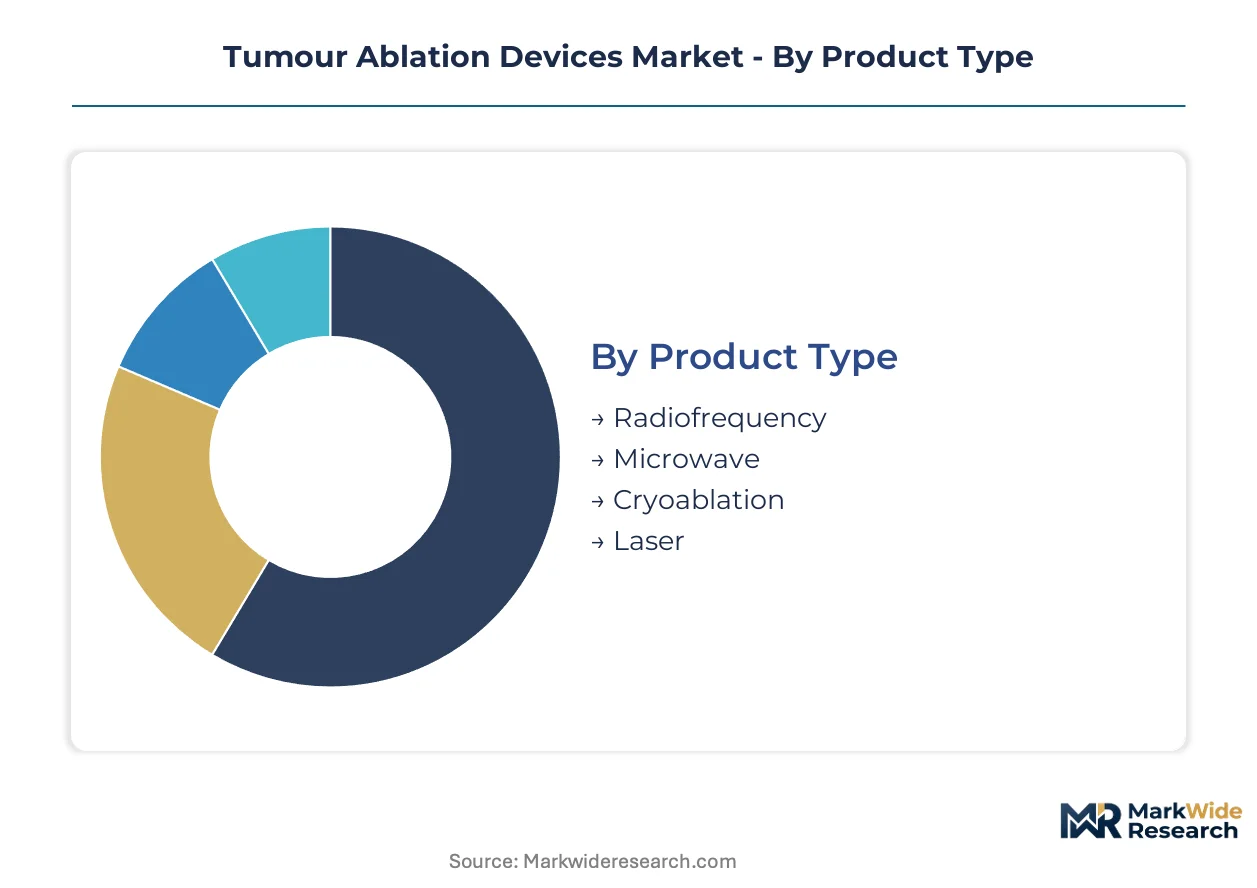
Segmentation in tumour ablation devices determines reimbursement pathways, regulatory clearance requirements, and site-of-care economics. Product type dictates capital intensity and disposable revenue mix. End user concentration shapes training protocols and sales force deployment priorities.
Product Type:
FDA 510(k) clearance timelines vary significantly across energy modalities, with microwave platforms leveraging predicate device lineages for faster market entry than novel cryogenic systems.
- Radiofrequency:Electrode arrays operating at 460-480 kHz deliver resistive heating through ionic agitation. Demand concentrates in United States community hospitals where interventional radiologist training infrastructure is deepest and CMS reimbursement for hepatic ablation is established.
- Microwave:Electromagnetic energy at 915 MHz and 2.45 GHz generates larger ablation zones with reduced heat-sink effects near vasculature. German and Japanese academic medical centers are prioritizing these systems for perivascular hepatic and pulmonary lesions where radiofrequency yields incomplete necrosis.
- Cryoablation:Pressurized argon-helium systems achieve temperatures below minus 40 degrees Celsius through Joule-Thomson expansion. Renal and prostate applications in tertiary centers command premium pricing where tissue preservation drives clinical decision-making.
- Laser:Nd:YAG and diode laser platforms deliver precise thermal damage through fiberoptic probes. Interstitial applications in neuro-oncology and spinal metastases represent niche deployment.
Radiofrequency handles the majority of throughput; microwave is the fastest mover on share.
End User:
Procurement authority is shifting toward integrated delivery networks that negotiate enterprise-wide disposable contracts separate from capital equipment purchases.
- Hospitals:Tertiary academic medical centers maintain the deepest interventional oncology departments with 24/7 procedural capacity. United States metropolitan health systems are expanding dedicated interventional radiology suites to capture oncology service line revenue.
- Outpatient Clinics:Freestanding interventional radiology practices in Germany and Japan perform percutaneous ablation under local anesthesia with same-day discharge. METI-aligned reimbursement in Osaka and Tokyo clusters supports this site-of-care migration.
- Ambulatory Surgical Centers:Medicare ASC payment rates for percutaneous tumour ablation lag hospital outpatient department reimbursement, limiting penetration despite lower overhead structures.
- Specialty Clinics:Urology-focused practices in United States suburban markets deploy cryoablation for prostate lesions outside hospital capital budgeting cycles.
Hospitals retain the dominant installed base; outpatient clinics are expanding most quickly as reimbursement shifts enable site-of-care migration.
Application:
Tumour location determines imaging guidance requirements, ablation zone geometry constraints, and proximity-to-vessel limitations that dictate modality selection.
- Liver Cancer:Hepatocellular carcinoma and colorectal metastases represent the largest procedural volume globally. Japan's national health insurance expansion for percutaneous liver ablation under METI direction concentrates demand in Tokyo-Osaka hospital clusters.
- Kidney Cancer:Partial nephrectomy alternatives in elderly comorbid populations favor cryoablation where renal function preservation is paramount. Cleveland Clinic and Mayo Clinic protocols influence community hospital adoption patterns.
- Lung Cancer:Ground-glass opacity lesions and oligometastatic disease drive microwave adoption for larger ablation zones in pneumonectomy-ineligible patients. Heat-sink effects from pulmonary vasculature limit radiofrequency efficacy.
- Bone Tumors:Osteoid osteoma and painful metastases represent underserved pediatric and palliative populations. Limb-salvage cryoablation protocols carry premium pricing tolerance with minimal competitive saturation.
Liver cancer commands the dominant procedure count; lung cancer applications are climbing the fastest as screening programs expand detectable early-stage populations.
Technology:
Energy delivery physics determines regulatory classification, clinical evidence requirements, and competitive moat durability across thermal and non-thermal modalities.
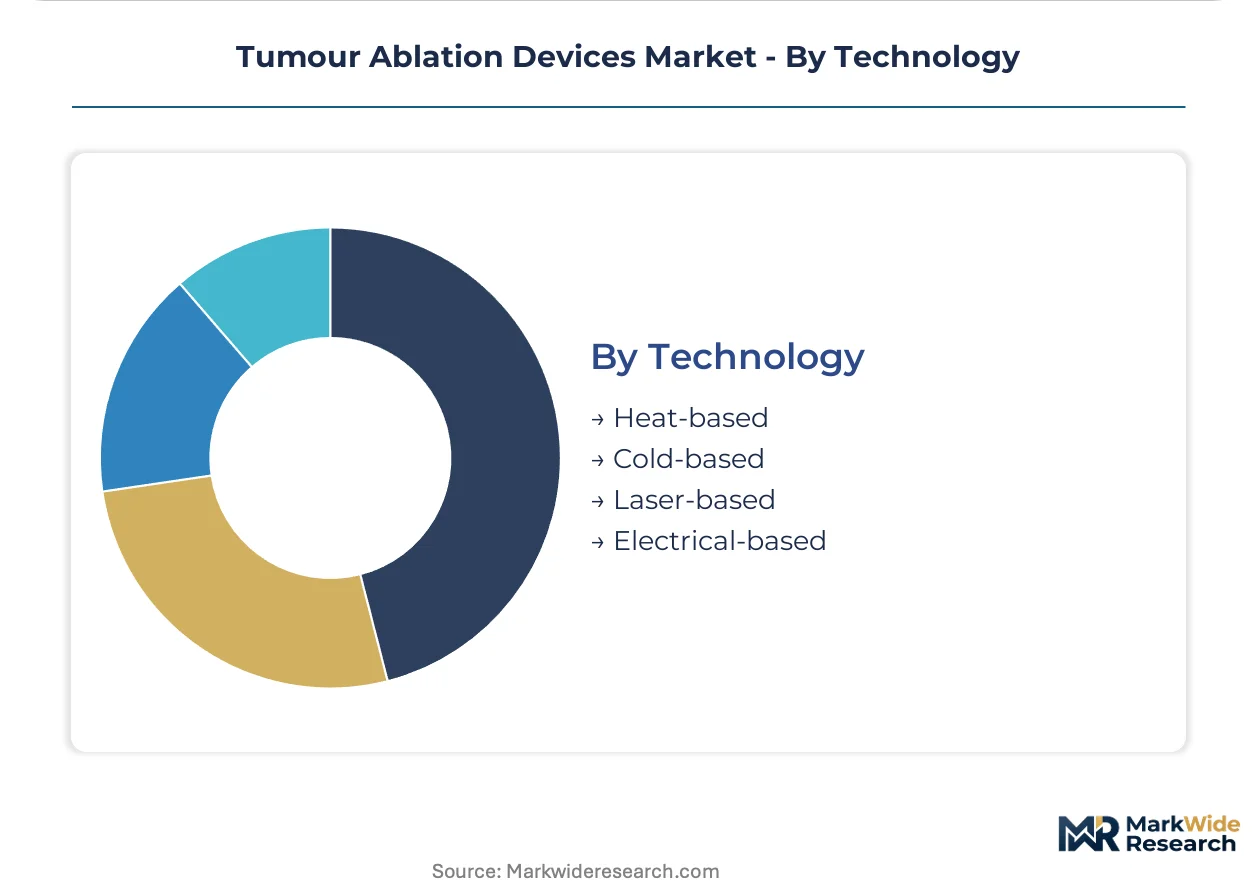
- Heat-based:Radiofrequency and microwave platforms constitute the revenue core with established predicate device pathways for FDA clearance. Temperature monitoring integration with MRI thermometry is expanding treatable anatomies.
- Cold-based:Argon-helium systems occupy a defensible technology tier with proprietary gas handling and probe insulation IP. Qatar and Russia helium supply concentration exposes production schedules to geopolitical disruption.
- Laser-based:Interstitial laser thermotherapy achieves precise spatial control for lesions adjacent to critical neural structures. Neurosurgical applications in German academic centers represent concentrated demand.
- Electrical-based:Irreversible electroporation delivers non-thermal cell death through nanopore formation in cell membranes. EU MDR clinical evidence requirements for novel active therapeutic devices extend regulatory timelines beyond microwave predicates.
Heat-based technology dominates current revenue pools; electrical-based systems hold the steepest expansion trajectory as clinical evidence accumulates for pancreatic and prostate applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in tumour ablation concentrates in Japanese and German hospital clusters where reimbursement density supports premium platform acquisition, while Brazilian and Indian markets operate on stripped-down generator economics that compress manufacturer margins.
United States
Metropolitan health systems in Houston and New York are consolidating interventional radiology service lines to capture oncology referral networks. FDA 510(k) clearance pathways for microwave platforms remain the regulatory benchmark for predicate device strategies. Cleveland Clinic and Mayo Clinic protocols influence cryoablation adoption patterns across community hospital networks.
Germany
Academic medical centers in Munich and Heidelberg prioritize microwave systems for perivascular hepatic lesions where radiofrequency heat-sink effects limit efficacy. EU MDR conformity assessment through notified body TÜV SÜD accelerates market entry for predicate-lineage devices. The Bavarian hospital cluster represents the densest installed base of MRI-thermometry-integrated platforms in Europe.
Japan
Tokyo and Osaka hospital networks drive percutaneous liver ablation volume under METI-aligned national health insurance expansion for hepatocellular carcinoma. PMDA consultation pathways for active therapeutic devices run parallel to FDA timelines, enabling synchronized global launches. Kansai region academic centers are piloting artificial intelligence planning integration with CT workstations.
Brazil
São Paulo academic medical centers are building interventional oncology capacity through ANVISA regulatory harmonization with FDA standards. The country's national health regulator has streamlined 510(k)-equivalent clearance timelines for microwave ablation platforms. Belo Horizonte hospital clusters represent the primary demand concentration outside the São Paulo metro.
China
Beijing and Shanghai tertiary hospitals are expanding microwave ablation departments for lung cancer applications as screening programs expand detectable early-stage populations. NMPA registration requirements for Class III active therapeutic devices mandate domestic clinical trials that extend market entry timelines. Yangtze River Delta hospital procurement committees are unbundling capital equipment from disposable electrode contracts.
Tumour Ablation Devices Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the tumour ablation landscape, with integrated imaging-surgical platforms commanding premium positioning while regional manufacturers compete on per-procedure generator economics. The vendor base separates into three strategic tiers: diversified medical technology conglomerates with navigation ecosystem leverage, interventional oncology specialists with deep electrode array IP, and regional champions with localized regulatory clearance advantages. Consolidation pressure is accelerating through health system procurement centralization and cross-border technology licensing arrangements.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson occupy positions anchored by surgical navigation platform integration that sustains hospital loyalty in complex oncology procedures. Boston Scientific Corporation exemplifies the interventional specialist archetype through concentrated expertise in radiofrequency electrode arrays. Stryker Corporation represents the cryoablation-focused technology tier with proprietary gas-based cooling system positioning. Siemens Healthineers sits within the imaging-integrated planning segment, embedding ablation workflows within CT and MRI ecosystems to reduce regulatory friction through pre-validated software-hardware combinations.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Stryker Corporation |
| AngioDynamics |
| Olympus Corporation |
| EDAP-TMS |
| Merit Medical Systems |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance tiers gate both supplier qualification and price differentiation in tumour ablation, with predicate-device lineages commanding premium positioning while novel modalities face compressed margins through extended regulatory timelines. Generator manufacturers navigate this bifurcation by unbundling capital equipment from disposable contracts, shifting negotiating leverage toward integrated delivery networks that aggregate procurement across multiple sites.
Pricing Analysis
Configured-to-order microwave systems with MRI-thermometry integration command spreads exceeding standard radiofrequency platforms by substantial margins, reflecting customization premiums for real-time margin control. Three-tier pricing structure across premium, standard, and economy levels stratifies by ablation zone precision, electrode array complexity, and after-sales service bundling. Cost compression in entry-level radiofrequency generators is intensifying because regional manufacturers in China and India compete on per-procedure economics. Community hospital networks exhibit highest price sensitivity, while tertiary academic centers in Germany and Japan tolerate premium positioning for proprietary gas-handling cryoablation systems.
Supply Chain Analysis
Port congestion across Rotterdam and Hamburg trade lanes elevates inbound logistics costs for argon-helium cryogenic systems manufactured in the United States, compressing landed margins for European distributors. Component sourcing concentrates on Germany for precision gas-handling valves, Japan for fiberoptic laser delivery systems, and the United States for RF generator assemblies. Single-source vulnerability in refined helium feedstock from Qatar and Russia exposes production schedules to geopolitical disruption. Distribution runs through medical device distributors with GPO contracts, though direct-to-hospital procurement is accelerating in consolidated United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization within integrated delivery networks signals a cyclical recovery phase, with hospital capital expenditure normalization following pandemic-era deferrals driving generator replacement demand.
For Market Incumbents: Fortify installed base retention through backward integration into electrode array manufacturing, reducing per-procedure cost exposure to third-party disposable suppliers. Deepen MRI-thermometry software-hardware validation to preempt regulatory friction under EU MDR post-market surveillance obligations. Emerging microwave entrants with predicate-device advantages threaten radiofrequency dominance in hepatic applications. For New Entrants and Emerging Players: Anchor in Brazil's underserved interior where ANVISA-FDA harmonization enables technology transfer without domestic clinical trial requirements. Pediatric bone tumour cryoablation represents the most penetrable white-space segment, with minimal competitive saturation and premium pricing tolerance. Pursue academic medical center partnerships in São Paulo and Belo Horizonte to establish clinical evidence generation pathways. For Investors and Strategic Acquirers: EU MDR's enhanced clinical evidence requirements reshape the acquisition landscape toward predicate-lineage microwave platforms with compressed regulatory friction versus novel electrical-based modalities. Long-term viability favors interventional oncology specialists with deep electrode IP over diversified conglomerates vulnerable to imaging ecosystem disruption. Monitor CMS reimbursement determinations for lung and bone metastases as the critical inflection signal for site-of-care economics and device procurement priorities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate-device lineages accelerate microwave platform clearances versus novel cryogenic systems. |
| CE Marking Pathway | TÜV SÜD conformity assessment enables synchronized EU launches for predicate-lineage devices. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic protocols influence cryoablation adoption across community networks. |
| Software Companion Development | AI planning integration with CT workstations reduces procedural variability and operator training burden. |
| Reimbursement Strategy | METI-aligned coverage expansion in Tokyo-Osaka clusters drives percutaneous liver ablation volume. |
Methodological Framework
A standing panel of interventional radiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, PMDA consultation pathway records, CMS Medicare reimbursement databases, and EU MDR notified body assessment reports. Bottom-up triangulation across generator shipment data and top-down reconciliation against health system capital expenditure disclosures anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling spanning energy modality, ablation zone geometry, end-user site-of-care tier, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to reimbursement rate changes and technology substitution patterns between radiofrequency and microwave platforms. Forecast inputs incorporated helium supply concentration risk and interventional radiologist workforce scarcity metrics.
Material uncertainties — reimbursement reversals for percutaneous lung ablation, helium supply disruptions from Qatar or Russia, and AI planning algorithm regulatory classification shifts — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Aerosol Drug Delivery Devices Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
Global Artificial Organ Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Vaginal Pessary Market
Medical Devices
Hearing Aids Market
Medical Devices
Transilluminators Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Respiratory Devices Market