
 Global Joint Pain Injections Market | 2026-2036
Global Joint Pain Injections Market Size, Share, and Industry Trends Forecast 2026-2036
Global Joint Pain Injections Market Foresight
CE marking under the EU MDR is collapsing the supplier base for hyaluronic acid viscosupplements, forcing smaller manufacturers to exit or consolidate. Pfizer leverages its biologics manufacturing scale to sustain corticosteroid supply across European hospital networks. Sanofi anchors its position through in-house production of active pharmaceutical ingredients for intra-articular therapies. Zimmer Biomet competes by integrating injection delivery systems with its orthopedic implant portfolios.
Joint pain injections comprise sterile formulations of corticosteroids, hyaluronic acid derivatives, or autologous biologicals delivered directly into synovial cavities or peri-articular tissues to modulate inflammation, restore viscoelasticity, or promote tissue repair. Manufacturing requires aseptic fill-finish capability, endotoxin control below 0.5 EU/mL, and particle size specifications for suspensions. Hyaluronic acid products command premium positioning due to longer pain-relief duration and repeat-injection economics. Corticosteroids dominate procedural volume in emergency and acute care settings where rapid anti-inflammatory action determines product selection. Ultrasound-guided delivery methods are capturing share from blind intra-articular techniques as reimbursement codes increasingly mandate image confirmation.
The FDA governs sterile injectable approvals through 21 CFR Part 211 cGMP requirements, while the EMA enforces MDR technical documentation and clinical evidence standards for viscosupplement reclassifications. Japan's PMDA maintains distinct pharmacovigilance reporting for biological joint therapies that shapes trial design for multinational sponsors. Stakeholders must monitor evolving reimbursement thresholds for platelet-rich plasma as health technology assessment bodies in Germany, France, and England issue divergent value determinations.
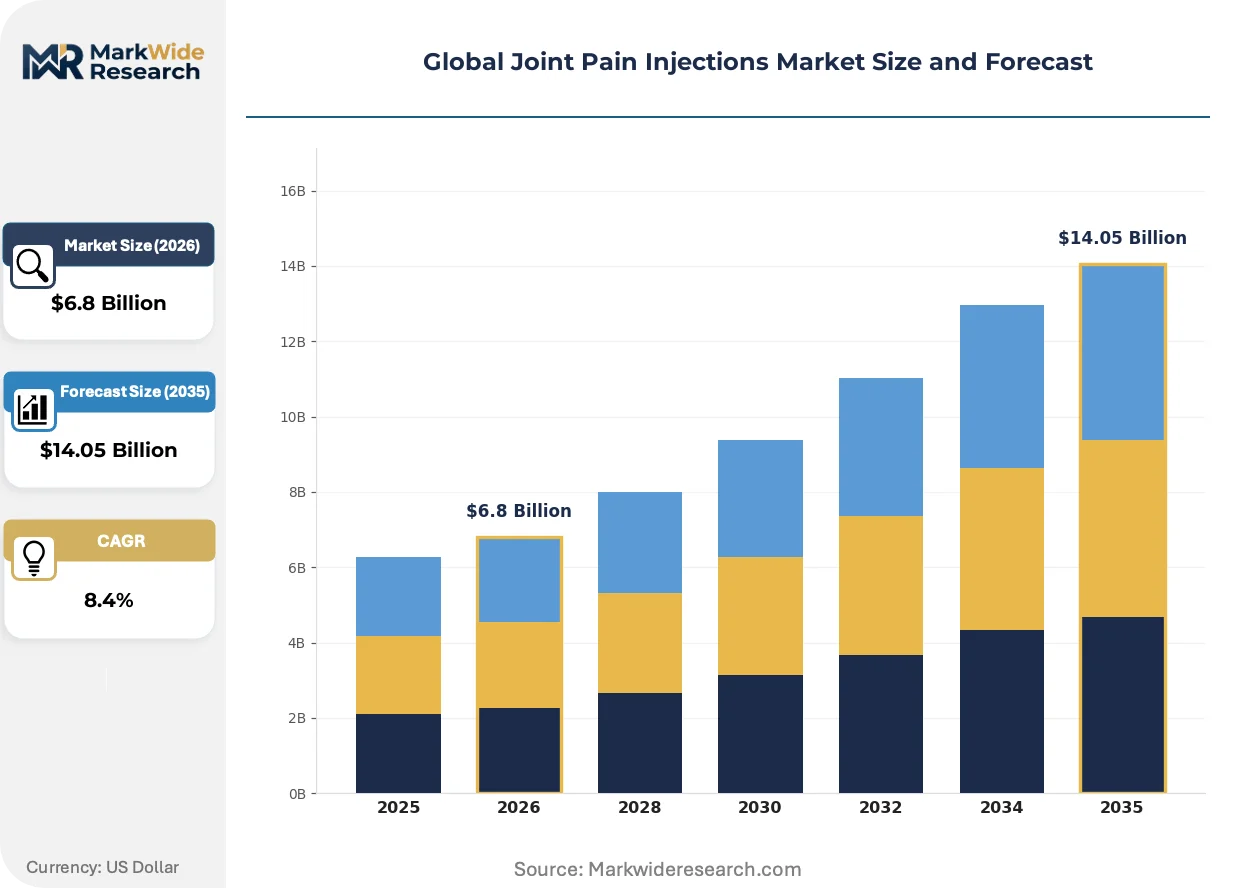
Market Dynamics
Ultrasound-guided injection protocols are compressing the competitive window for blind intra-articular techniques, forcing device manufacturers to bundle imaging compatibility into delivery system designs or face reimbursement exclusion.
Growth Catalysts
- Aging Demographics in Germany, Japan, and the United States:Orthopedic procedure volumes in these markets intersect with expanded private and public coverage for repeat hyaluronic acid injections, creating sustained demand pull for viscosupplement manufacturers.
- EU MDR Recertification Timeline:The compressed approval cycles for hyaluronic acid devices favor incumbent suppliers with established clinical evidence packages, accelerating consolidation among manufacturers with pre-existing technical documentation.
- Sports Medicine Facility Expansion:Specialized clinics across North America and Western Europe are standardizing ultrasound-guided protocols, driving equipment and consumable pull-through for compatible injection systems.
Market Restraints
- Active Pharmaceutical Ingredient Supply Concentration:Corticosteroid API production clusters in a limited number of European and Asian manufacturing sites, exposing finished dose suppliers to single-source disruption risks and input cost volatility.
- Reimbursement Divergence for Platelet-Rich Plasma:Health technology assessment bodies in Germany, France, and England issue conflicting value determinations, fragmenting market access and constraining volume growth for autologous biological therapies.
- Technical Limitation of Repeat Corticosteroid Exposure:Chondrotoxicity concerns limit injection frequency to three to four procedures annually per joint, capping per-patient revenue potential and driving therapy switching to hyaluronic acid alternatives.
Strategic Opportunities
- Underpenetrated Outpatient Surgery Centers in the United States:Ambulatory facilities in secondary metropolitan markets lack dedicated musculoskeletal injection protocols, representing white space for turnkey ultrasound-guided program implementation.
- Technology Convergence of Biologics Manufacturing and Orthopedic Distribution:Integration of aseptic fill-finish capability with implant logistics networks enables same-day autologous therapy preparation, compressing treatment timelines for sports medicine patients.
- Japan PMDA Pharmacovigilance Pathway:Distinct biological therapy reporting requirements create a regulatory moat for sponsors with established Japanese trial infrastructure, limiting competition from late-entering multinational manufacturers.
Industry Challenges
- Aseptic Manufacturing Talent Scarcity:Qualified personnel for endotoxin-controlled fill-finish operations command premium compensation, constraining capacity expansion timelines for mid-scale injectable manufacturers.
- EU MDR Technical Documentation Burden:Viscosupplement reclassification demands extensive clinical evidence generation, extending certification timelines and freezing product portfolio refreshes for resource-constrained suppliers.
- Legacy Blind Injection Technique Integration:Established physician training pathways resist ultrasound-guided protocol adoption, requiring sustained education investment to shift procedural behavior in mature markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Joint Pain Injections Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Hyaluronic Acid, Platelet-Rich Plasma, Botulinum Toxin, Analgesics Application: Osteoarthritis, Rheumatoid Arthritis, Tendonitis, Bursitis, Ligament Injuries End User: Orthopedic Clinics, Pain Management Centers, Sports Medicine Facilities, Rehabilitation Centers, Ambulatory Surgical Centers Delivery Method: Intra-articular, Peri-articular, Soft Tissue Injection, Ultrasound-Guided Injection, Fluoroscopy-Guided Injection |
| Companies Covered | Pfizer, Sanofi, Zimmer Biomet, Bioventus, Anika Therapeutics, Ferring Pharmaceuticals, Pacira BioSciences, SEIKAGAKU CORPORATION, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Joint Pain Injections Market Shifts & Advancements
Delivery technology convergence with imaging modalities is restructuring competitive requirements, while regulatory recertification waves and shifting site-of-care preferences are redrawing commercial access pathways across major markets.
Hyaluronic acid derivative formulations with extended chain length and cross-linked architecture are decomposing the traditional volume-based pricing model for viscosupplements. Sports medicine clinics in Germany and the United States are adopting these premium formulations for knee osteoarthritis patients requiring longer intervals between injections. The structural consequence is a bifurcation between commodity hyaluronic acid suppliers and manufacturers with proprietary polymer chemistry capabilities.
CE marking under the EU MDR is collapsing the supplier base for hyaluronic acid viscosupplements by demanding clinical evidence standards previously reserved for higher-risk device categories. Smaller manufacturers without pre-existing MDR technical documentation are exiting or consolidating, concentrating supply among European and multinational firms with dedicated regulatory affairs infrastructure. The knee osteoarthritis segment is most affected, with product availability compressing in Southern and Eastern European markets where local suppliers previously dominated.
Buyer concentration among integrated delivery networks in the United States is unbundling after-sales service from injection device procurement, forcing manufacturers to compete on capital equipment cost rather than bundled training and support. Hospital systems in Texas, Florida, and California are consolidating orthopedic service lines under single procurement committees, standardizing on ultrasound-compatible platforms across multiple facilities. This pattern is most visible in Medicare Advantage–dominated markets where episode-based reimbursement incentivizes capital efficiency over premium feature sets.
Global Joint Pain Injections Market Segmentation
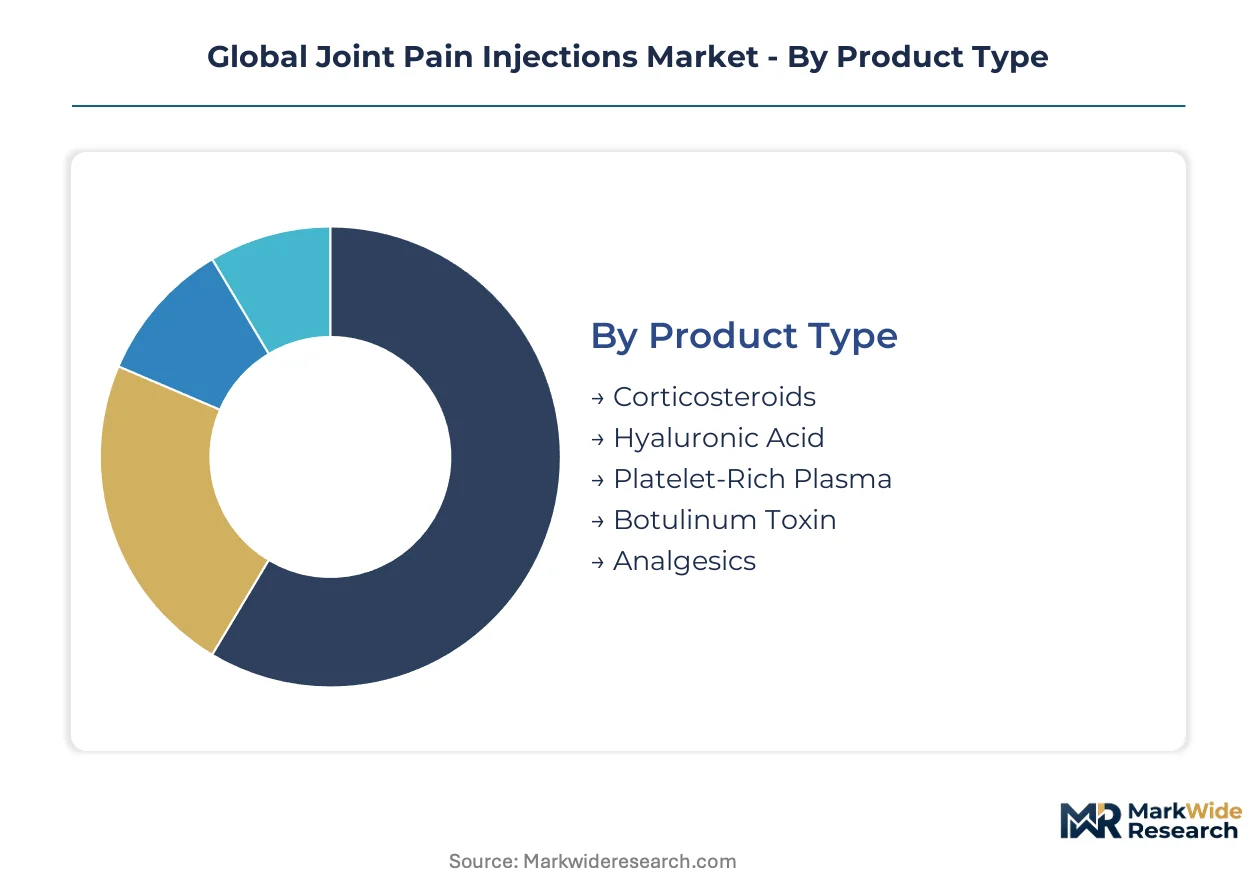
Joint pain injections flow through distinct channel configurations depending on formulation complexity and reimbursement pathways. Product type determines whether procurement occurs through hospital pharmacy formularies, specialty distributor networks, or direct-to-clinic biological preparation services.
Product Type:
Corticosteroids and hyaluronic acid derivatives dominate hospital and orthopedic clinic procurement through divergent margin structures and repeat-purchase economics.
- Hyaluronic Acid:Cross-linked polymer formulations command premium positioning in German and Japanese outpatient settings where extended dosing intervals justify higher per-procedure reimbursement. Sports medicine facilities in the United States are standardizing these viscosupplements for knee osteoarthritis patients requiring maintenance therapy without quarterly intervention.
- Corticosteroids:Methylprednisolone and triamcinolone suspensions concentrate in emergency department and acute care formularies where rapid anti-inflammatory onset drives selection. Supply contracts with European hospital networks favor manufacturers with captive API production and aseptic fill-finish certification under EU MDR standards.
- Platelet-Rich Plasma:Autologous preparation protocols restrict this segment to specialized orthopedic and sports medicine clinics with on-site centrifuge capability.
- Botulinum Toxin:Off-label intra-articular applications remain limited to academic medical centers with institutional review board oversight for experimental protocols.
- Analgesics:Lidocaine and bupivacaine formulations serve as procedural adjuncts rather than standalone therapies, bundled with corticosteroid injections in ambulatory settings.
By volume, corticosteroids lead. By growth pace, hyaluronic acid is ahead.
Application:
Clinical indication shapes site-of-care selection and determines whether therapy occurs in hospital-based settings or decentralized specialty clinics.
- Osteoarthritis:Knee and hip joint degeneration generates the majority of hyaluronic acid and corticosteroid demand, with German orthopedic clinics and Japanese pain management centers representing concentrated referral volumes for repeat injection protocols.
- Tendonitis:Rotator cuff and Achilles presentations are shifting toward ultrasound-guided delivery in United States sports medicine facilities, where image confirmation supports procedural reimbursement under Medicare Advantage episode-based models.
- Rheumatoid Arthritis:Systemic disease management through rheumatology practices maintains corticosteroid injection as bridge therapy during biologic agent initiation or flare management.
- Bursitis:Subacromial and trochanteric presentations concentrate in physical medicine and rehabilitation practices with blind peri-articular technique expertise.
- Ligament Injuries:Anterior cruciate and medial collateral damage in athletic populations drives platelet-rich plasma adoption despite divergent health technology assessment determinations across England, France, and Germany.
Osteoarthritis captures the largest patient volume. Tendonitis is climbing the fastest as ultrasound-guided protocols expand.
End User:
Facility type determines capital equipment requirements, staff training investment, and whether procurement occurs through group purchasing organizations or direct manufacturer relationships.
- Sports Medicine Facilities:Dedicated clinics in Texas, Florida, and California are standardizing ultrasound-compatible injection platforms across multi-site networks, unbundling device procurement from training service contracts to optimize capital efficiency under episode-based reimbursement.
- Orthopedic Clinics:German and Japanese private practice networks concentrate hyaluronic acid demand through established referral relationships with statutory and private insurers covering repeat viscosupplementation protocols.
- Pain Management Centers:United States ambulatory facilities in secondary metropolitan markets represent underpenetrated white space for turnkey ultrasound-guided program implementation.
- Rehabilitation Centers:Post-acute settings maintain corticosteroid and analgesic injection capability for flare management during functional restoration protocols.
- Ambulatory Surgical Centers:Medicare-certified facilities in the United States are expanding musculoskeletal service lines, though joint injection volume remains secondary to arthroscopic procedures.
Sports medicine facilities are gaining share fastest. Orthopedic clinics retain the largest procedure volume.
Delivery Method:
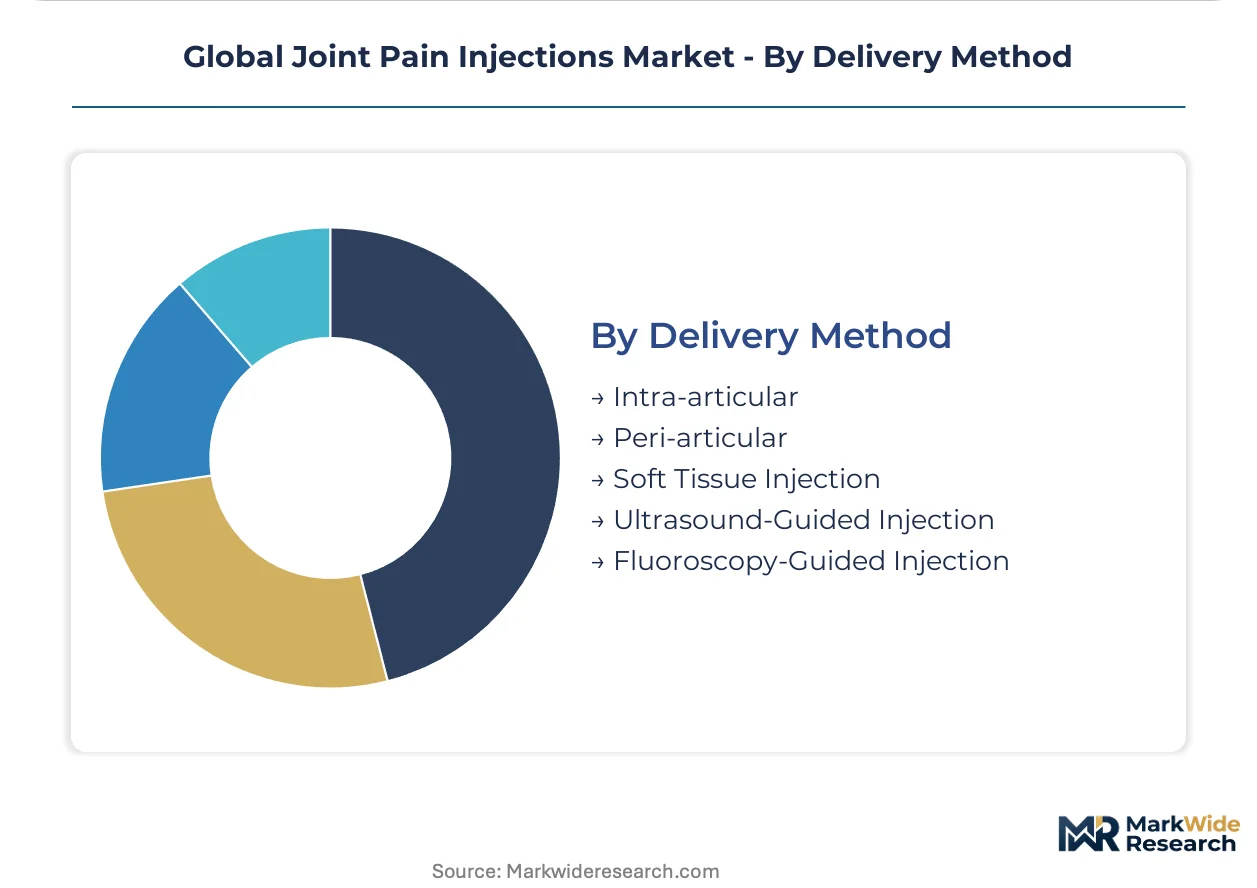
Technique selection increasingly determines reimbursement eligibility and shapes device manufacturer competitive requirements.
- Ultrasound-Guided Injection:Real-time image confirmation is capturing share from blind techniques as United States payers mandate documentation for hyaluronic acid and platelet-rich plasma coverage, compressing the competitive window for non-compatible delivery systems.
- Intra-articular:Direct synovial cavity delivery remains the standard for corticosteroid and hyaluronic acid administration, with accuracy rates improving through ultrasound adoption in German and Japanese academic medical centers.
- Peri-articular:Soft tissue and capsular targeting for bursitis and tendonitis presentations maintains volume in rehabilitation and primary care settings without imaging infrastructure.
- Soft Tissue Injection:Trigger point and ligamentous delivery concentrates in physical medicine practices with established manual technique expertise.
- Fluoroscopy-Guided Injection:Radiation-based confirmation is retreating to spine and sacroiliac applications, with orthopedic joint procedures shifting to ultrasound for cost and accessibility advantages.
Intra-articular techniques retain the highest procedure count. Ultrasound-guided delivery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate purchasing authority for hyaluronic acid and corticosteroid formulations, while divergent reimbursement systems fragment access for platelet-rich plasma therapies.
United States
Medicare Advantage episode-based reimbursement models incentivize ultrasound-guided injection adoption across Texas, Florida, and California health systems. FDA 21 CFR Part 211 cGMP requirements govern sterile fill-finish certification for domestic manufacturing. Integrated delivery networks in secondary metropolitan markets represent underpenetrated white space for turnkey musculoskeletal program implementation.
Germany
Statutory health insurance coverage for repeat viscosupplementation protocols sustains hyaluronic acid demand in private orthopedic practice networks. EU MDR technical documentation standards compress approval timelines for incumbent suppliers with established clinical evidence packages. The Bavarian medical technology cluster around Munich anchors manufacturing infrastructure for cross-linked polymer formulations.
Japan
Aging demographics intersect with expanded national health insurance coverage for knee osteoarthritis interventions, concentrating procedure volume in Kanto and Kansai region pain management centers. PMDA pharmacovigilance reporting requirements for biological joint therapies shape trial design and create regulatory moats for established sponsors. Tokyo-based academic medical centers standardize ultrasound-guided accuracy protocols for intra-articular delivery.
United Kingdom
NICE health technology assessment determinations restrict platelet-rich plasma reimbursement to specific tendonitis indications, fragmenting market access for autologous biological therapies. MHRA post-Brexit regulatory alignment with EU MDR standards maintains certification requirements for hyaluronic acid device suppliers. London and Southeast England sports medicine clinics drive adoption of imaging-compatible injection platforms.
Switzerland
Private insurance reimbursement for premium hyaluronic acid formulations sustains above-average per-procedure economics in Zurich and Geneva outpatient settings. Swissmedic medical device regulations enforce clinical evidence standards comparable to EU MDR requirements. The Basel pharmaceutical manufacturing corridor supports captive API production for intra-articular corticosteroid formulations.
Global Joint Pain Injections Market Competitive Landscape
Player mix skews toward multinational pharmaceutical conglomerates with captive biologics manufacturing infrastructure, tiered mid-scale orthopedic device specialists, and emerging regional hyaluronic acid suppliers confronting EU MDR consolidation pressure. Consolidation dynamics favor incumbents with pre-existing technical documentation and aseptic fill-finish certification. Strategic archetypes include vertically integrated API-to-device manufacturers, imaging-technology convergent platform developers, and autologous biological therapy service integrators. Dominant competitive moves encompass M&A-driven regulatory asset accumulation and backward integration into polymer chemistry capabilities.
Among multinational pharmaceutical conglomerates, Pfizer and Sanofi occupy positions exemplifying scale-driven supply security across European hospital networks, with the former leveraging biologics manufacturing infrastructure and the latter anchoring through in-house API production. Zimmer Biomet represents the orthopedic-device-convergence archetype, integrating injection delivery systems with implant portfolios. SEIKAGAKU CORPORATION and Anika Therapeutics sit within the specialized viscosupplement tier, their positioning reflecting proprietary hyaluronic acid formulation capabilities.
| Leading Market Players |
|---|
| Pfizer |
| Sanofi |
| Zimmer Biomet |
| Bioventus |
| Anika Therapeutics |
| Ferring Pharmaceuticals |
| Pacira BioSciences |
| SEIKAGAKU CORPORATION |
| Teva Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day API inventory buffers at European corticosteroid fill-finish facilities concentrate pricing leverage among manufacturers with captive triamcinolone production, compressing margin capture for dose-formulators dependent on spot market procurement.
Pricing Analysis
Cost-plus contracts with hyaluronic acid API indexation dominate viscosupplement procurement between German orthopedic networks and polymer suppliers. Three-tier pricing structure across premium cross-linked, standard linear, and economy unbranded formulations differentiates on chain length architecture and CE marking tier under EU MDR. Pricing pressure stems from integrated delivery network unbundling of device training from capital equipment sales in Texas and Florida health systems. Hospital procurement committees exhibit highest price sensitivity, while Japanese pain management centers demonstrate lowest sensitivity due to national health insurance reimbursement floors.
Supply Chain Analysis
Italy and Spain anchor aseptic fill-finish capacity for methylprednisolone suspensions, while South Korea and Japan concentrate fermentation-based hyaluronic acid API production. Finished dose manufacturing draws from European corticosteroid active pharmaceutical ingredients, Japanese sodium hyaluronate raw material, and United States-sourced injection device components. Single-source vulnerability concentrates in triamcinolone acetonide API with limited qualified European suppliers under EU MDR certification. Distribution runs through specialty pharmaceutical distributors to hospital pharmacy formularies and direct-to-clinic biological preparation services for autologous therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against oral NSAID-to-injection switching protocols and emerging gene therapy intra-articular candidates that threaten repeat-injection economics.
For Market Incumbents: Compound regulatory asset depth through EU MDR technical documentation accumulation for hyaluronic acid portfolios, eliminating smaller competitors unable to sustain clinical evidence generation costs. Backward integration into cross-linked polymer chemistry capabilities secures formulation differentiation against commodity viscosupplement suppliers. Prioritize ultrasound-compatible delivery system bundling to defend against imaging-technology convergent platform developers. For New Entrants and Emerging Players: Anchor in underpenetrated United States pain management centers in secondary metropolitan markets lacking turnkey ultrasound-guided program infrastructure. Target ambulatory surgical center musculoskeletal service line expansion as Medicare-certified facilities diversify beyond arthroscopic procedures. Pursue private-label hyaluronic acid supply contracts with German orthopedic clinic networks seeking alternatives to incumbent polymer suppliers facing EU MDR consolidation pressure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory moat play because EU MDR recertification timelines and Japan PMDA pharmacovigilance pathways create durable barriers against late-entering multinational manufacturers. Acquisition target archetype: mid-scale viscosupplement specialists with pre-existing MDR technical documentation and established Japanese trial infrastructure. Watch for health technology assessment convergence on platelet-rich plasma reimbursement across Germany, France, and England as volume inflection signal for autologous biological therapy segment.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Clinical evidence packages compress competitor entry windows for hyaluronic acid device recertification. |
| Ultrasound-Guided Delivery Platform Development | Imaging compatibility captures reimbursement codes mandating real-time intra-articular confirmation. |
| Captive API Manufacturing Scale-Up | In-house triamcinolone production insulates against European single-source supply disruption risks. |
| Japanese PMDA Trial Infrastructure Buildout | Established pharmacovigilance reporting creates regulatory moats against late-entering sponsors. |
| Outpatient Surgery Center Partnership Program | Turnkey musculoskeletal protocol implementation penetrates underdeveloped secondary metropolitan markets. |
Research Methodology
Operator-level perspectives from hospital pharmacy directors, orthopedic clinic procurement managers, sports medicine facility administrators, and GPO contracts specialists anchored the qualitative base for this analysis. Primary interview intelligence combined with secondary validation from FDA 21 CFR Part 211 filings, EMA MDR technical documentation databases, Japanese PMDA pharmacovigilance reports, and hospital procurement database extracts. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis triangulated market sizing across the forecast architecture.
Sensitivity analysis tested forecast robustness against reimbursement policy divergence scenarios and API supply disruption events throughout the projection horizon. Segmentation modeling spanned product type, application indication, end-user facility category, delivery method technique, and regional regulatory cluster dimensions. CAGRs derived from procedure volume trend extrapolation, pricing trajectory assessment, and share-shift dynamics between corticosteroid, hyaluronic acid, and autologous biological formulations. Forecast inputs incorporated EU MDR recertification timeline compression effects and ultrasound-guided protocol adoption curves.
Underlying assumptions cover stable reimbursement codes for hyaluronic acid viscosupplementation, with deviation risk concentrated in health technology assessment determinations for platelet-rich plasma and corticosteroid chondrotoxicity guideline revisions. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory recalibration and supply concentration events. Recalibration cycles align with material shifts in EU MDR enforcement patterns, Medicare Advantage episode-based reimbursement expansion, and biological therapy trial outcome disclosures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Monitors Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Vaginal Specula Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Dialysis Device and Concentrates Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Global Endotracheal Tubes Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
Ambulatory X-Ray Devices Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Medical Device Outsourcing Market