
 Aerosol Drug Delivery Devices Market | 2026-2036
Aerosol Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Aerosol Drug Delivery Devices Market Insights
Polypropylene is hardening its position as the preferred housing material for metered dose inhalers, replacing polycarbonate in cost-sensitive product lines. AstraZeneca leverages its integrated respiratory portfolio to sustain manufacturing scale across multiple device platforms. AptarGroup, Inc. anchors the supply chain for valve and actuator technologies that dominate North American and European sourcing. Koninklijke Philips N.V. competes through connected nebulizer systems that integrate with remote patient monitoring infrastructure.
Aerosol drug delivery devices generate therapeutic aerosols through mechanical, pneumatic, or propellant-driven mechanisms, with particle size distribution typically engineered between one and five micrometers to optimize lung deposition. These systems serve as the primary administration route for inhaled corticosteroids, bronchodilators, and emerging biologic therapies in chronic respiratory disease management. Metered dose inhalers occupy the largest volume position due to decades of clinical familiarity and compact form factor, while soft mist inhalers represent the fastest-expanding category as patients seek breath-actuated alternatives to coordinate-dependent devices. Nebulizers command premium positioning in acute and pediatric segments where passive inhalation is clinically necessary.
The FDA enforces strict bioequivalence standards for generic inhaled products under its draft guidance for orally inhaled and nasal drug products, directly shaping R&D investment and clinical trial design for device developers. EMA's MDR framework and the EU F-Gas Regulation constrain propellant selection and device sustainability claims, forcing reformulation of hydrofluoroalkane-based systems. The EPA monitors environmental release of residual propellants, adding compliance layers to end-of-life device management. Stakeholders must monitor evolving pharmacopeial standards for delivered dose uniformity and anticipate regulatory divergence between jurisdictions that will fragment approval pathways for next-generation connected inhalers.
Market Dynamics
The transition from hydrofluoroalkane propellants to low-global-warming-potential alternatives is forcing wholesale device redesign across metered dose inhaler portfolios, compressing formulation timelines and restructuring supplier relationships.
Growth Catalysts
- EMA MDR enforcement:Stricter clinical evidence requirements for inhaled generics are accelerating investment in advanced deposition modeling and in vitro testing capabilities among device developers.
- Home care migration:Pulmonology practices in the United States and Germany are expanding remote patient monitoring programs that bundle connected nebulizers with telehealth reimbursement codes.
- Biologic formulation compatibility:Soft mist inhaler platforms are gaining traction for monoclonal antibody delivery, opening indications beyond traditional small-molecule bronchodilators.
Market Restraints
- Propellant supply concentration:European manufacturing of HFA-152a and HFO-1234ze remains captive to a limited set of fluorochemical specialists, exposing device makers to input cost volatility.
- Dose uniformity verification:FDA bioequivalence standards for orally inhaled products require expensive cascade impaction studies that extend generic approval timelines by 18-24 months.
- Polymer substitution limits:Cyclic olefin polymers suitable for high-barrier drug contact surfaces command 3-4x polypropylene pricing, constraining cost engineering in mass-market devices.
Strategic Opportunities
- Pediatric unmet need:Breath-actuated dry powder inhalers with age-appropriate resistance profiles represent white space in Japan, where childhood asthma prevalence exceeds 10%.
- EU F-Gas quota trading:Early adopters of propellant-free mechanical aerosol systems can monetize avoided quota consumption through secondary market mechanisms.
- Pharmacy channel integration:Direct-to-patient subscription models for nebulizer consumables are penetrating Germany's pharmacy network, bypassing traditional hospital procurement.
Industry Challenges
- Formulation-device coupling:The FDA's weight on device-specific bioequivalence prevents interchangeability across inhaler platforms, fragmenting manufacturing scale.
- Aerosol physics talent scarcity:Computational fluid dynamics expertise for lung deposition modeling concentrates in academic centers, constraining commercial R&D expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerosol Drug Delivery Devices Market |
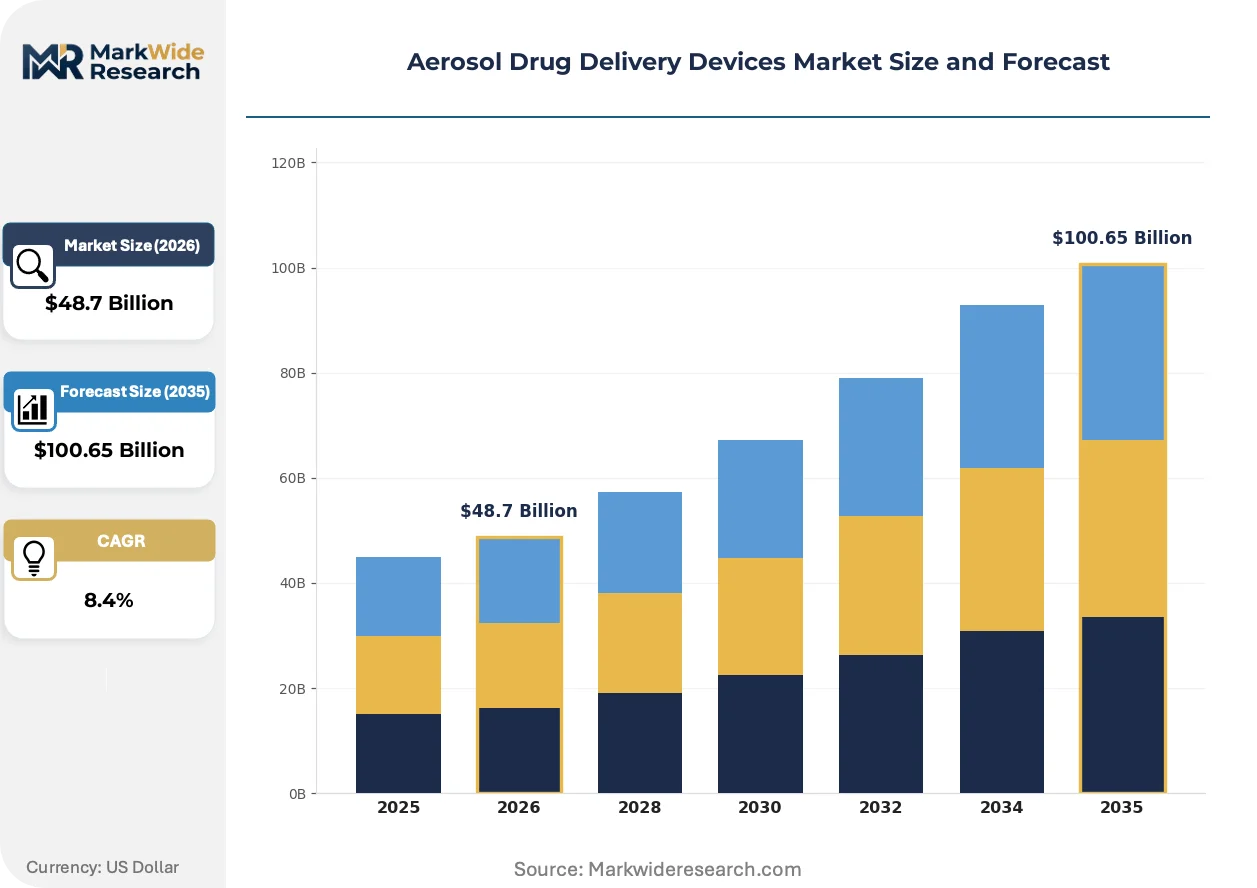
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Metered Dose Inhalers, Nebulizers, Dry Powder Inhalers, Soft Mist Inhalers End User: Hospitals, Home Care Settings, Clinics, Emergency Services Therapeutic Area: Asthma, COPD, Allergic Rhinitis, Cystic Fibrosis Distribution Channel: Pharmacies, Online Retail, Hospital Pharmacies, Direct Sales |
| Companies Covered | AstraZeneca, AptarGroup, Inc., Koninklijke Philips N.V., Novartis AG, Teva Pharmaceutical Industries Ltd, PARI Respiratory Equipment, Inc., OMRON Corporation, Catalent, Inc., Aerogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerosol Drug Delivery Devices Market Trends and Innovations
Connected inhaler ecosystems are maturing from pilot programs to standard-of-care infrastructure, with regulatory frameworks now catching up to hardware capabilities. This convergence is compressing development cycles and redrawing competitive boundaries.
Smart nebulizer systems with embedded flow sensors and Bluetooth connectivity are expanding into chronic obstructive pulmonary disease management protocols across United States accountable care organizations. Pulmonology groups in Texas and Florida are deploying these devices to reduce 30-day readmission penalties. The data infrastructure is expanding into risk-based contracting arrangements that tie device adherence metrics to reimbursement rates.
The EU F-Gas Regulation's phasedown schedule is forcing reformulation of entire metered dose inhaler portfolios before patent cliffs hit blockbuster respiratory drugs. German and French regulators are coordinating transitional approval pathways for propellant switches that maintain therapeutic equivalence. Generic manufacturers are accelerating HFA-152a compatibility studies to capture first-mover position as originator products face supply quota constraints.
Hospital procurement committees are unbundling nebulizer device purchases from disposable circuit contracts, reversing decades of bundled pricing. This disintermediation is compressing vendor margins while creating entry points for specialized disposable suppliers. The pattern is most visible in United States health systems pursuing standardization across acquired community hospitals.
Aerosol Drug Delivery Devices Market Segmentation
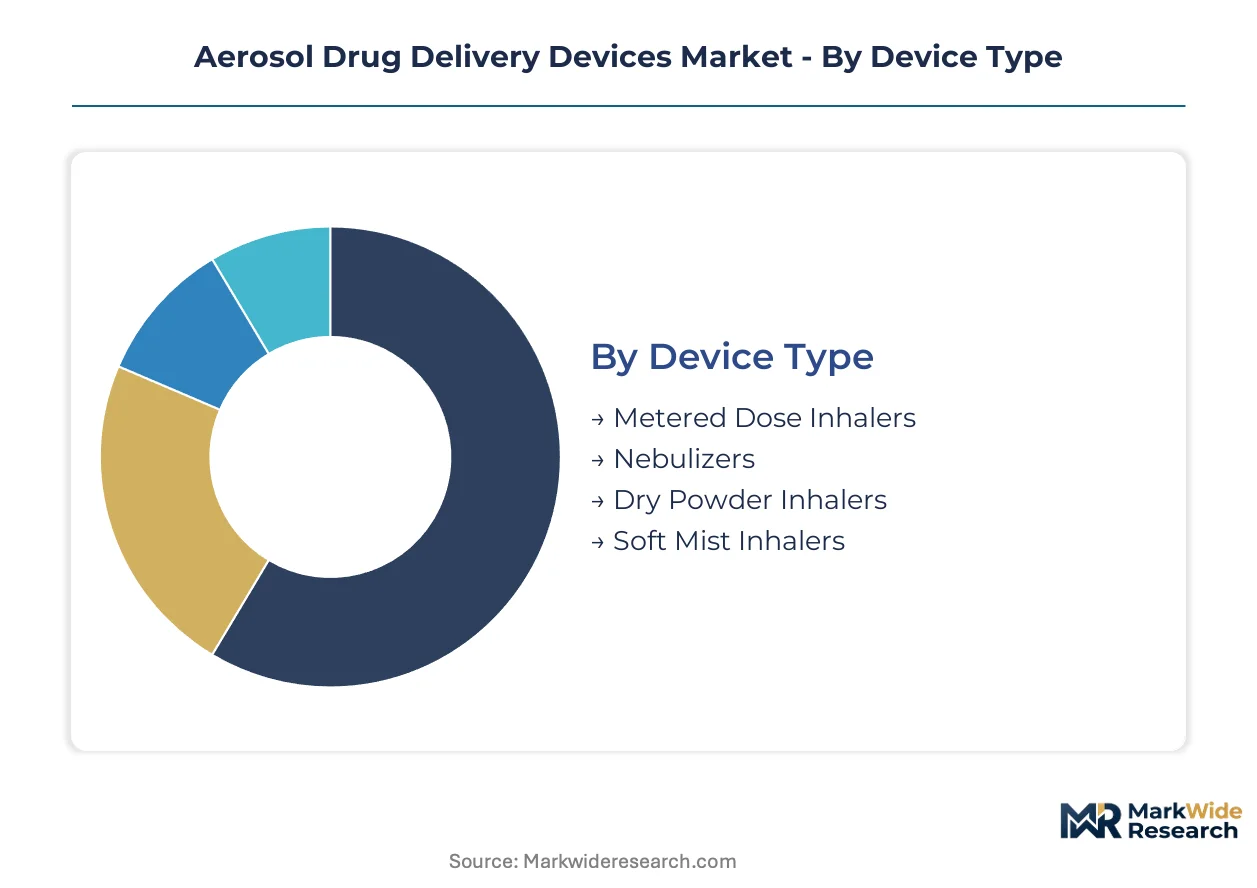
Device architecture determines reimbursement pathways and manufacturing scale in this market. Segmentation reveals where formulation-device coupling creates competitive moats versus commodity pressure.
Device Type:
Customization intensity spans from standardized mechanical platforms to breath-actuated systems requiring patient-specific tuning.
- Metered Dose Inhalers:Hydrofluoroalkane propellant systems dominate prescription volumes through compact form factors and decades of clinical familiarity. United States Medicare Part B reimbursement codes sustain procurement for chronic obstructive pulmonary disease maintenance therapy despite environmental compliance costs.
- Soft Mist Inhalers:Mechanical spring-actuated aerosol generation eliminates propellant dependence entirely. Germany's statutory health insurance funds are expanding formulary inclusion for elderly patients who struggle with hand-breath coordination required by traditional devices.
- Nebulizers:Compressor and vibrating mesh variants serve acute care protocols where passive inhalation is clinically necessary.
- Dry Powder Inhalers:Breath-actuated powder dispersion systems eliminate coordination requirements but depend on adequate inspiratory flow rates.
Most installed capacity flows through Metered Dose Inhalers. Expansion is steepest in Soft Mist Inhalers.
End User:
Cost tier stratification separates capital-intensive institutional procurement from recurring consumables in decentralized settings.
- Home Care Settings:Portable nebulizers and connected inhalers enable self-administered therapy with remote monitoring integration. Texas and Florida pulmonology groups bundle these devices with telehealth reimbursement codes to reduce hospital readmission penalties.
- Hospitals:High-volume compressor nebulizer systems and emergency stockpiles of rescue inhalers dominate capital equipment budgets. United States health systems are unbundling device purchases from disposable circuit contracts, compressing vendor margins.
- Clinics:Outpatient respiratory practices require demonstration devices and sample inhalers for patient training.
- Emergency Services:Compact rescue inhalers and portable oxygen-driven nebulizers support pre-hospital acute bronchospasm management.
Volume concentrates in Home Care Settings. Margin expansion is strongest in Hospitals.
Therapeutic Area:
Application maturity varies from well-established maintenance protocols to emerging biologic delivery indications.
- Asthma:Controller and rescue inhalers constitute the foundational prescription base across all age groups. Japan's childhood asthma prevalence exceeding 10% sustains pediatric device development programs.
- COPD:Triple therapy inhalers and long-acting bronchodilators drive premium device adoption in aging populations. Germany's disease management programs bundle device provision with pulmonary rehabilitation reimbursement.
- Allergic Rhinitis:Nasal spray aerosol devices serve seasonal and perennial rhinitis with over-the-counter accessibility.
- Cystic Fibrosis:High-frequency nebulization of mucolytics and antibiotics requires specialized durable equipment.
Prescription volume clusters in Asthma. Steepest device innovation cycles appear in COPD.
Distribution Channel:
Supply concentration patterns separate regulated pharmacy networks from direct manufacturer-patient relationships.
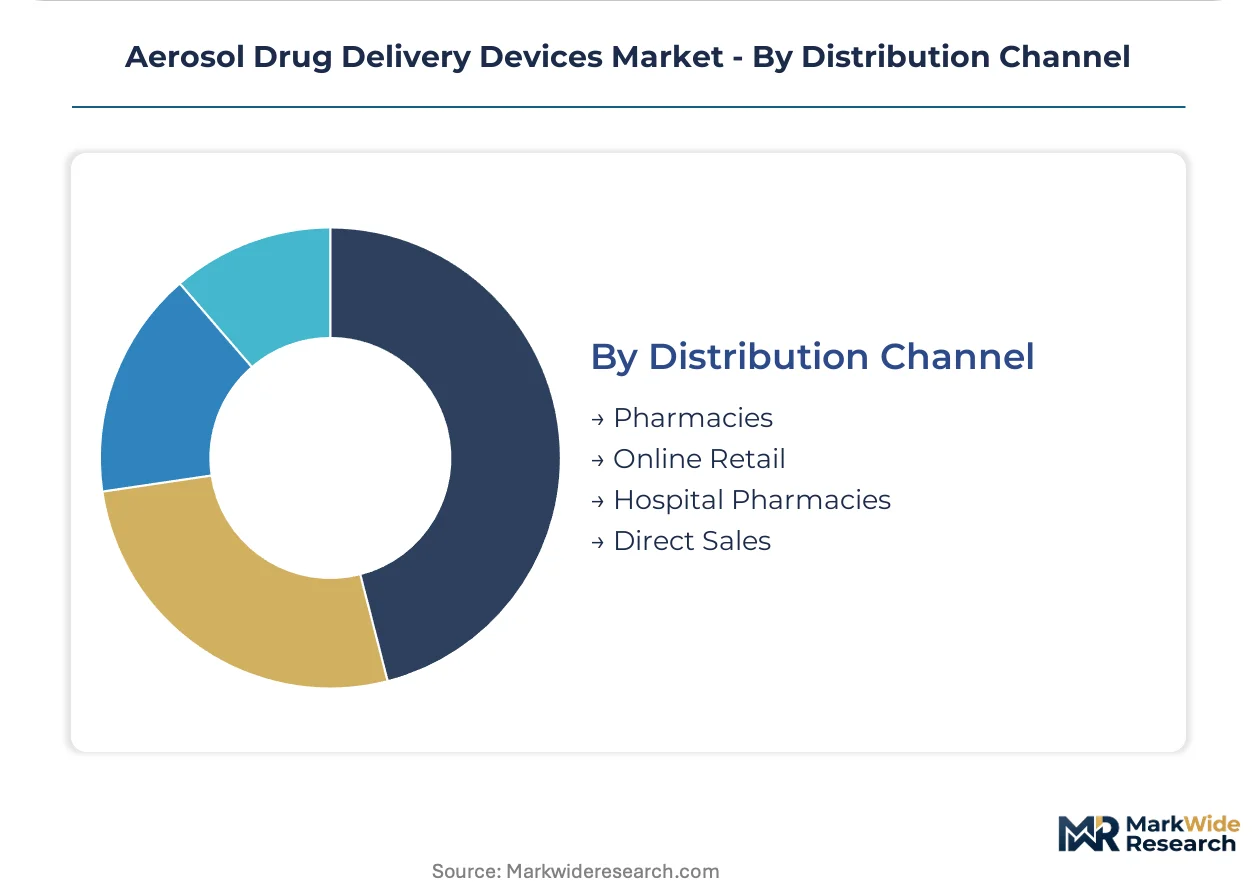
- Pharmacies:Community and retail pharmacy networks handle the majority of prescription inhaler dispensing with insurance adjudication. Germany's pharmacy network is penetrating direct-to-patient subscription models for nebulizer consumables.
- Hospital Pharmacies:Inpatient formularies and discharge medication reconciliation drive device selection for transitioning patients. United States 340B pricing programs influence procurement decisions for eligible institutions.
- Online Retail:E-commerce platforms expand access for over-the-counter devices and replacement accessories.
- Direct Sales:Manufacturer field forces supply specialized nebulizer systems and institutional contracts for health systems.
Transaction volume runs through Pharmacies. Channel margin expansion is fastest in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Carolina's Research Triangle anchors device development for respiratory therapeutics, hosting contract research organizations that validate deposition modeling for FDA submissions. Manufacturing scale concentrates in established pharmaceutical clusters across three continents.
United States
Medicare Part B reimbursement codes sustain metered dose inhaler procurement for COPD maintenance therapy in the aging population. The FDA enforces strict bioequivalence standards for generic inhaled products under its draft guidance for orally inhaled and nasal drug products. Texas and Florida pulmonology groups deploy connected nebulizer systems to reduce 30-day hospital readmission penalties.
Germany
Statutory health insurance funds expand formulary inclusion for soft mist inhalers targeting elderly patients with hand-breath coordination difficulties. The EU F-Gas Regulation's phasedown schedule forces reformulation of hydrofluoroalkane-based metered dose inhaler portfolios. Bavarian and North Rhine-Westphalian manufacturing clusters coordinate transitional approval pathways for propellant switches.
Japan
Childhood asthma prevalence exceeding 10% sustains pediatric device development programs for breath-actuated dry powder inhalers. The PMDA reviews age-appropriate resistance profiles for emerging mechanical aerosol platforms. Tokyo and Osaka medical device districts concentrate regulatory consulting expertise for inhaler submissions.
United Kingdom
The NHS Long Term Plan prioritizes community-based respiratory care, expanding home nebulizer provision for cystic fibrosis patients. EMA MDR enforcement accelerates investment in advanced deposition modeling capabilities among device developers. London and Cambridge clusters specialize in connected inhaler data infrastructure for remote patient monitoring.
India
Rising COPD prevalence in urban centers drives demand for cost-engineered dry powder inhalers in tier-2 and tier-3 cities. The CDSCO aligns with evolving pharmacopeial standards for delivered dose uniformity in generic inhaled products. Ahmedabad and Hyderabad pharmaceutical manufacturing hubs scale polypropylene housing production for metered dose inhalers.
Aerosol Drug Delivery Devices Market Competitive Landscape
Global majors compete with regional champions across device platform diversity, with pharmaceutical-origin companies holding formulation-device coupling advantages while specialized component suppliers capture recurring valve and actuator revenue. The structure tiers between integrated respiratory portfolio owners, precision component specialists, and connected system innovators. Three archetypes dominate: originators with captive device platforms, contract manufacturers with multi-client flexibility, and technology licensors monetizing proprietary aerosol generation mechanisms. Competitive moves center on backward integration into propellant supply chains and strategic partnerships for connected health data infrastructure.
Within the integrated pharmaceutical tier, AstraZeneca and Novartis AG occupy positions exemplifying scale across multiple device platforms. AptarGroup, Inc. represents the precision component archetype, anchoring supply chain concentration for valve and actuator technologies. Koninklijke Philips N.V. exemplifies the connected system vector, competing through nebulizer platforms that integrate with remote patient monitoring infrastructure.
| Leading Market Players |
|---|
| AstraZeneca |
| AptarGroup, Inc. |
| Koninklijke Philips N.V. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd |
| PARI Respiratory Equipment, Inc. |
| OMRON Corporation |
| Catalent, Inc. |
| Aerogen |
| Others |
Pricing and Supply Chain Analysis
Computational fluid dynamics specialists clustered in Boston and Cambridge academic centers drive labor-cost differentials that widen pricing-tier spreads between commodity nebulizer housings and precision-engineered soft mist platforms. This workforce concentration forces manufacturers to stratify engineering investment across premium connected systems and cost-optimized mechanical alternatives.
Pricing Analysis
Input-cost pass-through from fluorochemical propellant quotas and cyclic olefin polymer premiums shapes a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA bioequivalence certification tier and connected health data infrastructure bundling. Pricing pressure stems from unbundled hospital procurement compressing vendor margins in the compressor nebulizer segment. Home care settings exhibit highest price sensitivity, while cystic fibrosis treatment centers demonstrate lowest sensitivity due to clinical necessity.
Supply Chain Analysis
Hydrofluoroalkane propellant supply rests on German and French fluorochemical specialists, with valve and actuator manufacturing anchored in United States and Swiss precision component clusters. Raw material dependencies span polypropylene housings, cyclic olefin polymer drug-contact surfaces, and stainless-steel mesh for vibrating nebulizers. Single-source vulnerability in HFA-152a production exposes device makers to quota-driven disruption. Distribution runs through pharmacy networks in Germany and hospital GPO contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EMA MDR enforcement and FDA bioequivalence standards shift procurement toward deposition-validated premium platforms over commodity alternatives.
For Market Incumbents: Hedge propellant transition risk through backward integration into HFA-152a supply agreements with German chemical specialists, while consolidating connected nebulizer data infrastructure to defend against telehealth platform entrants. Lock in multi-year hospital GPO contracts before unbundling accelerates margin compression. For New Entrants and Emerging Players: Enter via pediatric breath-actuated dry powder inhalers in Japan, where PMDA age-appropriate resistance guidelines create regulatory white space unclaimed by established players. Partner with Texas and Florida pulmonology groups for remote patient monitoring pilot programs that bypass entrenched hospital procurement. For Investors and Strategic Acquirers: Pharmaceutical companies with captive respiratory portfolios are the most active acquirer in this space, seeking formulation-device coupling advantages. Target contract manufacturers with multi-client HFA-152a compatibility capabilities and FDA submission track records. Watch EU F-Gas quota price movements as the inflection signal for propellant-free mechanical system valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Transition Partnership | Secures HFA-152a supply quotas with German chemical producers ahead of originator patent cliffs. |
| Connected Nebulizer FDA Submission | Unlocks Medicare remote patient monitoring reimbursement codes in Texas and Florida ACOs. |
| Pediatric DPI CE Marking Pathway | Opens statutory health insurance formulary inclusion in Germany for elderly coordination-challenged patients. |
| Hospital GPO Contract Renewal | Defends compressor nebulizer volume before unbundling separates device from disposable circuit procurement. |
| Computational Fluid Dynamics Acquisition | Captures scarce lung deposition modeling talent concentrated in Boston and Cambridge academic centers. |
Research Methodology
Direct dialogue with regulatory affairs leads at inhaled product developers, hospital procurement managers at United States health systems, GPO contracts specialists, and pulmonology practice administrators grounded the qualitative foundation. Secondary validation drew from FDA OINDP draft guidance documents, EMA MDR implementation reports, EU F-Gas Regulation quota registries, and CMS Medicare Part B reimbursement code filings. Bottom-up device shipment estimates and top-down pharmaceutical respiratory revenue allocations were triangulated to anchor market sizing.
Bottom-up modeling of metered dose inhaler, soft mist inhaler, nebulizer, and dry powder inhaler unit economics across the analysis window was cross-checked against top-down pharmaceutical company respiratory segment disclosures. Segmentation dimensions included device architecture, end-user setting, therapeutic indication, and distribution channel. CAGRs were derived from regression-adjusted growth rate convergence. Forecast inputs incorporated EU F-Gas phasedown schedules and PMDA pediatric device review timelines.
The model holds under stable regulatory enforcement timelines and propellant quota allocations; deviation in FDA bioequivalence guidance finalization or EU F-Gas quota price volatility would shift competitive positioning and margin trajectories. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
General Surgical Devices Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Artificial Eye Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Organoids Kits Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
Heart Defect Closure Devices Market