
 Global Artificial Organ Market | 2026-2036
Global Artificial Organ Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Organ Market Foresight
Buyer concentration among integrated hospital networks is repositioning procurement leverage toward vendors with full-lifecycle service capabilities. Medtronic plc leverages its cardiac support portfolio to anchor multi-year contracts with consolidated health systems. Boston Scientific Corporation competes through specialized interventional platforms that address acute organ failure workflows. Abbott Laboratories differentiates via diagnostic-to-therapeutic integration across renal replacement system deployments.
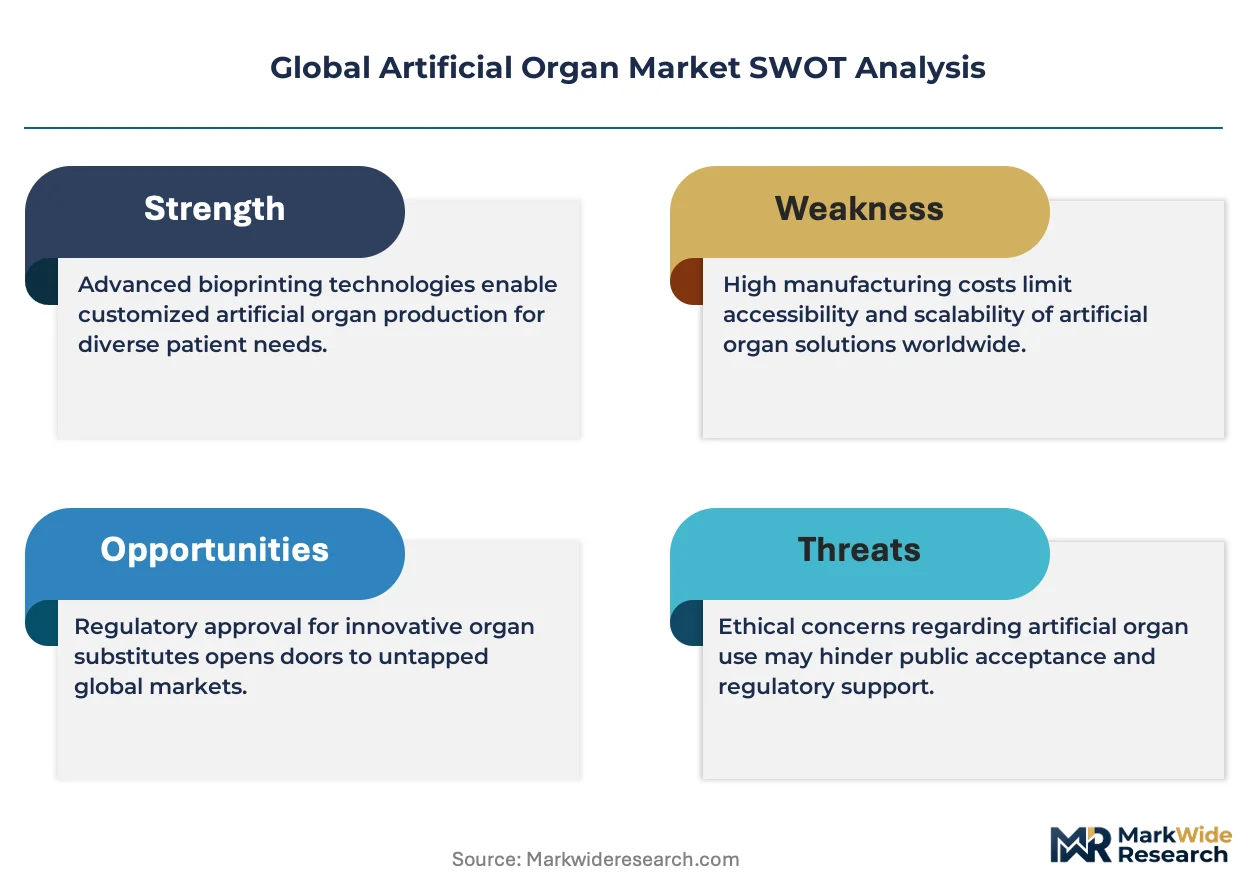
Artificial organs comprise engineered biological or synthetic constructs designed to replace or augment native organ function through mechanical, electromechanical, or tissue-integrated mechanisms, typically incorporating biocompatible polymers, living cells, or hybrid membranes with pore sizes calibrated for selective molecular transport. These devices serve critical therapeutic purposes in chronic disease management, acute organ failure intervention, and transplant alternatives where donor organ scarcity creates persistent unmet need. Cardiac support devices and renal replacement systems occupy the largest installed bases, reflecting decades of clinical validation and established reimbursement codes. 3D bioprinting and stem cell engineering represent the fastest-expanding technology segments, where margin pools concentrate around proprietary bioink formulations and patient-specific scaffold architectures.
The FDA breakthrough device program, EU MDR conformity requirements, and Japan's PMDA regenerative medicine framework collectively shape market access timelines, clinical evidence standards, and post-market surveillance obligations for artificial organ manufacturers. ISO 14155 and ISO 10993 standards govern biocompatibility and clinical investigation protocols, creating compliance barriers that favor organizations with dedicated regulatory infrastructure. Stakeholders must monitor how evolving reimbursement thresholds for bioartificial constructs intersect with health technology assessment methodologies in major markets.
Market Dynamics
Hospital procurement consolidation around integrated organ support platforms is compressing vendor margins while favoring suppliers with full-lifecycle service capabilities across cardiac, renal, and hepatic replacement systems.
Growth Catalysts
- FDA Breakthrough Device Designation:The accelerated pathway compresses commercialization timelines for bioartificial constructs, enabling earlier revenue recognition for developers of hybrid membrane systems.
- Chronic Disease Management Reimbursement:Mature frameworks in Germany, Japan, and the United States expand patient access to renal replacement and cardiac support devices through predictable coverage codes.
- 3D Bioprinting:Patient-specific scaffold architectures reduce rejection rates and enable on-demand production of vascularized tissue constructs for transplant alternatives.
Market Restraints
- Bioink Raw Material Concentration:Proprietary collagen and alginate formulations rely on concentrated suppliers in Switzerland and the United States, exposing manufacturers to input cost volatility.
- EU MDR Conformity Costs:Enhanced clinical evidence requirements for Class III implantable devices extend approval timelines and inflate regulatory expenditure for bioartificial organ developers.
- Donor Organ Availability Improvement:Advances in organ preservation and transport technologies partially alleviate scarcity pressures that drive artificial organ demand in acute failure interventions.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentives attract contract manufacturing investment for dialysis membrane and pump component assembly serving domestic and export markets.
- Stem Cell-Tissue Engineering Convergence:Integration of induced pluripotent stem cell sourcing with automated bioreactor culture systems enables scalable production of immunocompatible organoids.
- Direct-to-Hospital Distribution:Bypassing traditional device distributors, manufacturers establish captive logistics networks to capture service revenue and installation margin in consolidated health systems.
Industry Challenges
- ISO 10993 Biocompatibility Testing Bottlenecks:Limited certified laboratory capacity for cytotoxicity and sensitization assays delays preclinical validation timelines for novel polymer formulations.
- Cross-Functional Talent Scarcity:Integration of mechanical engineering, cell biology, and regulatory expertise remains concentrated among specialists with experience in both ISO 14155 clinical investigation design and GMP manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Organ Market |
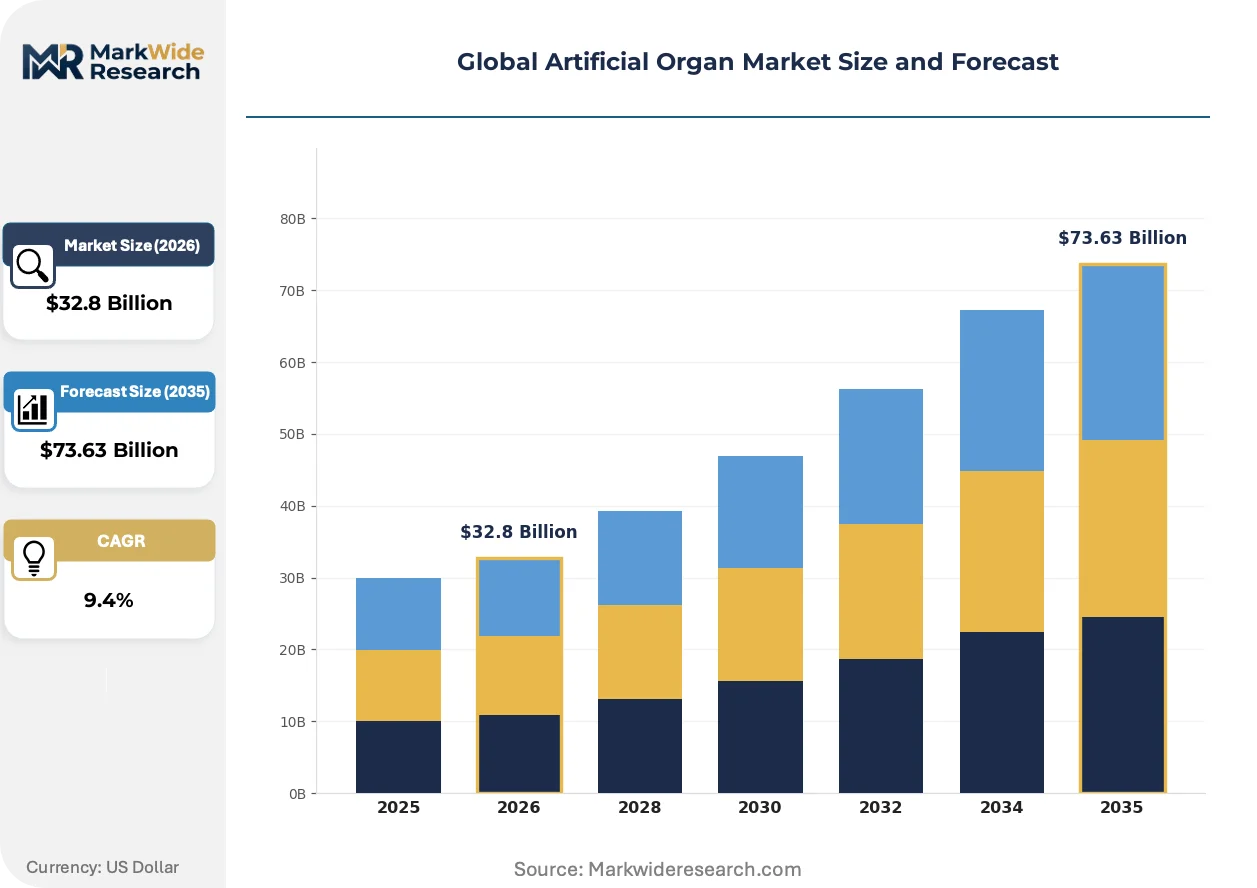
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $73.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Support Devices, Renal Replacement Systems, Hepatic Assist Devices, Pulmonary Assist Systems, Neurological Prosthetics, Endocrine Implants Application: Chronic Disease Management, Acute Organ Failure, Transplant Alternatives, Trauma Recovery, Research Models, Regenerative Therapies End User: Specialized Clinics, Academic Research Institutes, Biomaterials Companies, Rehabilitation Centers, Government Agencies, Biotech Startups Technology: 3D Bioprinting, Microfluidics, Nanomaterial Scaffolds, Bioartificial Constructs, Stem Cell Engineering, Synthetic Biomembranes |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Edwards Lifesciences Corporation, Zimmer Biomet Holdings Inc., Baxter International Inc., Getinge AB, SynCardia Systems LLC, Berlin Heart GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Organ Market Shifts & Advancements
Electromechanical miniaturization and biohybrid material science are converging to enable implantable systems that blur the boundary between mechanical support and biological regeneration.
Bioartificial constructs incorporating living cells within synthetic scaffolds are electrifying clinical trial pipelines for hepatic and pancreatic support applications. Transplant centers in the United States and Germany are prioritizing these hybrid systems for acute-on-chronic liver failure protocols. The technology is compressing the timeline between first-in-human studies and conditional approval by demonstrating functional equivalence to bridge-to-transplant devices.
Japan's PMDA regenerative medicine framework is accelerating conditional approval pathways for cell-based organoids, reducing pre-market clinical trial requirements for bioartificial kidneys. Manufacturers must establish post-market surveillance infrastructure capable of tracking long-term immunogenicity outcomes across diverse patient populations. Renal replacement system developers are responding by embedding real-time biomarker sensors to satisfy pharmacovigilance obligations.
Integrated service contracts are displacing transactional device sales in consolidated dialysis networks, bundling equipment, consumables, and technical support under multi-year agreements. Equipment vendors are absorbing maintenance liability and outcome risk previously borne by hospital procurement departments. Germany's hospital financing reforms are accelerating this transition by penalizing readmission costs for device-related complications.
Global Artificial Organ Market Segmentation
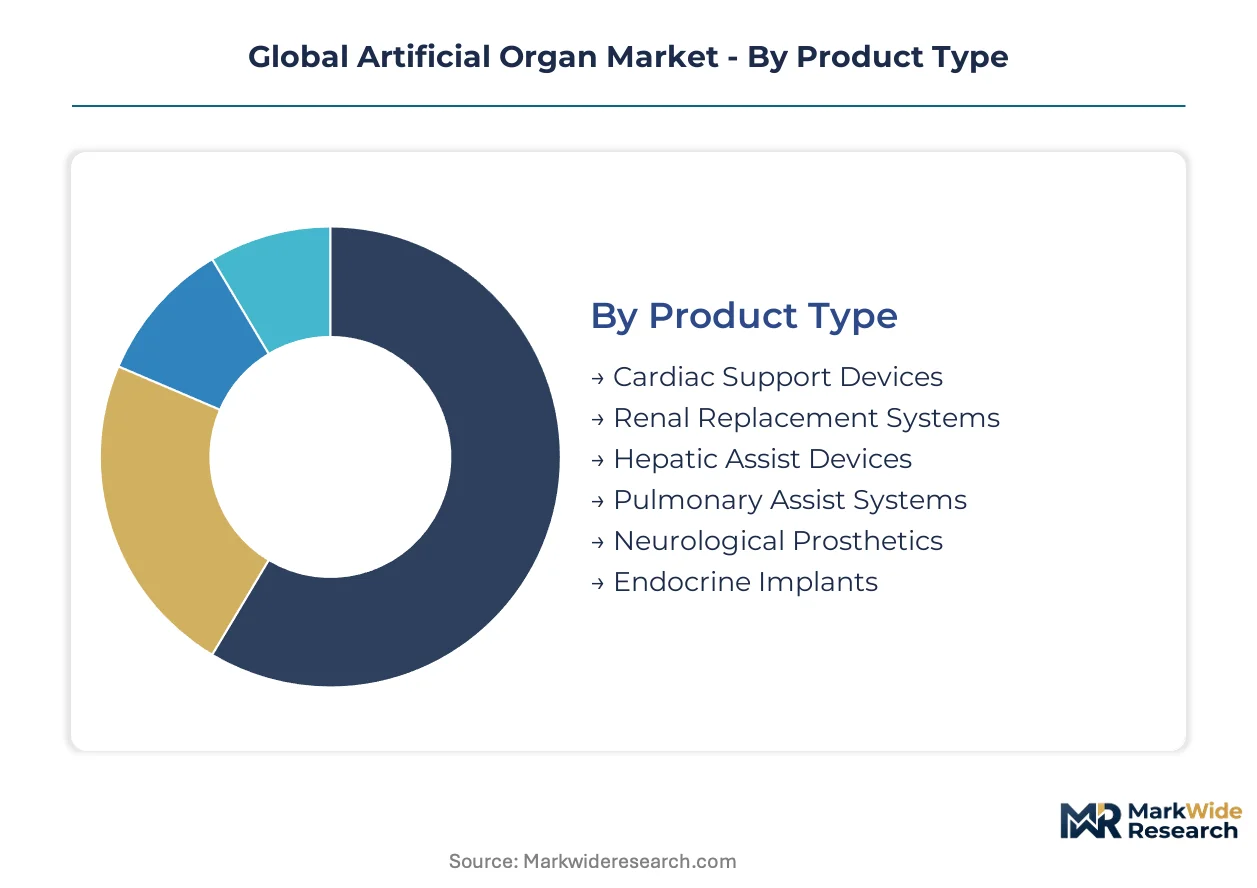
Segmentation in artificial organs reveals how clinical validation timelines, reimbursement density, and manufacturing complexity concentrate revenue across distinct technology-product pairings. Procurement consolidation among hospital networks favors vendors with cross-category platform expertise rather than single-modality specialists.
Product Type:
Technical maturity and installed base scale determine margin sustainability across organ replacement categories.
- Cardiac Support Devices:Mechanical circulatory support systems incorporate centrifugal or pulsatile pumps with biocompatible blood-contacting surfaces. Demand concentrates in transplant centers across the United States and Germany where bridge-to-transplant protocols command favorable reimbursement. Ventricular assist device manufacturers leverage decades of hemocompatibility data to defend procurement contracts.
- Renal Replacement Systems:Dialysis membranes and portable filtration units address end-stage renal disease through hemodialysis or peritoneal modalities. Japan's expanded chronic disease reimbursement and India's PLI scheme for medical devices are accelerating regional production capacity for membrane components.
- Hepatic Assist Devices:Bioartificial liver support systems combine cellular bioreactors with plasma separation circuits for acute-on-chronic failure.
- Pulmonary Assist Systems:Extracorporeal membrane oxygenation circuits and ambulatory oxygenators serve acute respiratory failure in intensive care settings.
- Neurological Prosthetics:Deep brain stimulators and neural interface arrays target movement disorders and sensory restoration applications.
- Endocrine Implants:Automated insulin delivery systems and artificial pancreas constructs integrate continuous glucose monitoring with algorithmic dosing.
Cardiac support leads on scale; bioartificial hepatic systems lead on momentum.
Application:
Clinical endpoint requirements and regulatory evidence thresholds fragment addressable markets across intervention contexts.
- Chronic Disease Management:Long-term implantable systems for heart failure and renal insufficiency demand biocompatibility profiles validated across multi-year follow-up periods. Medicare and Germany's statutory health insurance provide predictable coverage codes that stabilize procurement planning for dialysis networks.
- Acute Organ Failure:Temporary circulatory or respiratory support devices prioritize rapid deployment and weaning protocols over longevity metrics. ICU consolidation in the United States is standardizing equipment platforms across cardiac surgery and medical intensive care units.
- Transplant Alternatives:Destination therapy indications for patients ineligible for donor organs require durable mechanical solutions with minimal anticoagulation burden.
- Trauma Recovery:Battlefield and emergency applications drive miniaturization priorities for portable organ support.
- Research Models:Preclinical testing platforms and organ-on-chip systems serve pharmaceutical toxicity screening.
- Regenerative Therapies:Cell-based organoid development targets eventual biological replacement rather than mechanical bridging.
Chronic management commands the revenue base; regenerative applications are climbing the fastest.
End User:
Purchasing authority and technical sophistication shape vendor engagement models across customer categories.
- Specialized Clinics:Dialysis chains and cardiac support centers negotiate multi-year equipment leases bundled with consumable supply agreements. Fresenius Medical Care and DaVita procurement specifications dominate membrane and dialyzer purchasing volumes in North America.
- Academic Research Institutes:NIH-funded centers and Max Planck Institute networks drive early-stage bioartificial organ development through investigator-initiated grants.
- Biomaterials Companies:Collagen and alginate suppliers serve as contract manufacturers for scaffold components.
- Rehabilitation Centers:Neural prosthetic fitting and training programs require specialized technical support infrastructure.
- Government Agencies:Defense research programs and public health procurement establish specifications for ruggedized field-deployable systems.
- Biotech Startups:Venture-backed developers concentrate on 3D bioprinting platforms and stem cell-derived organoids.
Specialized clinics dominate procurement volume; biotech startups show the steepest expansion trajectory.
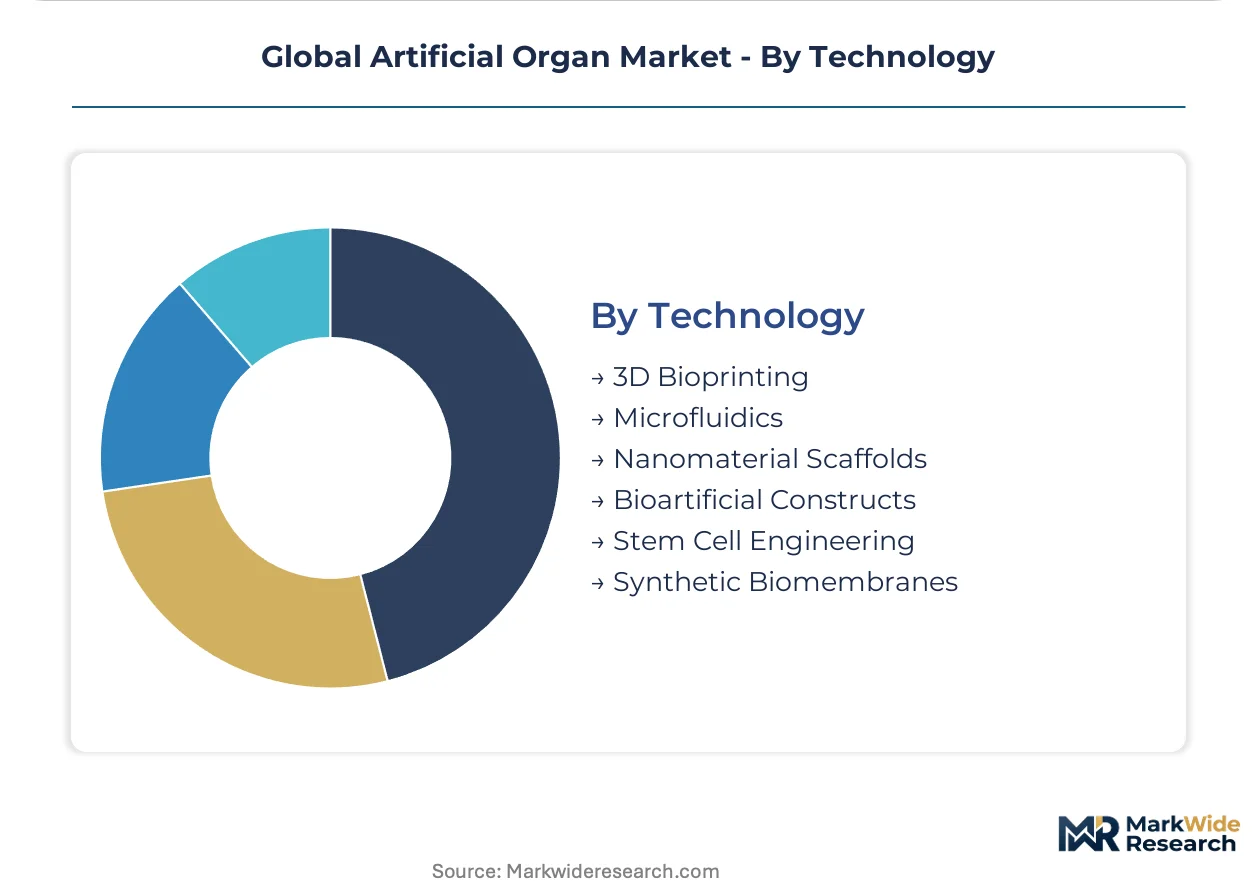
Technology:
Intellectual property concentration and manufacturing scalability differentiate competitive positions across enabling platforms.
- 3D Bioprinting:Extrusion and stereolithographic systems deposit cell-laden bioinks with vascular channel architectures. Switzerland's precision engineering cluster and Boston's academic-industrial corridor host the dominant equipment and formulation patent holders.
- Microfluidics:Organ-on-chip platforms replicate tissue-tissue interfaces for pharmaceutical screening applications.
- Nanomaterial Scaffolds:Electrospun polymer matrices and self-assembling peptide hydrogels provide structural templates for cell infiltration.
- Bioartificial Constructs:Hybrid systems integrating living cells within synthetic perfusion circuits target hepatic and renal support applications.
- Stem Cell Engineering:Induced pluripotent cell sourcing and directed differentiation protocols enable patient-specific immunocompatible tissue.
- Synthetic Biomembranes:Polyethersulfone and polysulfone hollow fiber membranes with calibrated pore size distributions serve dialysis and oxygenation functions.
Synthetic biomembranes anchor current revenue; 3D bioprinting platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized transplant surgeons and bioengineers concentrate in the United States, Germany, and Japan, anchoring the geographic distribution of artificial organ development and commercial deployment. These talent clusters align with mature reimbursement frameworks and regulatory pathways that accelerate clinical translation.
United States
Transplant centers in Houston, Pittsburgh, and Cleveland drive demand for ventricular assist devices and total artificial hearts through established bridge-to-transplant protocols. The FDA breakthrough device designation compresses commercialization timelines for bioartificial constructs, enabling earlier market entry for hybrid membrane developers. The Boston-Cambridge corridor hosts concentrated venture capital flows into 3D bioprinting platforms and stem cell engineering startups.
Germany
Statutory health insurance reimbursement codes stabilize procurement planning for dialysis networks and cardiac support centers across Baden-Württemberg and Bavaria. The EU MDR conformity requirements for Class III implantable devices elevate clinical evidence standards, favoring manufacturers with dedicated regulatory infrastructure. Berlin and Aachen anchor industrial clusters for precision pump components and biocompatible polymer formulations serving European transplant programs.
Japan
Expanded chronic disease reimbursement under national health insurance broadens patient access to renal replacement systems and destination therapy devices. The PMDA regenerative medicine framework accelerates conditional approval pathways for cell-based organoids, reducing pre-market trial burdens. Tokyo and Osaka metropolitan areas concentrate manufacturing capacity for hollow fiber membranes and automated perfusion circuits.
India
Rising end-stage renal disease prevalence and expanding dialysis infrastructure drive procurement volumes for membrane components and portable filtration units. The PLI scheme for medical devices attracts contract manufacturing investment for pump assembly and dialyzer production serving domestic and export markets. Hyderabad and Bengaluru host emerging clusters for affordable cardiac support device development and regulatory consulting services.
Switzerland
Precision engineering expertise in the Zurich-Basel corridor dominates proprietary collagen and alginate bioink formulations for 3D bioprinting applications. Swissmedic oversight of advanced therapy medicinal products ensures alignment with EU regulatory standards while maintaining streamlined national procedures. Geneva and Lausanne academic institutions supply specialized talent in biomaterials science and microfluidic scaffold design.
Global Artificial Organ Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across cardiac, renal, and hepatic replacement categories, creating a tiered structure where scale advantages intersect with technological depth. Medtronic plc and Abbott Laboratories anchor the diversified tier with cross-platform service capabilities, while Berlin Heart GmbH and SynCardia Systems LLC occupy focused positions in mechanical circulatory support. Strategic moves concentrate on multi-year integrated service contracts with consolidated health systems and captive logistics networks that bypass traditional distribution channels.
Among diversified medical technology conglomerates, Medtronic plc, Boston Scientific Corporation, and Abbott Laboratories represent the archetype of full-lifecycle service providers anchoring procurement decisions across integrated hospital networks. These companies exemplify competitive positioning built on decades of hemocompatibility data and diagnostic-to-therapeutic integration. Edwards Lifesciences Corporation and Zimmer Biomet Holdings Inc. occupy positions within specialized interventional and orthopedic-adjacent segments, while Baxter International Inc. and Getinge AB sit within the renal and acute care support tiers.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| Zimmer Biomet Holdings Inc. |
| Baxter International Inc. |
| Getinge AB |
| SynCardia Systems LLC |
| Berlin Heart GmbH |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA breakthrough-designated bioartificial constructs and standard mechanical support devices manifests in both pricing power and supply chain configurations. Premium-tier manufacturers in Switzerland and the United States command captive supply agreements for proprietary collagen formulations, while commodity membrane producers in India and China compete on scale economics for dialysis consumables.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for dialysis membranes and pump components, compressing margins for established suppliers in Japan and Germany. Three-tier pricing structure across premium, standard, and economy levels separates FDA-designated bioartificial systems from CE-marked mechanical devices and unbranded consumables. Pricing pressure stems from hospital procurement consolidation demanding bundled service contracts. Dialysis chains exhibit highest price sensitivity; transplant centers demonstrate lowest sensitivity due to outcome-based procurement criteria.
Supply Chain Analysis
Refurbishment flows for ventricular assist devices and dialysis equipment create reverse logistics networks concentrated in the United States and Germany, extending asset lifecycles and displacing new unit demand. Manufacturing draws from Switzerland for precision bioink formulations, Japan for hollow fiber membranes, and India for pump assembly. Single-source vulnerability concentrates in proprietary alginate suppliers. Distribution runs through captive logistics networks established by diversified conglomerates serving consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial organ market operates as a regulatory compounder where FDA breakthrough device designations and Japan's PMDA regenerative medicine framework accelerate commercialization timelines and expand reimbursable indications.
For Market Incumbents: To counter margin compression from India's PLI-driven manufacturing scale, Medtronic plc and Abbott Laboratories should deepen backward integration into biocompatible polymer production and anchor multi-year integrated service contracts with consolidated dialysis networks. Certification investment in EU MDR conformity infrastructure defends procurement access against emerging Asian competitors. For New Entrants and Emerging Players: Mid-tier hospital systems in India's secondary cities represent an underserved buyer archetype seeking affordable cardiac support devices with localized technical support. Regulatory consulting partnerships in Hyderabad and Bengaluru provide the most penetrable entry pathway. Direct-to-hospital distribution models bypass entrenched GPO relationships and capture installation margin. For Investors and Strategic Acquirers: Consolidation pressure builds where cross-functional talent scarcity intersects with ISO 10993 biocompatibility testing bottlenecks, favoring acquirers with captive regulatory infrastructure. Long-term viability over a multi-decade horizon rests on stem cell-tissue engineering convergence capabilities. The signal to watch is conditional approval velocity under Japan's PMDA regenerative medicine framework as inflection indicator for bioartificial kidney commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Bundles equipment, consumables, and maintenance liability under multi-year agreements with consolidated health systems. |
| FDA Breakthrough Designation Pursuit | Compresses commercialization timelines for bioartificial constructs and enables earlier revenue recognition. |
| Backward Integration into Bioinks | Captures margin pools around proprietary collagen and alginate formulations concentrated in Switzerland. |
| India PLI Scheme Participation | Attracts contract manufacturing investment for dialysis membrane production serving domestic and export markets. |
| Real-Time Biomarker Sensor Embedding | Satisfies Japan PMDA pharmacovigilance obligations for cell-based organoid post-market surveillance. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with transplant surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs specialists were combined with secondary validation from FDA 510(k) filings, PMDA approval databases, hospital procurement records, and CMS Medicare reimbursement data. Triangulation across these sources ensures segmentation integrity across product type, application, and technology dimensions.
Historical trendline analysis of installed base growth and replacement cycles informs projection modeling across the analysis window. Segmentation dimensions include organ system category, intervention context, end-user purchasing authority, and enabling technology platform. CAGRs were derived from regression analysis of validated data points against macroeconomic healthcare expenditure indicators and regulatory approval velocity metrics specific to bioartificial construct commercialization.
Inputs from FDA and PMDA regulatory databases were available through the study window; gaps in long-term immunogenicity outcome data for cell-based organoids introduce uncertainty bands around adoption curve assumptions. Practitioners should monitor conditional approval decisions under Japan's regenerative medicine framework and EU MDR clinical evidence requirement evolution for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Healthcare Additive Manufacturing Market
Medical Devices
Clear Aligners Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Diabetes Devices Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Urethral Bulking System Market
Medical Devices
Smart Mask Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Hybrid Microcirculation Detector Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Europe Surgical Visualization Products Market