
 Transilluminators Market | 2026-2036
Transilluminators Market Size, Share, and Industry Trends Forecast 2026-2036
Transilluminators Market Outlook
Academic research laboratories is reorganizing procurement priorities toward safer blue-light and LED transilluminators, displacing traditional UV-heavy configurations in core facilities. Thermo Fisher Scientific leverages its fluorescence instrumentation ecosystem to bundle gel documentation systems with transilluminator modules. Bio-Rad Laboratories anchors its position through vertical integration into electrophoresis consumables that lock in hardware placement. Cleaver Scientific competes on manufacturing scale from its UK base, shipping compact units that target budget-constrained teaching labs.
A transilluminator is a benchtop optical device that emits specific wavelengths—typically 302 nm UV, 470 nm blue light, or broad-spectrum white LED—to excite fluorescent dyes bound to nucleic acids or proteins in agarose or polyacrylamide gels, enabling visualization and documentation of separated biomolecules. LED transilluminators now dominate new installations due to their elimination of toxic mercury lamps, instant on-off capability, and tunable excitation bands that reduce sample photodamage. UV transilluminators retain share in high-sensitivity DNA analysis workflows where low-detection-limit ethidium bromide imaging remains standard, though this segment faces regulatory pressure from laboratory safety officers. Digital imaging technology is displacing traditional eyepiece viewing across all product tiers, as integrated CMOS sensors and analysis software become baseline expectations rather than premium upgrades.
The EPA regulates mercury lamp disposal under the Universal Waste Rule, pushing facilities toward LED alternatives that eliminate hazardous waste streams. FDA oversight of clinical diagnostic laboratories using transilluminators for quality control in nucleic acid testing enforces performance validation protocols that favor established suppliers with 510(k)-adjacent documentation. ISO 13485 quality management requirements shape procurement criteria for pharmaceutical companies integrating gel imaging into regulated drug development workflows. Stakeholders must monitor how state-level laboratory safety regulations accelerate blue-light adoption timelines and whether digital imaging standardization creates switching costs that consolidate vendor relationships.
Market Dynamics
LED-based excitation technology is fragmenting the installed base of mercury-lamp UV transilluminators as laboratory safety officers enforce hazardous waste elimination protocols under tightened environmental regulations.
Growth Catalysts
- EPA Universal Waste Rule:The regulation mandates documented mercury lamp disposal chains, accelerating LED replacement cycles in university core facilities and commercial sequencing centers.
- CRISPR workflow standardization:High-throughput gene editing protocols require tunable excitation bands that only solid-state sources provide, pulling hardware refresh demand from NIH-funded genomics programs.
- Digital imaging convergence:Integrated CMOS sensors with cloud-connected analysis software are displacing eyepiece viewing, creating bundled upgrade paths that consolidate vendor relationships.
Market Restraints
- UV sensitivity threshold:Ethidium bromide detection at picogram concentrations still requires 302 nm mercury excitation, locking a segment of forensic and diagnostic labs into legacy hardware.
- Phosphor coating supply:Rare-earth dopants for blue-to-UV conversion in LED engines concentrate in Chinese processing facilities, exposing OEMs to export quota volatility.
- Validation documentation burden:FDA 21 CFR Part 11 compliance for clinical diagnostic imaging imposes six-to-twelve month qualification timelines that favor incumbent suppliers with established 510(k) portfolios.
Strategic Opportunities
- Teaching laboratory segment:Budget-constrained undergraduate biology programs in India and Southeast Asia represent unserved demand for compact, filter-swappable units below premium price tiers.
- Protein gel fluorescence:SYPRO Ruby and Deep Purple dye workflows for proteomics quality control are migrating from laser scanners to LED transilluminators, opening adjacent application revenue.
- ISO 13485 certification pathway:Pharmaceutical companies integrating gel imaging into regulated drug development workflows require quality-managed hardware, creating margin expansion for certified suppliers.
Industry Challenges
- Optical engineering talent:Shortage of specialists combining fluorescence microscopy expertise with solid-state illumination design extends product development cycles and inflates R&D compensation.
- Legacy system integration:Gel documentation software from 2015-2019 installations uses proprietary image formats that resist migration to cloud-based analysis platforms, creating customer friction during upgrade conversations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transilluminators Market |
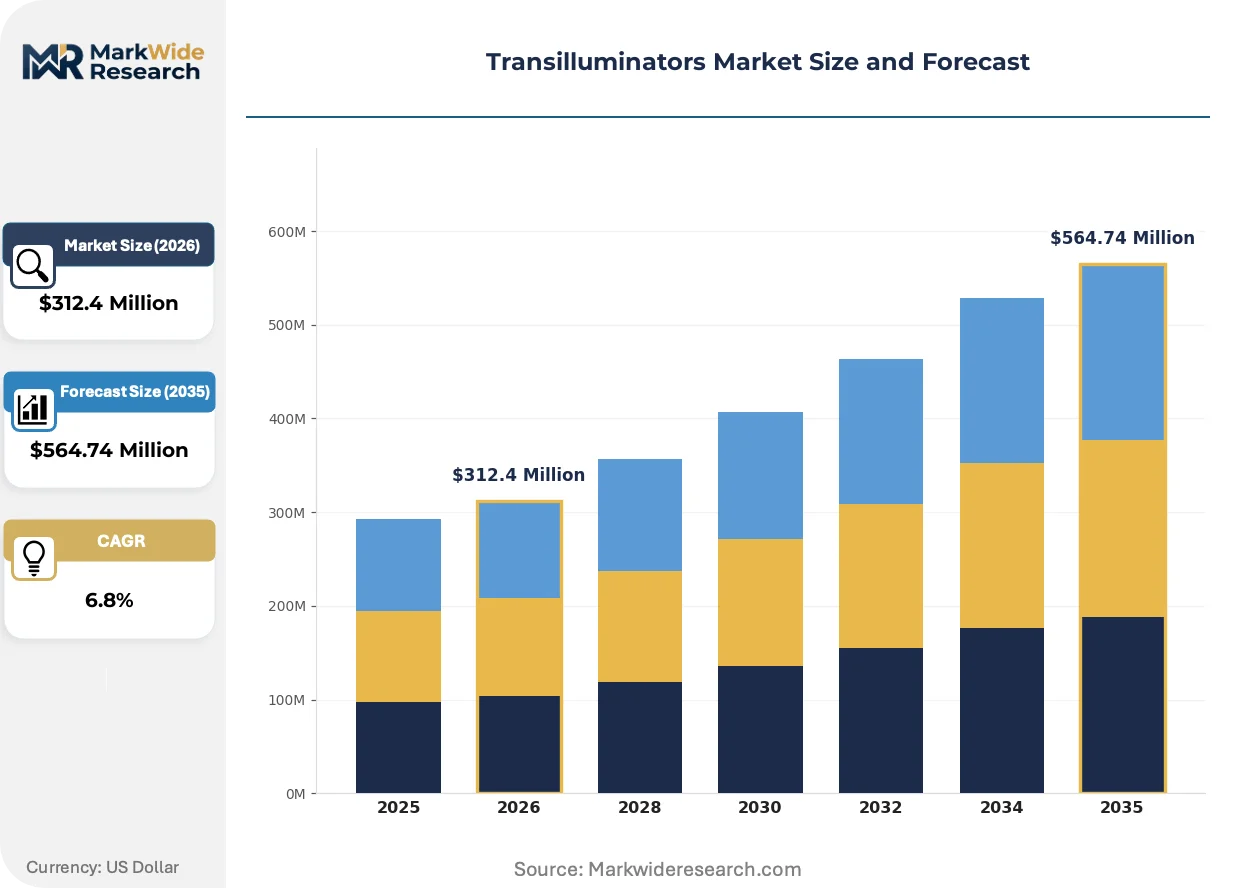
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Transilluminators, UV Transilluminators, Blue Light Transilluminators, Handheld Transilluminators End User: Research Laboratories, Clinical Laboratories, Educational Institutions, Pharmaceutical Companies Application: Gel Imaging, DNA Analysis, Protein Detection, Cell Biology Technology: Fluorescence Technology, Laser Technology, Optical Technology, Digital Imaging |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, VWR International, Cleaver Scientific, Analytik Jena, Syngene, Thomas Scientific, DNR Bio-Imaging Systems, Wealtech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transilluminators Market Strategic Shifts
Transilluminator architecture is pivoting from standalone benchtop hardware toward modular excitation engines embedded in integrated electrophoresis workflows, compressing the addressable market for discrete units while expanding system-level contract values.
Multi-wavelength LED engines are fragmenting product categories that historically separated UV, blue-light, and white-light models into distinct SKUs. Core facilities at research-intensive universities now specify tunable 365-470-550 nm sources that eliminate filter swaps between nucleic acid and protein applications. This consolidation is compressing SKU proliferation strategies and forcing OEMs to defend margin through software differentiation rather than hardware segmentation.
REACH Annex XVII restrictions on mercury-containing equipment are accelerating phase-out timelines for UV lamp transilluminators across European Union member states. The regulation's industrial consequence is a mandatory replacement cycle that bypasses normal capital depreciation schedules, concentrating demand spikes in 2026-2027 procurement windows. Germany and France are responding fastest, with national laboratory safety frameworks now requiring documented mercury elimination plans as a condition of institutional liability insurance renewal.
Academic procurement officers are consolidating vendor relationships through multi-year framework agreements that bundle transilluminator hardware with consumables and service contracts. This behavior shift displaces transactional spot purchasing that previously characterized teaching lab equipment acquisition. The pattern is most visible in United States R1 universities, where shared instrumentation grants from NSF and NIH now mandate single-source documentation to ensure interoperability across distributed core facilities.
Transilluminators Market Segmentation
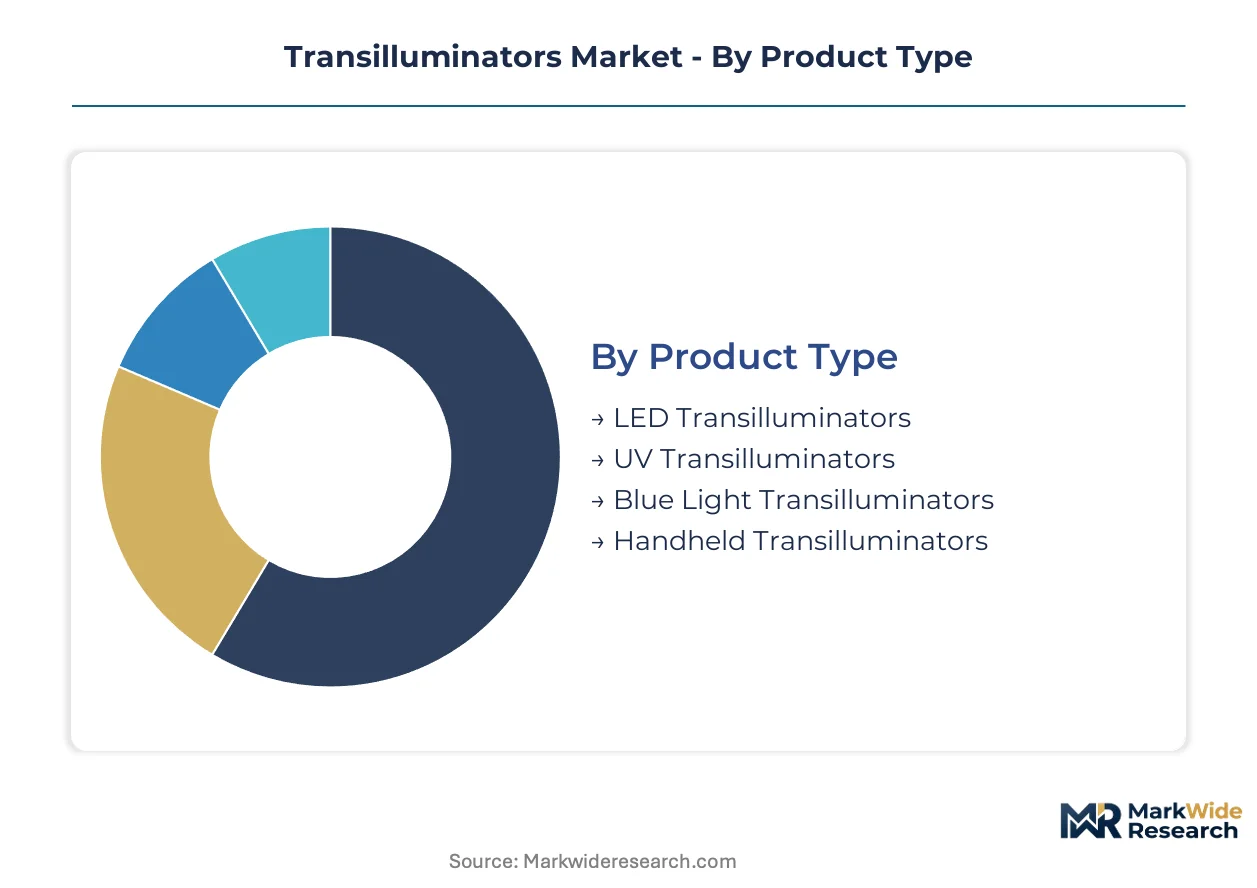
Transilluminator procurement patterns diverge sharply across product architectures and end-use settings. Segment-level demand concentrates in regulatory-sensitive installations where mercury elimination timelines and workflow standardization requirements reshape equipment specifications.
Product Type:
LED transilluminators dominate domestic replacement cycles in EPA-regulated facilities, while UV units retain export concentration in forensic and diagnostic markets with delayed environmental compliance deadlines.
- LED Transilluminators:Solid-state excitation engines eliminate mercury disposal chains and enable instant wavelength switching between 365-470-550 nm bands. Demand concentrates in United States NIH-funded genomics core facilities where CRISPR workflow standardization mandates tunable illumination. The EPA Universal Waste Rule accelerates replacement of legacy mercury hardware in university and commercial sequencing centers.
- UV Transilluminators:Mercury-lamp systems operating at 302 nm deliver picogram-sensitivity ethidium bromide detection required for forensic DNA analysis and clinical diagnostic quality control. Export-led demand persists in laboratories with extended phase-out timelines, though REACH Annex XVII restrictions in European Union member states compress residual market windows.
- Blue Light Transilluminators:470 nm excitation reduces sample photodamage for safe classroom demonstrations and routine nucleic acid visualization.
- Handheld Transilluminators:Battery-powered portable units serve field-based environmental monitoring and point-of-care diagnostic applications.
LED transilluminators command the established base. The steepest expansion runs through blue-light variants as teaching laboratories prioritize student safety.
End User:
Research laboratories absorb premium-tier hardware with integrated documentation systems, while educational institutions drive volume demand for cost-optimized entry-level configurations.
- Research Laboratories:Molecular biology core facilities require multi-wavelength engines with CMOS-integrated imaging and cloud-connected analysis software. Procurement concentrates in R1 universities with NSF and NIH shared instrumentation grants mandating single-source vendor frameworks for interoperability across distributed facilities.
- Clinical Laboratories:FDA-regulated nucleic acid testing workflows enforce 21 CFR Part 11 validation documentation favoring established suppliers with 510(k)-adjacent quality systems. ISO 13485 certification requirements shape pharmaceutical integration decisions.
- Educational Institutions:Undergraduate biology programs in India and Southeast Asia generate unserved demand for compact filter-swappable units below premium price tiers.
- Pharmaceutical Companies:Regulated drug development workflows require quality-managed gel imaging with documented performance validation for IND submissions.
Research laboratories command the established base. The steepest expansion runs through clinical laboratories as nucleic acid testing standardization accelerates hardware refresh cycles.
Application:
Gel imaging applications concentrate procurement in high-throughput sequencing facilities, while protein detection workflows migrate from laser scanners toward LED-based transillumination.
- Gel Imaging:Integrated electrophoresis workflows now embed modular excitation engines, compressing the addressable market for standalone transilluminators while expanding system-level contract values. Digital imaging convergence with CMOS sensors and analysis software displaces eyepiece viewing across all product tiers.
- DNA Analysis:High-sensitivity forensic and diagnostic protocols retain UV excitation requirements for ethidium bromide detection at low concentration thresholds.
- Protein Detection:SYPRO Ruby and Deep Purple dye workflows for proteomics quality control are migrating from laser scanners to LED transilluminators.
- Cell Biology:Live-cell imaging applications require reduced phototoxicity excitation sources compatible with extended observation protocols.
Gel imaging commands the established base. The steepest expansion runs through protein detection as proteomics workflows adopt LED-based instrumentation.
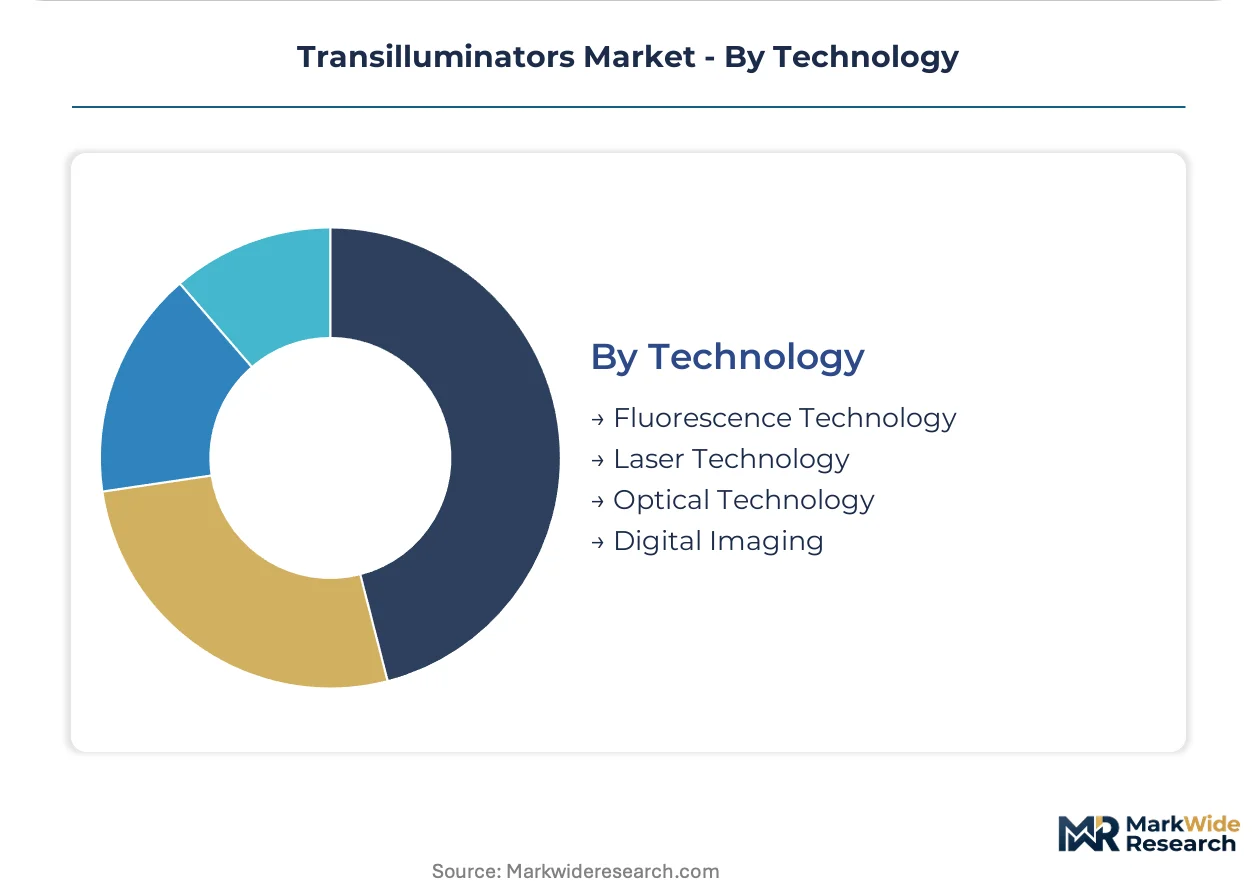
Technology:
Fluorescence technology anchors revenue concentration in research-intensive installations, while digital imaging creates bundled upgrade paths that consolidate vendor relationships.
- Fluorescence Technology:Ethidium bromide, SYBR Green, and gel-red dye excitation remains the foundational detection modality for nucleic acid visualization. Research core facilities specify tunable LED engines that eliminate filter swaps between multiple fluorophore applications.
- Digital Imaging:Integrated CMOS sensors with automated exposure algorithms and cloud-based analysis platforms displace manual documentation workflows. Academic procurement officers favor multi-year framework agreements bundling hardware with software subscriptions.
- Laser Technology:Confocal scanning systems retain position in high-resolution proteomics applications requiring sub-micron spatial resolution.
- Optical Technology:Filter-based wavelength selection persists in budget-constrained installations prioritizing capital cost over operational flexibility.
Fluorescence technology commands the established base. The steepest expansion runs through digital imaging as integrated documentation becomes a baseline procurement requirement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision optical components to sequencing centers across the United States and Asia-Pacific research hubs, establishing the primary trade corridor for transilluminator subassemblies and excitation engine modules.
United States
NIH-funded genomics programs at Stanford, MIT, and the Broad Institute drive replacement cycles for tunable LED systems. The EPA Universal Waste Rule mandates documented mercury lamp disposal chains, accelerating LED adoption in university core facilities. Boston's Route 128 biotech corridor concentrates demand from CRISPR workflow standardization initiatives.
Germany
REACH Annex XVII restrictions on mercury-containing equipment compress replacement timelines for UV lamp transilluminators. The country's national laboratory safety framework requires documented mercury elimination plans as a condition of institutional liability insurance renewal. Heidelberg and Munich research clusters prioritize multi-wavelength LED engines for proteomics quality control workflows.
China
Domestic sequencing centers in Shenzhen and Beijing expand procurement of solid-state excitation systems as the Ministry of Ecology and Environment tightens hazardous waste regulations. Rare-earth dopant processing for blue-to-UV conversion concentrates in Jiangsu and Inner Mongolia facilities, exposing OEMs to export quota volatility. Shanghai's Zhangjiang Hi-Tech Park anchors demand from pharmaceutical contract research organizations.
United Kingdom
Research-intensive universities consolidate vendor relationships through multi-year framework agreements bundling hardware with consumables. The Health and Safety Executive enforces laboratory safety protocols that accelerate blue-light adoption in teaching facilities. Cambridge and Oxford core facilities specify integrated CMOS documentation systems for distributed interoperability.
India
Budget-constrained undergraduate biology programs in Maharashtra and Karnataka generate unserved demand for compact filter-swappable units below premium price tiers. The Central Pollution Control Board extends hazardous waste rules to educational institutions, creating regulatory pressure for mercury elimination. Bangalore's biotech cluster drives procurement from genomics startups and contract research organizations.
Transilluminators Market Competitive Environment
Listed leaders compete with private specialists across capital access and R&D scale dimensions, producing a tiered structure where public companies leverage fluorescence instrumentation ecosystems while private fabricators compete on manufacturing agility. Thermo Fisher Scientific and Bio-Rad Laboratories anchor the premium tier through bundled gel documentation systems and electrophoresis consumables integration. Mid-scale specialists compete on ISO 13485 certification pathways for pharmaceutical quality-managed workflows. Dominant competitive moves include strategic partnerships for cloud-connected analysis software and geographic expansion into Southeast Asian teaching laboratory segments.
Among United States-based instrumentation conglomerates, Thermo Fisher Scientific and Bio-Rad Laboratories exemplify the ecosystem-anchored archetype, occupying positions where fluorescence instrumentation portfolios enable bundled hardware placement. Cleaver Scientific represents the manufacturing-scale specialist, with UK-based production targeting budget-constrained institutional segments through compact unit configurations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| VWR International |
| Cleaver Scientific |
| Analytik Jena |
| Syngene |
| Thomas Scientific |
| DNR Bio-Imaging Systems |
| Wealtech Corporation |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supplier qualification and price differentiation in pharmaceutical-integrated workflows, creating a bifurcated market where certified OEMs command premium positioning while uncertified competitors compete on capital cost alone. Buyers in regulated drug development environments absorb higher price points to secure documented quality management, whereas teaching laboratories prioritize equipment cost over certification overhead.
Pricing Analysis
Next-generation multi-wavelength LED engines command a generation-gap premium over legacy mercury-lamp UV units and first-generation single-band LED systems. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by ISO 13485 certification status and integrated CMOS documentation capability. Cost compression in the economy tier intensifies as Chinese manufacturers scale compact filter-swappable units for budget-constrained educational markets. Academic procurement officers exhibit highest price sensitivity, while pharmaceutical quality control departments prioritize performance validation over capital expenditure.
Supply Chain Analysis
Rare-earth dopant processing in Jiangsu and Inner Mongolia province facilities constitutes a chokepoint for blue-to-UV conversion phosphors, exposing OEMs to export quota volatility. Excitation engine assembly draws from German precision optical component suppliers, Chinese rare-earth processing, and Japanese CMOS sensor fabrication. Single-source vulnerability concentrates in phosphor coating supply chains subject to environmental regulatory disruption. Distribution runs through academic laboratory supply distributors and direct pharmaceutical procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transilluminator demand sits in early-cycle expansion as CRISPR workflow standardization penetrates NIH-funded genomics core facilities, creating replacement pull that bypasses normal capital depreciation schedules.
For Market Incumbents: Fortify ecosystem lock-in by bundling tunable LED hardware with cloud-connected analysis software subscriptions, neutralizing emerging entrants competing on capital cost alone. Deepen backward integration into phosphor coating supply through offtake agreements with Jiangsu processing facilities, reducing exposure to rare-earth export quota volatility. Prioritize ISO 13485 certification maintenance to defend pharmaceutical segment positioning against mid-scale specialists.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission opens European teaching laboratory procurement channels ahead of REACH Annex XVII enforcement windows. Target compact filter-swappable configurations for undergraduate biology programs in Maharashtra and Karnataka, where Central Pollution Control Board mercury rules create regulatory pull without incumbent saturation. Lead with safety-officer value propositions emphasizing student photodamage reduction over sensitivity specifications.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital imaging module integration as CMOS sensor commoditization reduces excitation engine manufacturing barriers. Five-to-ten year viability favors acquisition targets with established ISO 13485 quality systems and pharmaceutical customer relationships over pure hardware fabricators. Monitor EPA Universal Waste Rule enforcement intensity as the inflection signal for LED replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-wavelength Engine Development | Tunable 365-470-550 nm sources eliminate SKU proliferation while defending margin through software differentiation. |
| Cloud-connected Analysis Platform Integration | CMOS-integrated documentation with automated exposure algorithms displaces manual workflows across NIH-funded core facilities. |
| ISO 13485 Certification Pathway Investment | Quality-managed hardware positioning captures pharmaceutical contract research organization procurement with documented IND submission support. |
| Teaching Laboratory Geographic Expansion | Compact filter-swappable units address unserved demand in Maharashtra and Karnataka undergraduate programs below premium tiers. |
| Phosphor Coating Supply Agreement | Long-term offtake with Jiangsu rare-earth processors mitigates export quota volatility exposure for blue-to-UV conversion engines. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA enforcement documentation, NIH grant award databases, and REACH Annex XVII regulatory filings, with inputs from laboratory safety officers, core facility directors, and pharmaceutical quality control managers. Primary interviews with procurement officers at R1 universities and biomedical engineers at contract research organizations informed demand segmentation. Secondary validation drew from FDA 510(k) clearance databases, ISO certification registries, and customs trade data for optical component flows. Bottom-up equipment shipment analysis triangulates against top-down research expenditure modeling.
Segmentation dimensions modeled include excitation technology generation, end-use regulatory environment, and application workflow integration depth across the projection horizon. CAGRs derive from replacement cycle timing analysis, regulatory phase-out schedule enforcement probability, and genomics program funding trajectory assessment. Industry-specific forecast inputs incorporate CRISPR protocol standardization adoption curves and mercury lamp disposal cost escalation under EPA Universal Waste Rule compliance.
Decision-makers should treat outputs as directional under base assumptions of sustained NIH genomics funding and REACH Annex XVII enforcement continuity; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as state-level laboratory safety regulation acceleration and phosphor export quota disruption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Pharma Robots Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Aortic Valve Replacement Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Drainage Catheters Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Acne Treatment Devices Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Hospital and Pre-Hospital External Defibrillator Market