
 Electroporation Instruments Market | 2026-2036
Electroporation Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Electroporation Instruments Market Analysis
Modular platform architecture is decoupling hardware from disposable cartridge sets, letting buyers scale throughput without replacing base units. Lonza leverages its manufacturing scale to supply integrated workflow systems across cell therapy manufacturing suites. Bio-Rad Laboratories, Inc. anchors its position through deep specialization in pulsed-field protocols for research markets. Thermo Fisher Scientific Inc. competes by extending its channel control into academic procurement networks worldwide.
Electroporation instruments apply controlled electrical pulses to transiently permeabilize cell membranes, enabling nucleic acid or protein delivery with field strengths typically ranging from hundreds of volts to kilovolts per centimeter depending on cell type and application. Their primary commercial purpose centers on manufacturing-grade cell engineering for gene-modified therapies and large-molecule bioproduction. Bench-top systems dominate current installed bases in academic and early-stage research settings, while high-voltage platforms represent the fastest-growing category as contract manufacturers scale electroporation for clinical vector production. Gene therapy applications command premium pricing due to stringent electrical-parameter reproducibility requirements, whereas cell transfection remains the volume anchor across research institutions.
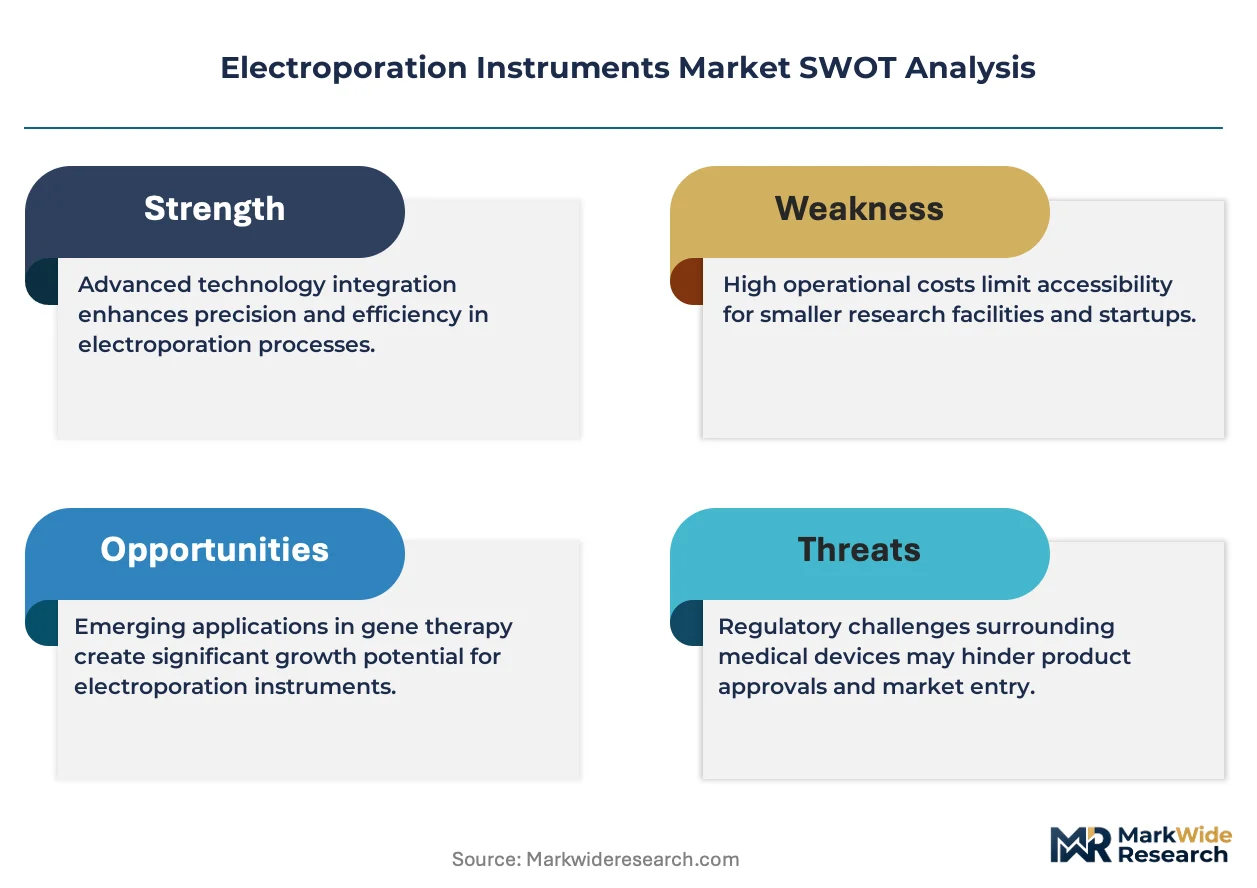
FDA cell-and-gene therapy guidance and EMA's ATMP framework shape electrical-validation protocols and documentation burdens for instrument vendors seeking clinical-market access. ISO 13485 quality-system requirements and IEC 61010-1 safety standards further constrain design pathways, particularly for high-voltage platforms entering European and North American markets. Stakeholders must monitor evolving electrical-parameter harmonization between FDA process-validation expectations and EMA's evolving Good Manufacturing Practice annexes for advanced therapies.
Market Dynamics
Modular electroporation platforms are fragmenting capital expenditure timelines across contract manufacturers, forcing instrument vendors to decouple hardware from consumable revenue streams and restructure pricing around throughput tiers rather than unit shipments.
Growth Catalysts
- Gene therapy manufacturing scale-up:Pharmaceutical companies are procuring clinical-grade electroporation systems to meet FDA process-validation requirements for cell-and-gene therapy production. The tightening electrical-parameter documentation standards are accelerating replacement cycles for legacy research-grade equipment.
- CRISPR editing workflows:Research institutions and biotech startups are standardizing electroporation as the primary delivery mechanism for ribonucleoprotein complexes, driving instrument demand across academic procurement networks in the United States, Germany, and China.
- mRNA vector production:Contract development and manufacturing organizations are expanding high-voltage platform capacity to support lipid nanoparticle encapsulation workflows, with field strength requirements above 1 kV/cm becoming standard for large-scale transfection.
Market Restraints
- High-voltage safety compliance costs:IEC 61010-1 certification requirements for European and North American market access impose substantial design-validation burdens on platform developers, particularly for multi-kilovolt systems entering clinical manufacturing environments.
- Single-source consumable dependency:Proprietary cartridge architectures from dominant vendors lock buyers into captive supply relationships, limiting price negotiation leverage and creating vulnerability to supply interruptions concentrated in Swiss and German manufacturing footprints.
- Electroporation-magnetofection hybrid competition:Emerging non-viral delivery technologies targeting primary cell types are capturing share in immunotherapy research segments where electrical parameter optimization remains technically demanding.
Strategic Opportunities
- India biologics manufacturing expansion:CDSCO's streamlined medical device registration pathways and PLI scheme incentives for biopharma infrastructure are attracting instrument vendors to establish localized technical support and calibration services.
- Closed-system automation convergence:Integration of electroporation modules with single-use bioreactor platforms is enabling continuous processing workflows that reduce cleanroom footprint requirements and operator exposure risks.
- ISO 13485 quality-system differentiation:Vendors achieving comprehensive certification ahead of competitors can capture premium positioning in clinical-grade procurement evaluations where documentation completeness outweighs marginal price advantages.
Industry Challenges
- Electrophysiology specialist scarcity:The intersection of cell biology and electrical engineering expertise required for protocol optimization remains concentrated in a limited pool of practitioners, constraining customer training and field application support scaling.
- Legacy system integration complexity:Manufacturing suites with established viral vector infrastructure face substantial revalidation costs when retrofitting electroporation platforms into existing cleanroom layouts and quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroporation Instruments Market |
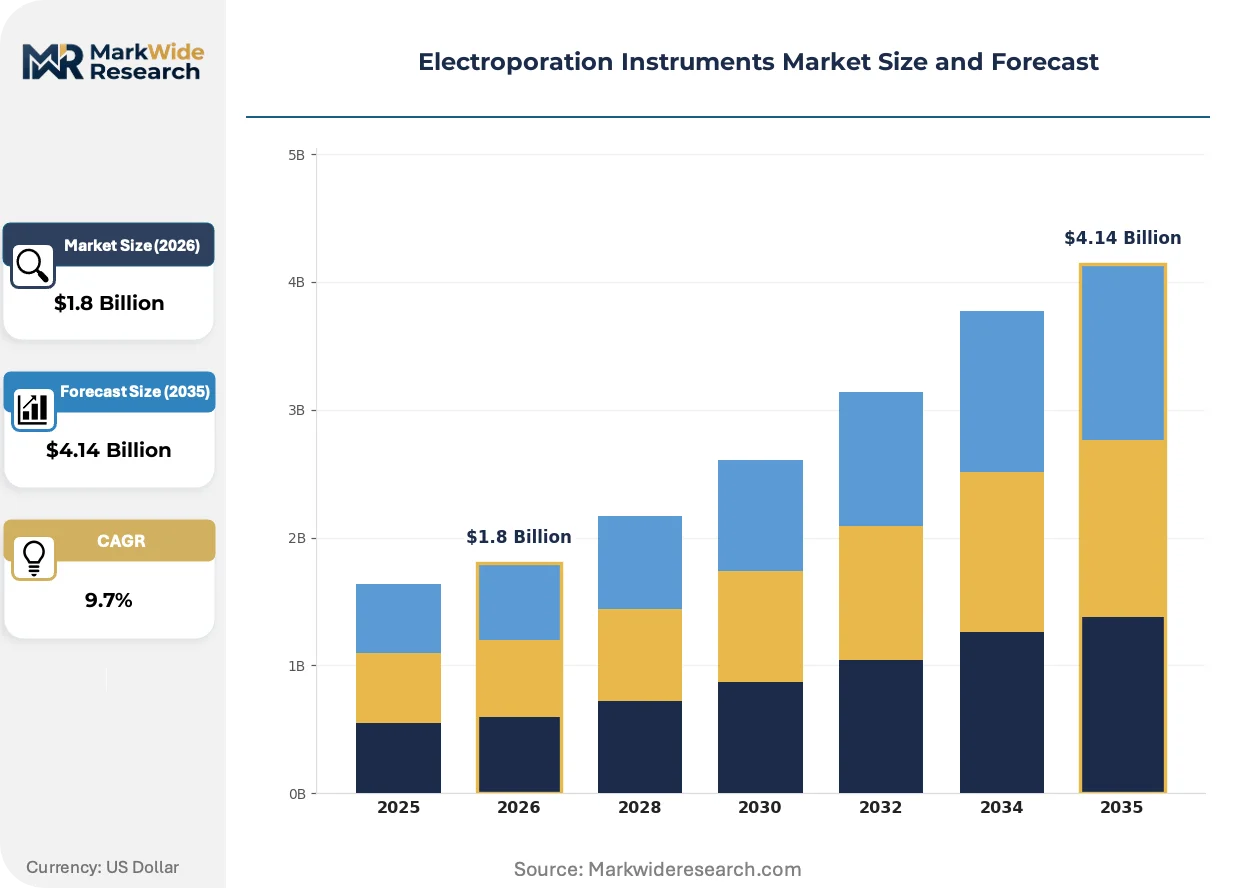
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-top, Portable, High-Voltage, Handheld Technology: Pulsed Electric Fields, Nanosecond Pulses, Square Waves, Continuous Waves Application: Gene Therapy, Cell Transfection, Vaccine Development, Cancer Treatment End User: Pharmaceutical Companies, Research Institutions, Academic Labs, Biotechnology Firms |
| Companies Covered | Lonza, BEX Co. Ltd., Bio-Rad Laboratories, Inc., Harvard Bioscience Inc., Eppendorf AG, Thermo Fisher Scientific Inc., MaxCyte, Inc., Celetrix LLC, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroporation Instruments Market Emerging Trajectories
Digital pulse-shaping architectures and real-time impedance monitoring are compressing protocol development cycles and enabling adaptive field delivery that responds to cell-density variations during processing.
Microfluidic electroporation chips are integrating precision electrode geometries with laminar flow control to achieve single-cell resolution in high-throughput screening applications. Contract research organizations are adopting these systems for rare disease target validation where transfection efficiency variance directly impacts program progression decisions. The technology is integrating with automated liquid-handling platforms to eliminate manual sample-transfer steps and reduce well-to-well reproducibility errors.
EMA's evolving Good Manufacturing Practice annexes for advanced therapy medicinal products are mandating electrical-parameter traceability documentation that exceeds current FDA process-validation expectations. Instrument vendors are reconfiguring software architectures to capture pulse waveform metadata and operator authentication logs as standard outputs. High-voltage platforms destined for European clinical manufacturing suites face the most compressed compliance timelines as notified bodies interpret the new documentation requirements.
Equipment-as-a-service contracting is displacing capital purchase models among mid-scale cell therapy developers seeking to conserve cash runway for regulatory milestones. Leasing structures with embedded consumable minimums and remote diagnostic subscriptions are capturing preference among Series B-stage biotechnology companies in the Boston and San Diego clusters. This financing flexibility is most visible in the United States where venture-backed manufacturing scale-up decisions prioritize balance-sheet preservation over long-term cost optimization.
Electroporation Instruments Market Segmentation
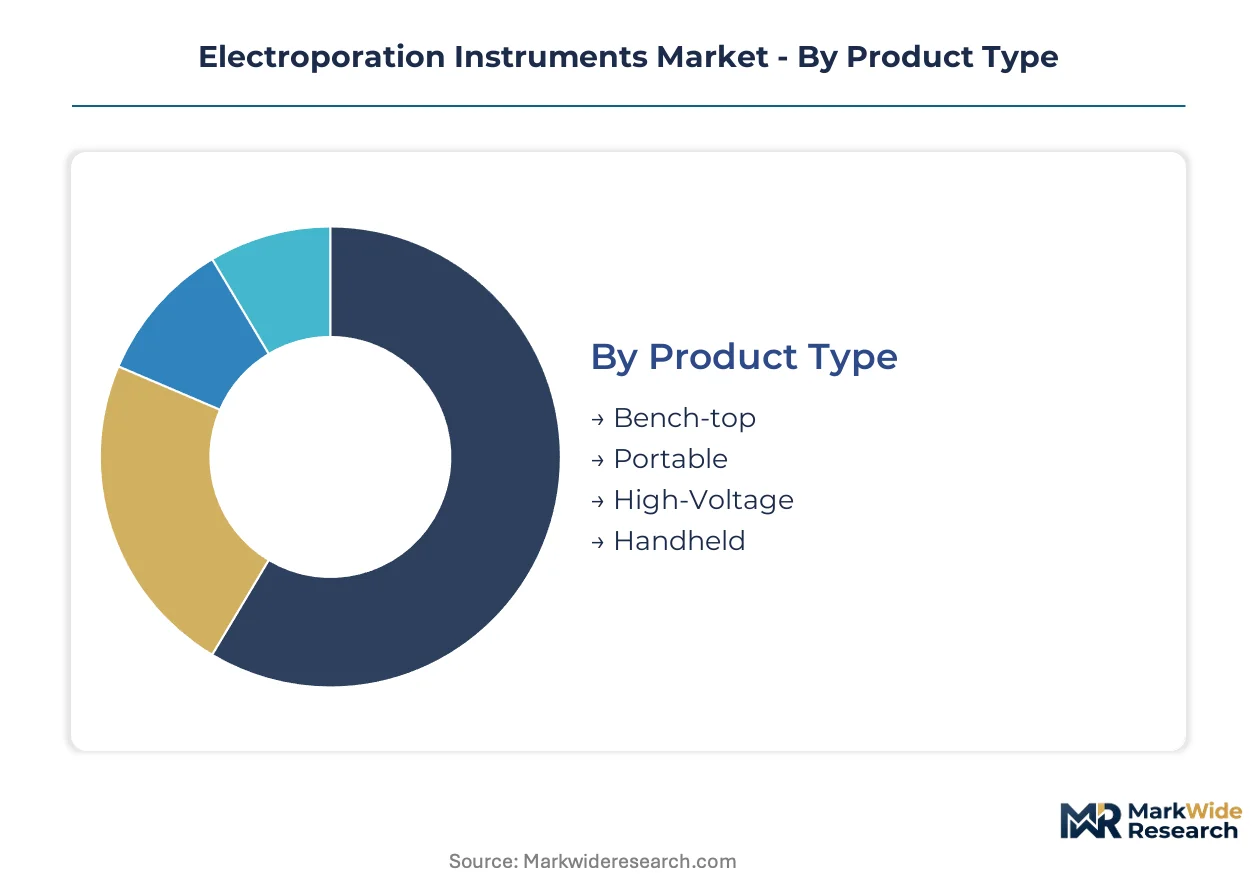
Electroporation instrument segmentation reveals divergent specification requirements across research, clinical, and manufacturing environments. Each axis—product form factor, pulse architecture, therapeutic target, and buyer type—carries distinct electrical-parameter tolerances and regulatory documentation burdens.
Product Type:
Voltage output and throughput capacity define the hardware taxonomy, with field strength requirements scaling directly from laboratory screening to commercial vector production.
- Bench-top:Fixed-electrode cuvette systems dominate academic installed bases with field strengths typically spanning 100–1,000 V/cm. Demand concentrates in United States and German research institutions where CRISPR protocol standardization drives replacement cycles for legacy units.
- High-Voltage:Multi-kilovolt platforms with programmable pulse trains serve contract manufacturers scaling mRNA and cell therapy production. CDMOs in the United States and China are procuring these systems to meet FDA process-validation requirements for clinical-grade electroporation.
- Portable:Battery-operated field units with reduced voltage ceilings suit point-of-care gene therapy research in resource-constrained settings.
- Handheld:Miniaturized single-sample devices address specialized applications in veterinary and agricultural biotechnology with limited throughput demands.
Mature deployment sits with bench-top systems in academic networks. Newer deployment is concentrated in high-voltage platforms entering GMP manufacturing suites.
Technology:
Pulse waveform architecture determines membrane permeabilization kinetics and cell viability outcomes, with protocol selection tightly coupled to target cell type and cargo molecule.
- Pulsed Electric Fields:Microsecond-duration exponential decay pulses remain the default for bacterial and yeast transformation workflows. Pharmaceutical companies in Germany and Switzerland standardize on these protocols for established bioproduction cell lines.
- Square Waves:Precisely controlled voltage plateaus enable fine-tuned membrane recovery dynamics for sensitive primary cells. Biotechnology firms in the Boston and San Diego clusters favor square-wave systems for T-cell engineering in immunotherapy pipelines.
- Nanosecond Pulses:Ultrashort high-intensity fields target intracellular organelles without plasma membrane disruption.
- Continuous Waves:Sustained low-field exposure supports electrochemotherapy applications in localized cancer treatment.
Square-wave deployment dominates immunotherapy manufacturing investment. Pulsed electric field systems retain the largest cumulative installed base across fermentation-based bioproduction.
Application:
Therapeutic target dictates electrical-parameter validation depth, with gene therapy applications commanding the most stringent reproducibility documentation.
- Gene Therapy:Viral and non-viral vector manufacturing requires pulse-to-pulse consistency within tight tolerances to ensure transduction efficiency batch-to-batch. FDA guidance on cell-and-gene therapy process validation is accelerating instrument procurement across United States pharmaceutical facilities.
- Cell Transfection:Research-grade nucleic acid delivery for protein expression and knockdown studies represents the volume anchor across academic procurement networks.
- Vaccine Development:mRNA and DNA vaccine platforms utilize electroporation for both antigen delivery and manufacturing-stage plasmid production.
- Cancer Treatment:Electrochemotherapy and tumor-infiltrating lymphocyte engineering drive specialized high-field applications.
Cell transfection commands the broadest installed base across research settings. Gene therapy applications are climbing the fastest as clinical manufacturing scales.
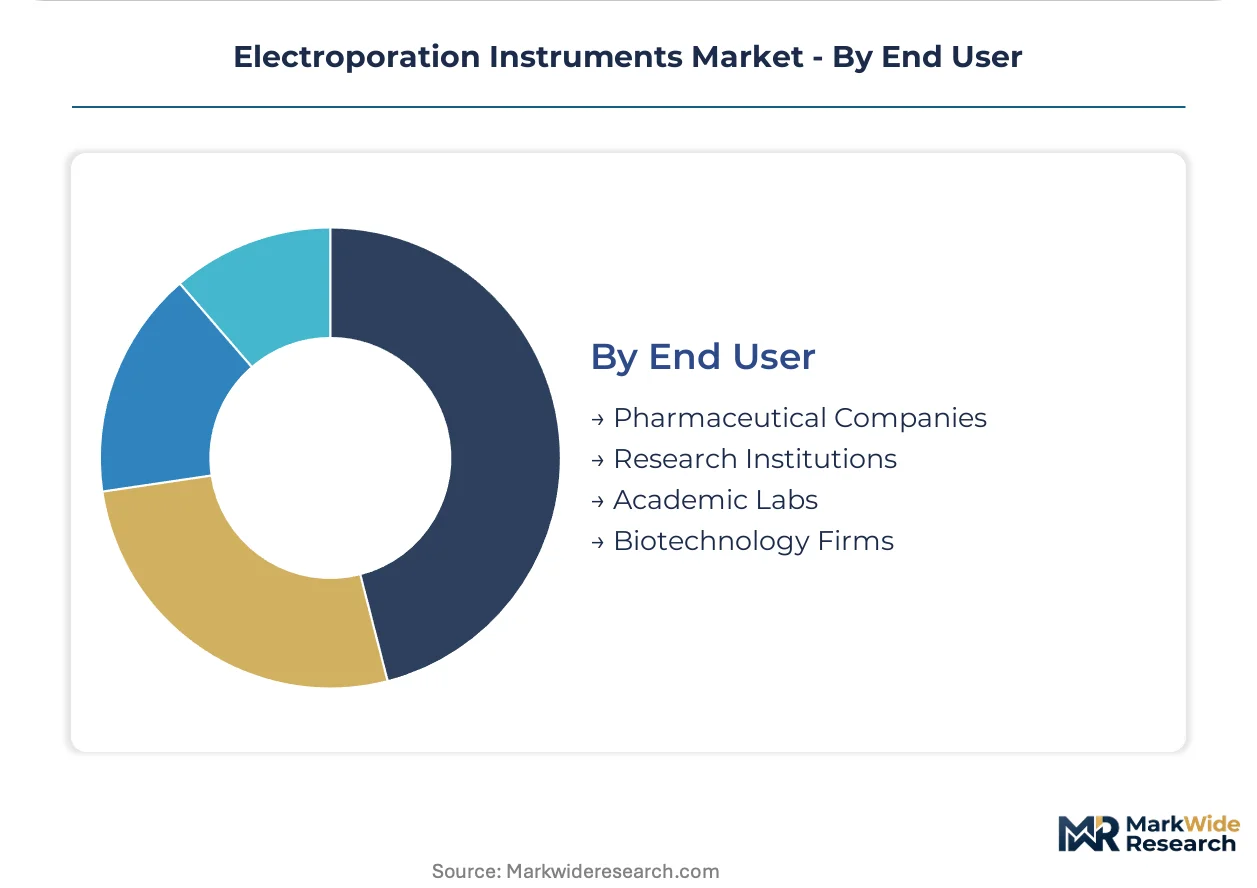
End User:
Buyer type determines procurement evaluation criteria, balancing capital constraints against regulatory documentation requirements.
- Pharmaceutical Companies:Integrated workflow procurement with ISO 13485-certified vendors dominates capital allocation for clinical manufacturing scale-up. United States and Chinese pharmaceutical firms are consolidating supplier relationships around vendors with comprehensive quality-system documentation.
- Research Institutions:Grant-funded acquisition prioritizes protocol flexibility and multi-user accessibility over GMP compliance.
- Academic Labs:Individual investigator grants drive fragmented purchasing with strong price sensitivity and limited service contract attachment.
- Biotechnology Firms:Venture-backed cell therapy developers favor equipment-as-a-service structures to preserve cash runway for regulatory milestones.
Academic labs represent the most mature penetration. Biotechnology firms are the fastest-expanding customer segment as Series B-stage companies build manufacturing capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's life sciences tax incentive zones and China's Hainan Free Trade Port are concentrating electroporation instrument demand around cell therapy manufacturing clusters. Regulatory harmonization pressures are reshaping procurement patterns across pharmaceutical hubs.
United States
FDA process-validation requirements for cell-and-gene therapy production are accelerating replacement of research-grade equipment with clinical-grade systems. The 21st Century Cures Act framework shapes electrical-parameter documentation standards for ATMP manufacturing. Boston and San Diego clusters host Series B-stage biotechnology firms favoring equipment-as-a-service contracting to preserve cash runway.
Germany
EMA's evolving GMP annexes for advanced therapies are mandating electrical-parameter traceability that exceeds current FDA expectations. The country's medical device regulation under MDR constrains notified body interpretation timelines for high-voltage platform certifications. Heidelberg and Munich pharmaceutical corridors concentrate CRISPR protocol standardization demand across academic procurement networks.
China
NMPA streamlined registration pathways for innovative medical devices are attracting instrument vendors to establish localized technical support. The Hainan Free Trade Port and Greater Bay Area pilot zones offer tariff advantages for biopharma infrastructure investment. Shanghai and Suzhou manufacturing clusters are scaling mRNA vector production capacity with field strength requirements above 1 kV/cm.
India
CDSCO's medical device registration simplification and PLI scheme incentives for biopharma infrastructure are drawing calibration service localization. The country's national pharmaceutical regulator is aligning with ISO 13485 quality-system expectations for clinical-grade procurement. Hyderabad and Bengaluru biotech corridors are emerging as CDMO destinations for contract manufacturing scale-up.
Switzerland
Swissmedic's ATMP framework interpretation shapes electrical-validation protocols for European market access. The country's precision manufacturing base concentrates proprietary cartridge architectures that lock buyers into captive supply relationships. Basel and Zurich pharmaceutical clusters anchor integrated workflow procurement across cell therapy manufacturing suites.
Electroporation Instruments Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument tiers. The vendor base stratifies between multi-product life sciences platforms and dedicated electroporation technology developers. Three archetypes dominate: diversified workflow integrators, pulsed-field protocol specialists, and high-throughput manufacturing-scale providers. Consolidation pressure is driving M&A activity around consumable cartridge technologies, while capacity expansion concentrates in Swiss and German manufacturing footprints.
Within the diversified conglomerate tier, Lonza and Thermo Fisher Scientific Inc. exemplify integrated workflow positioning across cell therapy manufacturing suites. Bio-Rad Laboratories, Inc. represents the research-market specialist archetype with deep pulsed-field protocol concentration. These three companies anchor the competitive structure, with Lonza leveraging manufacturing scale, Thermo Fisher extending channel control into academic networks, and Bio-Rad maintaining research-grade specialization.
| Leading Market Players |
|---|
| Lonza |
| BEX Co. Ltd. |
| Bio-Rad Laboratories, Inc. |
| Harvard Bioscience Inc. |
| Eppendorf AG |
| Thermo Fisher Scientific Inc. |
| MaxCyte, Inc. |
| Celetrix LLC |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Clinical-grade procurement mandates from FDA and EMA are compressing vendor lead times for ISO 13485-certified systems, forcing manufacturers to hold finished-goods inventory in Switzerland and Germany and elevating pricing for immediate availability against standard-queue delivery.
Pricing Analysis
Expedited lead-time premiums of fifteen to twenty percent separate immediate-delivery clinical-grade units from standard-queue orders in the United States and German markets. Three-tier pricing structure across GMP-certified, research-grade, and portable field units reflects documentation burden and voltage ceiling differentiation. Cost compression in research-grade bench-top segments is intensifying because academic procurement consolidation favors multi-unit tenders with service bundling. Biotechnology firms with venture-backed cash constraints exhibit highest price sensitivity, while pharmaceutical manufacturing procurement prioritizes electrical-parameter traceability over marginal unit cost.
Supply Chain Analysis
High-voltage capacitor and precision electrode supply rests on Swiss and German specialty component manufacturers with limited secondary sourcing. Proprietary cartridge architectures draw from single-source injection molding and electrode fabrication in Basel and Zurich manufacturing corridors. Single-source vulnerability concentrates in ceramic substrate and biocompatible polymer feedstocks for clinical-grade consumables. Distribution runs through authorized service networks with embedded calibration capabilities rather than arms-length wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cartridge manufacturing capacity in Switzerland and Germany operates at effective utilization ceilings, propping pricing power for vendors with captive consumable production and creating queuing premiums for non-integrated buyers.
For Market Incumbents: To counter equipment-as-a-service contracting displacement among Series B-stage biotechnology firms, anchor recurring revenue through embedded consumable minimums and remote diagnostic subscriptions. Deepen backward integration into precision electrode fabrication to secure cartridge supply against Swiss manufacturing bottlenecks. Prioritize ISO 13485 certification maintenance ahead of EMA GMP annex enforcement timelines to defend clinical-grade procurement positioning. For New Entrants and Emerging Players: CDSCO's streamlined medical device registration pathways in India open a window for localized technical support and calibration service establishment without European MDR notification body delays. Target underpenetrated CDMO corridors in Hyderabad and Bengaluru with field-strength-flexible platforms that accommodate both research-grade screening and early-phase manufacturing scale-up. Lead with equipment-as-a-service financing structures to match incumbent contracting flexibility. For Investors and Strategic Acquirers: The window for entry favors consumable cartridge technology specialists with precision electrode IP and established Swiss or German manufacturing relationships. Long-term viability hinges on electrical-parameter software traceability capabilities as EMA documentation requirements exceed FDA expectations. Watch FDA-EMA electrical-parameter harmonization negotiations as the inflection signal for platform architecture consolidation versus fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Quality System Certification | EMA's GMP annex enforcement elevates documentation completeness above price in clinical procurement evaluations. |
| Cartridge Manufacturing Backward Integration | Captive electrode fabrication in Basel-Zurich corridor insulates against Swiss specialty component bottlenecks. |
| Equipment-as-a-Service Contracting | Boston and San Diego biotechnology clusters prioritize balance-sheet preservation over capital purchase ownership. |
| Digital Pulse-Shape Software Development | Real-time impedance monitoring capabilities compress protocol development cycles for CRISPR editing workflows. |
| India Technical Support Localization | CDSCO registration pathways and PLI incentives attract calibration service establishment outside European MDR timelines. |
Methodological Framework
FDA guidance documents, EMA ATMP framework publications, and ISO 13485 certification registries formed the secondary backbone for regulatory pathway mapping. Primary interviews with cell therapy manufacturing executives, biomedical engineering directors at contract development organizations, GMP quality assurance leads, and academic CRISPR protocol specialists combined with secondary validation across instrument vendor technical specifications and hospital procurement databases. Bottom-up unit shipment estimates and top-down pharmaceutical capital expenditure allocations were triangulated to anchor market sizing.
Historical trendline analysis of gene therapy manufacturing capacity expansion and mRNA vector production buildout informed growth trajectory assumptions across the projection horizon. Segmentation modeling incorporated product form factor, pulse waveform architecture, therapeutic application target, and end-user procurement type with voltage output tier and certification grade as electroporation-specific dimensions. CAGRs were derived from pharmaceutical facility buildout pipelines and CDMO electroporation platform procurement disclosures.
The model assumes a particular technology adoption path; alternative pathways for nanosecond pulse organelle-targeting systems would alter the outlook if primary cell immunotherapy manufacturing shifts away from square-wave membrane permeabilization. Forecasts reflect assumptions about regulatory harmonization timing and cartridge supply chain stability. A small set of triggers—EMA GMP annex finalization, FDA process-validation guidance revision, and Swiss-German manufacturing capacity expansion announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Pathology Instruments Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Visual Field Testing Equipment Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Global Wavefront Aberrometers Market