
 At-Home Blood Collection Kits and Devices Market | 2026-2036
At-Home Blood Collection Kits and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
At-Home Blood Collection Kits and Devices Market Insights
Buyer concentration across telehealth providers is restructuring procurement dynamics for at-home blood collection platforms. BD leverages its manufacturing scale to supply institutional telehealth networks with integrated lancet and micro-container systems. Tasso differentiates through proprietary capillary action technology that eliminates venipuncture for chronic disease monitoring panels. YourBio Health specializes in dried blood spot card formats that clinical laboratories accept for remote lipid and HbA1c testing workflows.
At-home blood collection kits and devices encompass sterile, single-use systems engineered to extract defined blood volumes—typically 20–500 µL for capillary methods—through skin incision or vacuum-assisted micro-needling, with anticoagulant stabilization and ambient-temperature transport compatibility as core functional parameters. These systems serve the industrial purpose of decentralizing diagnostic sample acquisition from phlebotomy centers to patient-controlled environments. Capillary blood collection dominates current volume due to lower technical barriers for self-administration, while venous blood collection commands premium positioning where higher analytical sensitivity is required. Dried blood spot cards represent the fastest-growing format as specialty pharmacies and research organizations adopt them for therapeutic drug monitoring and population genetic screening programs.
FDA 510(k) clearance pathways and Clinical Laboratory Improvement Amendments standards govern US market access, with the former dictating device safety thresholds and the latter determining which collected samples qualify for reimbursable analysis. The European Medical Device Regulation and In Vitro Diagnostic Regulation impose additional conformity requirements on manufacturers distributing through EU health clinics and online retailers. Stakeholders must monitor evolving payer policies on remote sample validity, as reimbursement acceptance will determine whether direct-to-consumer channels sustain their current expansion trajectory or consolidate around clinically validated telehealth integrations.
Market Dynamics
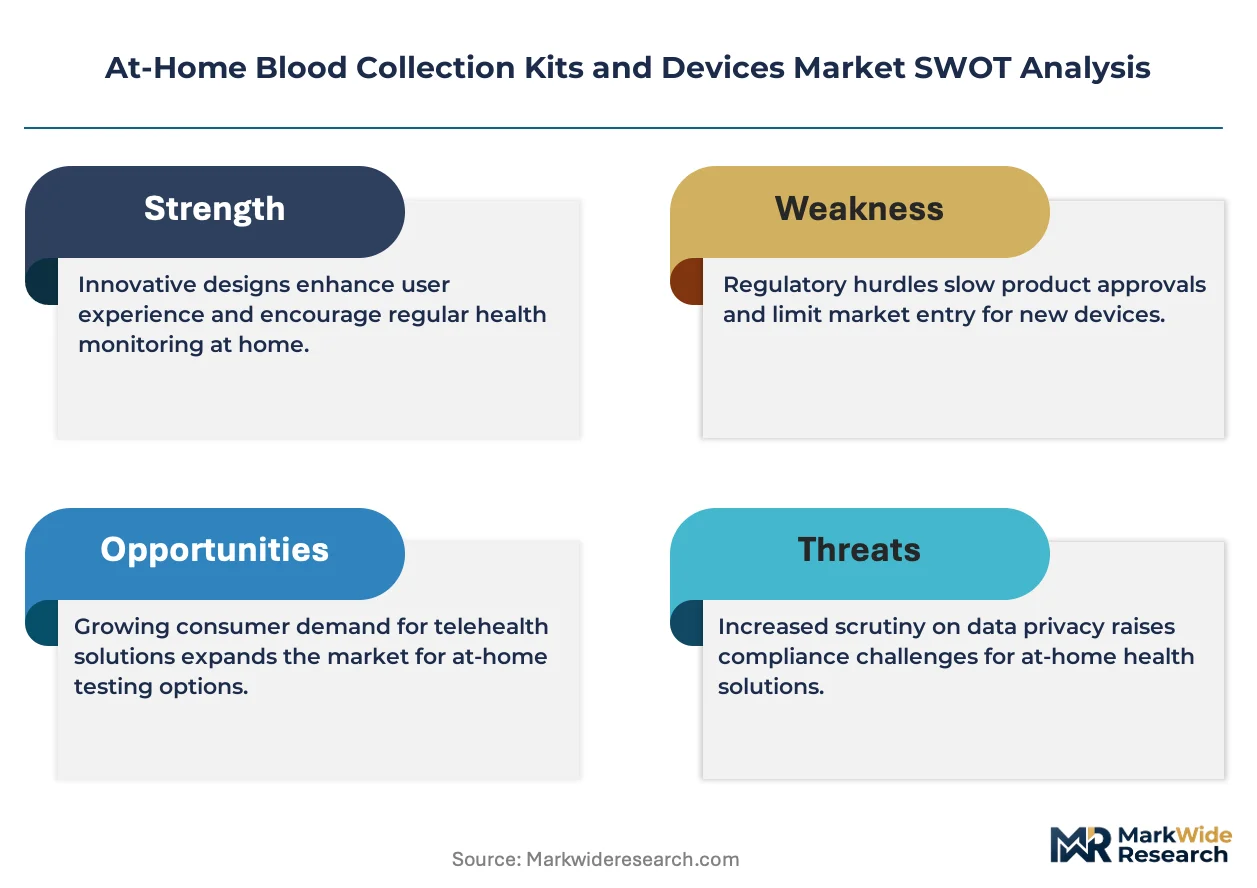
Telehealth platform consolidation is compressing procurement cycles for at-home blood collection systems, as integrated care networks demand validated, reimbursable sample workflows rather than standalone consumer devices.
Growth Catalysts
- Medicare reimbursement expansion:CMS guidance on remote patient monitoring is validating capillary-based collection for chronic disease management, pulling device volumes into institutional channels.
- Capillary action engineering:Advances in microfluidic channel design are eliminating venipuncture requirements for HbA1c and lipid panels, collapsing the skill barrier for self-collection.
- Specialty pharmacy networks:Mail-order therapeutic drug monitoring programs are standardizing dried blood spot workflows for immunosuppressant and anticoagulant surveillance.
Market Restraints
- Anticoagulant stabilization chemistry:Proprietary buffer formulations from single-source suppliers create input cost volatility and formulation lock-in for device manufacturers.
- Sample validity disputes:Payer skepticism toward capillary-derived values versus venous benchmarks limits reimbursable test menus and constrains addressable diagnostic panels.
- Transport temperature requirements:Ambient stability claims face CLIA scrutiny, forcing redundant cold-chain infrastructure that erodes cost advantages of remote collection.
Strategic Opportunities
- Rural health clinic integration:Federally Qualified Health Centers in underserved US counties are piloting at-home collection to extend phlebotomy reach without capital investment in draw stations.
- Population genetic screening:Direct-to-consumer genomic platforms are adopting dried blood spot cards as an alternative to saliva collection for epigenetic and carrier screening applications.
- FDA OTC pathway evolution:Draft guidance on over-the-counter diagnostic devices is creating a regulatory tailwind for manufacturers seeking to bypass prescription-channel friction.
Industry Challenges
- Clinical laboratory integration:LIS compatibility and sample tracking protocols require bespoke API development for each reference lab partner, stretching engineering bandwidth.
- Human factors validation:FDA 510(k) submissions demand extensive usability studies with lay users, extending certification timelines and pre-revenue burn rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | At-Home Blood Collection Kits and Devices Market |
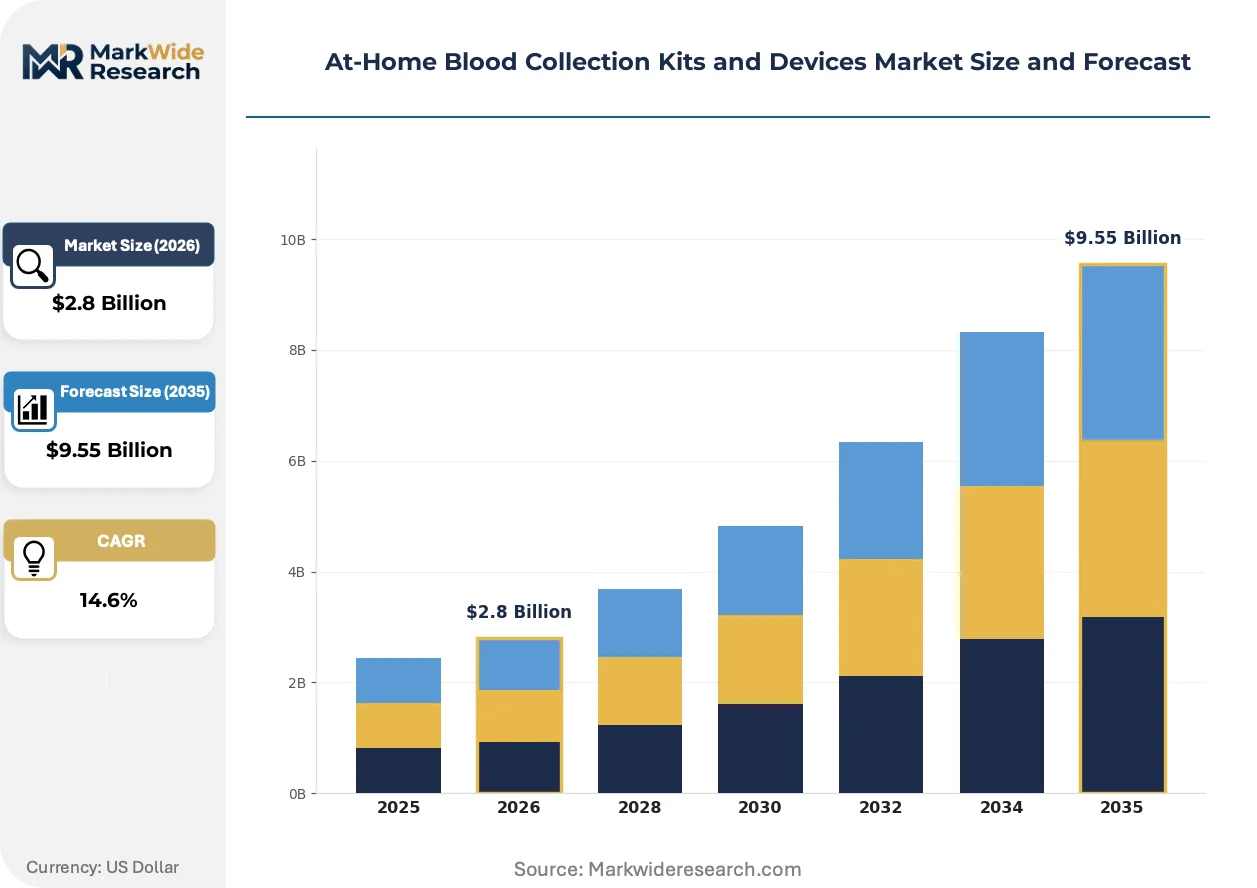
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary Blood Collection, Venous Blood Collection, Micro-Containers, Dried Blood Spot Cards, Lancets Application: Chronic Disease Monitoring, Infectious Disease Testing, Genetic Screening, Wellness Testing, Therapeutic Drug Monitoring End User: Homecare Patients, Telehealth Providers, Clinical Laboratories, Specialty Pharmacies, Research Organizations Distribution Channel: Online Retailers, Pharmacies, Direct-to-Consumer, Medical Supply Distributors, Health Clinics |
| Companies Covered | BD, Tasso, Trajan Group Holdings, YourBio Health, Capitainer, A. Menarini Diagnostics, R-Biopharm, Owen Mumford, Spot On Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
At-Home Blood Collection Kits and Devices Market Trends and Innovations
Device architectures are converging around single-use, fully integrated systems that embed lancet, collection vessel, and stabilization chemistry into disposable cartridges, eliminating user assembly errors and contamination risk.
Micro-needle array technology is absorbing development investment from chronic disease monitoring programs seeking painless, repeatable sampling without skin preparation. Geriatric and pediatric telehealth providers are piloting silicon-based microneedle patches for HbA1c surveillance at four-week intervals. The technology is absorbing volume from traditional spring-loaded lancets in segments where pain tolerance limits compliance.
REACH compliance deadlines for chemical substances in medical devices are forcing reformulation of anticoagulant coatings and plasticizers used in collection vessels. European manufacturers face accelerated testing timelines for SVHC substitution in capillary tubes and desiccant housing materials. Dried blood spot card suppliers serving EU specialty pharmacies are prioritizing cellulose substrate alternatives to maintain market access.
Hospital-at-home programs are unbundling diagnostic procurement from traditional reference laboratory contracts, creating direct purchasing relationships with device manufacturers. Health system supply chains are consolidating vendor lists around platforms with validated transport logistics and integrated result reporting. This pattern is most visible in US Medicare Advantage networks where capitated payments incentivize total cost reduction across the diagnostic episode.
At-Home Blood Collection Kits and Devices Market Segmentation
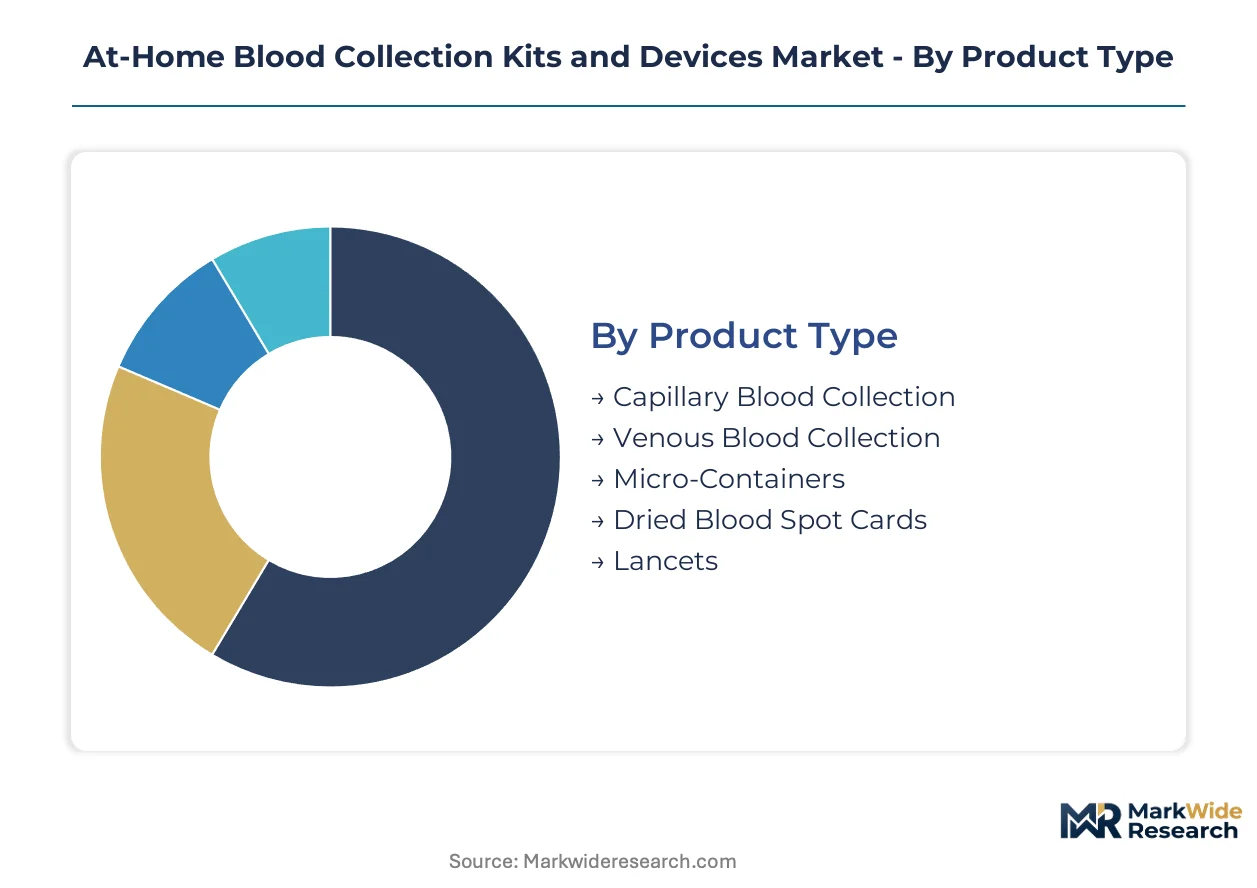
Segmentation in at-home blood collection reveals how procurement power concentrates across telehealth networks and specialty pharmacies. Product architecture choices directly determine reimbursement eligibility and transport logistics feasibility.
Product Type:
Buyers prioritize collection reliability and ambient stability over unit cost when selecting format categories for chronic disease panels.
- Capillary Blood Collection:Skin-incision methods using spring-loaded lancets or vacuum-assisted micro-needles extract 20–500 µL volumes without venipuncture. US Medicare Advantage networks favor this format for HbA1c and lipid monitoring due to self-administration feasibility and lower skill barriers.
- Dried Blood Spot Cards:Cellulose or synthetic substrates absorb defined blood volumes for ambient-temperature transport without cold-chain infrastructure. Specialty pharmacies in Germany and the Netherlands standardize this format for immunosuppressant therapeutic drug monitoring programs.
- Venous Blood Collection:Vacuum tube systems requiring phlebotomy-level technique command premium positioning where analytical sensitivity demands higher sample volume.
- Micro-Containers:Anticoagulant-coated vessels designed for precise micro-volume collection integrate with automated laboratory analyzers.
- Lancets:Single-use incision devices with calibrated blade depths reduce pain scores and improve compliance in pediatric and geriatric populations.
Volume sits with capillary systems; growth tilts toward dried blood spot cards.
Application:
Reimbursement policy determines which diagnostic panels sustain viable economics for remote sample workflows.
- Chronic Disease Monitoring:HbA1c, lipid, and renal function panels dominate institutional procurement volumes. US CMS remote patient monitoring guidance validates capillary-derived values for diabetes management, pulling device demand into Medicare-reimbursable channels.
- Therapeutic Drug Monitoring:Immunosuppressant and anticoagulant surveillance programs at mail-order pharmacies require precise analyte stability during ambient transport. Dried blood spot formats gain preference over traditional plasma tubes for cyclosporine and tacrolimus testing.
- Infectious Disease Testing:HIV and hepatitis C screening applications face payer skepticism regarding capillary sample equivalence to venous benchmarks.
- Genetic Screening:Carrier and pharmacogenomic testing platforms adopt blood spots as alternatives to saliva collection for epigenetic analysis.
- Wellness Testing:Direct-to-consumer hormone and vitamin panels operate outside reimbursement frameworks, constraining sustainable pricing power.
Revenue concentrates in chronic disease monitoring; therapeutic drug monitoring climbs the fastest.
End User:
Procurement scale and technical validation requirements fragment across institutional versus consumer-directed channels.
- Telehealth Providers:Integrated care networks demand FDA 510(k)-cleared devices with validated laboratory information system APIs. Procurement concentrates among US-based virtual-first health plans seeking capitated cost reduction.
- Specialty Pharmacies:Mail-order drug monitoring programs require ambient-stable collection formats with chain-of-custody documentation. European pharmacy networks drive dried blood spot standardization for transplant medication surveillance.
- Homecare Patients:Individual purchasers prioritize pain reduction and simplicity over analytical menu breadth.
- Clinical Laboratories:Reference labs impose stringent sample validity protocols that limit reimbursable test menus for capillary-derived specimens.
- Research Organizations:Population genetic studies and biomarker discovery programs value dried blood spots for biobanking efficiency and participant convenience.
Telehealth providers command current volume; specialty pharmacies represent the steepest expansion trajectory.
Distribution Channel:
Channel selection determines regulatory pathway complexity and payer reimbursement access.
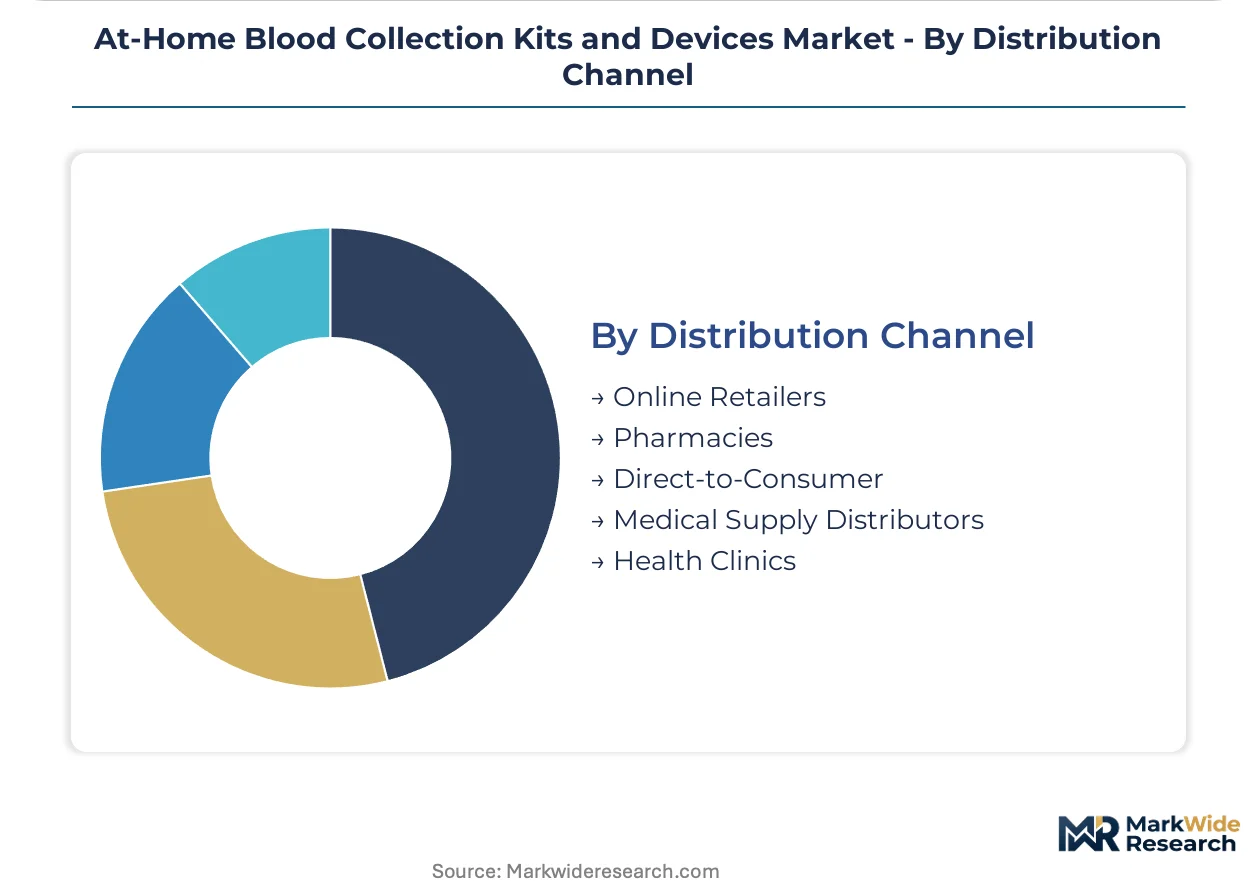
- Direct-to-Consumer:Subscription-based diagnostic platforms bypass prescription requirements through wellness framing. FDA draft guidance on over-the-counter diagnostic devices creates regulatory tailwinds for manufacturers seeking to circumvent clinical channel friction.
- Medical Supply Distributors:Institutional procurement through Cardinal Health and McKesson networks requires CLIA-compliant sample handling documentation and validated cold-chain logistics.
- Online Retailers:Amazon and specialized health platforms face state-level laboratory licensing restrictions that constrain test menu breadth.
- Pharmacies:CVS and Walgreens pilot in-store collection coaching services to bridge self-administration skill gaps.
- Health Clinics:Federally Qualified Health Centers in rural US counties deploy at-home collection to extend phlebotomy reach without capital investment in draw stations.
Medical supply distributors anchor institutional volume; direct-to-consumer channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer manufacturing clusters in Germany's industrial heartland supply precision microfluidic components that anchor European device production for capillary blood collection systems.
United States
Medicare Advantage networks in Minnesota and Florida drive institutional procurement volumes for HbA1c monitoring devices. FDA 510(k) clearance timelines shape product launch sequencing for manufacturers targeting remote patient monitoring reimbursement. The Research Triangle Park corridor in North Carolina concentrates contract manufacturing for dried blood spot card substrates.
Germany
Specialty pharmacy networks in Bavaria and Baden-Württemberg standardize ambient-stable collection formats for immunosuppressant therapeutic drug monitoring. ECHA REACH compliance deadlines force reformulation of anticoagulant coatings and plasticizers in collection vessels. The Stuttgart metropolitan region hosts precision injection molding facilities for micro-container production.
Netherlands
Mail-order diagnostic platforms in Randstad urban centers adopt capillary action devices for direct-to-consumer lipid panels. Clinical Laboratory Improvement Amendments equivalence assessments determine reimbursable test menus for Dutch-collected specimens. The Eindhoven high-tech cluster supplies microfluidic channel fabrication equipment to device manufacturers.
Japan
Pediatric telehealth providers in Kanto prefecture pilot silicon-based microneedle patches for pain-reduced HbA1c surveillance. PMDA consultation procedures guide over-the-counter diagnostic pathway submissions for home-use devices. The Osaka-Kobe manufacturing belt produces spring-loaded lancets with calibrated blade depths for geriatric populations.
Australia
Rural health clinics in Queensland and Western Australia deploy at-home collection to extend phlebotomy reach without capital investment in draw stations. TGA conformity assessment procedures align with EU MDR standards for device market authorization. The Melbourne biomedical precinct validates dried blood spot workflows for population genetic screening programs.
At-Home Blood Collection Kits and Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microneedle patch and fully integrated cartridge architectures. The vendor base stratifies across three tiers: diversified medical device conglomerates with manufacturing scale, venture-backed technology specialists with proprietary capillary engineering, and regional contract manufacturers serving private-label distributors. Two dominant competitive moves are reshaping positioning: strategic partnerships with telehealth platforms for validated sample workflows, and vertical integration into anticoagulant stabilization chemistry to reduce input cost volatility.
Among the named players, BD exemplifies the diversified conglomerate archetype with institutional supply chain reach, while Tasso and YourBio Health occupy positions as technology specialists differentiated through proprietary collection architectures. Trajan Group Holdings represents the mid-tier contract manufacturing segment serving European diagnostic networks. These three anchors illustrate how competitive positioning fragments across scale-driven, innovation-driven, and regional-service vectors.
| Leading Market Players |
|---|
| BD |
| Tasso |
| Trajan Group Holdings |
| YourBio Health |
| Capitainer |
| A. Menarini Diagnostics |
| R-Biopharm |
| Owen Mumford |
| Spot On Sciences |
| Others |
Pricing and Supply Chain Analysis
Micro-needle array manufacturing migration from precision machining to semiconductor-style photolithography is collapsing unit economics for capillary collection devices while concentrating production capacity among wafer-fabrication specialists in Germany and Japan. This process shift simultaneously reduces per-unit lancet costs and locks out second-tier contract manufacturers lacking cleanroom infrastructure, reshaping procurement leverage across the device tier.
Pricing Analysis
Warranty and validation-service bundling separates institutional telehealth contracts from direct-to-consumer unbundled hardware sales, with the former commanding premium positioning through CLIA-compliant sample handling documentation. Three-tier pricing structure across premium, standard, and economy levels tracks FDA 510(k) clearance status and laboratory information system integration depth. Cost compression in the standard tier is intensifying because specialty pharmacy networks are consolidating vendor lists around validated ambient-stability claims. Homecare patients exhibit highest price sensitivity, while Medicare Advantage purchasing committees prioritize total episode cost reduction over per-device expenditure.
Supply Chain Analysis
Domestic-content mandates in the US Inflation Reduction Act and India's Production-Linked Incentive scheme for medical devices are forcing reformulation of sourcing strategies for anticoagulant-coated micro-containers. Precision injection molding concentrates in Germany and the Netherlands, while cellulose substrate production for dried blood spot cards draws from Sweden and Finland. Single-source dependency on proprietary buffer formulations from Japanese chemical suppliers creates vulnerability to REACH-related substitution timelines. Distribution runs through Cardinal Health and McKesson networks for institutional channels, with Amazon and specialized health platforms capturing direct-to-consumer volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 510(k) clearance timelines and CLIA validation requirements create a barrier-to-entry moat that rewards early-certification investment and punishes late entrants with extended pre-revenue burn.
For Market Incumbents: Lock in telehealth platform partnerships through exclusive validated-workflow agreements before microneedle patch technology displaces traditional spring-loaded lancets in pediatric and geriatric segments. Backward integration into anticoagulant stabilization chemistry reduces input cost volatility from single-source Japanese suppliers. Capacity addition in North Carolina's Research Triangle Park corridor shortens lead times for dried blood spot card substrates serving Medicare Advantage networks.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models in wellness testing segments where FDA over-the-counter guidance creates regulatory tailwinds bypassing prescription-channel friction. Rural health clinic integration through Federally Qualified Health Center pilot programs represents the most penetrable institutional channel, as these buyers prioritize capital-avoidance over brand recognition. Population genetic screening platforms adopting blood spots for epigenetic analysis offer a specific go-to-market angle with lower clinical validation burdens than chronic disease monitoring.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medical device conglomerates seeking telehealth platform integration capabilities and proprietary capillary engineering IP. Long-term viability hinges on sustained Medicare reimbursement expansion for remote patient monitoring across the analysis window. Acquisition target archetype: venture-backed technology specialists with FDA-cleared microneedle platforms and validated laboratory partnerships. The signal to watch is CMS guidance on capillary-derived sample equivalence to venous benchmarks, which would expand reimbursable test menus and validate premium pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance validates device safety for Medicare Advantage procurement committees. |
| Hospital System Partnership | Integration with LIS platforms locks in reference laboratory sample workflows. |
| CE Marking Pathway | MDR compliance opens EU specialty pharmacy networks for dried blood spot formats. |
| Software Companion Development | API integration with telehealth platforms enables capitated payment capture. |
| Reimbursement Strategy | CMS remote patient monitoring guidance pulls device demand into institutional channels. |
Research Methodology
Document review covered FDA 510(k) filings, CMS Medicare reimbursement guidance, EMA MDR technical documentation, and hospital procurement database extracts, complemented by interviews with telehealth platform executives, clinical laboratory directors, specialty pharmacy procurement managers, and biomedical engineers at Federally Qualified Health Centers. Secondary validation drew from GPO contracts, CLIA laboratory accreditation records, and customs trade data for precision microfluidic component flows. Bottom-up device shipment estimates triangulated against top-down diagnostic test volume projections.
Segment-level outputs across product type, application, end user, and distribution channel dimensions were generated through structured modeling of Medicare Advantage enrollment patterns, specialty pharmacy mail-order growth, and direct-to-consumer subscription adoption. CAGRs were derived from regression analysis of historical reimbursement policy shifts and telehealth platform consolidation rates. Forecast inputs incorporated microneedle patch pain-tolerance compliance data and REACH SVHC substitution timelines for anticoagulant coatings.
The model assumes a particular technology adoption path where silicon-based microneedle arrays displace spring-loaded lancets in chronic disease monitoring; alternative pathways involving vacuum-assisted micro-needles or fully integrated cartridge systems would alter the competitive concentration outlook. Forecasts reflect assumptions regarding sustained CMS reimbursement validation for capillary-derived specimens and stable anticoagulant chemistry supply. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Subdermal Contraceptive Implants Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Brain-On-Chip Model Market
Medical Devices
UHD Surgical Display Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
United States Anesthesia Devices Market
Medical Devices
Submucosal Injections Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Global Liposuction Surgery Devices Market