
 Trauma and Extremities Market | 2026-2036
Trauma and Extremities Market Size, Share, and Industry Trends Forecast 2026-2036
Trauma and Extremities Market Intelligence
A divergence in material science and manufacturing precision is rebalancing the market between premium, patient-specific implants and standardized, volume-driven commodity devices. Stryker Corporation leverages its Mako robotic-arm assisted surgery platform to drive adoption of its high-value joint reconstruction systems. Smith & Nephew specializes in advanced wound management and extremities solutions. Meanwhile, Zimmer Biomet competes on a broad portfolio covering both high-end and standard trauma hardware.
Trauma and extremities devices are implants and instruments designed to treat fractures and conditions of the limbs. These products, often made from titanium alloys or PEEK polymers, restore anatomical function. While plates and screws are a mature product category, biodegradable implants represent a high-growth technology segment. The end-user landscape is also shifting as more procedures migrate to ambulatory surgical centers.
Device market access is governed by stringent regulatory bodies, including the FDA in the United States and the EMA under the MDR framework in Europe. China's NMPA has also implemented stricter clinical trial requirements for Class III medical devices. Future competitive advantage will depend on generating robust clinical evidence to support reimbursement claims in value-based healthcare systems.
Market Dynamics
The fundamental dynamic shaping the trauma and extremities market is the bifurcation between high-cost, technologically advanced implants and volume-driven, standardized devices. This split is driven by parallel demands for patient-specific solutions and cost-containment pressures in high-volume health systems.
Growth Catalysts
- Biodegradable Implants:The development of resorbable materials like magnesium alloys and polymers eliminates the need for secondary removal surgeries, reducing total patient care costs and appealing to ambulatory surgical centers seeking procedural efficiency.
- Expanding Hospital Infrastructure:Rapid construction of new hospitals and surgical facilities in China is creating substantial new demand for a wide range of trauma fixation products, from basic plates and screws to advanced intramedullary nails.
- Value-Based Reimbursement:Healthcare systems are increasingly adopting payment models that reward positive long-term patient outcomes, creating a powerful incentive for devices that can demonstrate superior clinical performance and durability through robust data.
Market Restraints
- Stringent Regulatory Hurdles:The EU's Medical Device Regulation (MDR) imposes extensive clinical data and post-market surveillance requirements, increasing compliance costs and delaying market entry for new and existing devices.
- Raw Material Price Volatility:The cost of medical-grade titanium alloys and PEEK polymer, essential for implant manufacturing, is subject to supply chain disruptions and geopolitical factors, pressuring manufacturer margins.
- Surgical Technique Conservatism:The learning curve associated with new implant systems and surgical techniques can slow adoption among orthopedic surgeons, who often prefer familiar, proven methods and devices for critical procedures.
Strategic Opportunities
- Patient-Specific Instrumentation:Leveraging 3D printing and advanced imaging allows for the creation of custom surgical guides and implants, offering a path to premium pricing and improved surgical accuracy for complex fracture patterns.
- Ambulatory Surgical Center Solutions:Developing pre-sterilized, single-use instrument and implant kits tailored for common extremity procedures addresses the specific needs of ASCs for efficiency, inventory reduction, and predictable costs.
- Clinical Data Generation for NMPA Approval:Investing in local clinical trials in China to meet the NMPA's stricter requirements can provide a significant competitive advantage for accessing the country's high-volume market.
Industry Challenges
- Interoperability of Systems:Ensuring that new robotic-assisted surgical platforms and smart implants can seamlessly integrate with disparate hospital information systems and legacy surgical equipment is a significant technical and logistical hurdle.
- Specialized Talent Scarcity:A shortage of material scientists with expertise in advanced polymers and biocompatible metals, alongside a lack of surgeons trained on new robotic platforms, constrains innovation and adoption.
- Clinical Evidence Demands:Generating the level of long-term clinical evidence required by regulators like the FDA and payers to prove the superiority of a new technology is a costly and time-consuming process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trauma and Extremities Market |
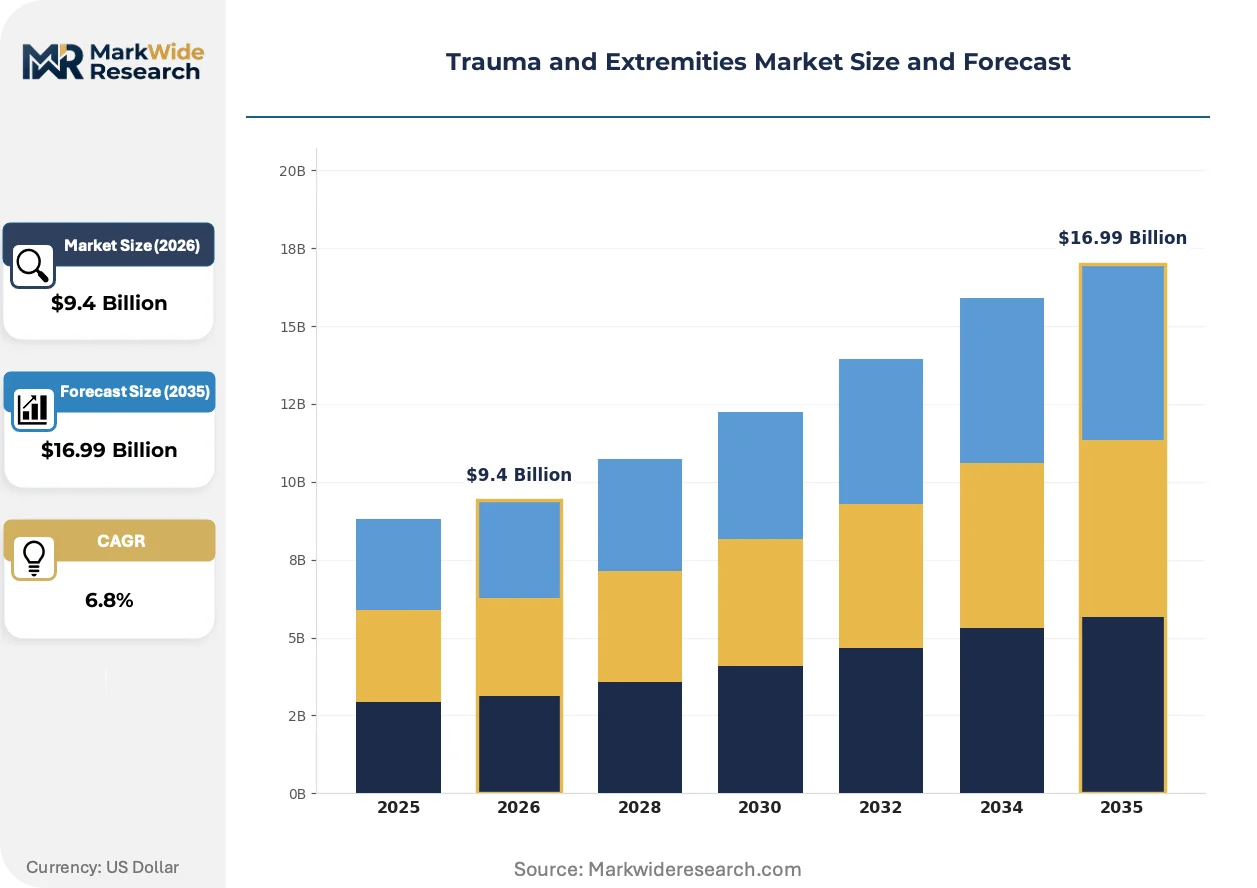
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Intramedullary Nails, External Fixators, Bone Cements Application: Fracture Repair, Joint Reconstruction, Ligament Repair, Soft Tissue Stabilization, Bone Grafting End User: Orthopedic Clinics, Trauma Centers, Ambulatory Surgical Centers, Specialized Hospitals, Rehabilitation Facilities Technology: Minimally Invasive Surgery, Computer-Assisted Surgery, Biodegradable Implants, 3D Printing, Navigation Systems |
| Companies Covered | Smith & Nephew, Integra LifeSciences, DePuy Synthes, Enovis Corporation, Arthrex, Stryker Corporation, Medtronic, Orthofix Medical, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trauma and Extremities Market Strategic Shifts & Innovations
Material science advancements and data-driven healthcare economics are reshaping competitive positioning. The market is simultaneously rewarding innovations in biocompatible materials and manufacturing precision while also supporting the scale advantages of standardized, high-volume device production.
Biodegradable implants, crafted from resorbable polymers or magnesium alloys, are designed to provide temporary fracture support before safely dissolving within the body. Orthopedic surgeons are adopting these devices for specific non-load-bearing applications, particularly in pediatric orthopedics, to eliminate the need for secondary hardware removal surgeries. This technology is absorbing the market share previously occupied by permanent titanium implants in select indications.
The European Union's Medical Device Regulation (MDR) has intensified scrutiny on clinical evidence and lifecycle management for all medical devices. This framework forces manufacturers to conduct more rigorous clinical evaluations and post-market surveillance to obtain or maintain CE marking. Class III devices, such as complex joint implants, face the highest burden, compelling some firms to prune less profitable product lines within the European market.
A procedural shift is accelerating as payers incentivize the migration of less complex fracture cases from inpatient hospitals to more cost-effective ambulatory surgical centers (ASCs). This change disrupts traditional sales channels that were built around large hospital procurement departments, creating an opening for suppliers with efficient, kit-based solutions. The trend is most advanced in the United States healthcare system, where ASCs prioritize operational speed and predictable supply costs.
Trauma and Extremities Market Segmentation
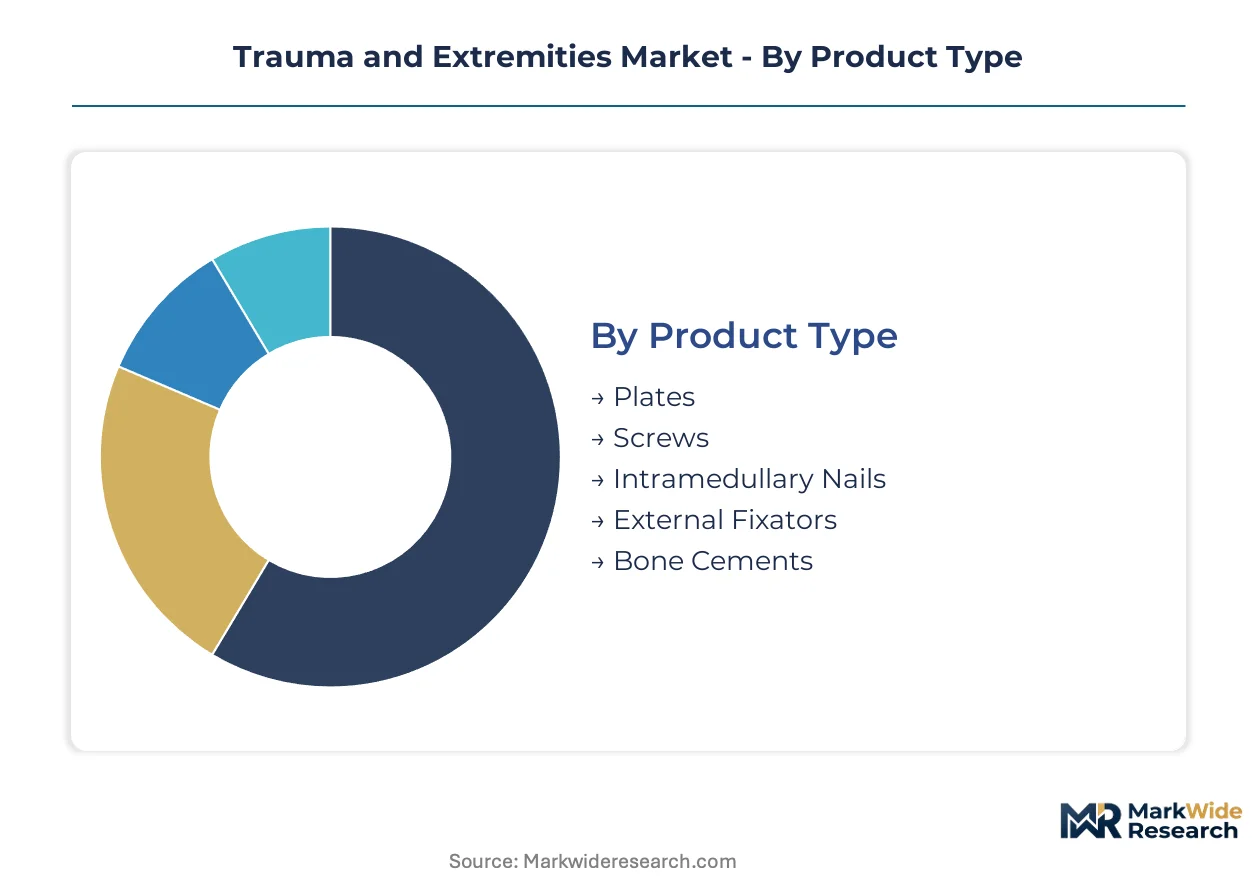
The Trauma and Extremities Market is segmented to reflect the diverse needs of patients and healthcare providers. This segmentation highlights the ongoing tension between highly customized, patient-specific solutions and standardized, cost-effective devices. Understanding these distinctions is crucial for strategic market positioning.
Product Type:
The product type segmentation reveals a spectrum from foundational fixation hardware to advanced internal supports, reflecting the customization-versus-standardization dynamic.
- Plates:These load-bearing devices, often made from titanium alloys, provide rigid fixation for bone fragments. Demand concentrates in China's rapidly expanding hospital system for basic fracture repair procedures.
- Intramedullary Nails:Designed as internal splints for long bone fractures, these devices are inserted into the bone marrow cavity. Their adoption is high in specialized trauma centers for complex, high-energy injuries.
- Screws:Essential for securing plates and fragments, screws come in various sizes and materials, offering versatile fixation solutions across numerous indications.
- External Fixators:These systems provide temporary or definitive stabilization for severe open fractures, utilizing pins inserted through the skin and bone connected to an external frame.
- Bone Cements:Primarily polymethyl methacrylate (PMMA) based, bone cements are used to fill bone voids and secure implants, particularly in joint fixation.
Most installed capacity flows through Plates. Expansion is steepest in Intramedullary Nails.
Application:
The application segment delineates the primary clinical uses of trauma and extremities devices, with distinct volume and value profiles.
- Fracture Repair:This segment involves restoring the anatomical integrity of bones after traumatic injury using various fixation devices. Demand for fracture repair is high in ambulatory surgical centers and China's new hospitals.
- Joint Reconstruction:These procedures replace or resurface damaged joint components, typically due to arthritis or severe trauma. Specialized orthopedic hospitals in countries with aging populations drive demand for these complex interventions.
- Ligament Repair:This application focuses on restoring stability to damaged soft tissues, particularly after sports-related injuries or other trauma.
- Soft Tissue Stabilization:Devices in this category provide support and fixation for injured soft tissues, aiding in the healing process post-trauma.
- Bone Grafting:This application involves using bone tissue to promote healing and fill defects, often following complex fractures or tumor resections.
Demand for Fracture Repair continues to drive overall market volume, while innovation in Joint Reconstruction is creating new therapeutic avenues.
End User:
The end-user segmentation highlights the evolving landscape of care delivery, influenced by cost pressures and procedural complexity.
- Ambulatory Surgical Centers:These outpatient facilities perform less complex surgical procedures, emphasizing efficiency and cost-effectiveness. The US healthcare system is a significant driver for device adoption in these settings.
- Trauma Centers:Specialized facilities equipped for severe and life-threatening injuries, requiring a broad range of advanced fixation devices. Major metropolitan areas in countries like Germany and the United States house numerous such centers.
- Orthopedic Clinics:These facilities primarily handle consultations, diagnostics, and minor procedures, often serving as referral points for more complex surgeries.
- Specialized Hospitals:Hospitals with dedicated orthopedic departments handle complex surgeries, long-term patient care, and advanced reconstructive procedures.
- Rehabilitation Facilities:These centers focus on post-operative recovery and functional restoration, playing a crucial role in patient outcomes after trauma.
The shift toward outpatient care benefits Ambulatory Surgical Centers, while Trauma Centers remain critical for complex, high-acuity cases.
Technology:
Technological advancements are reshaping treatment paradigms, with a focus on precision, faster recovery, and improved patient outcomes.
- Biodegradable Implants:Crafted from resorbable polymers or magnesium alloys, these implants provide temporary support before dissolving. Demand for these devices is expanding within ambulatory surgical centers and for pediatric orthopedic applications.
- 3D Printing:This technology enables the creation of custom surgical guides and patient-specific implants, enhancing precision for complex fracture patterns. Premium pricing segments in countries like the United States leverage these advanced solutions.
- Minimally Invasive Surgery:Techniques that use smaller incisions, reducing patient trauma and accelerating recovery times for various procedures.
- Computer-Assisted Surgery:Robotic platforms and advanced imaging systems enhance surgical precision and consistency, particularly in joint reconstruction.
- Navigation Systems:These systems provide real-time intraoperative guidance, improving the accuracy of implant placement and reducing surgical complications.
Disruptive innovation from Biodegradable Implants is altering material science, while 3D Printing is enabling greater surgical precision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A specialized workforce of orthopedic surgeons and medical device engineers anchors the market across several key geographies. These regions combine advanced healthcare infrastructure with significant patient populations requiring trauma and extremities treatments. Regulatory frameworks and local manufacturing capabilities further shape regional market dynamics.
United States
Demand for patient-specific implants and efficient fracture repair procedures drives the market in the United States. The FDA's stringent approval processes ensure device safety and efficacy, influencing product development cycles. Medical device manufacturing clusters in California and Massachusetts foster innovation in biodegradable materials and 3D printing technologies.
Germany
Advanced joint reconstruction and complex trauma care generate consistent demand within Germany's robust healthcare system. The EU's Medical Device Regulation (MDR) imposes rigorous clinical evidence requirements on manufacturers operating here. Specialized orthopedic device production in Tuttlingen and Bavaria maintains a strong European market presence.
China
Expanding hospital infrastructure and a large patient base significantly increase demand for basic fracture fixation products in China. The NMPA's stricter clinical trial requirements for Class III medical devices now mandate local data generation. Medical device parks in Jiangsu and Guangdong are rapidly increasing domestic production capacity.
India
Growing healthcare access and an increasing incidence of road traffic accidents stimulate demand for trauma and extremities devices across India. The CDSCO regulates medical device imports and manufacturing, promoting local production through initiatives like the PLI scheme. Medical device clusters in Chennai and Hyderabad focus on cost-effective solutions for the region.
Trauma and Extremities Market Key Industry Players
Capital-heavy producers compete with asset-light designers and specialized solution providers in the trauma and extremities market. This market structure reflects a bifurcation between high-volume, standardized hardware and premium, technologically advanced implants. Key archetypes include large diversified healthcare conglomerates, specialized orthopedic device manufacturers, and innovative material science startups. Companies engage in strategic partnerships to expand their product portfolios and pursue geographic expansion into high-growth regions.
On the premium-tier vector, Stryker Corporation leverages its robotic platforms to drive adoption of high-value systems. Smith & Nephew occupies a position focused on advanced wound management and extremities solutions. Zimmer Biomet sits within the broad portfolio segment, offering both high-end and standard trauma hardware across diverse applications.
| Leading Market Players |
|---|
| Smith & Nephew |
| Integra LifeSciences |
| DePuy Synthes |
| Enovis Corporation |
| Arthrex |
| Stryker Corporation |
| Medtronic |
| Orthofix Medical |
| Zimmer Biomet |
| Others |
Cost & Logistics Intelligence
Ambulatory surgical centers' demand for efficiency and cost-effectiveness drives suppliers to develop predictable, kit-based solutions, influencing pricing models. This shift creates distinct pricing tiers based on procedural complexity and end-user needs.
Pricing Analysis
The market exhibits a bundled-versus-unbundled service split, influencing device pricing. Pricing stratifies across premium, standard, and economy tiers, reflecting customization levels for patient-specific implants or the volume scale of standardized hardware. Brand premium, exemplified by Stryker's robotic platforms, commands higher prices for integrated systems. Cost compression in high-volume health systems creates downward pressure on standardized devices, particularly impacting price-sensitive ambulatory surgical centers, while specialized trauma centers prioritize advanced solutions.
Supply Chain Analysis
Reverse logistics for trauma devices primarily involve instrument sterilization and implant disposal, with limited refurbishment for single-use items. Supply centers in China, Germany, and the United States produce most trauma and extremities devices, relying on medical-grade titanium alloys and PEEK polymers. Raw material price volatility and stringent regulatory restrictions, such as the EU MDR, pose structural risks. Distribution runs through direct sales forces to major hospitals and ambulatory surgical centers, complemented by regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trauma and extremities market functions as a stable compounder, driven by consistent demand for fracture repair procedures in an aging global population. Technological advancements in biodegradable implants further sustain long-term expansion.
For Market Incumbents:Extend Mako robotic-arm assisted surgery platform capabilities into new extremity indications to counter specialized startup competition. Invest in robust clinical evidence generation to meet EU MDR requirements and secure value-based reimbursement, defending premium pricing. Deepen vertical integration into advanced material science, particularly biodegradable polymers, to control innovation pathways. Reinforce channel control within ambulatory surgical centers by offering integrated, efficient procedural kits.
For New Entrants and Emerging Players:Launch via specialized distributor networks targeting ambulatory surgical centers in the United States, focusing on efficiency. Develop novel biodegradable implants for pediatric orthopedics, a less saturated segment with high demand for secondary surgery elimination. Offer custom 3D printed surgical guides for complex fracture patterns, providing a premium niche. Focus on pre-sterilized, single-use kits to simplify procurement and reduce overhead for outpatient facilities.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized material science startups developing advanced biodegradable implants and precision manufacturing firms. The market offers long-term viability due to consistent demand for trauma care and ongoing technological innovation. Target companies with strong intellectual property in 3D printing or novel resorbable materials. The signal to watch is accelerated NMPA approval for Class III devices in China, indicating market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Evidence Generation | Ensures reimbursement for high-value devices under value-based healthcare systems. |
| Biodegradable Material R&D | Enables new product lines, reducing secondary surgeries for pediatric patients. |
| 3D Printing Technology Integration | Delivers patient-specific implants, enhancing precision for complex fracture patterns. |
| Ambulatory Surgical Center Partnership | Expands market reach by addressing efficiency and cost needs of ASCs. |
| China Local Clinical Trials | Unlocks access to China's rapidly expanding hospital system and NMPA approvals. |
Research Approach
Direct dialogue with orthopedic surgeons, hospital purchasing committees, medical device engineers, and regulatory affairs leads grounded the primary research. Secondary validation drew from FDA filings, EMA submissions under MDR, NMPA guidelines, and GPO contracts. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data integrity.
The quantitative model produced volume and value projections across the analysis window, segmented by product type, application, end user, technology, and geographic region. Compound annual growth rates were derived from historical trends and anticipated procedure volume changes. Material science advancements and regulatory shifts served as key industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of raw material price volatility or major regulatory shifts. These forecasts reflect assumptions regarding market dynamics and technological adoption. Practitioners should monitor NMPA approval rates and EU MDR compliance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Babesiosis Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Spain Hair Transplant Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Global Sciatica Market
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
ALAD Porphyria Treatment Market