
 Global Sciatica Market | 2026-2036
Global Sciatica Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sciatica Market Foresight
The premium-commodity split in sciatica care is rebalancing around invasive versus non-invasive intervention pathways. Johnson & Johnson leverages its orthopedic portfolio to anchor premium surgical device segments. Teva Pharmaceutical Industries Limited competes through generic oral analgesic scale, sustaining volume leadership in cost-sensitive markets.
Sciatica denotes radiating pain along the sciatic nerve pathway, typically triggered by lumbar disc herniation or spinal stenosis compressing nerve roots at the L4-S1 levels; diagnostic protocols rely on straight-leg raise tests, MRI confirmation, and electromyography to distinguish radiculopathy from referred pain syndromes. Oral analgesics and muscle relaxants occupy mature, high-volume positions with thinning margins, while minimally invasive procedures capture expanding margin pools as ambulatory surgical centers upgrade their interventional capabilities. Nerve blocks and physical therapy equipment segments are gaining traction among orthopedic clinics seeking same-day discharge protocols.
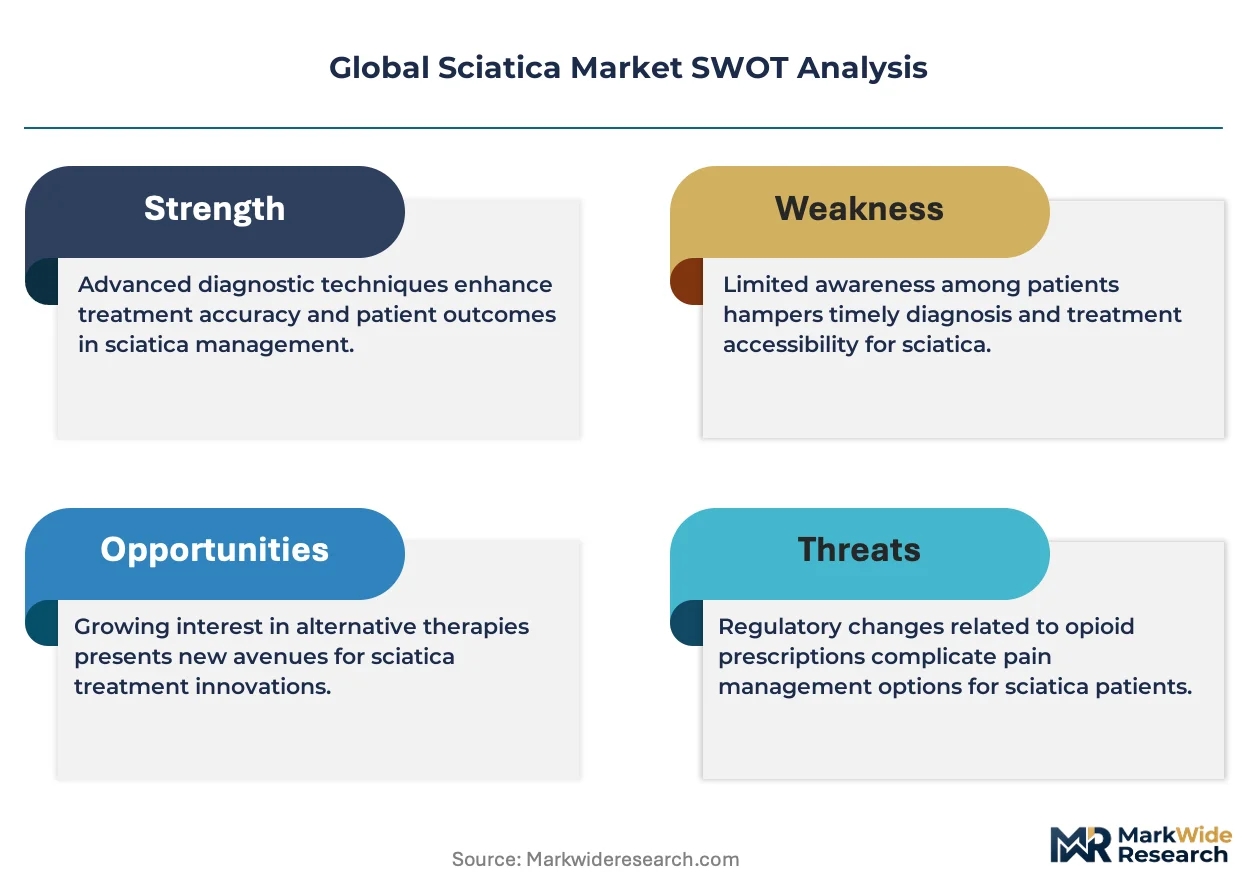
FDA premarket clearance pathways shape device commercialization timelines for spinal implants, while the EU MDR recertification burden is filtering smaller device manufacturers from European market access. The EU AI Act introduces new compliance layers for diagnostic algorithms used in lumbar MRI interpretation. Stakeholders must monitor reimbursement parity between surgical and conservative therapy codes as payors recalibrate value-based thresholds for chronic back pain interventions.
Market Dynamics
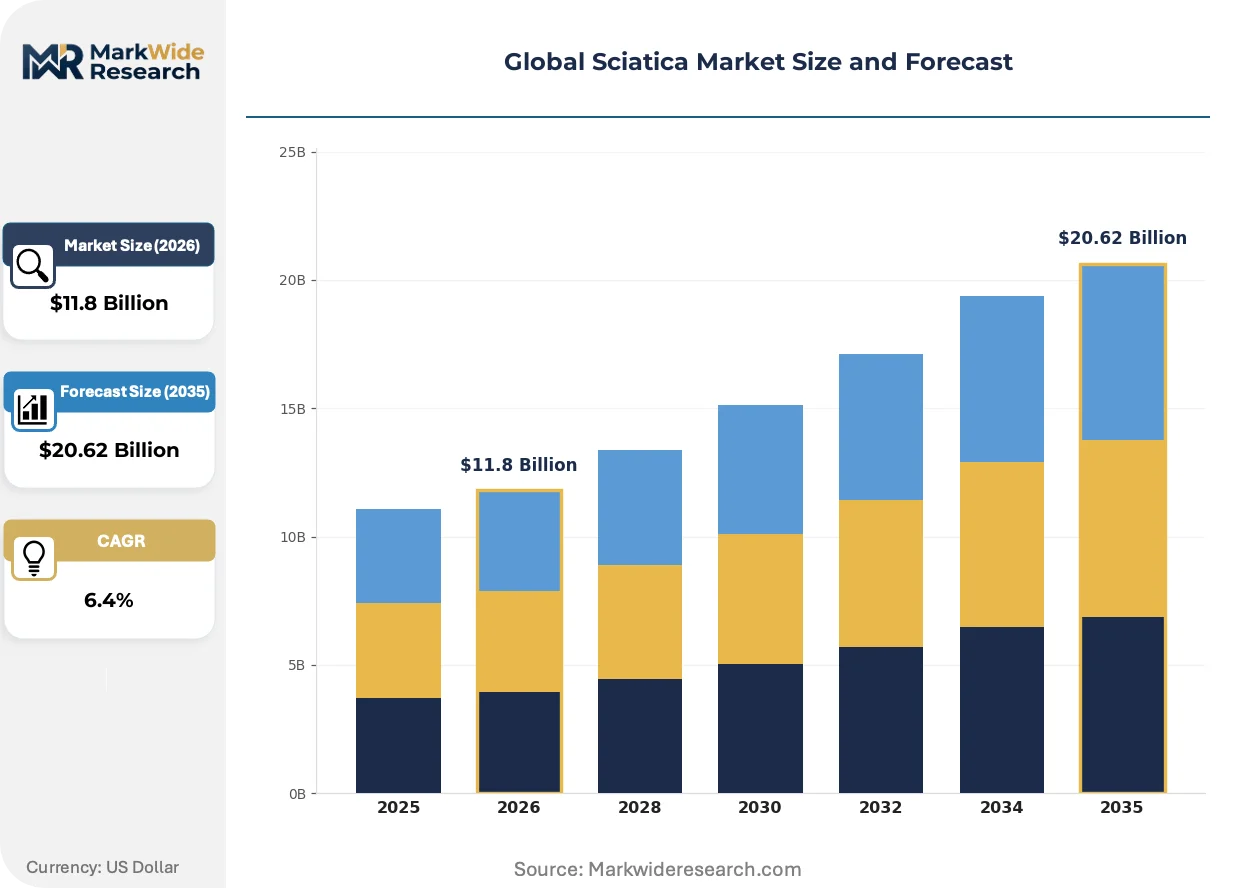
The global sciatica market pivots on a reimbursement recalibration that is compressing surgical procedure volumes while amplifying ambulatory interventional capacity. Pain management clinics and orthopedic ASCs are reconfiguring their service mix around same-day nerve blocks and minimally invasive decompression, responding to payor value-based thresholds that now favor conservative pathways for uncomplicated radiculopathy.
Growth Catalysts
- EU MDR recertification wave:The Medical Device Regulation's tightened premarket scrutiny is filtering marginal spinal implant manufacturers from European market access, concentrating procurement among established suppliers with robust quality management systems.
- Ambulatory surgical center expansion:United States-based ASCs are upgrading interventional suites for fluoroscopy-guided epidural steroid injections and percutaneous discectomy, capturing patients who previously required hospital admission.
- Lumbar MRI AI integration:Diagnostic algorithms for automated disc herniation detection are accelerating radiology throughput and reducing specialist referral bottlenecks in high-volume pain clinics.
Market Restraints
- Opioid prescribing contraction:DEA enforcement and state-level prescription drug monitoring programs have compressed oral analgesic volumes, eliminating a historical revenue bridge for primary care practices managing acute sciatica flares.
- Titanium and PEEK supply concentration:Spinal implant manufacturers remain dependent on a narrow supplier base in Germany and Switzerland for medical-grade polymers and machined components, exposing margin pressure from input cost volatility.
- Spinal fusion efficacy scrutiny:Large-scale orthopedic registry data from Sweden and the United Kingdom has weakened clinical confidence in fusion for isolated disc herniation, dampening surgical device demand in conservative-dominant European markets.
Strategic Opportunities
- India's procedural gap:Lumbar discectomy penetration in tier-2 and tier-3 Indian cities remains below diagnostic capacity, creating whitespace for mobile C-arm-equipped surgical units and tele-radiology partnerships.
- Radiofrequency ablation convergence:Combination devices integrating cooled RF with pulsed radiofrequency modalities are opening multi-lesion treatment protocols for chronic radiculopathy in United States pain management clinics.
- Japan's aging surgical demand:METI reimbursement incentives for day-surgery spinal decompression are aligning hospital capital investment with demographic-driven volume expansion in the Kanto and Kansai regions.
Industry Challenges
- Interventional pain specialist shortage:Fellowship-trained physicians capable of fluoroscopy-guided lumbar procedures remain concentrated in United States coastal metros, constraining ASC expansion into secondary markets.
- EU AI Act diagnostic compliance:Algorithm developers for lumbar MRI interpretation face unresolved classification ambiguity and notified body backlog, delaying commercial deployment timelines.
- Implant-hospital integration complexity:Spinal device vendors must navigate incompatible electronic health record systems and procurement portals across United States health systems, fragmenting account management resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sciatica Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Analgesics, Corticosteroids, Muscle Relaxants, Nerve Blocks, Physical Therapy Equipment Therapy Area: Lower Back Pain, Lumbar Radiculopathy, Degenerative Disc Disease, Spinal Stenosis, Piriformis Syndrome End User: Orthopedic Clinics, Rehabilitation Centers, Pain Management Clinics, Chiropractic Offices, Neurology Centers Delivery Mode: Oral Medication, Injectable Therapies, Physical Therapy Sessions, Minimally Invasive Procedures, Surgical Intervention |
| Companies Covered | Johnson & Johnson, Medtronic plc, Boston Scientific Corporation, Stryker Corporation, Zimmer Biomet, Abbott Laboratories, Teva Pharmaceutical Industries Limited, Pfizer Inc., Sorrento Therapeutics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sciatica Market Shifts & Advancements
Neuromodulation and targeted drug delivery systems are redefining the chronic sciatica treatment hierarchy, displacing open surgical decompression as the default for refractory cases. Device manufacturers are engineering smaller-form-factor implants and bioresorbable carriers that align with ambulatory care economics and shortened recovery expectations.
Closed-loop spinal cord stimulators with evoked compound action potential sensing are electrifying the chronic pain device segment. Pain management clinics in the United States are adopting these systems at accelerating pace for failed back surgery syndrome with radicular components. The technology is compressing traditional tonic stimulation market share by demonstrating superior paresthesia-free pain relief in registry cohorts.
The EU AI Act's risk-based classification framework is reshaping diagnostic software commercialization. Lumbar MRI interpretation algorithms now face conformity assessment requirements that extend development timelines by twelve to eighteen months. European radiology groups are responding by consolidating procurement around vendors with established quality management system certifications, favoring incumbent players over startup entrants.
United States payors are unbundling facility fees from professional fees for interventional spine procedures, creating direct price transparency pressures on ASCs. Pain management groups in Texas and Florida are responding with vertically integrated practice models that capture imaging, injection, and physical therapy revenue within single tax identification numbers. This consolidation is visible most acutely in metropolitan markets where commercial insurance concentration enables direct contracting leverage.
Global Sciatica Market Segmentation
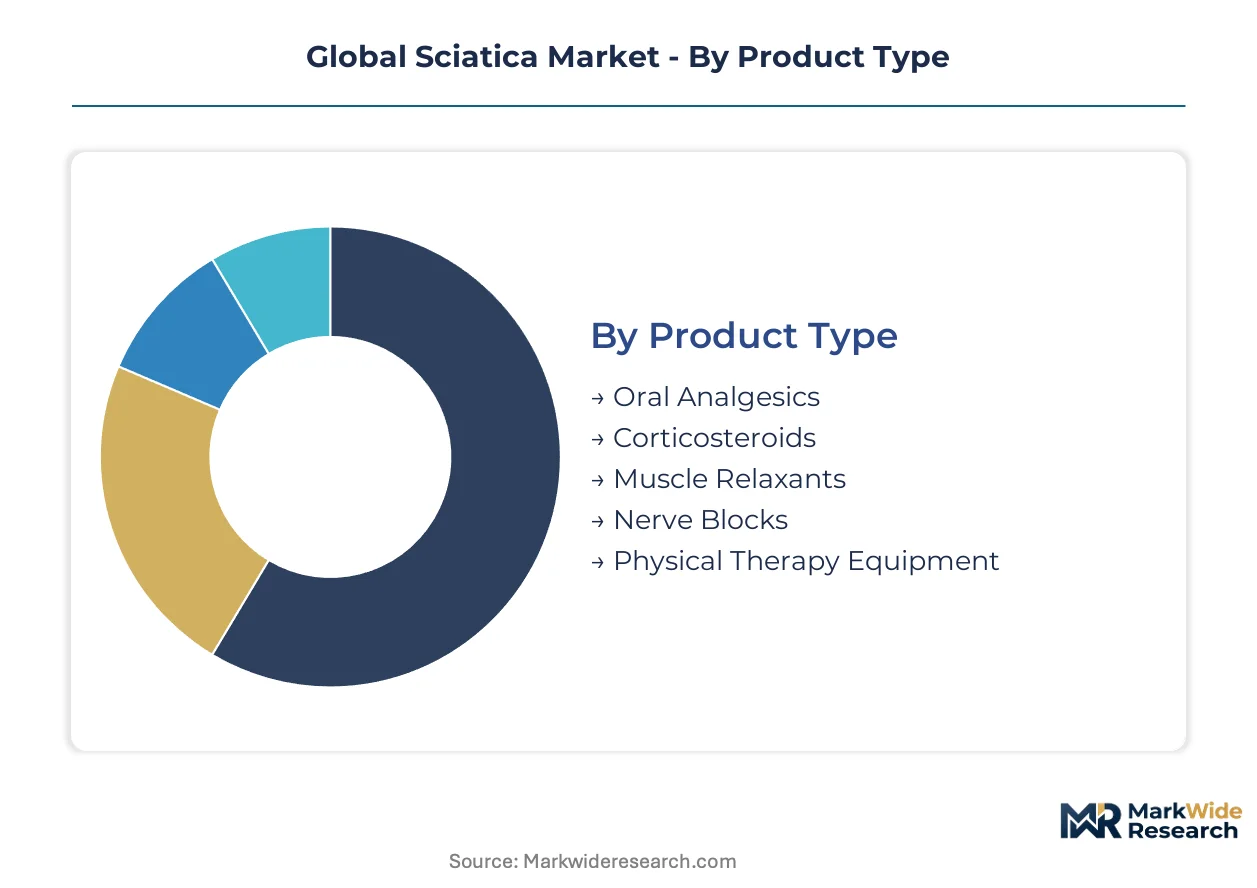
Sciatica treatment pathways diverge sharply across intervention intensity, creating distinct procurement ecosystems for pharmaceutical, device, and service providers. Segmentation reveals where margin pools concentrate versus where volume scales dominate.
Product Type:
Formulation chemistry and administration route determine reimbursement coding and margin structure across the product spectrum.
- Oral Analgesics:NSAIDs and acetaminophen-based formulations constitute high-volume, low-margin dispensing through retail pharmacy and primary care channels. DEA enforcement and state prescription monitoring programs in the United States have compressed opioid-containing variants, shifting volume toward non-narcotic alternatives.
- Nerve Blocks:Fluoroscopy-guided epidural steroid injections and selective nerve root blocks command premium interventional reimbursement in ambulatory surgical centers. United States pain management clinics are expanding suite capacity for these procedures as payors favor same-day discharge protocols over surgical admission.
- Corticosteroids:Injectable methylprednisolone and triamcinolone formulations serve acute flare management with established clinical protocols.
- Muscle Relaxants:Cyclobenzaprine and tizanidine address spasticity components in mixed-mechanism presentations.
- Physical Therapy Equipment:Traction devices, electrical stimulation units, and lumbar support systems anchor conservative care pathways.
Oral Analgesics lead on scale; Nerve Blocks lead on momentum.
Therapy Area:
Anatomical diagnosis drives treatment selection intensity and surgical candidacy thresholds.
- Lumbar Radiculopathy:Nerve root compression at L4-S1 levels defines the core surgical and interventional addressable population. MRI confirmation protocols and electrodiagnostic testing standardize diagnosis in United States and European practice guidelines.
- Spinal Stenosis:Central and foraminal narrowing in aging populations generates recurring procedural demand. Japanese METI reimbursement incentives for day-surgery decompression are accelerating volume in the Kanto and Kansai regions.
- Lower Back Pain:Nonspecific presentations dominate primary care encounters with conservative-first management.
- Degenerative Disc Disease:Discogenic pain without radiculopathy limits surgical candidacy under evolving clinical guidelines.
- Piriformis Syndrome:Entrapment neuropathy mimicking sciatica requires differential diagnostic workup.
Lumbar Radiculopathy captures the deepest intervention intensity; Spinal Stenosis is climbing the fastest as demographics shift.
End User:
Site-of-care economics and specialist availability reshape patient routing across delivery settings.
- Pain Management Clinics:Fellowship-trained interventionalists concentrate in United States coastal metros, performing fluoroscopy-guided injections and radiofrequency ablation. Texas and Florida markets exhibit vertical integration trends combining imaging, injection, and physical therapy under single tax identifiers.
- Orthopedic Clinics:Surgical and nonsurgical spine specialists coordinate care pathways with direct MRI access and implant vendor relationships. EU MDR recertification burdens are filtering procurement toward established device suppliers with robust quality management systems.
- Rehabilitation Centers:Physical therapy protocols anchor conservative care with standardized outcome metrics.
- Chiropractic Offices:Manipulation and mobilization services compete for initial patient presentation.
- Neurology Centers:Electrodiagnostic confirmation and medical management of complex radiculopathy cases.
Pain Management Clinics lead on momentum; Orthopedic Clinics retain the deepest surgical connectivity.
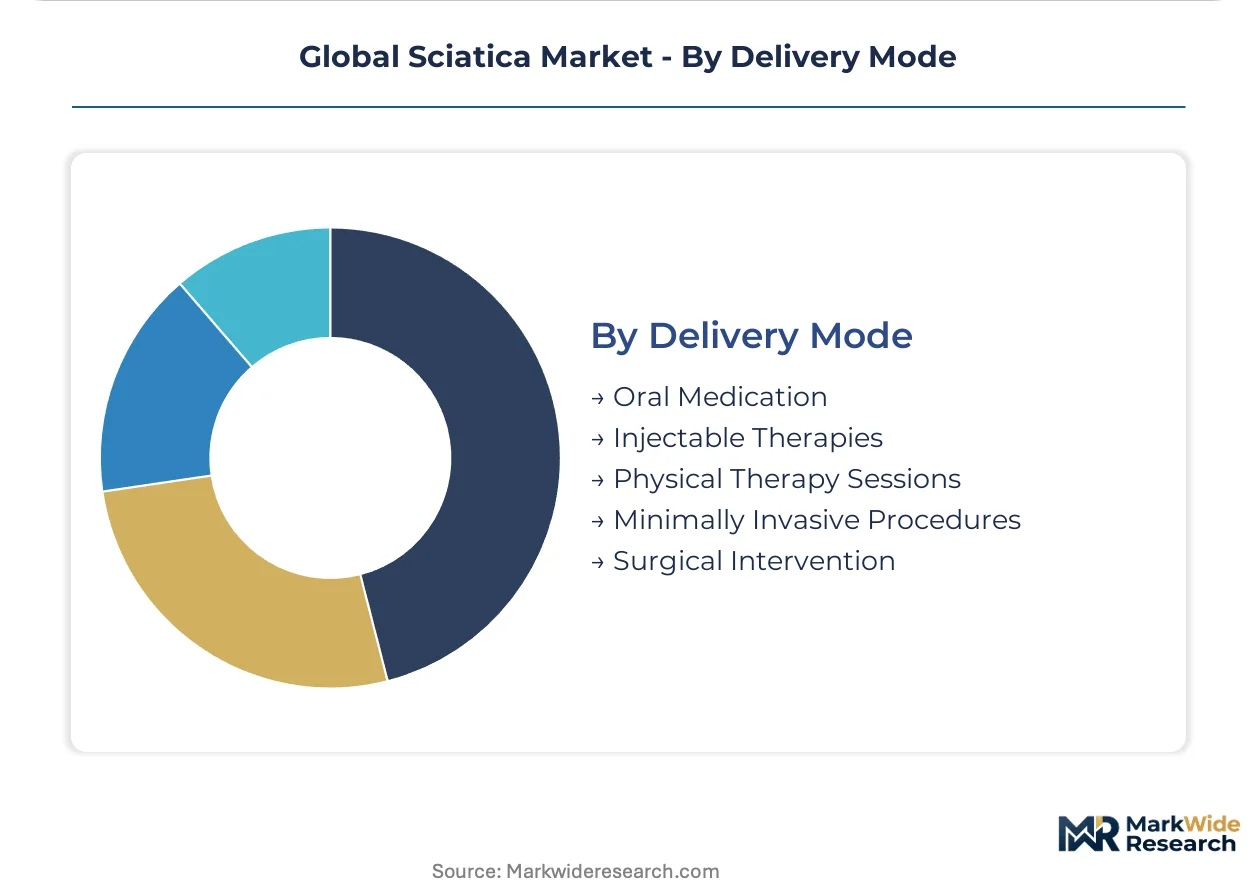
Delivery Mode:
Invassiveness gradient determines facility fee structures and recovery economics.
- Minimally Invasive Procedures:Percutaneous discectomy, endoscopic decompression, and interspinous spacer placement align with ambulatory surgical center economics. United States ASCs are upgrading interventional suites to capture patients previously requiring hospital admission.
- Injectable Therapies:Epidural steroid injection, facet block, and sacroiliac joint injection protocols standardize across pain management practice. Unbundling of facility and professional fees is creating direct price transparency pressures in commercial insurance markets.
- Oral Medication:First-line pharmacologic management with thinning margins in generic-saturated markets.
- Physical Therapy Sessions:Structured exercise and manual therapy protocols with variable adherence.
- Surgical Intervention:Open decompression and fusion procedures facing efficacy scrutiny and reimbursement compression.
Minimally Invasive Procedures are gaining share fastest; Injectable Therapies bridge the largest patient population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates procedure volumes that exceed Germany's surgical output by a factor of three, while Japan's aging demographics are accelerating day-surgery decompression protocols faster than any OECD peer.
United States
Pain management clinics in Texas and Florida are consolidating imaging, injection, and physical therapy under single tax identifiers to capture unbundled facility fees. FDA premarket clearance pathways shape spinal implant commercialization timelines for Boston Scientific and Stryker. ASCs in Houston and Miami are upgrading fluoroscopy suites for same-day nerve blocks previously requiring hospital admission.
Germany
Medical-grade titanium and PEEK polymer suppliers in Baden-Württemberg and Bavaria concentrate spinal implant input sourcing, exposing manufacturers to machining cost volatility. EU MDR recertification burdens are filtering marginal device vendors from European market access. Stuttgart's orthopedic device cluster is consolidating procurement around established suppliers with robust quality management systems.
Japan
METI reimbursement incentives for day-surgery spinal decompression are aligning hospital capital investment with demographic-driven volume expansion. PMDA regulatory pathways favor incremental device modifications over novel implant categories. Kanto and Kansai region hospitals are converting inpatient beds to ambulatory suites for lumbar decompression procedures.
India
Lumbar discectomy penetration in tier-2 and tier-3 cities remains below diagnostic capacity, creating whitespace for mobile C-arm-equipped surgical units. CDSCO medical device registration timelines extend commercial deployment for imported spinal implants. Hyderabad and Chennai are emerging as tele-radiology hubs supporting remote MRI interpretation for underserved hinterland clinics.
United Kingdom
Large-scale orthopedic registry data from Sweden and the UK has weakened clinical confidence in spinal fusion for isolated disc herniation. NICE guidelines are tightening surgical candidacy thresholds for uncomplicated radiculopathy. London's pain management networks are redirecting patients toward conservative-first pathways with standardized outcome metrics.
Global Sciatica Market Competitive Landscape
Top-tier vendors anchor premium surgical device segments, while generic pharmaceutical manufacturers compete on oral analgesic scale. The market structures around three strategic archetypes: diversified orthopedic conglomerates with spinal implant portfolios, interventional pain device specialists, and volume-driven generic drug suppliers. Consolidation pressures favor M&A activity among mid-scale neuromodulation developers and capacity expansion in ambulatory-compatible implant manufacturing.
Within the diversified orthopedic tier, Johnson & Johnson and Medtronic plc exemplify platform breadth spanning surgical implants and interventional systems. Stryker Corporation occupies a position bridging open surgical and minimally invasive decompression technologies. Teva Pharmaceutical Industries Limited represents the generic-scale archetype competing through oral analgesic volume leadership in cost-sensitive markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic plc |
| Boston Scientific Corporation |
| Stryker Corporation |
| Zimmer Biomet |
| Abbott Laboratories |
| Teva Pharmaceutical Industries Limited |
| Pfizer Inc. |
| Sorrento Therapeutics, Inc. |
| Others |
Supply & Pricing Matrix
United States payor unbundling of facility and professional fees for interventional spine procedures is compressing ambulatory surgical center margins and forcing procurement officers toward consolidated supplier relationships with volume-based contracting leverage. This demand-side consolidation is reshaping how spinal implant vendors structure pricing tiers and where they locate manufacturing capacity to preserve margin.
Pricing Analysis
Capacity additions in United States ASCs are reshaping price floors for fluoroscopy-guided procedures as same-day discharge protocols expand. Pricing stratifies across premium implant tiers with EU MDR certification, standard device tiers with FDA clearance, and economy tiers serving cost-sensitive Indian and Southeast Asian markets. Cost compression in oral analgesics is intensifying because DEA enforcement has eliminated opioid-containing variants from primary care dispensing. Generic pharmaceutical manufacturers exhibit the highest price sensitivity; neuromodulation device vendors with closed-loop spinal cord stimulator portfolios command the lowest.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss suppliers of medical-grade titanium and PEEK polymers for spinal implant machining. Manufacturing draws from concentrated input bases in Baden-Württemberg for precision-machined components, Bavaria for polymer extrusion, and United States heartland for nitinol shape-memory alloys. Tariff exposure on Chinese-sourced rare earth elements used in MRI magnets creates margin volatility for diagnostic equipment vendors. Distribution runs through orthopedic GPOs in the United States, hospital procurement consortia in Germany, and government tenders in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global sciatica market reads as a late-cycle quality story where reimbursement parity shifts and EU MDR compliance burdens are concentrating procurement around vendors with robust quality management systems and established notified body relationships.
For Market Incumbents: Acquire ambulatory surgical center partnerships to secure procedural volume anchoring against emerging pain management clinic networks. Consolidate EU MDR recertification resources to filter marginal competitors from European market access. Backward integration into German titanium machining capacity mitigates input cost volatility from concentrated supplier bases. For New Entrants and Emerging Players: Tele-radiology platforms offer the lowest barrier route into India's tier-2 and tier-3 city whitespace where diagnostic capacity lags surgical penetration. Target lumbar MRI AI interpretation software for European radiology groups facing notified body backlog and classification ambiguity under the EU AI Act. Pursue direct hospital system partnerships in Texas and Florida where vertical integration trends concentrate purchasing authority. For Investors and Strategic Acquirers: Asymmetric upside sits with neuromodulation device specialists engineering closed-loop spinal cord stimulators for failed back surgery syndrome populations. Long-term viability hinges on reimbursement strategy execution and FDA premarket clearance pathway navigation. Watch for METI reimbursement incentive expansion beyond Kanto and Kansai as Japan's demographic pressure accelerates day-surgery conversion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Completion | Filters marginal vendors from European spinal implant procurement, concentrating share among established suppliers. |
| Ambulatory Surgical Center Partnership | Captures unbundled facility fees in Texas and Florida markets where vertical integration trends dominate. |
| Lumbar MRI AI Software Development | Addresses radiology throughput bottlenecks under EU AI Act conformity assessment requirements. |
| Closed-Loop Neuromodulation Launch | Displaces tonic stimulation market share with paresthesia-free pain relief demonstrated in United States registries. |
| India Mobile Surgical Unit Deployment | Bridges tier-2 and tier-3 city procedural gaps through C-arm-equipped units and tele-radiology partnerships. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining structured interviews with pain management clinic directors, orthopedic spine surgeons, hospital purchasing committee members, and GPO contracts managers alongside secondary validation. Sources include FDA 510(k) filings, EUDAMED device registration data, CMS Medicare procedure volume databases, Japanese METI reimbursement bulletins, and CDSCO medical device import records. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include intervention intensity, delivery mode, therapy area, and end-user site-of-care economics. CAGRs derive from procedure volume trajectories, reimbursement code valuation trends, and implant ASP erosion patterns. Industry-specific inputs incorporate EU MDR recertification timeline assumptions and METI day-surgery incentive expansion scenarios.
The model assumes a particular technology adoption path; alternative pathways for closed-loop spinal cord stimulation or bioresorbable implant carriers would alter the outlook. Forecasts reflect assumptions about payor value-based threshold calibration and regulatory clearance timeline normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Refsum Disease Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Influenza Treatment Market