
 Thoracolumbar Stabilization Devices Market | 2026-2036
Thoracolumbar Stabilization Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Thoracolumbar Stabilization Devices Market Outlook
Additive manufacturing is reconfiguring implant production workflows across the thoracolumbar fixation segment. Medtronic plc leverages titanium lattice structures to improve osseointegration profiles in posterior spinal fusion constructs. DePuy Synthes sustains broad geographic coverage through vertically integrated forging and finishing operations. Globus Medical differentiates via robotics-assisted navigation systems that tighten screw placement accuracy in complex deformity cases.
Thoracolumbar stabilization devices are mechanical implants designed to restore spinal column integrity through rigid or motion-preserving fixation, typically manufactured from titanium alloys or polyetheretherketone composites with thread pitches ranging from 1.25 to 2.0 millimeters for pedicle screw engagement. These systems primarily serve to immobilize vertebral segments, correct deformity, or facilitate fusion following trauma, degenerative collapse, or oncologic resection. Rigid stabilization technology anchors the majority of current revenue owing to established reimbursement codes and surgeon familiarity, while dynamic stabilization and hybrid systems are gaining traction among younger patients seeking motion preservation. Biodegradable solutions remain nascent but occupy strategic interest from developers targeting pediatric applications where permanent metal retention raises long-term concerns.
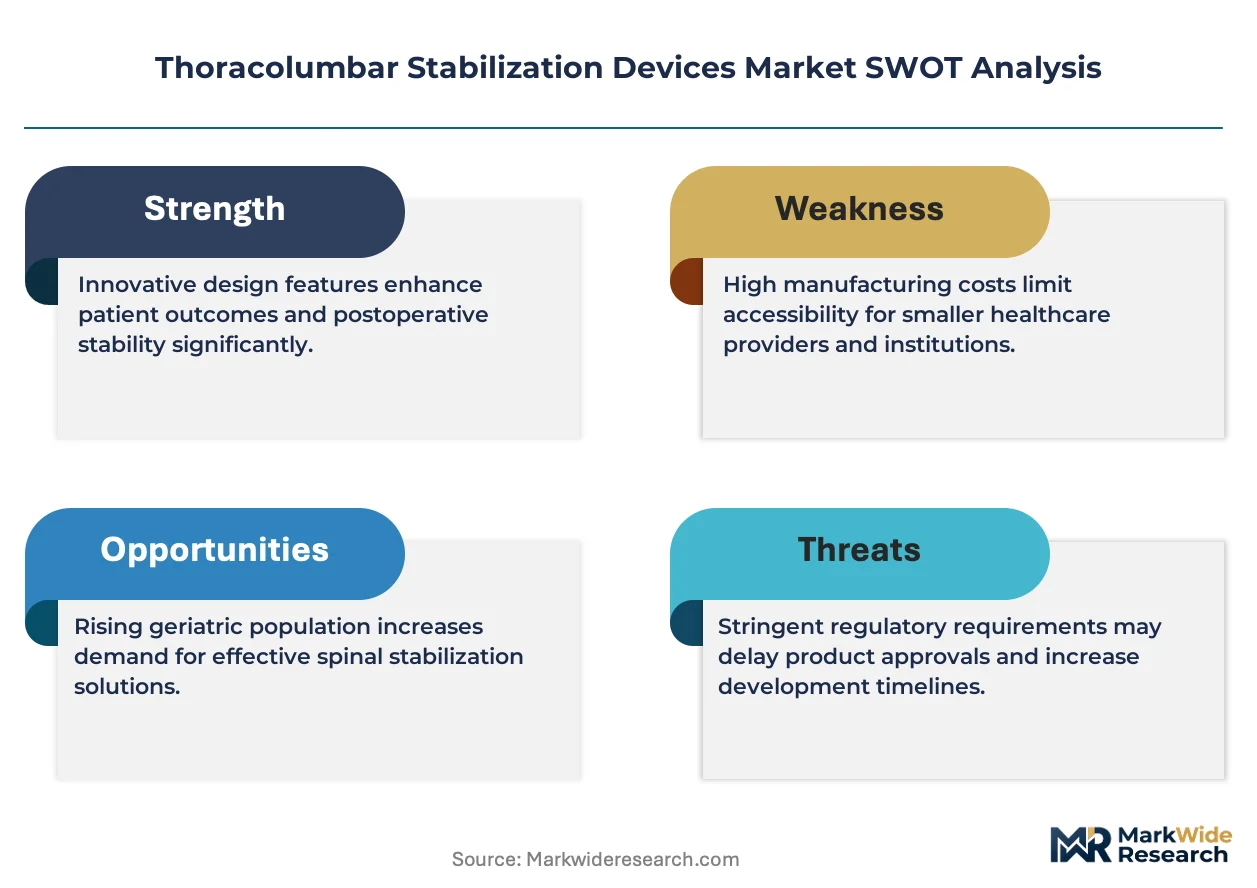
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards shape product development timelines and clinical evidence thresholds for thoracolumbar implant manufacturers. Japan's PMDA imposes additional biocompatibility testing protocols that extend market entry lead times for foreign suppliers. Stakeholders must monitor evolving health technology assessment criteria from Germany's Federal Joint Committee and France's HAS, as these agencies increasingly tie reimbursement to comparative effectiveness data against conservative management.
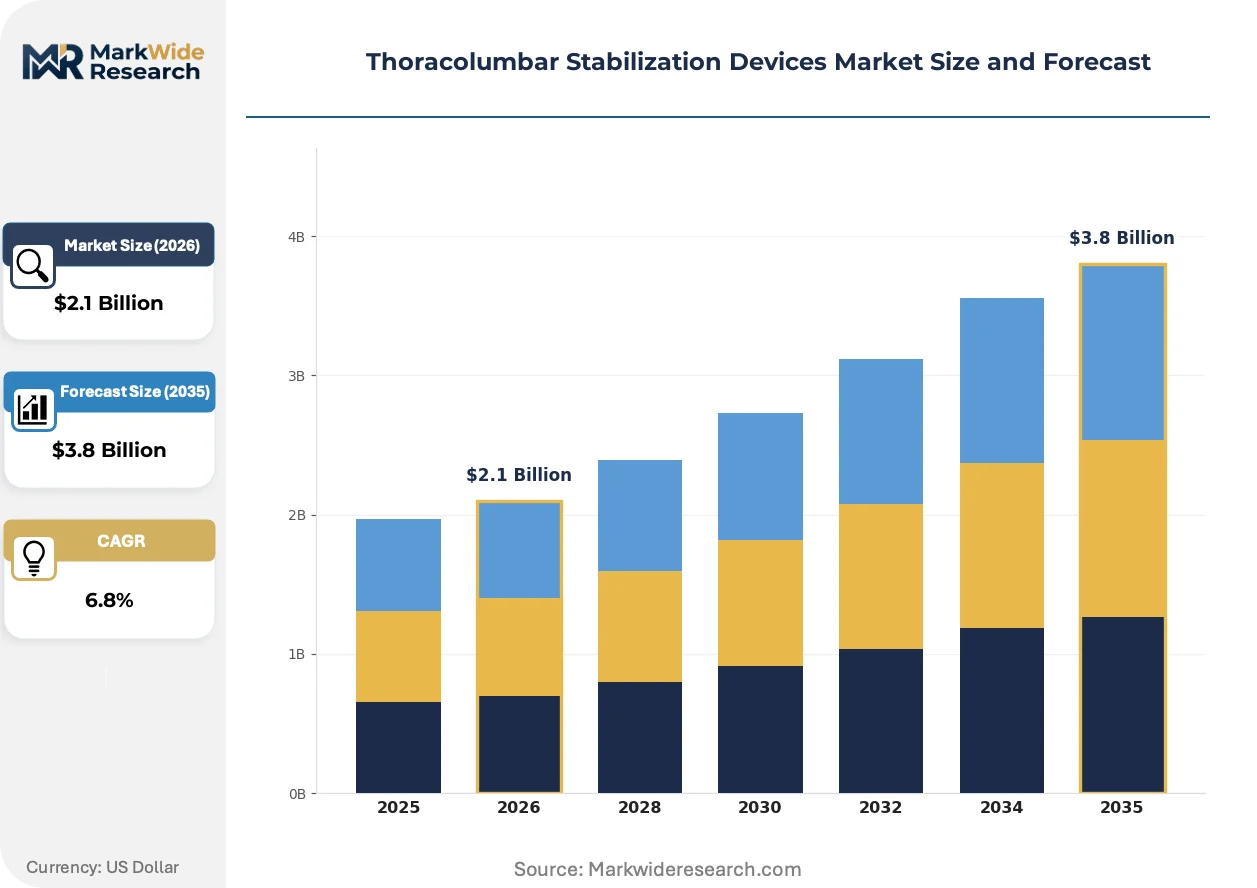
Market Dynamics
The thoracolumbar stabilization devices market is undergoing a fundamental reconfiguration as additive manufacturing displaces conventional forging workflows, compressing production lead times for patient-specific titanium lattice implants while forcing incumbent suppliers to retool capital equipment portfolios.
Growth Catalysts
- EU MDR compliance acceleration:The Medical Device Regulation's enhanced clinical evidence requirements are filtering out marginal competitors and consolidating procurement decisions around established suppliers with robust technical documentation capabilities.
- Japan's aging surgical population:PMDA's streamlined review pathways for priority medical devices are attracting foreign manufacturers to address the country's expanding degenerative spine disease burden among patients over 65.
- Robotics-assisted navigation:Screw placement accuracy improvements from integrated surgical robotics are expanding the addressable case mix to include complex deformity corrections previously deemed too high-risk for standard fixation.
Market Restraints
- Titanium sponge supply concentration:Raw material sourcing from a limited supplier base in Russia and China exposes implant manufacturers to price volatility and geopolitical disruption risks.
- Biocompatibility testing costs:ISO 10993 cytotoxicity and sensitization protocols require substantial capital allocation for in-house laboratory infrastructure or third-party contract testing fees.
- Motion-preserving substitution:Dynamic stabilization systems and artificial disc replacements are capturing select patient segments seeking alternatives to rigid fusion constructs.
Strategic Opportunities
- Pediatric biodegradable development:PLGA-based resorbable implants address the unmet need for temporary fixation in skeletally immature patients where permanent metal retention complicates future growth.
- Ambulatory surgery center penetration:Minimally invasive fixation techniques are enabling procedure migration from inpatient hospital settings to freestanding ASCs with favorable reimbursement profiles.
- India's CDSCO fast-track pathway:The regulator's priority review designation for orphan and innovative devices offers accelerated market entry for thoracolumbar systems addressing spinal tuberculosis and trauma.
Industry Challenges
- Surgical robotics integration complexity:Hardware and software interoperability between navigation platforms and implant instrumentation demands substantial R&D coordination and FDA 510(k) recertification cycles.
- Additive manufacturing qualification timelines:Process validation for electron beam melting and selective laser melting workflows extends design-to-market intervals beyond traditional machining benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thoracolumbar Stabilization Devices Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Surgical Plates, Rods, Screws Technology: Dynamic Stabilization, Rigid Stabilization, Hybrid Systems, Biodegradable Solutions Application: Trauma, Degenerative Disorders, Tumors, Congenital Defects End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Facilities, Home Healthcare |
| Companies Covered | Medtronic plc, DePuy Synthes, Stryker Corporation, Globus Medical, Zimmer Biomet Holdings, NuVasive, Inc., B. Braun Melsungen AG, Orthofix Medical Inc., Alphatec Spine, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thoracolumbar Stabilization Devices Market Strategic Shifts
Additive manufacturing is compressing the traditional boundaries between implant design and production, enabling topology-optimized structures that were previously impossible to machine while forcing supply chain reconfiguration around powder metallurgy and post-processing capabilities.
Patient-specific titanium lattice implants with engineered pore geometries for bone ingrowth are rendering obsolete the solid-core pedicle screws that dominated posterior spinal fusion for three decades. Academic medical centers in Germany and the United States are piloting these constructs for complex revision cases with poor bone quality. The shift is compressing the competitive moat of vertically integrated forging operations while elevating design software and powder characterization capabilities as strategic differentiators.
EU MDR's Article 61 clinical evaluation requirements are extending market access timelines for thoracolumbar implant manufacturers without predicate device equivalence. The regulation mandates systematic literature reviews and post-market clinical follow-up protocols that disproportionately burden mid-tier suppliers with limited regulatory affairs infrastructure. German and French notified bodies are prioritizing review resources toward high-volume cardiovascular and orthopedic categories, creating queuing delays for spinal device submissions.
Hospital procurement committees are consolidating vendor relationships around full-line suppliers capable of delivering instrumentation, biologics, and navigation platforms under single-source agreements. The purchasing model displaces the fragmented multi-vendor arrangements that characterized 2010s spine surgery. This concentration is most pronounced in United States integrated delivery networks and German hospital federations, where standardization committees now mandate interoperability between implant systems and electronic health record platforms.
Thoracolumbar Stabilization Devices Market Segmentation
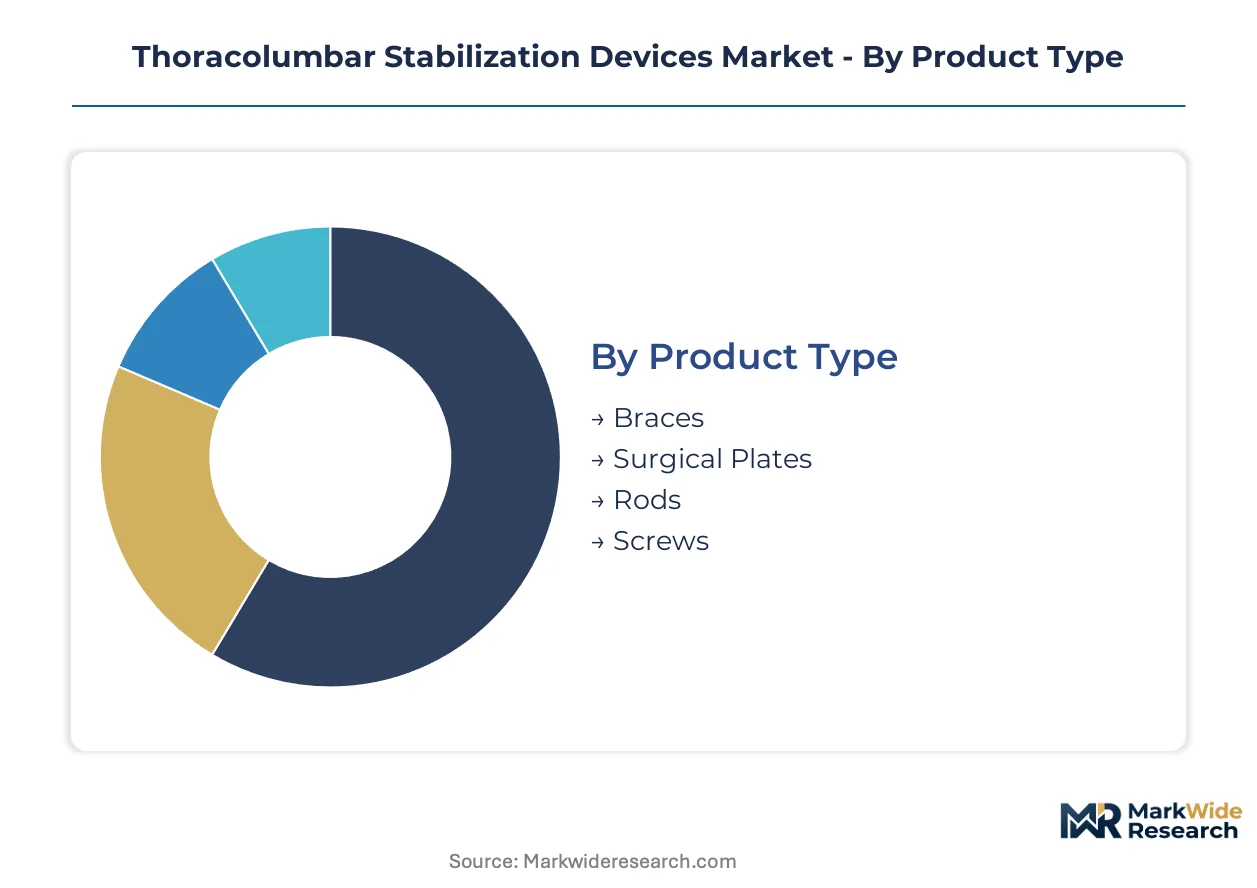
Segmentation in thoracolumbar stabilization reveals distinct procurement patterns across surgical settings and patient acuity levels. Product type selection hinges on bone quality and deformity complexity, while technology choice reflects the tension between fusion durability and motion preservation.
Product Type:
Use-case spectrum spans external immobilization for conservative management to internal fixation for complex reconstructive procedures.
- Screws:Titanium alloy pedicle screws with thread pitches from 1.25 to 2.0 millimeters anchor posterior spinal fusion constructs. Demand concentrates in United States academic medical centers where robotics-assisted navigation tightens placement accuracy in deformity corrections.
- Rods:Contourable titanium rods connect screw heads to distribute mechanical loads across fused segments. German hospital federations favor cobalt-chromium alloy variants for their superior fatigue resistance in long-segment constructs.
- Braces:External orthotic devices provide non-operative immobilization for stable compression fractures. Japan's aging population drives volume for lightweight carbon-fiber designs in outpatient rehabilitation settings.
- Surgical Plates:Anterior thoracolumbar plates stabilize vertebral bodies following corpectomy or trauma reconstruction. These constructs see selective use in oncologic resection cases where anterior column support is paramount.
Established volume favors screws; emerging adoption favors braces in conservative care pathways.
Technology:
Cost tier differentiation separates premium navigation-integrated systems from standard fixation platforms.
- Rigid Stabilization:Conventional fusion constructs eliminate motion at instrumented segments to achieve bony arthrodesis. United States integrated delivery networks anchor procurement volume here due to established CPT reimbursement codes and surgeon training familiarity.
- Dynamic Stabilization:Semirigid pedicle screw-based systems or interspinous spacers preserve limited motion while unloading diseased segments. Younger patient cohorts in Germany and Japan seek these alternatives to mitigate adjacent segment disease risks.
- Hybrid Systems:Combined rigid and dynamic elements address multilevel pathology with mixed stability requirements. These configurations gain traction in revision surgeries where prior fusion sites constrain treatment options.
- Biodegradable Solutions:PLGA-based resorbable implants provide temporary fixation for pediatric trauma without permanent metal retention. PMDA's interest in pediatric innovation accelerates development timelines for skeletally immature applications.
Revenue concentration remains with rigid stabilization; steepest expansion trajectory belongs to biodegradable platforms.
Application:
Patient acuity and surgical urgency shape implant selection criteria across the clinical spectrum.
- Degenerative Disorders:Spondylolisthesis and spinal stenosis drive elective fusion procedures in patients over 60. Japan's demographic profile sustains procedure volume expansion despite reimbursement pressure from the country's fee schedule revisions.
- Trauma:Unstable burst fractures and fracture-dislocations demand urgent surgical stabilization. United States Level I trauma centers prioritize inventory depth for polytrauma cases requiring rapid implant availability.
- Tumors:Metastatic spinal disease and primary neoplasms require en bloc resection with anterior and posterior column reconstruction. These complex cases concentrate at tertiary referral centers with multidisciplinary oncology teams.
- Congenital Defects:Scoliosis and kyphosis in pediatric populations necessitate growth-friendly or definitive fusion constructs. Early-onset scoliosis drives demand for magnetically controlled growing rods in specialized children's hospitals.
Procedure volume concentrates in degenerative indications; complexity premiums attach to tumor reconstructions.
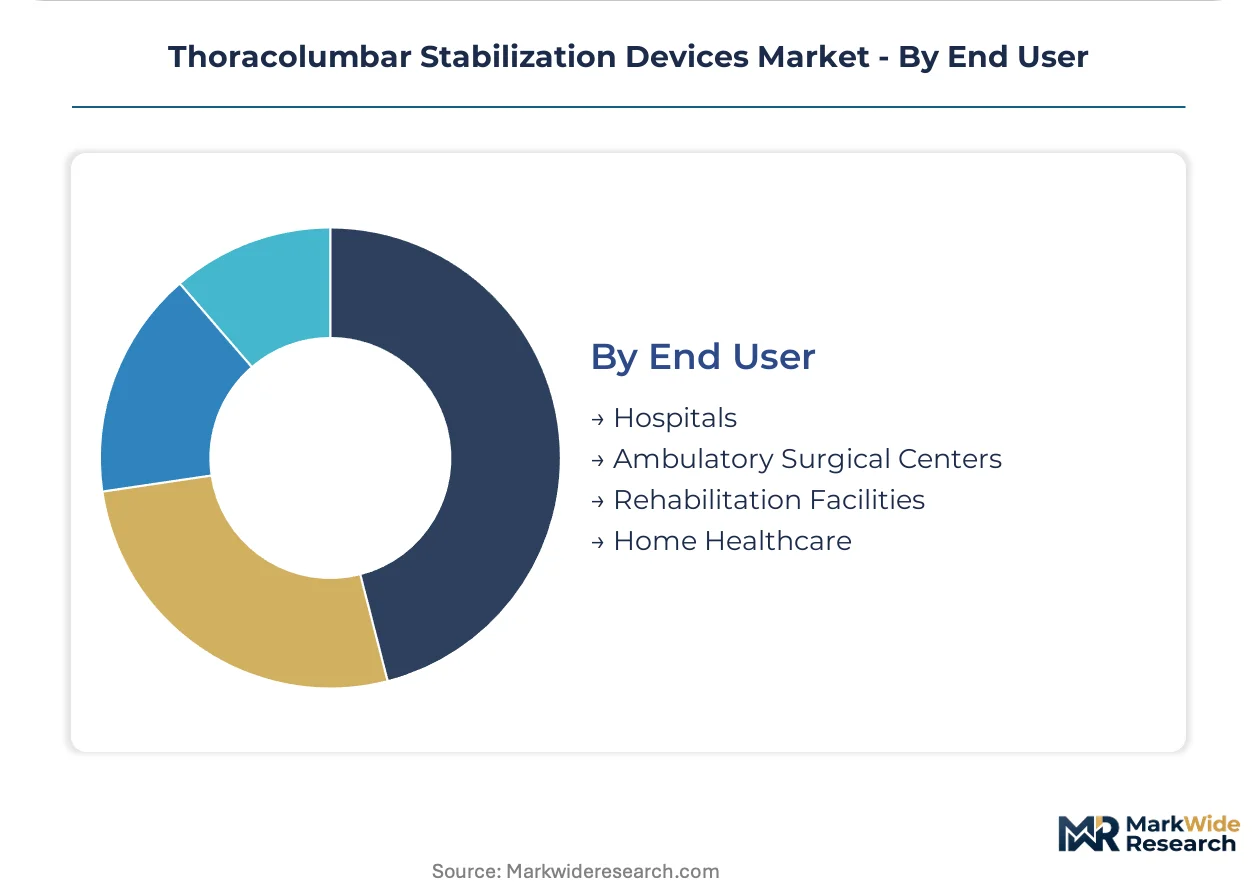
End User:
Facility type determines case mix, reimbursement pathway, and capital equipment requirements.
- Hospitals:Inpatient surgical suites handle complex deformity, trauma, and oncologic cases requiring intensive care support. German hospital federations consolidate vendor relationships around full-line suppliers delivering implants, biologics, and navigation platforms.
- Ambulatory Surgical Centers:Freestanding facilities capture minimally invasive decompression and single-level fusion procedures. United States ASCs exploit favorable site-of-service differentials under Medicare's HOPPS payment system.
- Rehabilitation Facilities:Post-acute centers manage brace fitting and mobility restoration following surgical stabilization. These settings emphasize orthotic customization for elderly patients with compromised bone density.
- Home Healthcare:External brace wear and wound monitoring extend into residential settings for select stable fracture patterns. Japan's community-based care integration supports this channel for rural elderly populations.
Revenue gravity centers on hospitals; site migration favors ambulatory surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and integrated delivery networks concentrate procurement authority for thoracolumbar stabilization systems. Hospital federations in Germany, trauma centers in the United States, and geriatric surgical units in Japan anchor demand volume. Regulatory pathways in each jurisdiction reshape competitive access and pricing power.
United States
Level I trauma centers and academic medical centers drive complex deformity and oncology case volume. FDA 510(k) premarket notification requirements compress design-to-market intervals for predicate-equivalent titanium constructs. The Greater Boston cluster anchors robotics-assisted navigation development, with Massachusetts General Hospital piloting patient-specific lattice implants for revision surgeries.
Germany
Hospital federations consolidate vendor relationships around full-line suppliers delivering implants, biologics, and navigation platforms. EU MDR Article 61 clinical evaluation requirements extend market access timelines for manufacturers without robust technical documentation infrastructure. The Baden-Württemberg region concentrates precision machining capabilities for cobalt-chromium rod production.
Japan
PMDA's streamlined review pathways for priority medical devices attract foreign manufacturers addressing degenerative spine disease in patients over 65. The country's aging demographic sustains elective fusion procedure volume despite fee schedule reimbursement pressure. Tokyo's Keiyō Industrial Zone hosts titanium alloy forging operations serving domestic implant demand.
India
CDSCO's fast-track pathway for orphan and innovative devices accelerates market entry for thoracolumbar systems addressing spinal tuberculosis and trauma. Private hospital chains in Maharashtra and Karnataka expand minimally invasive fixation capacity for medical tourism segments. Mumbai's pharmaceutical corridor attracts contract manufacturing for titanium sponge processing.
Switzerland
Swissmedic's alignment with EU MDR standards enables concurrent market access across European and Swiss jurisdictions. The country's precision engineering heritage supports development of high-tolerance instrumentation for complex deformity corrections. The Lake Geneva region concentrates orthopedic device R&D clusters serving both EU and domestic hospital procurement committees.
Thoracolumbar Stabilization Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement environments. The market structure concentrates around vertically integrated manufacturers with captive forging capacity and design-software specialists with additive manufacturing capabilities. Three archetypes dominate: full-line suppliers bundling implants with navigation platforms, titanium alloy specialists with powder metallurgy expertise, and robotics-integrated players tightening surgical accuracy. Competitive moves center on M&A for navigation technology access and strategic partnerships for ASC distribution expansion.
Among Ireland-registered multinationals, Medtronic plc exemplifies the full-line supplier archetype with integrated navigation and implant portfolios. DePuy Synthes, a Johnson & Johnson subsidiary, represents vertically integrated forging operations with broad geographic coverage. Globus Medical anchors the robotics-specialist tier, positioning its navigation systems for complex deformity applications. These three occupy distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| Medtronic plc |
| DePuy Synthes |
| Stryker Corporation |
| Globus Medical |
| Zimmer Biomet Holdings |
| NuVasive, Inc. |
| B. Braun Melsungen AG |
| Orthofix Medical Inc. |
| Alphatec Spine, Inc. |
| Others |
Value Chain & Pricing Dynamics
Russia and China's concentration of titanium sponge production anchors upstream cost structures for thoracolumbar implant manufacturers, concentrating margin pools with suppliers possessing captive forging capacity and EU MDR-compliant technical documentation infrastructure. This geographic sourcing concentration forces downstream pricing discipline around long-term offtake agreements indexed to London Metal Exchange titanium benchmarks.
Pricing Analysis
Cost-plus contracts with London Metal Exchange titanium indexation dominate procurement between implant manufacturers and raw material suppliers. Pricing stratifies across premium navigation-integrated systems, standard titanium alloy constructs, and economy-grade cobalt-chromium alternatives, with differentiation driven by FDA 510(k) clearance tier and robotics compatibility certification. Cost compression in the standard tier is intensifying because German hospital federations consolidate procurement around full-line suppliers. Ambulatory surgical centers exhibit highest price sensitivity due to site-of-service reimbursement differentials, while academic medical centers prioritize navigation integration over unit cost.
Supply Chain Analysis
Contract manufacturing for titanium lattice implants concentrates with electron beam melting specialists in Germany, Switzerland, and the United States. Supply chains draw from Russian titanium sponge, Chinese rare earth processing, and domestic precision machining for final instrumentation assembly. Single-source vulnerability permeates the electron beam melting equipment tier, where German and Swiss machine tool builders control additive manufacturing qualification protocols. Distribution runs through hospital procurement committees and group purchasing organizations, with integrated delivery networks consolidating vendor relationships under single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dynamic stabilization systems and artificial disc replacements threaten rigid fusion volumes, forcing incumbents to defend positioning through motion-preserving portfolio expansion and navigation platform bundling.
For Market Incumbents: Insulate core fusion revenue by acquiring additive manufacturing design capabilities for patient-specific lattice implants, addressing the threat from biodegradable PLGA alternatives in pediatric segments. Backward integration into titanium powder characterization laboratories secures supply continuity against Russian sponge export restrictions. Robotics-assisted navigation software development represents the priority capability investment for defending premium pricing in deformity corrections. For New Entrants and Emerging Players: Pursue CDSCO fast-track designation for spinal tuberculosis applications in Maharashtra and Karnataka private hospital chains, where minimally invasive fixation capacity expansion outpaces established supplier coverage. Pediatric biodegradable implants offer the most penetrable white-space segment given PMDA innovation incentives and unmet need for temporary fixation in skeletally immature patients. Direct distribution partnerships with ambulatory surgery centers bypass entrenched hospital procurement committee barriers. For Investors and Strategic Acquirers: Capital is best deployed toward design-software specialists with additive manufacturing capabilities and established EU MDR technical documentation infrastructure, as these assets command scarcity premiums in consolidated procurement environments. Long-term viability hinges on navigation platform interoperability and robotics integration depth rather than standalone implant commodity positioning. Watch FDA 510(k) clearance velocity for patient-specific lattice constructs as the inflection signal for additive manufacturing adoption tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Article 61 clinical evaluation capabilities filter marginal competitors from German hospital procurement. |
| Robotics Navigation Platform Development | Screw placement accuracy improvements expand addressable case mix to complex deformity corrections. |
| Additive Manufacturing Qualification | Electron beam melting process validation compresses design-to-market intervals for titanium lattice implants. |
| Ambulatory Surgery Center Distribution Partnership | Site-of-service migration captures favorable Medicare HOPPS reimbursement differentials. |
| Pediatric Biodegradable Implant Pipeline | PLGA-based resorbable constructs address unmet need for temporary fixation without permanent metal retention. |
Study Parameters
The analysis maps rigid stabilization, dynamic stabilization, hybrid systems, and biodegradable solutions, each validated through spinal surgeons, hospital purchasing committee members, biomedical engineers, and group purchasing organization contract managers. Primary fieldwork combined with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, PMDA priority review designations, and hospital procurement database records. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Assumptions held reimbursement stability fixed in United States Medicare and German statutory health insurance frameworks while varying robotics adoption rates and additive manufacturing qualification timelines. Segmentation dimensions modeled include product type, technology tier, application indication, and end-user facility category. CAGRs derived from procedure volume elasticities to aging demographic projections and surgical robotics penetration curves. Forecast inputs incorporated titanium sponge price volatility indices and EU MDR review queue duration estimates.
Sensitivities concentrate around PMDA regulatory pathway changes, EU MDR notified body capacity constraints, and titanium sponge supply disruptions from geopolitical events. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against hospital procurement database benchmarks and manufacturer reported segment revenues is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Memory Implants Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Ostomy Drainage Systems Market