
 Systemic Inflammatory Response Syndrome Treatment Market | 2026-2036
Systemic Inflammatory Response Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Systemic Inflammatory Response Syndrome Treatment Market Analytics
Buyer consolidation among hospital networks is realigning how SIRS therapy suppliers secure long-term contracts. Pfizer leverages its broad anti-infective portfolio to anchor relationships with integrated delivery networks. CytoSorbents Corporation specializes in blood purification technology for cytokine storm management. AstraZeneca competes through biologic immunomodulators targeting severe inflammatory pathways.
Systemic Inflammatory Response Syndrome treatment encompasses pharmacologic and device-based interventions that modulate dysregulated immune activation, including corticosteroid protocols, targeted cytokine inhibitors, and extracorporeal adsorption systems designed to clear circulating inflammatory mediators from patient blood. These therapies serve the primary commercial purpose of reducing multi-organ failure risk in critically ill patients admitted to intensive care units. Immunomodulators command premium positioning due to biologic manufacturing complexity and narrow therapeutic indices. Intravenous delivery dominates acute settings where rapid hemodynamic stabilization proves essential. The sepsis therapy area generates the most intensive R&D allocation as mortality-linked outcomes attract payer reimbursement prioritization.
The FDA maintains stringent oversight of anti-sepsis drug trials through its Division of Anti-Infective Products, while the EMA's Committee for Medicinal Products for Human Use evaluates novel immunomodulators under accelerated assessment pathways for life-threatening conditions. ISO 13485 certification requirements and EU MDR technical documentation standards shape market access timelines for device manufacturers. Stakeholders must monitor evolving CMS sepsis bundle reimbursement criteria and parallel EU HTA convergence processes to anticipate which therapeutic modalities will secure sustainable formulary placement.
Market Dynamics
Hospital procurement consolidation across the United States and Western Europe is compressing vendor margins while favoring integrated critical-care suppliers capable of bundling pharmacologic and device-based interventions under single-source contracts.
Growth Catalysts
- ICU Infrastructure Expansion:Aging demographics in Japan and Germany sustain bed capacity additions that expand the addressable patient base for cytokine adsorption therapies and immunomodulatory protocols.
- FDA Sepsis Guidance Alignment:The 2023 updated guidance accelerates trial design standardization, reducing regulatory uncertainty for novel anti-inflammatory candidates entering Phase III evaluation.
- Extracorporeal Technology Maturation:Blood purification sorbent manufacturing scale-up in specialized European facilities is lowering per-treatment device costs for hospital networks.
Market Restraints
- Biologic Input Cost Volatility:Recombinant protein production depends on mammalian cell culture media whose serum and growth factor prices fluctuate with agricultural commodity markets.
- EU MDR Technical Documentation Burden:Stricter classification for extracorporeal systems extends registration timelines by 18-24 months for device manufacturers without notified body pre-arrangements.
- Clinical Endpoint Complexity:Mortality-based trial requirements demand larger patient populations than surrogate marker designs, inflating development expenditures for immunomodulator sponsors.
Strategic Opportunities
- Japan Critical Care Penetration:Underutilized cytokine storm management protocols in regional Japanese hospitals present expansion potential for blood purification system distributors.
- CMS Sepsis Bundle Alignment:Reimbursement criteria evolution creates formulary placement incentives for therapies demonstrating organ failure reduction within 72-hour windows.
- Machine Learning-Enhanced Monitoring:Convergence of predictive analytics with continuous hemodynamic surveillance enables earlier SIRS identification and intervention timing optimization.
Industry Challenges
- ISO 13485 Auditor Scarcity:Limited pool of qualified medical device quality management certifiers creates bottlenecks for manufacturers pursuing EU market access.
- Legacy EHR Integration Friction:Proprietary data formats in established hospital information systems complicate real-time inflammatory biomarker dashboard deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Systemic Inflammatory Response Syndrome Treatment Market |
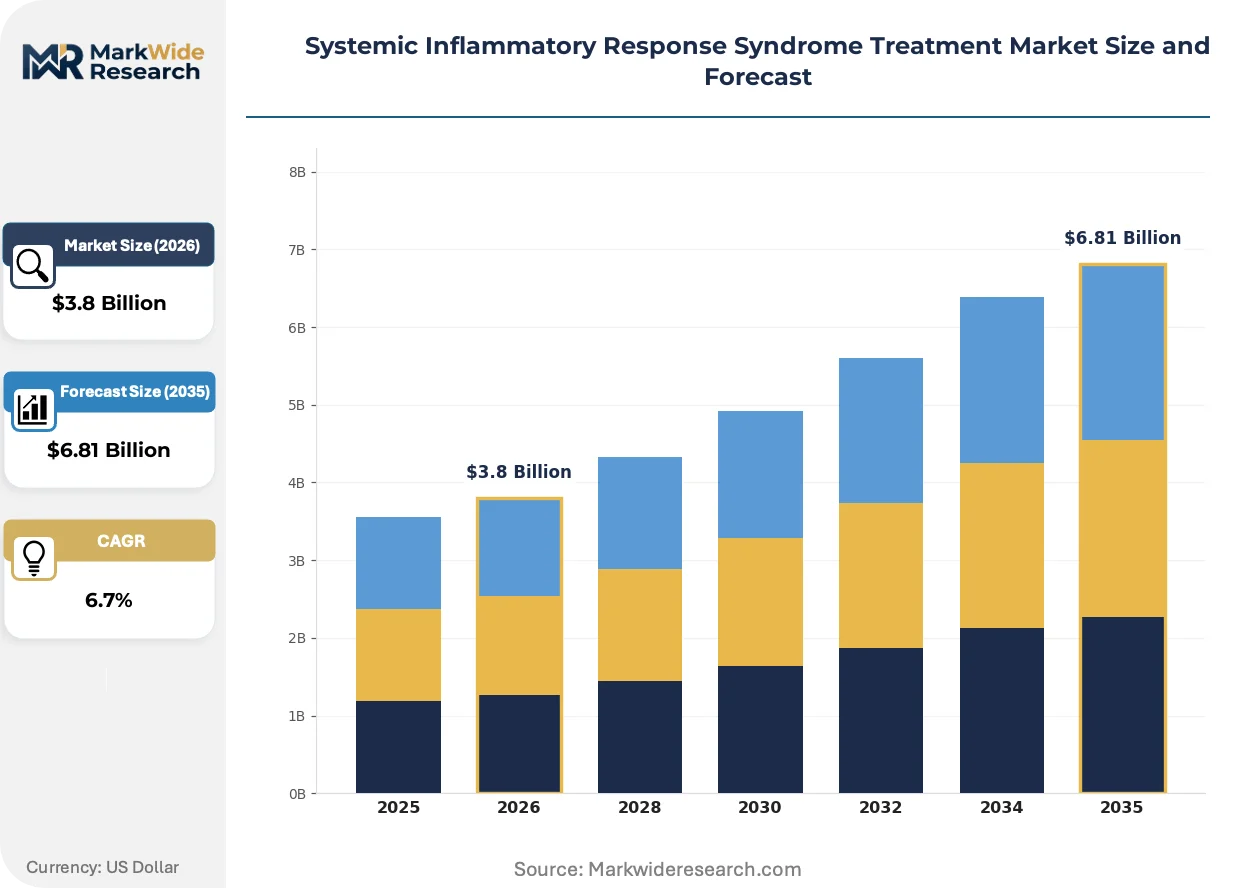
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunomodulators, Antibiotics, Corticosteroids, Antipyretics Delivery Mode: Intravenous, Intramuscular, Oral, Topical Therapy Area: Infectious Diseases, Trauma, Sepsis, Autoimmune Disorders End User: Hospitals, Clinics, Ambulatory Surgical Centers, Rehabilitation Facilities |
| Companies Covered | Siemens Healthineers, GlaxoSmithKline Plc, AstraZeneca, Asahi Kasei, Adrenomed AG, CytoSorbents Corporation, Pfizer, Recce Pharmaceuticals, Convatec Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Systemic Inflammatory Response Syndrome Treatment Market Evolving Landscape
Next-generation cytokine adsorption platforms are compressing treatment windows while regulatory convergence around sepsis endpoints is standardizing evidence requirements across major jurisdictions.
Polystyrene-divinylbenzene copolymer sorbents with enhanced biocompatibility coatings are overtaking first-generation activated charcoal systems in cytokine storm management. Academic medical centers in Germany and the United States have adopted these advanced materials for refractory septic shock protocols. The technology is overtaking conventional hemofiltration approaches by enabling selective inflammatory mediator removal without depleting essential plasma proteins.
The EU MDR's 2021 implementation timeline continues reshaping device commercialization pathways for extracorporeal blood purification manufacturers. Technical documentation requirements for Class III devices now mandate clinical evidence comparable to pharmaceutical standards, elevating barrier costs for mid-scale entrants. French and Italian hospitals are prioritizing MDR-certified systems in procurement evaluations, accelerating supplier consolidation toward established notified body relationships.
Integrated delivery networks in the United States are unbundling device procurement from pharmaceutical formulary decisions, creating separate contracting streams for blood purification hardware and anti-inflammatory drug protocols. This separation enables specialized critical-care suppliers to compete without anchoring comprehensive portfolios. The pattern is most visible in multi-hospital systems across Texas and Florida where sepsis mortality reduction initiatives drive technology assessment autonomy.
Systemic Inflammatory Response Syndrome Treatment Market Segmentation
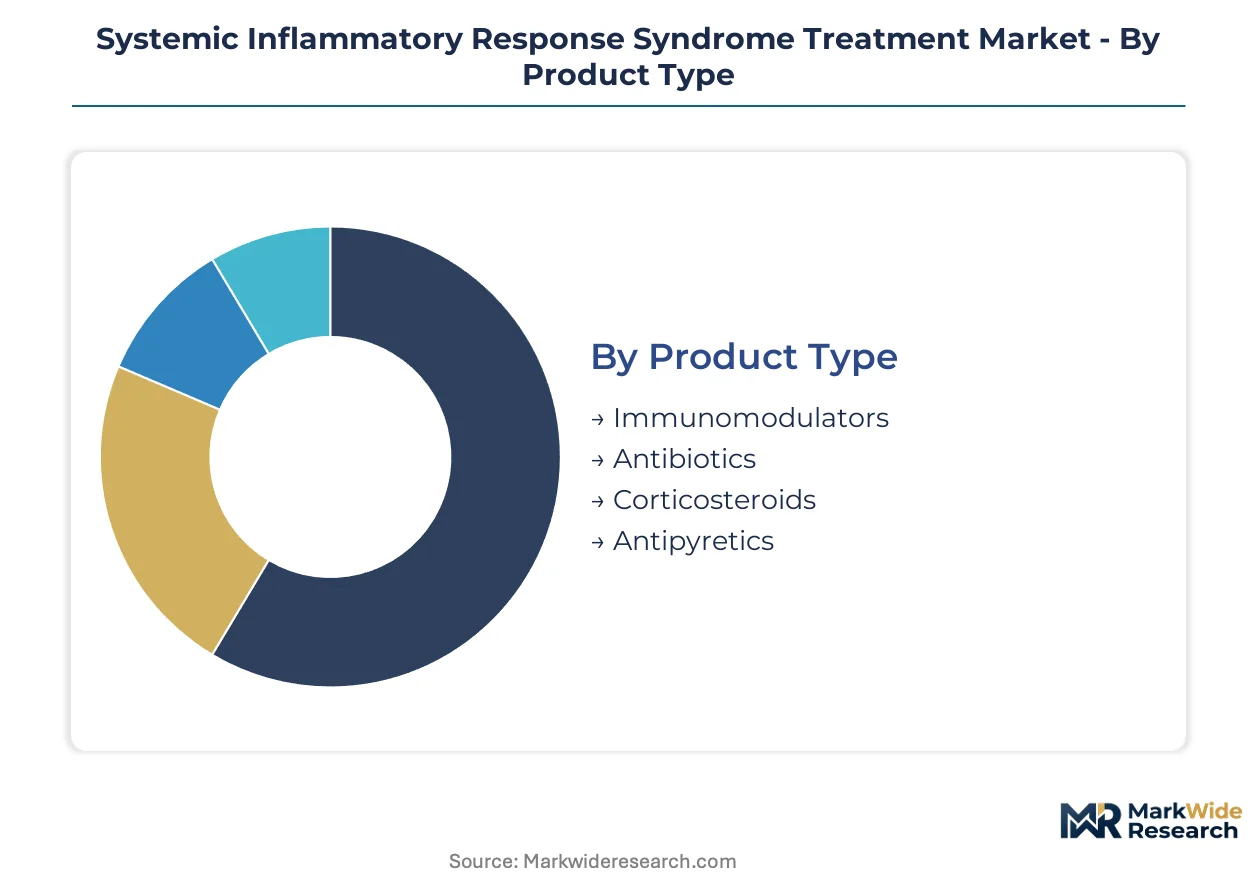
SIRS treatment procurement varies sharply by clinical setting and urgency of intervention. Hospital networks prioritize rapid-acting modalities for ICU stabilization, while outpatient facilities favor cost-containment profiles. Understanding these divergent buyer priorities enables suppliers to align portfolio investments with the highest-margin access points.
Product Type:
Cost tier separates acute critical-care buyers from step-down facility purchasers in this category.
- Immunomodulators:Biologic agents targeting specific cytokine pathways require cold-chain distribution and specialized pharmacy handling. Demand concentrates in tertiary ICU networks across the United States and Germany where mortality-linked reimbursement incentives justify premium acquisition costs.
- Antibiotics:Broad-spectrum and targeted anti-infective protocols remain the foundational pharmacologic intervention for SIRS of infectious origin. Japanese and French hospital procurement committees prioritize these agents within sepsis bundle compliance frameworks mandated by national health technology assessment bodies.
- Corticosteroids:Hydrocortisone and methylprednisolone protocols for refractory shock management offer lower per-dose costs with established efficacy profiles.
- Antipyretics:Temperature management adjuncts serve supportive care roles in fever reduction protocols across rehabilitation and long-term acute care settings.
Antibiotics lead volumes today; immunomodulators are gaining share fastest.
Delivery Mode:
Application urgency determines route selection, with hemodynamic instability dictating invasive administration.
- Intravenous:Direct vascular access enables immediate bioavailability for patients requiring rapid cytokine modulation or antimicrobial loading. German academic medical centers and US Level I trauma centers standardize IV-first protocols for septic shock admission pathways.
- Intramuscular:Depot formulations suit transitional care settings where vascular access maintenance proves challenging. Regional Japanese clinics utilize IM corticosteroid protocols for moderate SIRS presentations outside metropolitan ICU networks.
- Oral:Step-down therapy and prophylactic regimens favor enteral administration for hemodynamically stabilized patients.
- Topical:Localized inflammatory manifestations in burn and wound-associated SIRS receive targeted surface application.
Intravenous administration dominates acute revenue; oral formulations are expanding most quickly in cost-conscious markets.
Therapy Area:
Customer reimbursement intensity varies by underlying etiology, with mortality-linked indications commanding premium formulary placement.
- Sepsis:Dysregulated host response to infection generates the highest per-patient therapy expenditure due to combination pharmacologic and device-based interventions. US CMS sepsis bundle metrics and parallel French HAS evaluation criteria direct hospital investment toward mortality-reduction protocols.
- Infectious Diseases:Non-septic systemic inflammatory states from severe pneumonia and intra-abdominal infections drive substantial antibiotic consumption. Italian and Spanish hospital networks prioritize pathogen-specific stewardship programs within this segment.
- Trauma:Injury-induced systemic inflammation requires multimodal management addressing hemorrhage, tissue damage, and secondary infection risk.
- Autoimmune Disorders:Cytokine storm presentations in conditions such as Still's disease and lupus flare-ups utilize overlapping therapeutic modalities with sepsis protocols.
Sepsis applications anchor current value; autoimmune disorder protocols show steepest expansion trajectory.
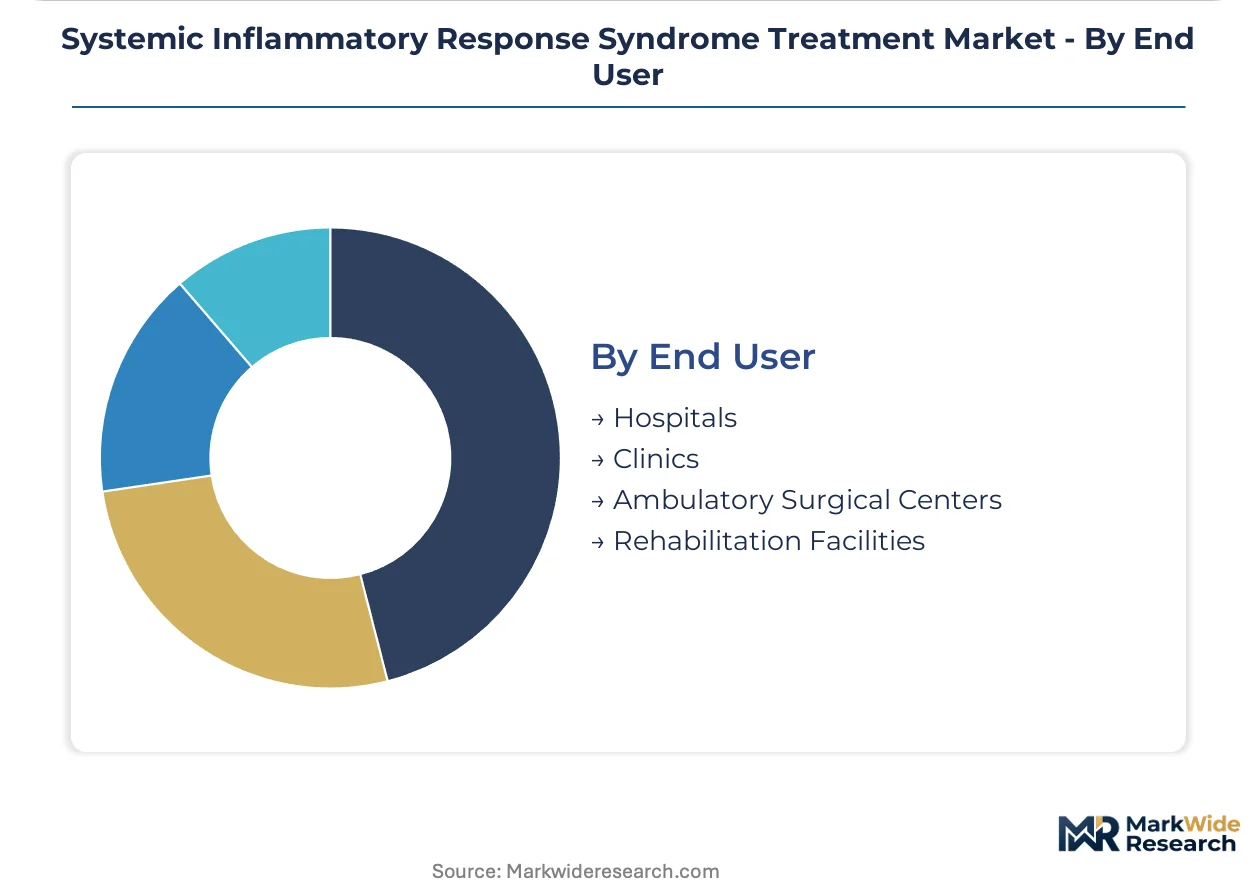
End User:
Volume concentration and margin structure diverge sharply across facility types, with integrated networks favoring single-source contracting.
- Hospitals:Tertiary and community hospital systems command the predominant share of SIRS therapy procurement through emergency department and ICU admission volumes. Texas and Florida multi-hospital systems in the United States unbundle device and pharmaceutical procurement to enable specialized critical-care supplier competition.
- Clinics:Outpatient infusion centers and urgent care facilities manage stabilized SIRS presentations with reduced monitoring intensity. German ambulatory care networks increasingly adopt cytokine adsorption protocols for early intervention outside traditional inpatient settings.
- Ambulatory Surgical Centers:Perioperative inflammatory prophylaxis and post-procedure monitoring create targeted demand for short-acting immunomodulatory agents.
- Rehabilitation Facilities:Long-term acute care hospitals and skilled nursing facilities manage recovery-phase SIRS with emphasis on cost-efficient oral and IM administration routes.
Hospitals generate dominant volume today; clinics are climbing the fastest as ambulatory capabilities expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan sustain comparable ICU bed densities yet diverge sharply in cytokine adsorption adoption rates, while the United States and emerging Asian markets present contrasting procurement consolidation patterns.
United States
Texas and Florida multi-hospital systems unbundle device procurement from pharmaceutical formulary decisions, creating separate contracting streams for blood purification hardware. CMS sepsis bundle metrics direct hospital investment toward mortality-reduction protocols with 72-hour organ failure endpoints. Level I trauma centers in Houston and Miami standardize IV-first septic shock admission pathways.
Germany
Academic medical centers in Munich and Heidelberg have adopted polystyrene-divinylbenzene copolymer sorbents for refractory septic shock protocols. The EU MDR's stricter Class III device classification extends registration timelines for extracorporeal manufacturers without notified body pre-arrangements. Bavarian hospital networks prioritize MDR-certified systems in procurement evaluations.
Japan
Regional hospitals outside metropolitan ICU networks present underutilized cytokine storm management protocols for blood purification system distributors. METI infrastructure incentives sustain bed capacity additions that expand the addressable patient base for cytokine adsorption therapies. The Kansai region around Osaka shows particular concentration in extracorporeal technology assessment.
United Kingdom
NHS England's sepsis improvement program mandates standardized inflammatory biomarker monitoring across acute trusts. London teaching hospitals pilot machine learning-enhanced hemodynamic surveillance for earlier SIRS identification. The MHRA operates accelerated assessment pathways for novel immunomodulators targeting life-threatening conditions.
France
French hospitals prioritize MDR-certified extracorporeal systems alongside ANSM pharmacovigilance requirements for biologic immunomodulators. The HAS evaluation criteria parallel US CMS metrics in directing investment toward mortality-reduction protocols. Lyon and Paris medical centers concentrate cytokine adsorption technology assessment expertise.
Systemic Inflammatory Response Syndrome Treatment Market Competitive Landscape
United States pharmaceutical conglomerates anchor one tier; German and Japanese device specialists hold differentiated positions in blood purification technology. The vendor base stratifies across integrated critical-care suppliers capable of bundling pharmacologic and device interventions, mid-scale immunomodulator developers, and focused extracorporeal system fabricators. Three archetypes dominate: broad anti-infective portfolio holders, selective cytokine pathway biologic developers, and sorbent-based blood purification engineers. Competitive moves concentrate on strategic partnerships with hospital networks and technology licensing arrangements for EU MDR compliance acceleration.
Within the biologic immunomodulator tier, AstraZeneca and GlaxoSmithKline Plc represent large-cap developers with established inflammation research infrastructures. Among blood purification specialists, CytoSorbents Corporation exemplifies the focused device archetype, while Asahi Kasei occupies a position bridging materials science and medical device fabrication. Siemens Healthineers sits within the diversified medtech conglomerate category with critical care monitoring and therapeutic device breadth. Pfizer anchors the broad anti-infective portfolio segment with established integrated delivery network relationships.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GlaxoSmithKline Plc |
| AstraZeneca |
| Asahi Kasei |
| Adrenomed AG |
| CytoSorbents Corporation |
| Pfizer |
| Recce Pharmaceuticals |
| Convatec Group Plc |
| Others |
Value Network & Pricing Analysis
Polystyrene-divinylbenzene copolymer sorbent manufacturing scale-up in specialized German and Austrian facilities is compressing per-treatment device costs while concentrating supply relationships among three notified-body-certified fabricators. This production-method transition simultaneously enables hospital network volume contracting and narrows vendor qualification pools for blood purification hardware.
Pricing Analysis
Capacity additions in Bavaria and Baden-Württemberg are reshaping price floors for cytokine adsorption cartridges. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified systems with clinical evidence packages from legacy CE-marked devices and unbundled consumable-only contracts. Price differentiation hinges on ISO 13485 certification tier and after-sales technical support bundling. Cost compression in the standard tier is intensifying because Japanese METI infrastructure subsidies are expanding regional hospital procurement autonomy. Community hospital systems exhibit highest price sensitivity; academic medical centers prioritize mortality-reduction efficacy over per-treatment economics.
Supply Chain Analysis
Mammalian cell culture media supply rests on German and Swiss specialty chemical producers for recombinant immunomodulator manufacturing. Sorbent resin fabrication draws from Austrian polymer specialists and Japanese materials science divisions. Blood purification device assembly sources from Germany, Japan, and the United States. Single-source vulnerability concentrates in notified body auditor availability for EU MDR Class III certification. Distribution runs through integrated delivery network procurement consortia in Texas and Florida, with separate pharmaceutical formulary and device hardware contracting streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR implementation and FDA sepsis guidance alignment are accelerating vendor consolidation and evidence-generation investment requirements.
For Market Incumbents: Extend EU MDR technical documentation capabilities through notified body pre-arrangements before competitor queue positioning hardens. Anchor integrated delivery network relationships by bundling cytokine adsorption hardware with anti-infective protocol consulting. Biologic input cost volatility from agricultural commodity-linked serum prices threatens margin stability; backward integration into cell culture media sourcing mitigates this exposure.
For New Entrants and Emerging Players: Specialized critical-care distributors in the Kansai region offer the most penetrable channel for blood purification system market entry. Target underutilized cytokine storm management protocols in regional Japanese hospitals outside metropolitan ICU networks. Machine learning-enhanced hemodynamic surveillance integration provides a differentiated go-to-market angle for earlier SIRS identification.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale immunomodulator developers because FDA sepsis guidance standardization is elevating Phase III trial costs beyond standalone capitalization. Five-to-ten year viability favors platforms with both pharmacologic and device-based intervention capabilities. Watch CMS sepsis bundle reimbursement criteria evolution as the inflection indicator for formulary placement prioritization.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerated notified body engagement compresses registration timelines for Class III devices. |
| Hospital System Partnership | Texas and Florida multi-hospital consortia unbundle procurement streams for specialized supplier access. |
| Reimbursement Strategy | CMS sepsis bundle alignment secures sustainable formulary placement for mortality-reduction protocols. |
| Software Companion Development | Machine learning-enhanced monitoring enables earlier SIRS identification for intervention timing optimization. |
| Manufacturing Scale-Up | Polystyrene-divinylbenzene copolymer sorbent production expansion lowers per-treatment device costs. |
Research Methodology
Multiple input streams — intensive care unit pharmacy directors, hospital procurement committee members, extracorporeal device biomedical engineers, and GPO contracts managers — were reconciled against FDA Division of Anti-Infective Products filings, EMA Committee for Medicinal Products for Human Use assessments, ClinicalTrials.gov protocol registries, and CMS sepsis bundle documentation. Secondary validation incorporated hospital procurement database analysis and EU MDR notified body certification records. Bottom-up patient volume modeling and top-down therapy expenditure estimates were triangulated to establish market sizing.
Cross-referencing historical cytokine adsorption adoption curves with panel input from German academic medical centers and Japanese regional hospital networks informed the analytical framework. Segmentation dimensions modeled encompass product type, delivery mode, therapy area, and end-user facility tier alongside regional regulatory cluster classification. CAGRs were derived from therapy volume projections calibrated to ICU bed capacity expansion trajectories and immunomodulator pipeline advancement rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, biologic input cost volatility, and CMS reimbursement criteria evolution. Forecasts reflect documented assumptions regarding regulatory pathway standardization and hospital procurement consolidation trajectories. A small set of named triggers — ISO 13485 auditor availability, notified body capacity constraints, and sepsis bundle metric revisions — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Myasthenia Gravis Treatment Market