
 Pelvic Organ Prolapse Repair Market | 2026-2036
Pelvic Organ Prolapse Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Organ Prolapse Repair Market Intelligence
Outpatient surgery centers is redrawing procurement patterns in pelvic organ prolapse repair, capturing volume once held by inpatient women's health hospitals. Boston Scientific Corporation leverages its synthetic mesh portfolio to sustain dominance in minimally invasive deployment categories. Coloplast A/S anchors its position through specialized urogynecology channel control across Nordic and North American markets. CooperSurgical, Inc. differentiates via biological graft R&D intensity targeting mesh-complication patient subsets.
Pelvic organ prolapse repair encompasses surgical and non-surgical interventions that restore anatomical support to prolapsed pelvic structures, employing polypropylene mesh, porcine or human-derived biological grafts, and permanent or absorbable sutures designed to withstand intraperitoneal pressure loads exceeding 40 mmHg during Valsalva maneuvers. The primary commercial purpose centers on symptom resolution and quality-of-life restoration for women experiencing stage II-IV prolapse. Synthetic mesh retains the largest revenue share despite litigation headwinds, while biological grafts command premium positioning in revision surgeries where host-tissue integration failure risks dominate clinical decision-making. Robotic-assisted deployment represents the fastest-growing procedural category, though vaginal surgery maintains the highest absolute case volume due to cost-accessibility advantages in emerging markets.
FDA 510(k) clearance pathways and EU MDR Class III device requirements impose substantial clinical evidence burdens on mesh manufacturers, directly elevating R&D thresholds and consolidating market access around well-capitalized incumbents. ISO 10993 biocompatibility testing and ASTM F2450 surgical mesh characterization standards further delineate product qualification protocols that shape competitive viability. Stakeholders must monitor evolving regulatory post-market surveillance mandates and reimbursement compression dynamics in outpatient settings to anticipate portfolio reallocation requirements.
Market Dynamics
Procedural migration toward outpatient settings is compressing hospital purchasing power while elevating ambulatory surgery center procurement sophistication, forcing manufacturers to reconfigure distribution and service models around lower-volume, higher-velocity fulfillment patterns.
Growth Catalysts
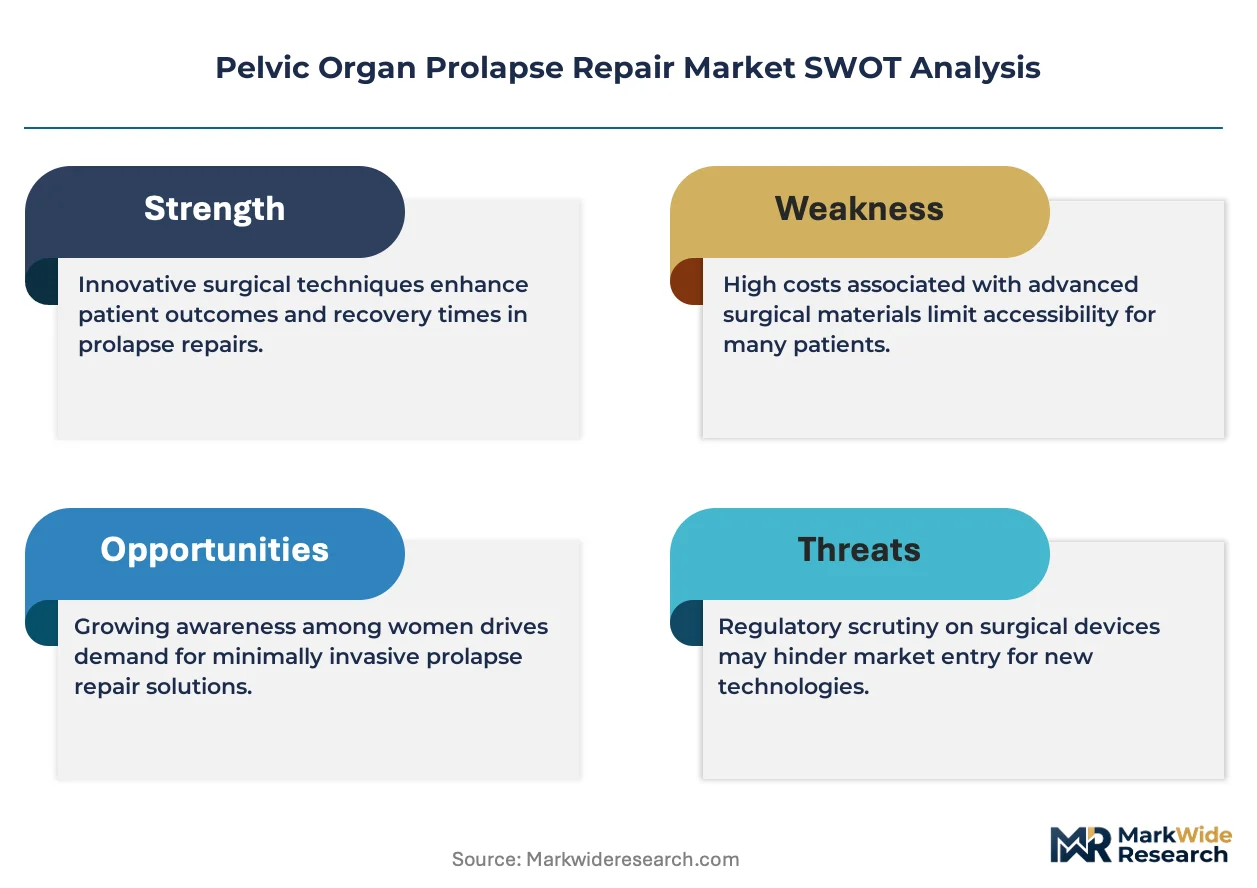
- EU MDR Class III device requirements:Elevated clinical evidence standards are filtering out undercapitalized competitors, consolidating market access around manufacturers with robust trial infrastructure and accelerating premium product positioning.
- Robotic-assisted deployment:Da Vinci surgical systems enable precise mesh placement with reduced recurrence rates, driving adoption among high-volume urogynecology practices seeking differentiation through technical sophistication.
- Revision surgery patient subsets:Biological graft demand concentrates among women with prior synthetic mesh complications, creating premium pricing power for porcine and human-derived tissue products with demonstrated host integration profiles.
Market Restraints
- Polypropylene input cost volatility:Petrochemical feedstock fluctuations directly compress synthetic mesh margins, particularly for standardized mid-tier products lacking pricing elasticity in competitive tenders.
- FDA 510(k) clearance timelines:Extended premarket notification review periods delay product launches and freeze R&D capital for 18-24 months, disadvantaging smaller manufacturers against well-resourced incumbents.
- Pessary non-surgical substitutes:Conservative management devices capture early-stage prolapse patients, narrowing the addressable surgical population to stage III-IV cases with symptom severity thresholds.
Strategic Opportunities
- India outpatient infrastructure buildout:Private hospital chains in Mumbai and Delhi are establishing dedicated urogynecology day-surgery units, creating first-mover positioning for mesh suppliers with localized regulatory filing capabilities.
- Biological-nanotechnology convergence:Collagen scaffold engineering combined with growth factor impregnation promises accelerated tissue ingrowth, targeting the revision surgery premium segment with differentiated clinical outcomes.
- Direct-to-facility distribution:Bypassing traditional hospital purchasing consortia through specialized urogynecology distributor networks captures margin and accelerates product education in high-volume ambulatory centers.
Industry Challenges
- ISO 10993 biocompatibility testing capacity:Contract laboratory bottlenecks extend product qualification timelines, forcing manufacturers to build in-house toxicology capabilities or accept delayed market entry.
- ASTM F2450 mesh characterization standard evolution:Shifting mechanical testing protocols require retooling of quality systems and potential design modifications for existing cleared products.
- Surgeon training pathway fragmentation:Inconsistent fellowship exposure to robotic and advanced laparoscopic techniques creates geographic deployment disparities and limits addressable market expansion in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Organ Prolapse Repair Market |
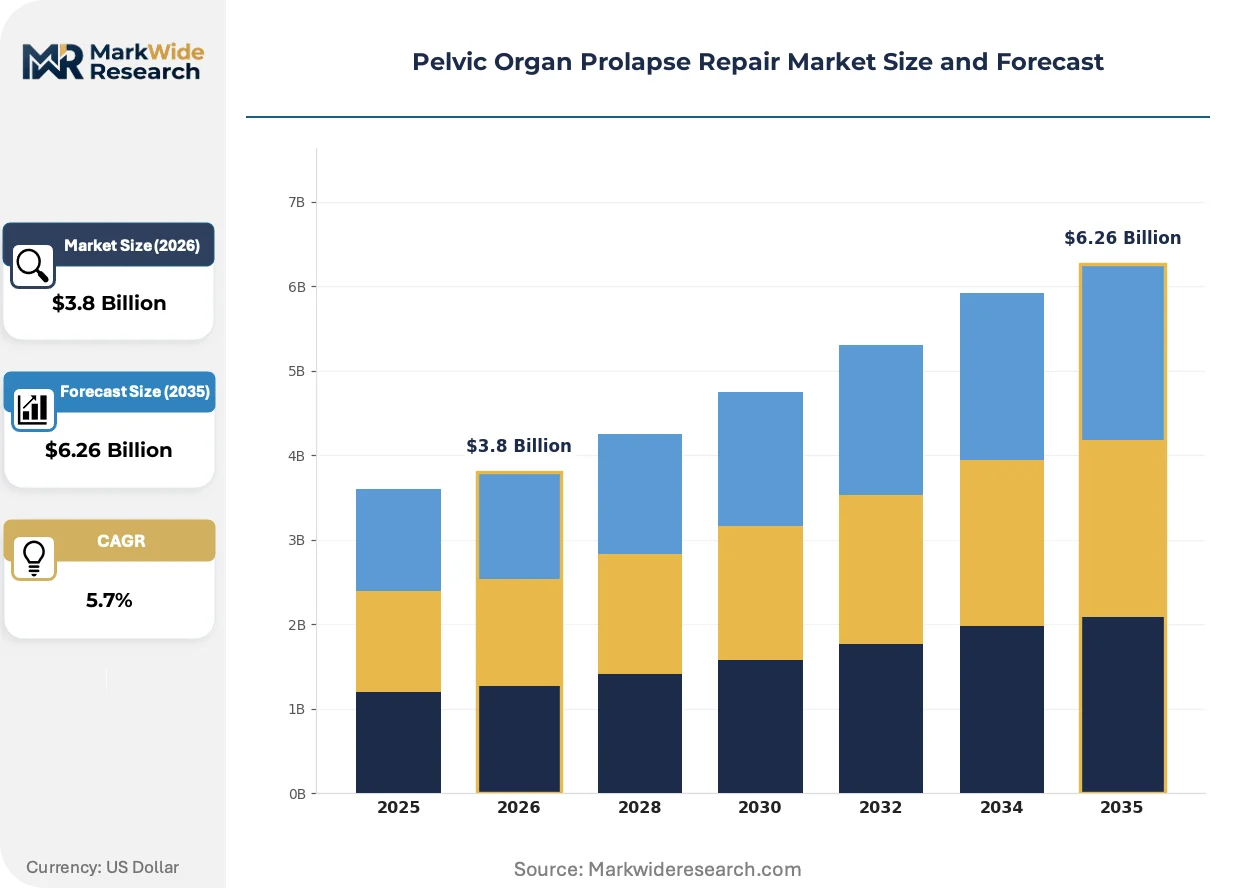
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Mesh, Biological Grafts, Sutures, Support Devices, Sling Systems Therapy Area: Uterine Prolapse, Cystocele, Rectocele, Enterocele, Vaginal Vault Prolapse End User: Gynecology Clinics, Specialized Surgical Centers, Outpatient Surgery Centers, Women's Health Hospitals Deployment: Open Surgery, Laparoscopic Repair, Robotic-Assisted Surgery, Vaginal Surgery |
| Companies Covered | Boston Scientific Corporation, Coloplast A/S, Johnson & Johnson Services, Inc., CooperSurgical, Inc., Ethicon Inc, Caldera Medical, Medtronic, Integra LifeSciences Corporation, Cook Group Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Organ Prolapse Repair Market Strategic Shifts & Innovations
Mesh material science and deployment platform evolution are bifurcating the competitive landscape between synthetic durability and biological integration, with regulatory surveillance intensity accelerating product lifecycle compression and forcing faster generational turnover.
Absorbable synthetic polymers are fragmenting the traditional permanent mesh category by offering intermediate-term mechanical support with eventual complete resorption, eliminating long-term erosion risks that drove litigation against polypropylene products. Ambulatory surgery centers in the United States are piloting these materials for younger patients with stage II-III prolapse who prioritize future fertility and mesh-free anatomy. The structural consequence is compressing revenue per procedure while expanding eligible patient populations beyond the historical 55-plus demographic.
EU MDR post-market surveillance mandates now require systematic long-term follow-up data collection for all implanted surgical mesh, transforming regulatory compliance from a premarket checkpoint into a continuous data infrastructure burden. Manufacturers must maintain patient registries with 10-year outcome tracking, elevating operational costs and favoring organizations with existing electronic health record integration capabilities. Nordic markets with centralized national health databases are adapting most rapidly, while fragmented Southern European systems face implementation delays.
Patient-directed care pathways are displacing traditional physician-referral networks as women increasingly research mesh complications and biological alternatives through online urogynecology communities before specialist consultation. This information asymmetry reduction empowers demand for specific product categories—particularly porcine-derived grafts—and pressures surgeons to justify material selection with transparent outcome data. California and New York metropolitan markets exhibit the most pronounced behavioral shift, with direct-to-consumer advertising from biological graft manufacturers accelerating the transition.
Pelvic Organ Prolapse Repair Market Segmentation
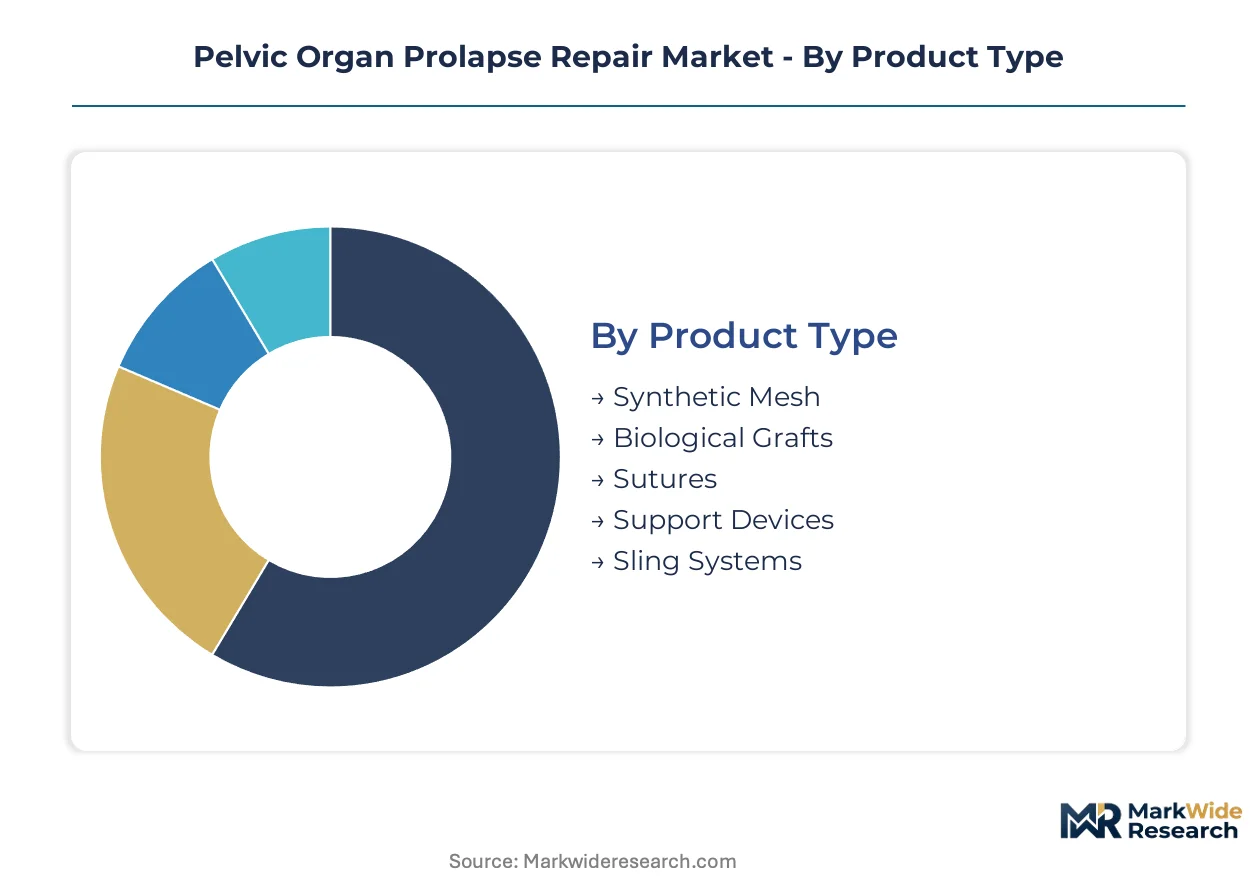
Pelvic organ prolapse repair segmentation reveals distinct procurement patterns across channels, with outpatient migration and reimbursement tiering creating divergent demand profiles for each product and deployment category. Understanding these segment boundaries enables targeted portfolio positioning against specific clinical and economic decision criteria.
Product Type:
Channel mix varies sharply by material category, with synthetic mesh flowing predominantly through hospital consortia contracts while biological grafts penetrate via specialized urogynecology distributor networks.
- Synthetic Mesh:Polypropylene monofilament or multifilament constructs dominate procedural volume through standardized kit configurations. United States hospital purchasing coalitions concentrate demand for mid-tier mesh specifications, though litigation exposure continues compressing pricing elasticity and accelerating absorbable polymer substitution.
- Biological Grafts:Porcine small intestinal submucosa and human dermal allografts command premium positioning in revision surgery pathways. Nordic markets with centralized outcome databases demonstrate fastest adoption rates, driven by EU MDR post-market surveillance requirements favoring documented host-tissue integration profiles.
- Sutures:Permanent and delayed-absorbable monofilaments serve native tissue repair techniques without mesh implantation.
- Support Devices:Pessaries and mechanical supports address non-surgical management of early-stage prolapse.
- Sling Systems:Pre-shaped mesh configurations target stress urinary incontinence concomitant with prolapse repair.
Synthetic mesh dominates installed base. Biological grafts are where expansion concentrates.
Therapy Area:
Cost tier stratification separates high-complexity vault procedures reimbursed at premium rates from standardized anterior compartment repairs subject to outpatient compression.
- Uterine Prolapse:Hysterectomy-concomitant repair represents the highest absolute procedure volume across all therapy areas. India's private hospital chains in Mumbai and Delhi are establishing dedicated day-surgery units for uterine-sparing sacrohysteropexy, creating volume concentration in emerging market outpatient infrastructure.
- Cystocele:Anterior vaginal wall prolapse repairs utilize the broadest product mix from simple plication sutures to full mesh kits. United States ambulatory surgery centers capture increasing cystocele volume through streamlined anterior colporrhaphy protocols, compressing revenue per procedure while expanding eligible patient populations.
- Rectocele:Posterior compartment defects drive biological graft preference where host-tissue quality concerns dominate.
- Enterocele:Apical enterocele repairs require advanced laparoscopic or robotic access for adequate visualization.
- Vaginal Vault Prolapse:Post-hysterectomy apical descent commands premium reimbursement in hospital settings.
Cystocele repairs generate highest procedural frequency. Vaginal vault prolapse represents the steepest expansion trajectory in robotic-assisted deployment categories.
End User:
Customer type fragmentation creates distinct service requirements, with high-velocity outpatient centers demanding just-in-time inventory against hospital systems negotiating enterprise pricing.
- Gynecology Clinics:Office-based diagnostic and pessary fitting services refer surgical cases to affiliated facilities.
- Specialized Surgical Centers:Dedicated urogynecology units concentrate expertise and procedure volume for complex repairs.
- Outpatient Surgery Centers:Ambulatory facilities in the United States are capturing volume once held by inpatient women's health hospitals through procedural migration. These centers prioritize kit standardization and rapid inventory turnover, forcing manufacturers to reconfigure distribution around lower-volume, higher-velocity fulfillment patterns.
- Women's Health Hospitals:Academic medical centers retain complex revision and multi-compartment cases requiring extended observation.
Women's health hospitals retain complex case concentration. Outpatient surgery centers are gaining share fastest across all therapy areas.
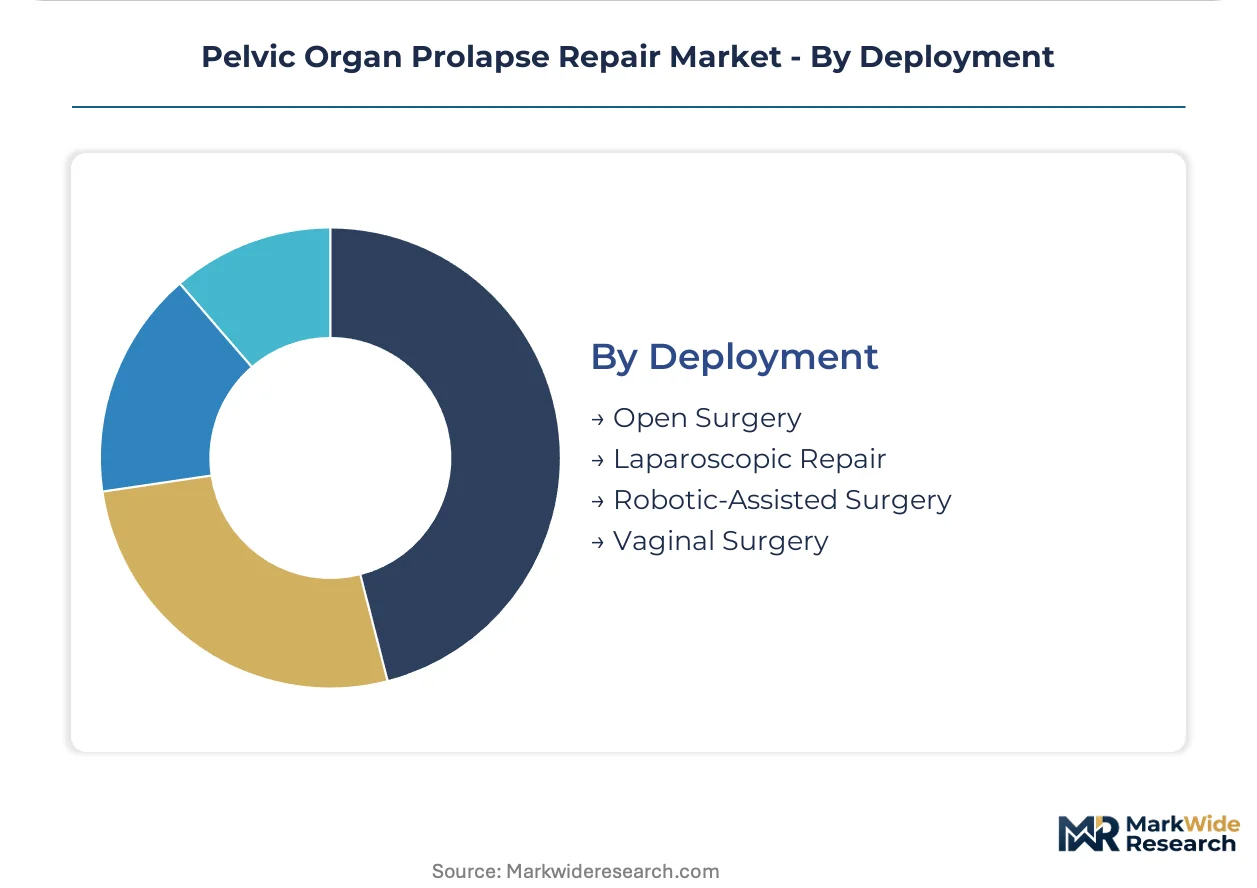
Deployment:
Technology maturity separates established vaginal approaches from capital-intensive robotic platforms, with laparoscopic repair occupying an intermediate position subject to surgeon training pathway availability.
- Open Surgery:Abdominal sacrocolpopexy through laparotomy retains indication for concomitant complex procedures.
- Laparoscopic Repair:Minimally invasive abdominal approaches require specialized suturing skill for mesh attachment.
- Robotic-Assisted Surgery:Da Vinci surgical systems enable precise mesh placement with reduced recurrence rates. California and New York metropolitan markets exhibit pronounced adoption concentration, with high-volume urogynecology practices seeking differentiation through technical sophistication and transparent outcome data.
- Vaginal Surgery:Native tissue and mesh-augmented vaginal approaches maintain highest absolute case volume globally. Cost-accessibility advantages in emerging markets sustain demand despite technical limitations for apical suspension, with India's private chains expanding dedicated day-surgery capacity.
Vaginal surgery commands highest procedural volume. Robotic-assisted deployment shows the most rapid technology diffusion in premium reimbursement markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Outpatient surgery centers in the United States concentrate the highest absolute buyer spending, while Nordic outcome-tracking infrastructure and Indian day-surgery buildouts reshape procurement geography.
United States
Ambulatory surgery centers in California and New York metropolitan markets capture procedural volume migrating from inpatient women's health hospitals. FDA 510(k) clearance pathways impose 18-24 month premarket notification timelines that freeze R&D capital for smaller manufacturers. Boston Scientific Corporation anchors synthetic mesh supply through specialized urogynecology distributor networks in high-velocity fulfillment zones.
Germany
Centralized statutory health insurance reimbursement supports higher intervention rates for stage III-IV prolapse repairs compared to Southern European markets. EU MDR Class III device requirements and post-market surveillance mandates filter out undercapitalized competitors, consolidating market access around manufacturers with robust trial infrastructure. The Rhine-Ruhr metropolitan region concentrates robotic-assisted deployment adoption among high-volume urogynecology practices seeking technical differentiation.
India
Private hospital chains in Mumbai and Delhi are establishing dedicated urogynecology day-surgery units for uterine-sparing sacrohysteropexy, creating volume concentration in emerging market outpatient infrastructure. CDSCO medical device registration requirements for imported surgical mesh elevate regulatory filing burdens on foreign suppliers. Cost-accessibility advantages sustain vaginal surgery demand despite technical limitations for apical suspension procedures.
Sweden
National health databases enable rapid adaptation to EU MDR post-market surveillance mandates requiring systematic long-term follow-up data collection. Biological graft demand concentrates among women with prior synthetic mesh complications, creating premium pricing power for porcine-derived products with demonstrated host-tissue integration profiles. Stockholm-based academic medical centers retain complex revision and multi-compartment cases requiring extended observation protocols.
Japan
Aging demographics and universal health coverage infrastructure support intervention rates comparable to Western European markets. PMDA premarket approval requirements for surgical mesh impose substantial clinical evidence burdens that elevate R&D thresholds. The Kanto region around Tokyo concentrates robotic-assisted deployment expertise, though vaginal surgery maintains highest absolute case volume due to cost-accessibility considerations in secondary markets.
Pelvic Organ Prolapse Repair Market Key Industry Players
Player mix skews toward diversified medical device conglomerates with established urogynecology channel control, though biological graft specialists occupy premium positioning in revision surgery pathways. Market structure reflects tiered consolidation: well-capitalized incumbents with FDA 510(k) clearance infrastructure dominate synthetic mesh categories, while smaller manufacturers concentrate in absorbable polymer niches and biological-nanotechnology convergence segments. Strategic archetypes include synthetic mesh generalists, biological graft premium specialists, and robotic deployment platform partners. Dominant competitive moves encompass direct-to-facility distribution bypassing hospital purchasing consortia, and in-house toxicology capability building to circumvent ISO 10993 biocompatibility testing bottlenecks.
Within the diversified conglomerate tier, Boston Scientific Corporation and Coloplast A/S exemplify archetypes with sustained channel dominance across deployment categories. Johnson & Johnson Services, Inc. occupies a position reflecting historical synthetic mesh litigation exposure and portfolio reallocation toward biological alternatives. CooperSurgical, Inc. sits within the biological graft specialist archetype, representing premium positioning in mesh-complication patient subsets. These three entities anchor competitive dynamics around regulatory filing capacity, specialized distributor network control, and R&D intensity targeting host-tissue integration profiles.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Coloplast A/S |
| Johnson & Johnson Services, Inc. |
| CooperSurgical, Inc. |
| Ethicon Inc |
| Caldera Medical |
| Medtronic |
| Integra LifeSciences Corporation |
| Cook Group Incorporated |
| Others |
Cost & Logistics Intelligence
Absorbable polymer substitution for permanent polypropylene mesh simultaneously shifts procurement geography toward Nordic outcome-tracking markets and compresses revenue per procedure while expanding addressable patient populations beyond historical demographics. This material transition feeds back into supplier consolidation, as biological graft manufacturers with demonstrated host-tissue integration profiles capture premium positioning in revision surgery pathways.
Pricing Analysis
Technology-generation pricing gaps separate permanent synthetic mesh at economy positioning, absorbable polymers at mid-tier standard placement, and biological grafts at premium levels. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 10993 biocompatibility certification depth, and volume scale through hospital purchasing coalitions. Pricing pressure stems from outpatient surgery center kit standardization demands compressing margins on legacy polypropylene products. Ambulatory facilities exhibit highest price sensitivity due to reimbursement compression, while academic medical centers retain lowest sensitivity for complex revision cases.
Supply Chain Analysis
The United States and Germany anchor synthetic mesh manufacturing through Boston Scientific and Coloplast A/S production facilities, while Denmark and Sweden concentrate biological graft processing from porcine and human-derived tissue sources. Polypropylene petrochemical feedstocks, porcine small intestinal submucosa, and human dermal allografts constitute critical input dependencies. Single-source vulnerability in ISO 10993 biocompatibility testing contract laboratories extends product qualification timelines. Distribution runs through specialized urogynecology distributor networks bypassing traditional hospital purchasing consortia in high-velocity ambulatory centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outpatient procedural migration represents an early-cycle expansion story, with ambulatory surgery center infrastructure buildout creating new addressable demand beyond traditional hospital-based intervention pools.
For Market Incumbents: Compound channel control through direct-to-facility distribution networks targeting high-volume urogynecology practices in California and New York metropolitan markets. Deepen backward integration into biological tissue processing to circumvent porcine-derived graft supply bottlenecks. Absorbable polymer R&D intensity serves as the priority defensive lever against litigation-exposed permanent mesh portfolios. For New Entrants and Emerging Players: Post-market surveillance data infrastructure services present a service-layer gap where incumbents under-serve EU MDR compliance requirements. Target Nordic markets with centralized national health databases for fastest biological graft penetration. Pursue CDSCO registration capabilities for India's Mumbai and Delhi day-surgery buildouts as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors biological-nanotechnology convergence specialists with host-tissue integration IP. Long-term viability across the projection horizon hinges on patient registry infrastructure and electronic health record integration capabilities. Watch EU MDR post-market surveillance implementation delays in Southern European systems as the inflection indicator for competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for absorbable polymer mesh in US ambulatory centers. |
| CE Marking Pathway | Enables biological graft distribution under EU MDR Class III surveillance mandates. |
| Hospital System Partnership | Locks in procurement volume through specialized urogynecology distributor networks. |
| Software Companion Development | Supports EU MDR patient registry compliance with electronic health record integration. |
| Reimbursement Strategy | Secures outpatient surgery center coverage for robotic-assisted deployment categories. |
Research Approach
A spread of perspectives from urogynecology surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions driving this analysis. Primary interview data combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up procedure volume modeling and top-down market sizing triangulation anchored the quantitative framework.
Segmentation dimensions modeled encompass product type, therapy area, end user facility type, and deployment technology across the analysis window. CAGRs derive from procedure migration rates, reimbursement tier evolution, and material substitution elasticity. Forecast inputs include robotic-assisted deployment diffusion curves, biological graft adoption in revision surgery pathways, and outpatient infrastructure buildout velocity.
Forecasts assume regulatory continuity in FDA 510(k) and EU MDR Class III device frameworks; material policy shifts would require re-modeling. Specific risks encompass polypropylene litigation exposure expansion, ISO 10993 testing capacity constraints, and surgeon training pathway fragmentation limiting addressable market expansion. Recalibration cycles align with material shifts in reimbursement tiering and post-market surveillance mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Premenstrual Syndrome Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Liver Transplantation Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Hyperammonemia Treatment Market