
 Acupuncture Treatment Market | 2026-2036
Acupuncture Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acupuncture Treatment Market Analytics
China is rewriting the supply landscape for acupuncture needles and electro-stimulation devices through scaled manufacturing clusters in Jiangsu and Zhejiang provinces. Mayo Clinic leverages its integrative medicine infrastructure to anchor clinical acupuncture programs across multiple US states. Modern Acupuncture competes through a franchise model that standardizes treatment protocols and controls patient flow across retail locations. ACA Acupuncture & Wellness specializes in community-style delivery, positioning its sliding-scale model to extend access in urban markets.
Acupuncture treatment involves the insertion of sterile filiform needles at specific anatomical points to modulate neurophysiological pathways, typically using needles ranging from 0.12 mm to 0.35 mm in diameter and 15 mm to 75 mm in length. The practice aims to restore homeostatic function by stimulating afferent nerve fibers and triggering endogenous opioid release. Pain Management applications dominate volume due to chronic condition prevalence and opioid-alternative prescribing trends among Western physicians. Private Clinics capture the deepest margin pools through direct-pay models, while Telehealth Consultations represent the fastest-growing delivery mode as practitioners adapt diagnostic and treatment guidance to remote formats.
The FDA regulates acupuncture needles as Class II medical devices under 21 CFR 880.5580, requiring sterility and single-use labeling that shapes product manufacturing standards and import compliance. China's NMPA oversees domestic device registration and Good Manufacturing Practice certification for needle producers, creating a dual-track compliance environment for exporters. WHO guidelines on traditional medicine safety provide a reference framework that national regulators in South Korea and Australia have adopted for practitioner training benchmarks. Stakeholders must monitor evolving insurance coding decisions by CMS and private payers that will determine whether acupuncture shifts from out-of-pocket cash payment to reimbursed care.
Market Dynamics
The WHO's inclusion of traditional medicine in the International Classification of Diseases is forcing insurance reimbursement frameworks to evolve across multiple jurisdictions, converting acupuncture from cash-pay wellness to billable medical care.
Growth Catalysts
- Opioid-alternative prescribing:Western physicians in pain management specialties are integrating needle-based therapies into chronic condition protocols. This shift reduces pharmaceutical dependency while expanding clinic referral volumes.
- CMS coding evolution:The US Centers for Medicare & Medicaid Services is expanding coverage determinations for acupuncture in low back pain management. This regulatory movement unlocks patient access previously blocked by out-of-pocket cost barriers.
- Standardized licensure pathways:Germany, South Korea, and Australia have implemented uniform practitioner certification requirements. These frameworks reduce regulatory friction and enable franchise model replication across urban clinic networks.
Market Restraints
- Needle supply concentration:Manufacturing clusters in Jiangsu and Zhejiang provinces control global production of sterile filiform needles. This geographic dependency creates vulnerability to export licensing delays and quality enforcement actions by China's NMPA.
- Reimbursement lag:Private insurers in the United States maintain inconsistent prior authorization requirements for acupuncture services. This administrative friction limits patient conversion from consultation to treatment.
- Practitioner training duration:Licensed acupuncturists require 1,900-3,000 hours of accredited education in most jurisdictions. This extended credentialing timeline constrains workforce expansion relative to patient demand growth.
Strategic Opportunities
- Telehealth diagnostic adaptation:Practitioners are developing remote patient assessment protocols that guide self-administered acupressure or prepare for in-person needle sessions. This channel innovation extends reach to rural and mobility-limited populations.
- Community-style delivery models:Sliding-scale payment structures in urban markets are capturing price-sensitive patients excluded from premium private clinic networks. This approach builds volume through high-throughput, semi-private treatment rooms.
- Electro-stimulation device integration:Combination therapies merging traditional needle insertion with peripheral nerve stimulation are gaining traction in sports medicine and rehabilitation centers. This technology convergence commands higher reimbursement rates than manual techniques alone.
Industry Challenges
- Practitioner workforce pipeline:Accredited acupuncture programs graduate fewer than 1,500 practitioners annually in the United States. This talent scarcity limits clinic expansion and extends patient wait times in high-demand metropolitan areas.
- FDA device compliance complexity:Single-use sterility requirements under 21 CFR 880.5580 necessitate rigorous supply chain documentation for imported needles. Smaller clinic networks struggle with vendor qualification costs and import record maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acupuncture Treatment Market |
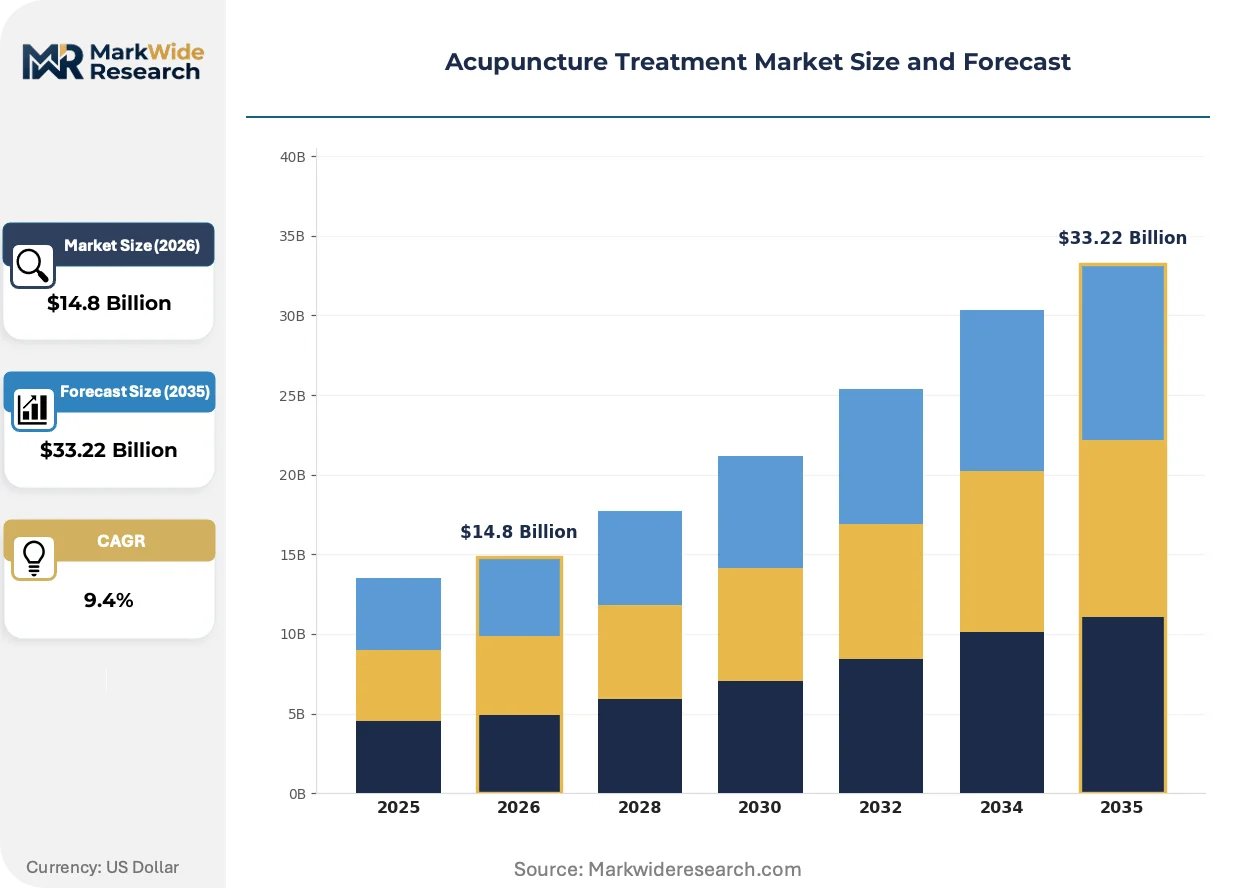
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acupuncture Needles, Electro-Acupuncture Devices, Moxibustion Tools, Acupressure Mats Application: Pain Management, Stress Relief, Digestive Disorders, Musculoskeletal Conditions End User: Private Clinics, Hospitals, Rehabilitation Centers, Home Care Delivery Mode: In-Person Treatments, Mobile Services, Telehealth Consultations, Workshops |
| Companies Covered | American College of Traditional Chinese Medicine, Mayo Clinic, Modern Acupuncture, Emory Healthcare, Allina Health, ACA Acupuncture & Wellness, Essentia Health, South Baylo University, Yinova Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acupuncture Treatment Market Evolving Landscape
Clinical acupuncture is undergoing instrumentation evolution alongside delivery model restructuring. Practitioners and device manufacturers are converging on technologies that standardize treatment reproducibility while payers pressure for outcome documentation.
Laser acupuncture devices are migrating from experimental applications to mainstream pain management protocols. Sports medicine clinics and physical therapy chains are adopting these needle-free alternatives for needle-phobic patients and surface-level point stimulation. This technology is migrating from niche wellness centers to hospital-based integrative medicine departments, compressing the addressable market for traditional filiform needles in certain indications.
The FDA's enforcement of Quality System Regulation for electro-acupuncture devices is tightening manufacturing documentation requirements. Device producers must now demonstrate electrical safety and biocompatibility testing comparable to Class II diagnostic equipment. Small-scale device manufacturers in South Korea and Taiwan are responding by consolidating through contract manufacturing partnerships to achieve regulatory economies of scale.
Self-referral patterns among chronic pain patients are displacing physician-gatekeered access in several urban markets. Direct-to-consumer marketing by franchise clinic networks is capturing patients who previously required primary care referrals. This behavioral shift is most visible in Australia and Germany, where private health insurance supplementary coverage reduces price sensitivity to direct-pay models.
Acupuncture Treatment Market Segmentation
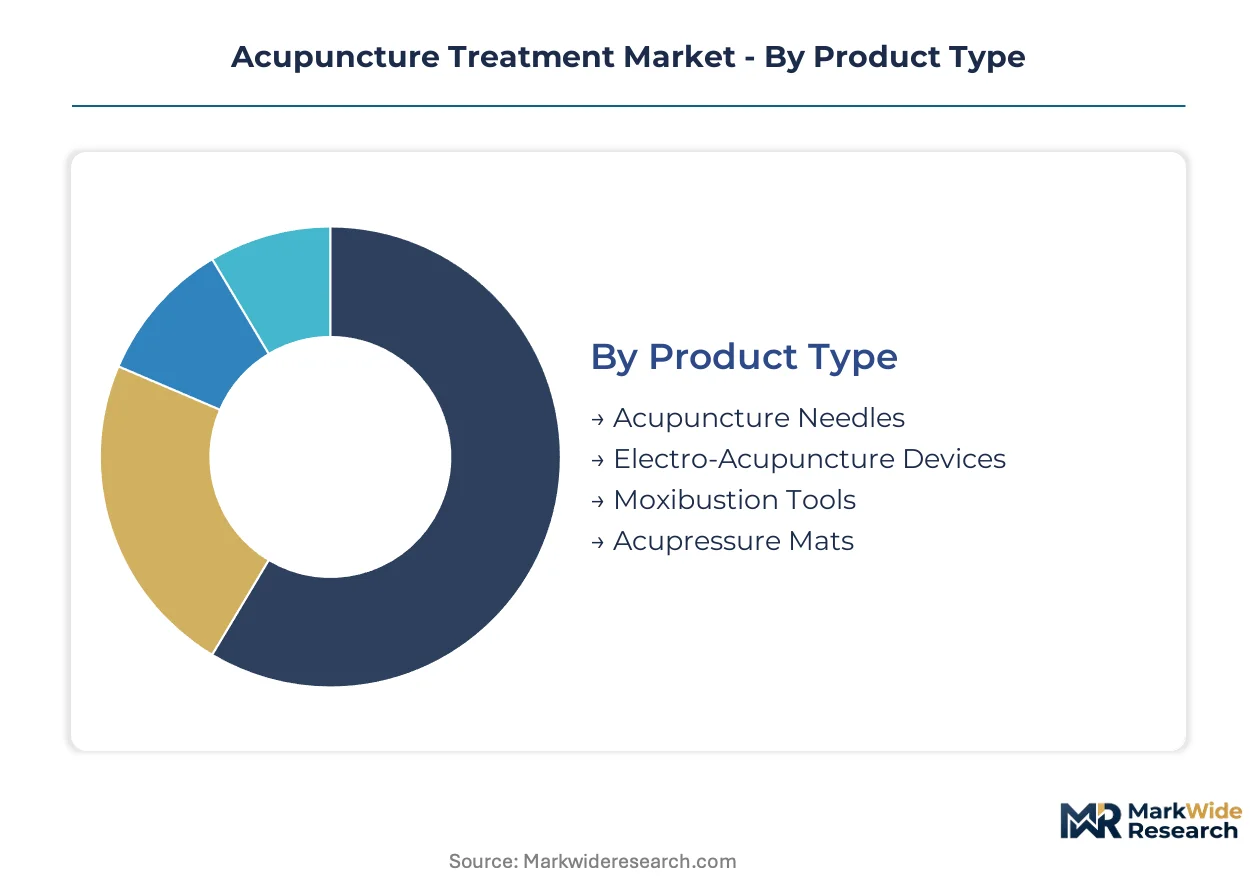
Segmentation in the acupuncture treatment market reveals divergent margin profiles and service intensity requirements across product categories and delivery channels. After-sales support demands vary sharply between disposable consumables and capital equipment, reshaping vendor business models and customer lifetime value calculations.
Product Type:
After-sales-service intensity escalates dramatically from single-use disposables to electro-stimulation capital equipment, with warranty claims and calibration demands concentrated in device segments.
- Acupuncture Needles:Sterile filiform needles manufactured from surgical-grade stainless steel, ranging 0.12-0.35mm in diameter and 15-75mm in length. Demand concentrates in private clinic networks across Germany and South Korea where bulk procurement contracts lock in multi-year supply relationships. Regulatory compliance with FDA 21 CFR 880.5580 and China's NMPA Good Manufacturing Practice certification drives vendor qualification costs.
- Electro-Acupuncture Devices:Class II medical devices delivering peripheral nerve stimulation through needle-integrated electrical leads. Rehabilitation centers in Australia and hospital integrative medicine departments in the United States command premium pricing for units with programmable frequency modulation and outcome documentation software.
- Moxibustion Tools:Heat therapy instruments utilizing compressed mugwort for indirect point stimulation. Traditional medicine practitioners in East Asian markets sustain demand despite limited insurance reimbursement.
- Acupressure Mats:Consumer-grade products featuring plastic stimulators on fabric backing. Home care adoption in urban European markets drives volume through direct-to-consumer channels with minimal service requirements.
Acupuncture Needles holds the largest share; momentum sits with Electro-Acupuncture Devices.
Application:
Clinical outcomes documentation requirements vary by therapeutic indication, with pain management protocols commanding the most rigorous reimbursement justification and regulatory scrutiny.
- Pain Management:Chronic condition protocols targeting lower back, osteoarthritis, and neuropathic pain through endogenous opioid pathway modulation. Western physician referrals in the United States are accelerating as CMS expands coverage determinations for low back pain management.
- Stress Relief:Sympathetic nervous system regulation for anxiety and sleep disorders. Corporate wellness programs in Germany and Australia are integrating employer-sponsored acupuncture benefits.
- Digestive Disorders:Gastrointestinal motility modulation through vagal nerve stimulation. Specialist referrals remain limited by inconsistent payer coverage.
- Musculoskeletal Conditions:Sports injury rehabilitation and post-surgical recovery protocols. Physical therapy chains in South Korea are adopting combination needle and electro-stimulation approaches.
Pain Management dominates volume; Stress Relief is expanding most quickly.
End User:
Capital allocation patterns and procurement sophistication diverge sharply between institutional buyers and individual practitioners, fragmenting vendor sales approaches.
- Private Clinics:Direct-pay models with sliding-scale and premium tier pricing. Franchise networks across Australia and Germany standardize protocols while capturing deepest margin pools through high patient throughput.
- Hospitals:Integrative medicine departments requiring Joint Commission compliance and electronic health record integration. Mayo Clinic's multi-state clinical acupuncture programs anchor this segment.
- Rehabilitation Centers:Post-acute care facilities combining needle therapy with physical rehabilitation. South Korean and Australian facilities lead electro-stimulation device adoption.
- Home Care:Self-administered acupressure and consumer device utilization. Telehealth guidance from licensed practitioners is extending reach to mobility-limited populations.
Private Clinics capture the highest margins; Home Care shows the steepest expansion trajectory.
Delivery Mode:
Channel economics shift dramatically with physical presence requirements, with remote formats eliminating facility overhead while constraining treatment modality scope.
- In-Person Treatments:Traditional needle insertion requiring clinical space and sterile field maintenance. Urban clinic density in Germany and South Korea enables appointment availability competitive with conventional medical specialties.
- Mobile Services:Practitioner travel to residential or corporate locations. Premium pricing in Australian metropolitan markets offsets logistical complexity.
- Telehealth Consultations:Remote diagnostic assessment and treatment guidance for self-administered acupressure. Rural patient access in the United States is climbing the fastest as licensure boards adapt scope-of-practice regulations.
- Workshops:Group education settings for wellness and preventive applications. Community-style delivery in urban US markets extends access through sliding-scale pricing.
In-Person Treatments retains volume leadership; Telehealth Consultations gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of sterile filiform needles clusters in Jiangsu and Zhejiang provinces, creating supply dependencies that ripple through clinic networks worldwide. Demand generation follows divergent regulatory pathways across major economies.
United States
Hospital integrative medicine departments and franchise clinic networks drive patient volume growth. CMS coding expansions for low back pain management are converting cash-pay wellness into reimbursed medical care. Mayo Clinic anchors multi-state clinical acupuncture programs.
Germany
Private clinic networks and corporate wellness programs sustain demand for standardized treatment protocols. Uniform practitioner certification requirements reduce regulatory friction for franchise model replication. Urban centers concentrate sliding-scale community delivery models.
China
Domestic device registration under NMPA and Good Manufacturing Practice certification shapes exporter compliance burdens. Manufacturing clusters in Jiangsu and Zhejiang provinces control global needle production volumes. Shanghai and Beijing anchor traditional medicine practitioner training pipelines.
Australia
Private health insurance supplementary coverage enables direct-to-consumer marketing by clinic networks. Rehabilitation centers lead electro-stimulation device adoption in post-acute care settings. Sydney and Melbourne concentrate urban clinic density competitive with conventional medical specialties.
South Korea
Physical therapy chains adopt combination needle and electro-stimulation approaches for sports injury rehabilitation. MFDS practitioner training benchmarks align with WHO traditional medicine safety guidelines. Seoul Capital Area standardizes licensure pathways enabling franchise replication.
Acupuncture Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in needle manufacturing and device fabrication. The market structures around three tiers: hospital-based integrative medicine departments, franchise clinic networks with standardized protocols, and independent community-style practitioners. Dominant competitive moves include strategic partnerships between device manufacturers and clinic networks, plus geographic expansion of franchise models into standardized regulatory environments.
Among hospital-based integrators, Mayo Clinic and Emory Healthcare exemplify the institutional tier with multi-state clinical program footprints. Modern Acupuncture occupies a position within the franchise model tier, standardizing treatment protocols across retail locations. ACA Acupuncture & Wellness represents the community-style delivery archetype with sliding-scale pricing structures in urban markets.
| Leading Market Players |
|---|
| American College of Traditional Chinese Medicine |
| Mayo Clinic |
| Modern Acupuncture |
| Emory Healthcare |
| Allina Health |
| ACA Acupuncture & Wellness |
| Essentia Health |
| South Baylo University |
| Yinova Center |
| Others |
Value Network & Pricing Analysis
Jiangsu and Zhejiang provinces anchor global needle manufacturing capacity, concentrating supply-side leverage among a handful of NMPA-certified producers who dictate terms to downstream clinic networks across Germany, Australia, and the United States. This geographic clustering amplifies pricing power for sterile filiform needles while electro-acupuncture device manufacturers absorb compliance costs that compress margins in the capital equipment tier.
Pricing Analysis
FDA 21 CFR 880.5580 dictates the pricing tier structure for acupuncture needles, separating premium single-use sterile products from economy-grade alternatives lacking comprehensive documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because smaller clinic networks struggle with vendor qualification burdens. Private hospital integrative medicine departments show the least price sensitivity, while independent community practitioners face acute margin pressure.
Supply Chain Analysis
Extended payment terms from Jiangsu manufacturers to Australian and German distributors have become standard practice, easing working capital constraints for clinic networks scaling inventory. Raw material flows draw from surgical-grade stainless steel suppliers in China, South Korea, and Japan, with electrical components for stimulation devices sourced from Taiwan. Single-source vulnerability concentrates in Jiangsu needle production clusters. Distribution runs through medical device wholesalers serving hospital systems and direct-to-clinic procurement platforms for independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO's ICD-11 traditional medicine inclusion constitutes a regulatory inflection that converts cash-pay wellness into reimbursed medical care, accelerating market disruption across insurance jurisdictions. This structural shift compresses legacy out-of-pocket models while rewarding providers who secure payer contracts.
For Market Incumbents: Pre-empt laser acupuncture substitution by integrating needle-free protocols into existing pain management service lines. Secure backward integration into electro-stimulation device supply through contract manufacturing partnerships with South Korean and Taiwanese producers. Lock in multi-year bulk needle supply contracts with Jiangsu manufacturers before NMPA export licensing tightens.
For New Entrants and Emerging Players: Rural United States markets present the most penetrable white-space opportunity, where telehealth-enabled diagnostic guidance bypasses physical clinic infrastructure requirements. Target employer-sponsored wellness programs in German corporate settings, where supplementary private insurance reduces patient price sensitivity. Pursue community-style delivery with sliding-scale pricing to capture price-sensitive urban volume excluded from premium franchise networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform integrators with established payer relationships over pure-play device manufacturers. Long-term viability hinges on reimbursement strategy execution rather than clinical efficacy differentiation alone. Watch CMS coding expansion velocity as the primary inflection indicator for valuation multiple expansion in the provider services tier.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | CMS coding expansion for low back pain unlocks patient access previously blocked by cash-pay barriers. |
| Telehealth Diagnostic Platform Launch | Remote assessment protocols extend practitioner reach to rural populations and mobility-limited patients. |
| Electro-Stimulation Device Integration | Combination therapies command premium rates in sports medicine and rehabilitation center contracts. |
| Community-Style Delivery Expansion | Sliding-scale models capture price-sensitive volume through high-throughput semi-private treatment rooms. |
| Franchise Protocol Standardization | Uniform treatment frameworks enable rapid replication across standardized regulatory environments in Germany and Australia. |
Research Methodology
Initial hypotheses were tested against primary input from licensed acupuncturists, hospital integrative medicine directors, medical device procurement managers, and private clinic network operators, then refined through secondary validation. Primary fieldwork combined structured interviews with practitioners across the United States, Germany, and Australia alongside GPO contracts analysis and CMS reimbursement database review. Secondary sources encompassed FDA 510(k) filings for needle devices, NMPA export registration records, WHO traditional medicine safety guidelines, and hospital procurement platform data. Bottom-up patient volume estimates triangulated against top-down spending flows from private insurers and national health systems.
Demand-supply balance modeling anchored forecast outputs, with segmentation across product type, application, end user, and delivery mode dimensions. Patient volume projections incorporated chronic pain prevalence trends, physician referral pattern shifts, and telehealth licensure evolution throughout the forecast period. CAGRs were derived from regression analysis of historical reimbursement expansion rates and clinic network formation velocity. Electro-stimulation device adoption curves and community-style clinic throughput metrics provided industry-specific forecast inputs.
Practitioners should monitor NMPA enforcement actions, CMS coverage determination timelines, and laser acupuncture efficacy study publication for early signals of forecast revision triggers. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Liver Transplantation Market
Medical Treatment
Transplantation Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Epiglottitis Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Brain Tumor Treatment Market