
 Knee Reconstruction Devices Market | 2026-2036
Knee Reconstruction Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Knee Reconstruction Devices Market Outlook
Software-defined surgical planning and maintenance contracts is broadening what orthopedic vendors monetize beyond hardware. Zimmer Biomet Holdings, Inc. leverages its robotics platform to lock in recurring revenue from navigation system subscriptions. Stryker Corporation anchors its position through service agreements tied to Mako surgical robot installations. Smith & Nephew plc differentiates by bundling rehabilitation protocols with implant warranties.
Knee reconstruction devices comprise implantable prostheses, precision instruments, and fixation systems engineered from cobalt-chrome alloys, titanium, and ultra-high molecular weight polyethylene to restore joint kinematics after osteoarthritic degeneration or trauma. Implants and surgical instruments command the largest revenue share due to recurring replacement cycles and instrument tray turnover, while robotics and navigation systems represent the fastest-expanding technology segment as hospitals justify capital expenditure through improved alignment accuracy and reduced revision rates. Standard techniques still dominate procedure volume in cost-sensitive settings, though margin pools increasingly shift toward biologics-enhanced fixation and patient-matched instrumentation.
FDA 510(k) pathways and EU MDR conformity requirements govern implant biocompatibility, sterilization validation, and clinical follow-up protocols, directly shaping product development timelines and market access costs. ISO 14155 and ASTM F2083 standards further constrain design verification for tibial tray fatigue resistance and polyethylene wear rates. Stakeholders must monitor how reimbursement shifts toward bundled payment models will reshape capital allocation between robotics infrastructure and conventional implant portfolios.
Market Dynamics
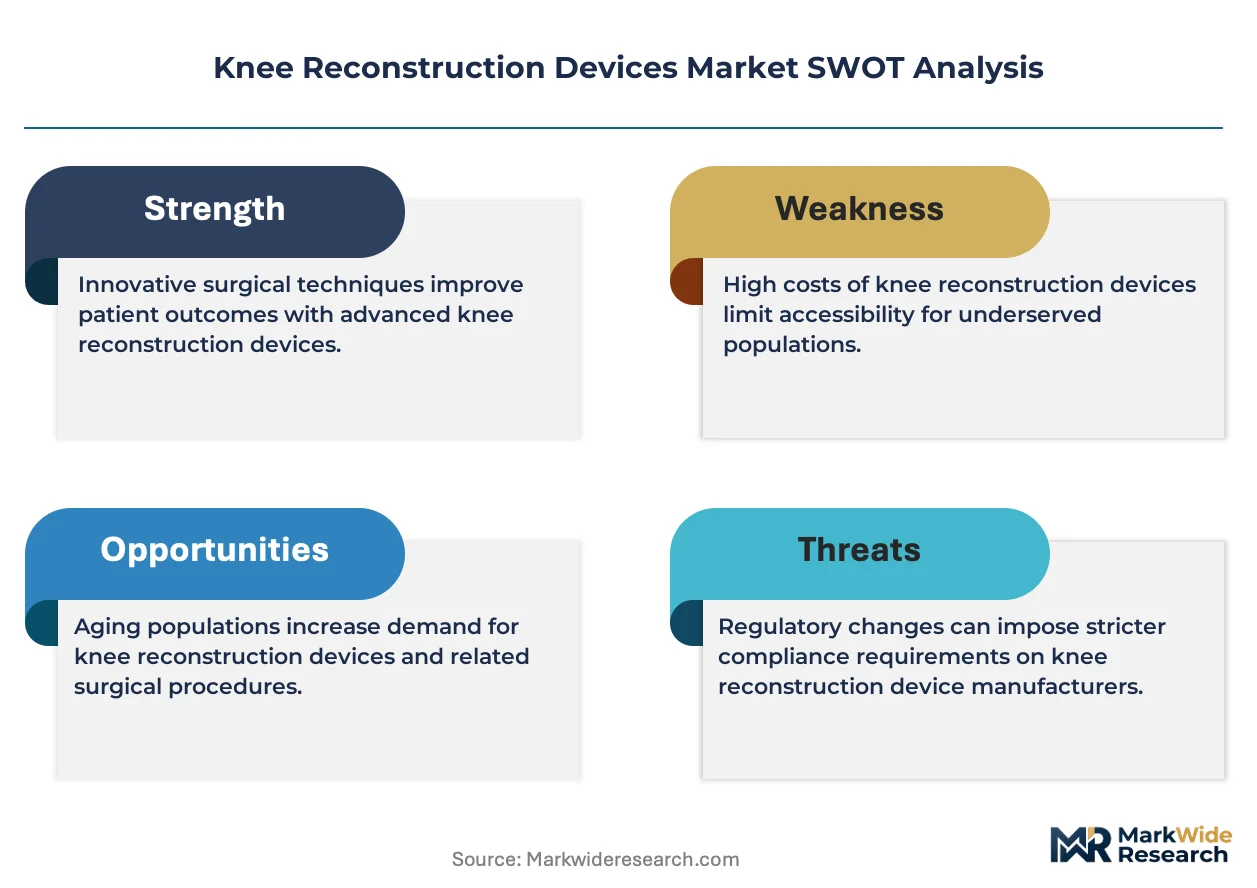
The knee reconstruction market is pivoting around robotics-assisted surgical platforms that demand new capital allocation models from hospitals while compressing revision rates through improved alignment precision.
Growth Catalysts
- Aging Demographics:The United States, Germany, and China are experiencing surgical volume expansion as populations over 65 require primary and revision arthroplasty procedures.
- EU MDR Compliance:Stricter conformity assessment requirements for patient-specific implants are elevating quality benchmarks and accelerating consolidation among qualified manufacturers.
- Robotics Integration:Navigation systems paired with preoperative planning software are capturing hospital capital budgets previously allocated to conventional instrument trays.
Market Restraints
- Cobalt-Chrome Supply Concentration:Foundry capacity for medical-grade alloys clusters in Germany and the United States, exposing OEMs to input cost volatility and extended lead times.
- FDA 510(k) Pathway Friction:Substantial equivalence demonstrations for novel bearing surfaces now require extended wear-testing protocols, stretching product development timelines.
- Conservative Treatment Substitution:Hyaluronic acid injections and biologic cartilage repair are delaying surgical intervention in early-stage osteoarthritis patients.
Strategic Opportunities
- China's Provincial Hospital Tier:Secondary cities in Sichuan and Shandong provinces are building arthroplasty capacity faster than multinational vendors have deployed sales infrastructure.
- Maintenance Contract Bundling:Service agreements covering robotics calibration and software updates represent recurring revenue streams detached from implant sales cycles.
- AI-Assisted Preoperative Planning:Machine learning algorithms analyzing CT datasets are converging with 3D printing workflows to enable same-day patient-matched instrumentation.
Industry Challenges
- Robotics Technician Scarcity:Hospital biomedical engineering departments lack personnel trained on Mako and ROSA platform troubleshooting, forcing vendor dependency for routine maintenance.
- Legacy Tray Integration:Ambulatory surgery centers face capital inefficiency when robotics workflows require parallel maintenance of conventional instrument sets for non-robotic cases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knee Reconstruction Devices Market |
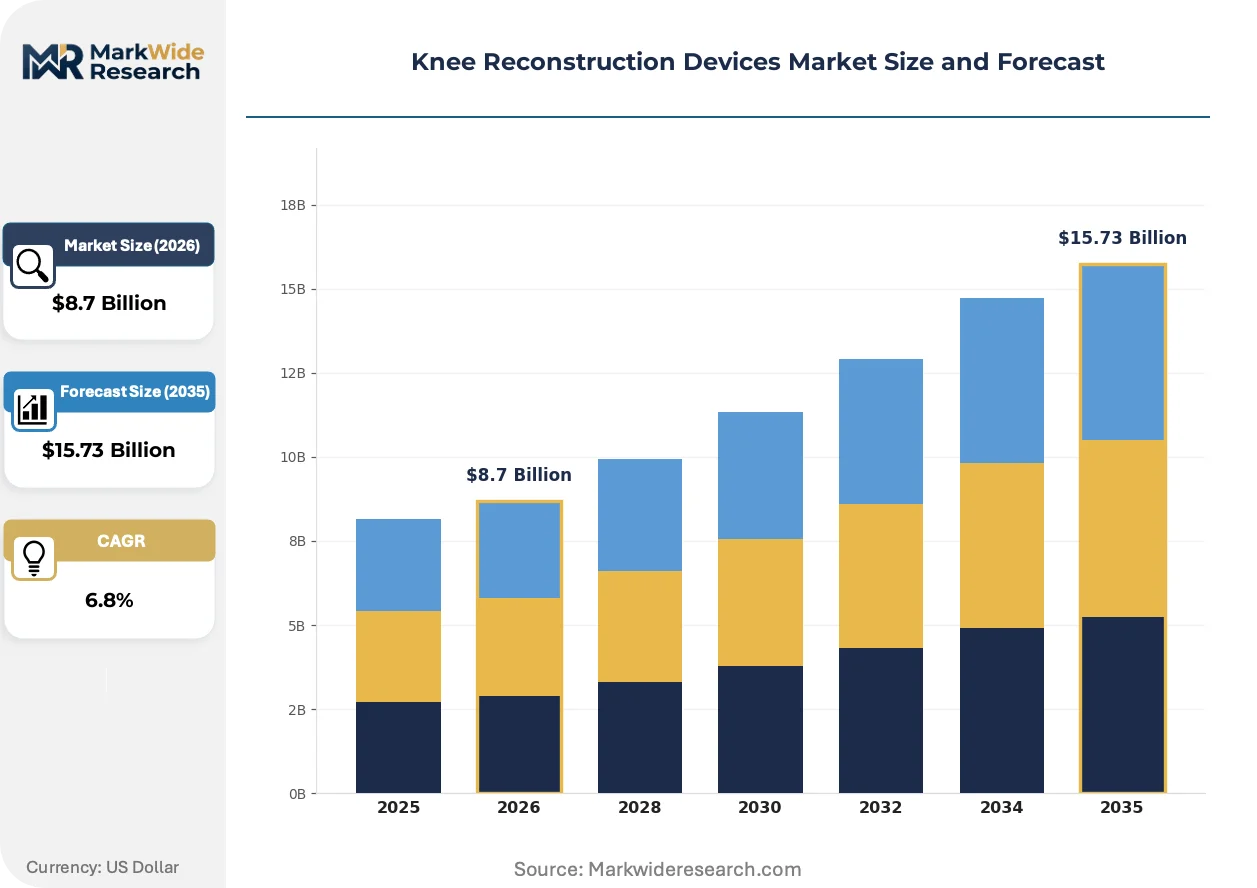
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Surgical Instruments, Bone Fixation Devices, Rehabilitation Devices Technology: Robotics, Navigation Systems, Biologics, Standard Techniques End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Rehabilitation Centers Application: Partial Replacement, Total Replacement, Revision Surgery, Sports Injuries |
| Companies Covered | Smith & Nephew plc, Exactech, Inc., Zimmer Biomet Holdings, Inc., MicroPort Scientific Corporation, Corin Group Limited, DePuy Synthes, Inc., B. Braun Melsungen AG, ConforMIS, Inc., Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knee Reconstruction Devices Market Strategic Shifts
Orthopedic vendors are engineering new monetization architectures around software-enabled surgical ecosystems rather than discrete hardware transactions. Three developments are restructuring competitive position.
Patient-matched instrumentation is absorbing capital previously directed to standard reusable trays. Large academic medical centers in the United States are converting to disposable, 3D-printed cutting guides that eliminate sterilization logistics. The shift is compressing instrument inventory carrying costs while locking hospitals into proprietary planning software subscriptions.
EMA's tightened scrutiny of biocompatibility documentation under EU MDR is forcing redesign cycles for polyethylene tibial inserts. Manufacturers must now submit extended clinical follow-up data for novel cross-linked formulations. European notified bodies are prioritizing review resources toward established OEMs with dedicated regulatory affairs teams, disadvantaging mid-tier competitors.
After-sales service unbundling is disrupting traditional distributor relationships in Germany. Hospital procurement departments are negotiating direct maintenance contracts with robotics manufacturers, bypassing regional orthopedic distributors that historically captured service margins. The disintermediation is most pronounced in Bavaria and North Rhine-Westphalia, where hospital chains have centralized purchasing authority.
Knee Reconstruction Devices Market Segmentation
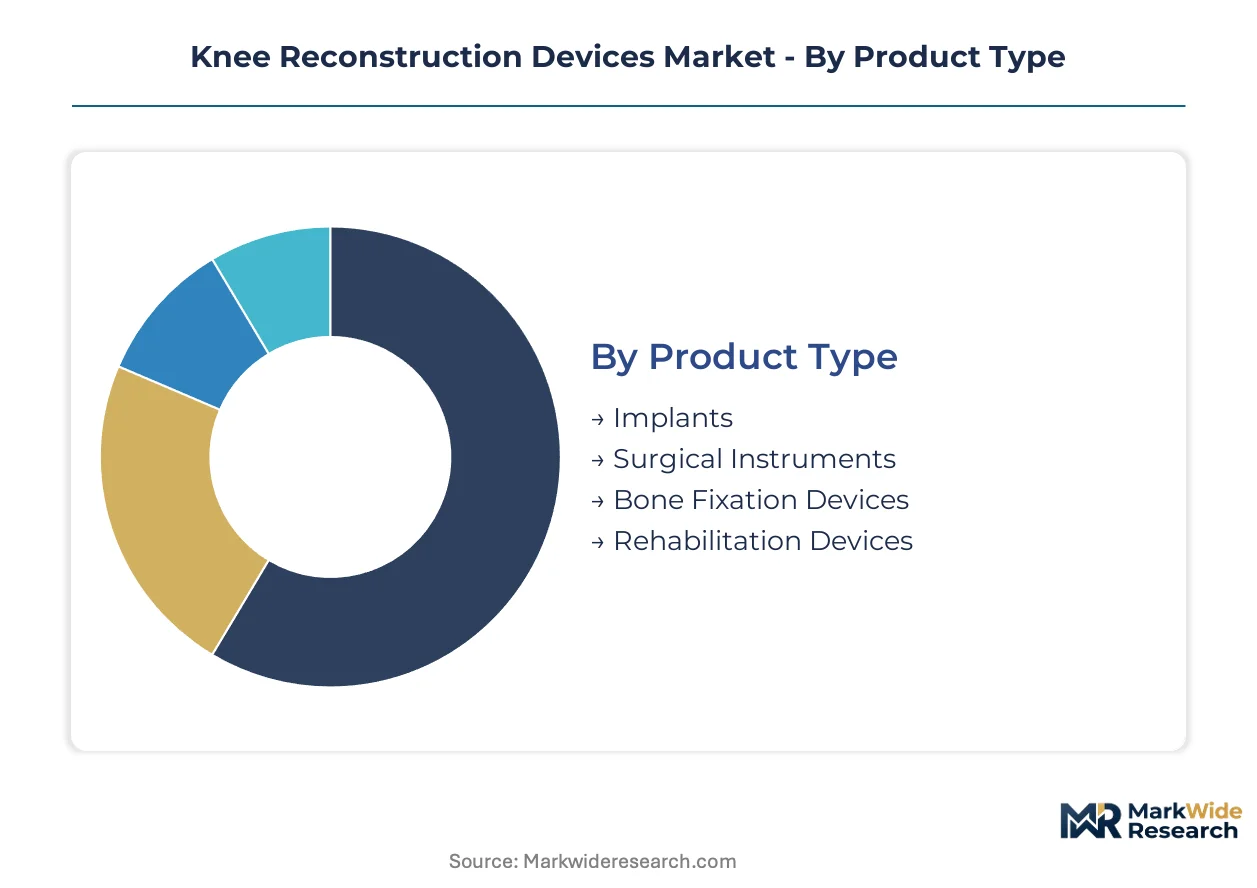
Segmentation in knee reconstruction reveals how capital flows diverge between hardware commoditization and software-enabled premium tiers. Product architecture, surgical technology, care setting, and procedure type each reshape margin structures and vendor competitive moats.
Product Type:
Material composition and regulatory classification determine replacement cycles and pricing power across implantable hardware.
- Implants:Cobalt-chrome and titanium femoral components paired with ultra-high molecular weight polyethylene tibial inserts constitute the revenue foundation. Demand concentrates in academic medical centers in the United States and Germany where revision burden justifies premium bearing surfaces.
- Surgical Instruments:Reusable stainless steel trays and disposable patient-matched cutting guides compete for hospital capital allocation. Ambulatory surgery centers in Texas and Bavaria are converting to single-use instrumentation to eliminate sterilization bottlenecks.
- Bone Fixation Devices:Interference screws and suture anchors manufactured from PEEK and bioabsorbable polymers secure graft fixation in ligament reconstruction.
- Rehabilitation Devices:Continuous passive motion machines and cryotherapy systems extend vendor touchpoints into post-acute recovery.
Mature deployment sits with Implants. Newer deployment is concentrated in Surgical Instruments.
Technology:
Capital intensity and clinical outcome differentiation separate subscription-based platforms from conventional hardware.
- Robotics:Mako and ROSA platforms demand seven-figure hospital investments with recurring software and maintenance contracts. United States hospital systems in Florida and Michigan are consolidating purchasing decisions at the IDN level to negotiate volume-based service agreements.
- Navigation Systems:Optical and electromagnetic tracking enables real-time instrument positioning without the capital burden of robotic arms. German hospitals in North Rhine-Westphalia are prioritizing navigation add-ons to existing instrument trays.
- Biologics:Platelet-rich plasma and mesenchymal stem cell adjuncts command out-of-pocket payment in cash-pay orthopedic clinics.
- Standard Techniques:Mechanical alignment guides and manual instrumentation retain dominance in cost-constrained settings.
Standard Techniques retain volume leadership. Robotics is gaining share fastest.
End User:
Reimbursement structure and case complexity dictate technology adoption thresholds across care settings.
- Hospitals:Inpatient facilities with 24-hour nursing coverage manage high-complexity revision cases and comorbid patient populations. China's provincial tertiary hospitals in Sichuan are building dedicated arthroplasty wards faster than vendor sales coverage can penetrate.
- Ambulatory Surgery Centers:Freestanding facilities optimized for rapid discharge capture primary knee replacement volume shifting from inpatient settings. United States ASCs in Arizona and Florida are investing in robotics to qualify for bundled payment contracts.
- Orthopedic Clinics:Physician-owned practices concentrate on diagnosis and conservative management before surgical referral.
- Rehabilitation Centers:Post-acute facilities manage functional recovery and prosthetic training.
Hospitals anchor procedure volume. Ambulatory Surgery Centers are expanding most quickly.
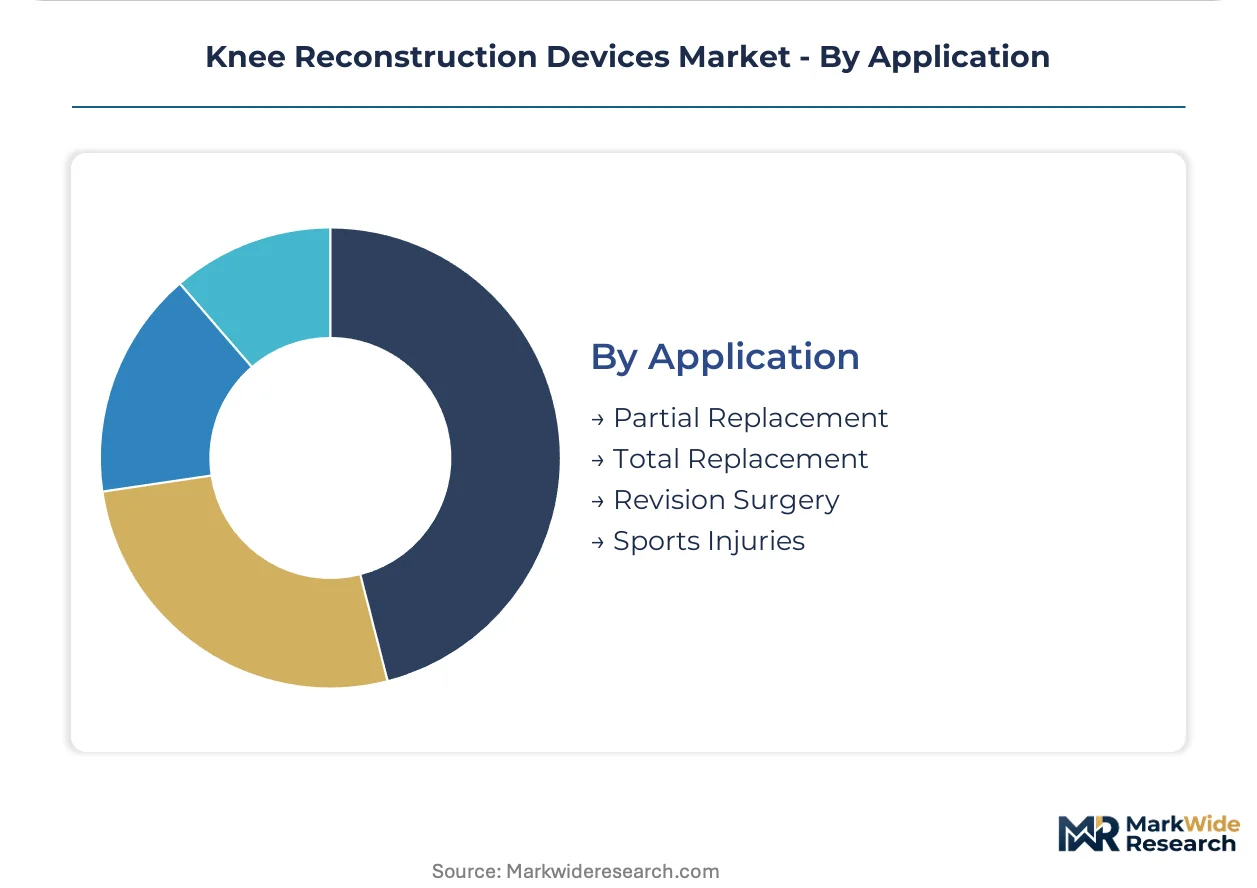
Application:
Procedure invasiveness and patient age profile determine implant longevity requirements and revision risk.
- Total Replacement:Full femoral and tibial resurfacing with patellar component optional represents the procedural standard. Germany's statutory health insurance system is tightening indication criteria to reserve total replacement for end-stage degeneration.
- Revision Surgery:Component exchange and bone loss management with augments and cones command premium pricing. United States academic centers in Boston and Philadelphia are developing specialized revision fellowship programs.
- Partial Replacement:Unicompartmental arthroplasty preserves cruciate ligaments and bone stock in younger patients.
- Sports Injuries:Ligament reconstruction and meniscal repair address traumatic damage in active populations.
Total Replacement dominates surgical volume. Revision Surgery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of medical-grade cobalt-chrome alloys concentrates in German and United States foundries, while surgical volume expansion tilts toward aging populations in China and Germany. This production-consumption divide shapes procurement strategies and regulatory compliance investments across major markets.
United States
Hospital systems in Florida and Michigan consolidate robotics purchasing at the integrated delivery network level to negotiate volume-based service agreements. FDA 510(k) pathways for novel bearing surfaces now demand extended wear-testing protocols that stretch product development timelines. Academic medical centers in Boston and Philadelphia anchor revision surgery specialization through dedicated fellowship programs.
Germany
Statutory health insurance tightening of total knee replacement indication criteria reserves procedures for end-stage degeneration cases. EU MDR conformity assessment elevates quality benchmarks for patient-specific implants and accelerates manufacturer consolidation. Hospital chains in Bavaria and North Rhine-Westphalia centralize procurement authority to negotiate direct robotics maintenance contracts.
China
Provincial tertiary hospitals in Sichuan and Shandong provinces build dedicated arthroplasty wards faster than multinational vendor sales coverage penetrates. NMPA clearance pathways for imported implants require extended clinical trial data from domestic patient populations. Secondary cities absorb capital investment in navigation systems as primary replacement volume shifts from tier-one municipalities.
Japan
Aging demographics drive surgical volume expansion in Kanto and Kansai regions where patients over 75 require complex revision procedures. PMDA review timelines for cross-linked polyethylene formulations extend product registration cycles beyond European equivalents. Metropolitan Tokyo hospitals prioritize navigation add-ons to existing instrument trays rather than full robotics platforms.
United Kingdom
NHS bundled payment models reshape capital allocation between robotics infrastructure and conventional implant portfolios across London and Southeast hospital trusts. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance obligations for manufacturers. Midlands-based procurement consortia negotiate multi-hospital maintenance contracts for surgical navigation systems.
Knee Reconstruction Devices Market Competitive Environment
Top-tier vendors anchor premium robotics and navigation platforms, while mid-tier specialists occupy patient-matched instrumentation and biologics adjacencies. The vendor base stratifies across three archetypes: diversified orthopedic conglomerates with robotics ecosystems, pure-play implant manufacturers with regulatory scale, and emerging specialists in 3D-printed instrumentation. Consolidation accelerates through strategic partnerships for software-defined surgical planning and direct hospital service contracting that bypasses traditional distribution.
Among diversified orthopedic conglomerates, Zimmer Biomet Holdings, Inc., Stryker Corporation, and Smith & Nephew plc exemplify contrasting platform strategies. Zimmer Biomet leverages robotics infrastructure to secure recurring navigation subscriptions. Stryker anchors market position through service agreements tied to capital equipment installations. Smith & Nephew differentiates through bundled rehabilitation protocols that extend vendor relationships into post-acute recovery phases.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Exactech, Inc. |
| Zimmer Biomet Holdings, Inc. |
| MicroPort Scientific Corporation |
| Corin Group Limited |
| DePuy Synthes, Inc. |
| B. Braun Melsungen AG |
| ConforMIS, Inc. |
| Stryker Corporation |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States and hospital chains in Germany concentrate purchasing power, forcing tiered pricing negotiations that separate premium robotics platforms from standard implant portfolios through service bundling rather than hardware differentiation alone.
Pricing Analysis
Margin tightening in standard implant tiers reflects EU MDR compliance cost absorption and cobalt-chrome alloy volatility. Three-tier pricing structure across premium robotics, standard navigation, and economy manual instrumentation dominates procurement negotiations. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service bundling. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers prioritize alignment accuracy over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and United States foundries supplying medical-grade cobalt-chrome alloys. Raw material dependencies center on titanium sponge from Japan, polyethylene resin from Belgium, and precision ceramics from Germany. Tariff exposure on Chinese-sourced surgical instrument blanks threatens cost structures. Distribution runs through regional orthopedic distributors in North America and direct hospital contracting in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU MDR conformity assessment requirements create a barrier-to-entry moat that favors established OEMs with dedicated regulatory affairs infrastructure over mid-tier competitors.
For Market Incumbents: Extend robotics platform penetration through multi-year service agreements that lock hospital systems into proprietary software ecosystems. Deepen backward integration into cobalt-chrome foundry partnerships to secure alloy supply against German capacity constraints. Prioritize EU MDR technical documentation investment to accelerate patient-specific implant clearance timelines ahead of mid-tier rivals. For New Entrants and Emerging Players: Capture white-space opportunity in China's Sichuan and Shandong provincial hospitals where arthroplasty capacity expansion outpaces multinational sales coverage. Target ambulatory surgery centers seeking disposable patient-matched instrumentation to eliminate sterilization logistics. Pursue direct-to-hospital 3D-printed cutting guide contracts bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier implant manufacturers with EU MDR technical files already submitted in Germany and the United Kingdom. Long-term viability hinges on software-enabled recurring revenue attachment rates rather than hardware transaction volume. Monitor FDA 510(k) clearance velocity for novel cross-linked polyethylene formulations as inflection indicator for revision surgery market positioning.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates patient-specific implant market access ahead of mid-tier competitors facing notified body backlog. |
| Robotics Service Agreement Expansion | Locks United States hospital systems into recurring software subscription revenue detached from implant sales cycles. |
| Disposable Instrumentation Manufacturing Scale-Up | Captures ambulatory surgery center demand for sterilization-free patient-matched cutting guides in Texas and Bavaria. |
| Hospital System Direct Contracting | Bypasses regional orthopedic distributors in Germany's Bavaria and North Rhine-Westphalia to capture service margins. |
| AI-Assisted Preoperative Planning Development | Converges machine learning CT analysis with 3D printing workflows for same-day patient-matched instrumentation delivery. |
Study Parameters
Independent corroboration across orthopedic surgeons, hospital purchasing committee members, biomedical engineering directors, and GPO contracts managers underwrites the qualitative findings. Primary interviews with robotics platform technicians and regulatory affairs specialists at major OEMs combined with secondary validation from FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up implant volume estimates triangulate against top-down capital expenditure tracking across United States integrated delivery networks.
Rate-of-change decomposition across the analysis window segments expansion by product architecture, surgical technology, care setting, and procedure type. Modeled dimensions include robotics adoption velocity, navigation system attach rates, and patient-matched instrumentation conversion curves. CAGRs derive from surgical volume projections calibrated to demographic aging trajectories in the United States, Germany, and China. Forecast inputs incorporate EU MDR clearance timeline assumptions and cobalt-chrome alloy supply elasticity.
The model holds under stable regulatory enforcement intensity and reimbursement parity between robotic and conventional techniques; deviation in bundled payment model adoption or FDA 510(k) pathway restructuring would shift capital allocation assumptions. Forecasts reflect documented assumptions regarding surgical volume elasticity and technology substitution thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Laser BPH Devices Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Spinal Traction Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Airway Management Market
Medical Devices
Chile Ultrasound Devices Market
Medical Devices
Auto Keratometer Market
Medical Devices
North America Surgical Microscopes Market
Medical Devices
Capsular Tension Rings Market