
 Malaria Treatment Market | 2026-2036
Malaria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Malaria Treatment Market Outlook
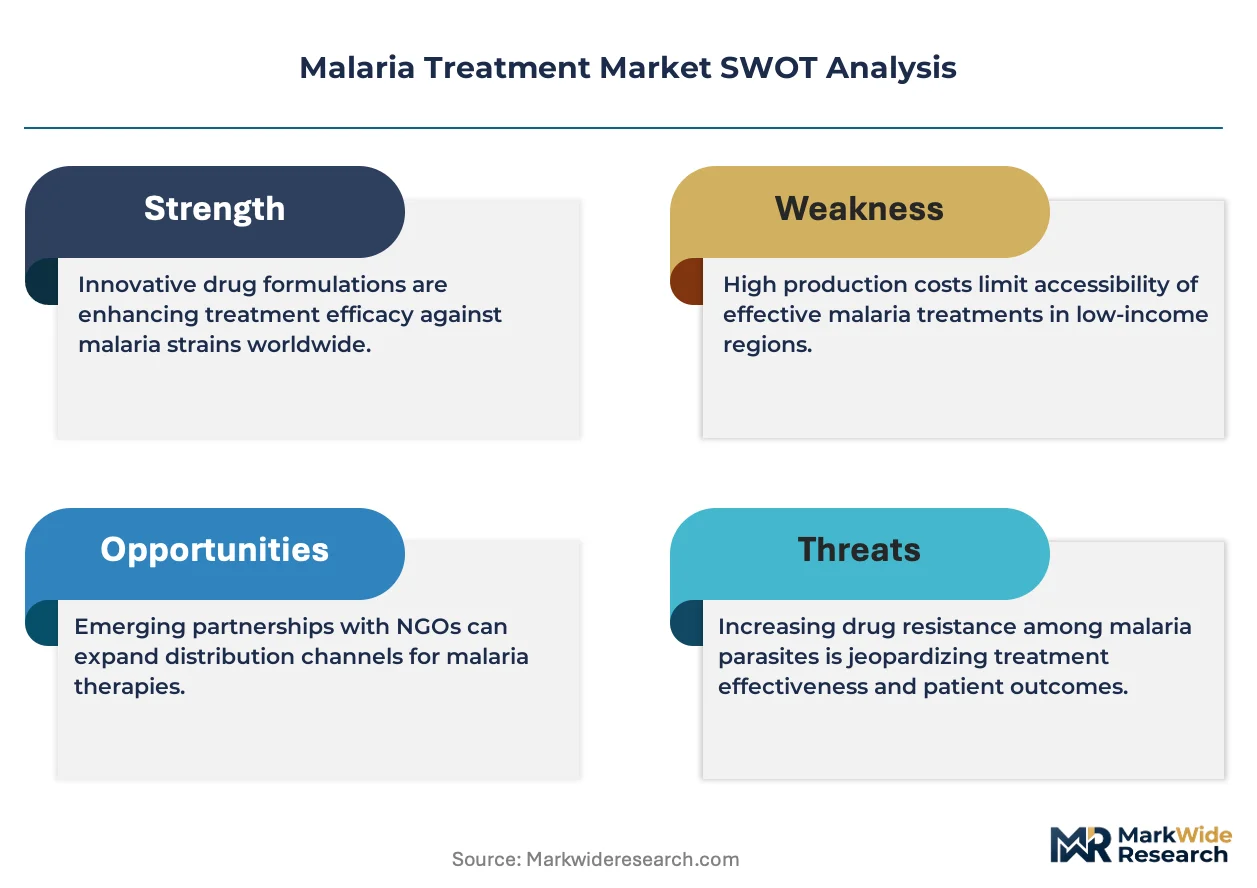
Sub-Saharan Africa is rewriting malaria treatment access dynamics through expanded ACT manufacturing partnerships. Novartis AG leverages its long-standing artemisinin supply agreements to sustain distribution reach across endemic zones. Cipla Inc. anchors generic ACT production with cost-optimized formulations for public tenders. Sanofi competes through vertically controlled artemisinin sourcing from cultivated rather than extracted raw material.
Malaria treatment encompasses pharmaceutical interventions targeting Plasmodium parasite clearance, with artemisinin-based combination therapy requiring precise co-formulation ratios to prevent resistance development. The primary purpose centers on rapid parasitemia reduction and transmission interruption in endemic populations. Artemisinin-Based Combination Therapy dominates value pools due to WHO first-line recommendation status, while oral administration routes capture the largest volume share across community health programs. Hospital Pharmacies concentrate critical intravenous quinine access for severe malaria cases, whereas NGO channels extend ACT reach into remote distribution networks.
WHO prequalification standards, FDA import requirements, and national malaria control program formularies collectively shape product registration pathways and procurement eligibility. EMA guidelines on fixed-dose combination stability testing further constrain manufacturer compliance scope for European export markets. Stakeholders must monitor artemisinin resistance surveillance data and corresponding treatment policy shifts to align pipeline investments with evolving protocol requirements.
Market Dynamics
Artemisinin resistance surveillance data from the WHO is forcing treatment protocol revisions across endemic zones, redirecting procurement toward next-generation combination therapies and reshaping manufacturer R&D priorities.
Growth Catalysts
- ACT procurement scale-up:Nigeria's National Malaria Elimination Programme expanded distributor networks to 36 states, doubling last-mile access points for community health workers.
- WHO prequalification pathways:Streamlined assessment frameworks for fixed-dose combinations accelerate manufacturer entry into Global Fund tender pools.
- Seasonal malaria chemoprevention:Sahel region pilot programs in Burkina Faso and Mali extend preventive treatment to 30 million children annually.
Market Restraints
- Artemisinin supply concentration:Cultivation of Artemisia annua concentrates in Vietnam and China, exposing formulation capacity to climatic yield volatility.
- Resistance surveillance costs:National malaria control programs in the Democratic Republic of Congo and Uganda divert operational budgets to molecular marker tracking infrastructure.
- Quinine displacement limits:Intravenous artesunate protocols for severe malaria cases reduce hospital pharmacy quinine volumes, compressing legacy product margins.
Strategic Opportunities
- Single-dose radical cure regimens:Tafenoquine and primaquine co-formulations for Plasmodium vivax elimination target Brazil and Southeast Asia relapse reservoirs.
- Sub-Saharan manufacturing localization:Rwanda and Ghana pharmaceutical parks offer tariff incentives for artemisinin extraction and tablet production.
- NGO-direct distribution channels:Médecins Sans Frontières and Clinton Health Access Initiative procurement bypasses fragmented wholesale layers in South Sudan and Chad.
Industry Challenges
- Stability testing protocols:EMA guidelines for fixed-dose combination shelf-life validation extend registration timelines by 18-24 months for European export markets.
- Pharmacovigilance infrastructure:Post-market adverse event reporting systems remain underdeveloped across francophone West Africa, complicating safety signal detection.
- Co-formulation chemistry expertise:Precise artemisinin derivative-to-partner drug ratio engineering requires specialized formulation scientists in short supply across generic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaria Treatment Market |
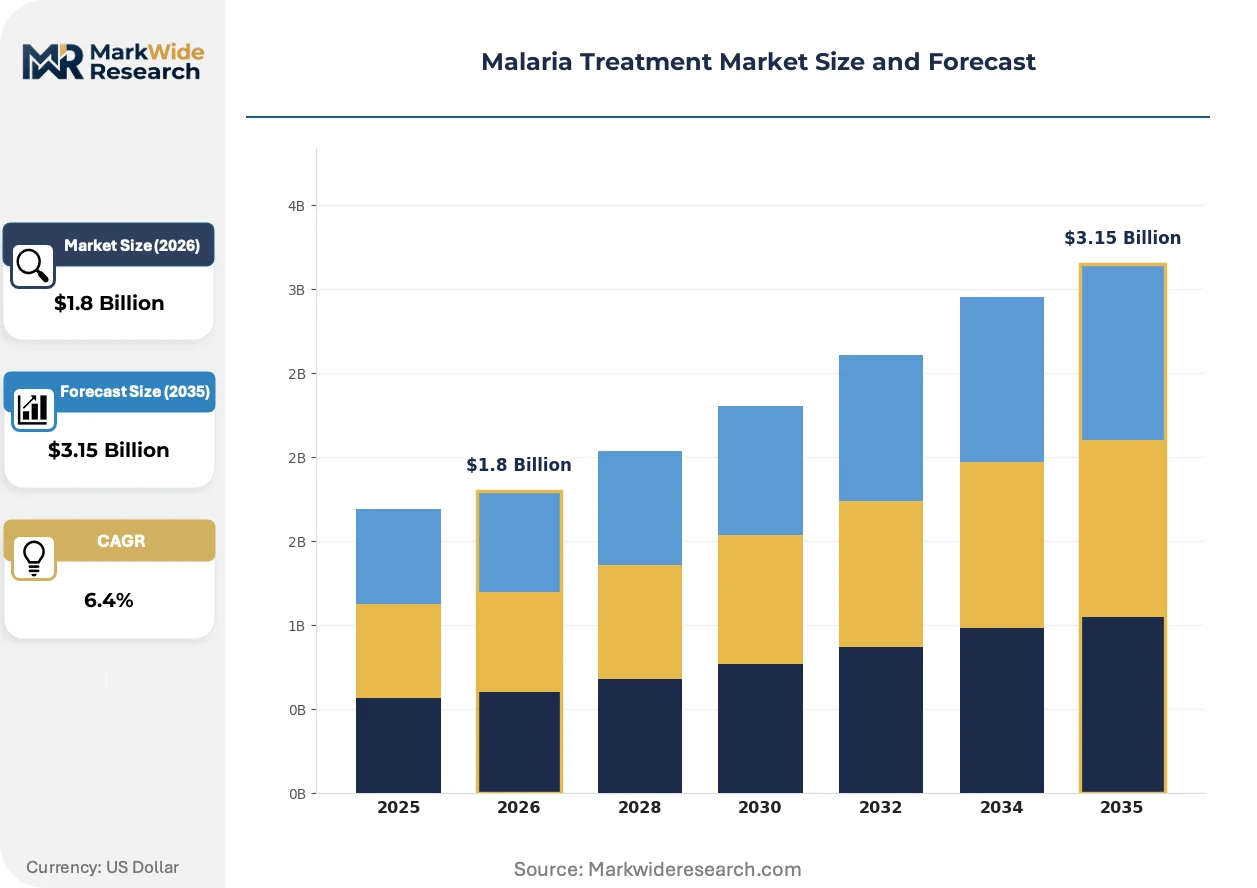
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artemisinin-Based Combination Therapy, Quinine, Mefloquine, Chloroquine Administration Route: Oral, Intravenous, Intramuscular, Rectal Patient Type: Children, Adults, Pregnant Women, Elderly Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, NGOs |
| Companies Covered | Novartis AG, Sanofi, Cipla Inc., Sun Pharmaceutical Industries Ltd., GSK Plc, Pfizer Inc., Ipca Laboratories Ltd, Lupin Ltd, Hikma Pharmaceuticals PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaria Treatment Market Strategic Shifts
Digital surveillance platforms and resistance tracking networks are compressing the feedback loop between field efficacy data and treatment policy revision, accelerating product lifecycle turnover for ACT manufacturers.
Blockchain-based supply chain verification is digitizing artemisinin provenance documentation from farm to formulation facility. Novartis and Cipla procurement teams pilot distributed ledger systems to authenticate cultivated versus extracted raw material sources. This transparency infrastructure is digitizing compliance documentation for WHO prequalification audits and reducing counterfeit product infiltration.
FDA import alert protocols for substandard antimalarial detection have intensified analytical testing requirements at US entry points. Third-party certification laboratories in India and China now perform pre-shipment dissolution profiling to preempt detention. Generic manufacturers serving PEPFAR and PMI programs absorb incremental QC costs to maintain tender eligibility.
Community health worker deployment models are displacing clinic-centric distribution for uncomplicated malaria cases. Rwanda and Ethiopia train 50,000 village-level distributors to administer rapid diagnostic tests and dispense ACT courses. This task-shifting is most visible in high-transmission rural districts where facility density falls below one per 10,000 population.
Malaria Treatment Market Segmentation
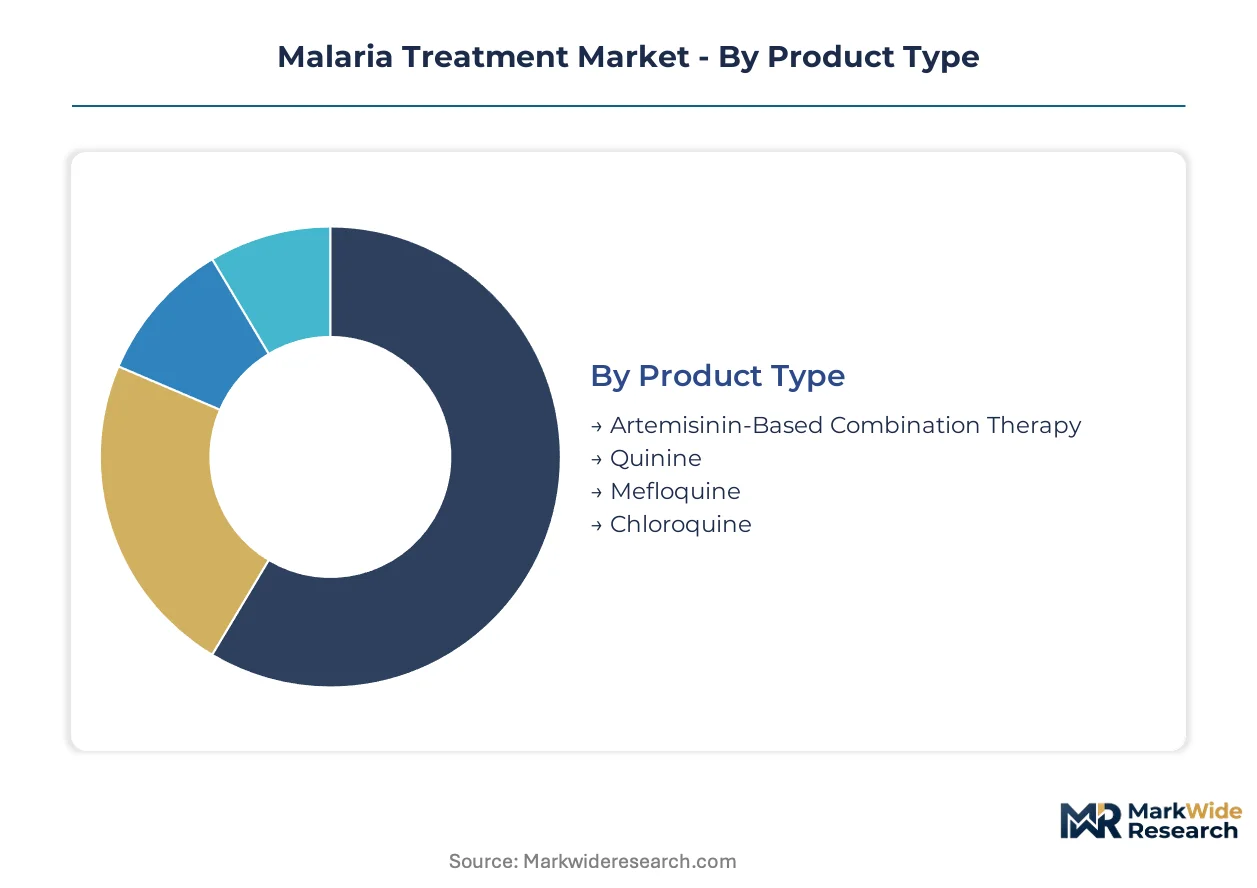
Segmentation in malaria treatment determines procurement pathways, pricing tiers, and distribution infrastructure investments. Manufacturers align formulation capabilities to specific patient populations and delivery contexts rather than pursuing universal product strategies.
Product Type:
After-sales service intensity varies sharply across product categories, with ACT requiring resistance surveillance partnerships and quinine demanding hospital-based adverse event monitoring infrastructure.
- Artemisinin-Based Combination Therapy:Fixed-dose co-formulations pair artemisinin derivatives with longer-acting partner drugs to prevent resistance emergence. Nigeria's National Malaria Elimination Programme and Uganda's Ministry of Health anchor procurement volumes for first-line uncomplicated malaria protocols.
- Quinine:Intravenous and oral alkaloid formulations serve severe malaria cases and first-trimester pregnancy contraindications where ACT is restricted. Hospital pharmacy networks in the Democratic Republic of Congo maintain cold-chain storage for parenteral quinine despite declining protocol preference.
- Mefloquine:Single-agent prophylaxis for travelers and military personnel with documented neuropsychiatric tolerability profiles.
- Chloroquine:Resurgent use in Central American and Caribbean zones where Plasmodium vivax remains sensitive; limited African applicability due to widespread falciparum resistance.
By volume, Artemisinin-Based Combination Therapy leads. By growth pace, Quinine is contracting as intravenous artesunate protocols expand.
Administration Route:
Cost tier stratification separates community-dispensed oral tablets from facility-based parenteral delivery requiring trained clinical staff.
- Oral:Tablet and dispersible formulations dominate community health worker deployment. Rwanda's 50,000 village-level distributors rely exclusively on oral ACT for uncomplicated case management in sub-facility settings.
- Intravenous:Hospital-confined delivery for severe malaria with cerebral complications or hemodynamic instability. Burkinabe and Malian referral hospitals concentrate IV artesunate capacity as quinine displacement accelerates.
- Intramuscular:Pre-referral stabilization dosing where IV access is delayed; community health worker scope limitations restrict deployment.
- Rectal:Artesunate suppositories for pre-referral severe malaria in remote districts; Médecins Sans Frontières programs in South Sudan and Chad utilize this route where injection safety is compromised.
By volume, Oral administration leads. By growth pace, Intravenous is gaining share fastest as severe malaria protocol upgrades penetrate district hospitals.
Patient Type:
Application context drives formulation differentiation—weight-banded dosing for pediatric populations and teratogenicity screening for reproductive-age women.
- Children:Dispersible tablet formulations with weight-calibrated dosing for under-five populations bearing disproportionate malaria mortality. Seasonal malaria chemoprevention campaigns in Burkina Faso and Mali target 30 million children annually with preventive drug courses.
- Adults:Standard fixed-dose combinations for working-age populations with highest transmission exposure in agricultural and mining occupational settings.
- Pregnant Women:First-trimester quinine restriction and intermittent preventive treatment protocols requiring sulfadoxine-pyrimethamine integration. WHO guidelines constrain ACT selection by gestational age.
- Elderly:Comorbidity-adjusted dosing for diabetes and cardiovascular medication interactions; limited dedicated formulation development.
By volume, Children leads. By growth pace, Pregnant Women is expanding most quickly as maternal health integration intensifies across sub-Saharan antenatal care platforms.
Distribution Channel:
Customer type concentration separates institutional procurement from retail fragmentation and direct NGO deployment.
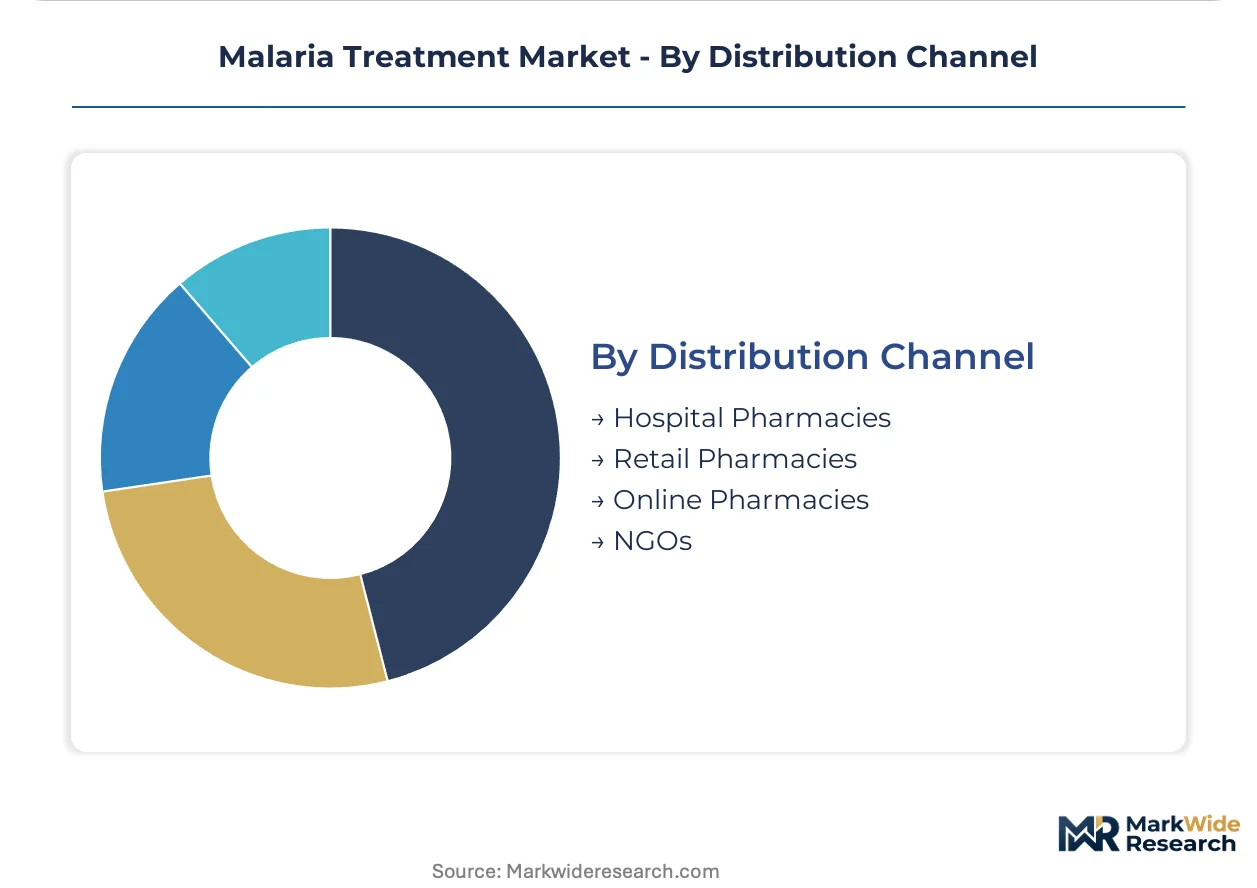
- Hospital Pharmacies:Critical stockholding for severe malaria parenterals and inpatient ACT courses. Nigerian federal teaching hospitals and Ugandan regional referral facilities anchor procurement for complicated case protocols.
- Retail Pharmacies:Urban and peri-urban access points for self-treating febrile patients; counterfeit infiltration risks necessitate stringent WHO prequalification verification.
- Online Pharmacies:Emerging urban channels with limited rural penetration; regulatory oversight gaps in francophone West Africa complicate authenticity assurance.
- NGOs:Médecins Sans Frontières and Clinton Health Access Initiative direct distribution bypasses wholesale fragmentation in South Sudan, Chad, and conflict-affected Congolese provinces.
By volume, Hospital Pharmacies leads. By growth pace, NGOs are climbing the fastest as emergency response and last-mile access programs expand donor funding allocations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Mombasa's container throughput underwrites East African ACT distribution networks, connecting landlocked procurement markets to Indian Ocean shipping lanes. This maritime gateway channels formulation supplies to interior health programs across the Great Lakes region.
Nigeria
Nigeria's National Malaria Elimination Programme drives distributor network expansion across 36 states, doubling last-mile access points for community health workers. The country's national pharmaceutical regulator enforces stringent import documentation for antimalarial shipments. Lagos anchors commercial procurement coordination, with Kano and Port Harcourt serving as northern and southern distribution hubs respectively.
Democratic Republic of Congo
Kinshasa's urban health facilities and eastern mining corridor settlements generate concentrated demand for severe malaria parenterals. National malaria control programs divert operational budgets to molecular marker tracking infrastructure. The copperbelt cities of Lubumbashi and Kolwezi concentrate hospital pharmacy networks for complicated case management.
Uganda
Kampala's referral hospitals and surrounding agricultural districts sustain high-volume ACT consumption for uncomplicated malaria protocols. The Ministry of Health anchors procurement volumes for first-line treatment guidelines. The northern Gulu corridor and western Mbarara cluster concentrate NGO distribution networks extending into South Sudan border zones.
Burkina Faso
Sahel region seasonal malaria chemoprevention campaigns target 30 million children annually across the country's central and eastern provinces. The national malaria control program integrates preventive drug courses with routine immunization platforms. Ouagadougou coordinates regional supply chains reaching into neighboring Mali and Niger.
India
Mumbai and Hyderabad pharmaceutical manufacturing clusters supply generic ACT formulations to Global Fund tender pools. CDSCO regulatory clearances enable export prequalification for WHO assessment pathways. Gujarat's active pharmaceutical ingredient belt feeds artemisinin derivative production for downstream tablet formulation.
Malaria Treatment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in raw material cultivation and extraction. The malaria treatment sector consolidates around vertically integrated pharmaceutical conglomerates with captive artemisinin supply agreements. Three archetypes dominate: multinational originators with cultivated sourcing networks, Indian generic manufacturers with cost-optimized tender strategies, and regional formulation specialists serving national procurement programs. Competitive moves center on backward integration into Artemisia annua cultivation and strategic partnerships with national malaria control programs for direct distribution access.
Among Swiss-origin pharmaceutical conglomerates, Novartis AG occupies a position exemplifying long-standing artemisinin supply chain anchoring across endemic zones. Sanofi represents the vertically controlled cultivation model with proprietary farm-to-formulation infrastructure. Within Indian generic manufacturing, Cipla Inc. anchors cost-optimized production archetypes for public tender participation, while Sun Pharmaceutical Industries Ltd. sits within the scale-driven formulation tier serving multi-country procurement contracts.
| Leading Market Players |
|---|
| Novartis AG |
| Sanofi |
| Cipla Inc. |
| Sun Pharmaceutical Industries Ltd. |
| GSK Plc |
| Pfizer Inc. |
| Ipca Laboratories Ltd |
| Lupin Ltd |
| Hikma Pharmaceuticals PLC |
| Others |
Value Chain & Pricing Dynamics
Gujarat's active pharmaceutical ingredient belt concentrates artemisinin derivative production capacity, tethering downstream tablet formulation pricing to upstream cultivation yields and extraction efficiency across Indian manufacturing clusters.
Pricing Analysis
Volume-discount tiering structures separate Global Fund tender pools from retail pharmacy markups, with WHO prequalification status commanding premium positioning over non-certified alternatives. Price differentiation hinges on regulatory certification tier and geographic delivery cost to landlocked African markets. Cost compression in generic ACT segments is intensifying because Indian manufacturers absorb incremental QC costs to maintain PEPFAR eligibility. Public procurement programs demonstrate highest price sensitivity, while hospital pharmacy networks for severe malaria parenterals show lowest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration rests with Mumbai and Hyderabad pharmaceutical clusters serving WHO prequalification pathways. Raw material dependencies draw from Vietnamese and Chinese Artemisia annua cultivation, Indian artemisinin extraction expertise, and East African formulation finishing capacity. Single-source vulnerability in cultivated artemisinin supply exposes procurement budgets to climatic yield volatility. Distribution runs through Mombasa maritime gateways connecting Indian Ocean shipping to Great Lakes region landlocked markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where WHO prequalification pathways and national malaria control program formularies create high switching costs for incumbent suppliers.
For Market Incumbents: Build regulatory moats through accelerated EMA stability testing investments and captive artemisinin sourcing agreements. Secure national malaria control program direct distribution partnerships to preempt NGO channel displacement. Counter emerging Indian generic manufacturer scale threats by anchoring cultivated rather than extracted raw material supply.
For New Entrants and Emerging Players: Build out sub-Saharan manufacturing localization in Rwanda and Ghana pharmaceutical parks to capture tariff incentives and bypass import documentation friction. Target seasonal malaria chemoprevention preventive drug courses as the most penetrable segment. Lead with NGO-direct distribution channel relationships to circumvent fragmented wholesale layers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with backward integration into Artemisia annua cultivation and proprietary farm-to-formulation infrastructure. Long-term viability over the next decade rests on resistance surveillance data integration capabilities and corresponding treatment policy pivot speed. Monitor artemisinin resistance molecular marker tracking infrastructure deployment as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivated Artemisinin | Sanofi's proprietary farm-to-formulation infrastructure reduces yield volatility exposure from Vietnamese and Chinese extraction. |
| WHO Prequalification Pathway Investment | Streamlined assessment frameworks for fixed-dose combinations accelerate manufacturer entry into Global Fund tender pools. |
| Sub-Saharan Manufacturing Localization | Rwanda and Ghana pharmaceutical parks offer tariff incentives for artemisinin extraction and tablet production. |
| NGO-Direct Distribution Channel Partnership | Médecins Sans Frontières and Clinton Health Access Initiative procurement bypasses fragmented wholesale layers in South Sudan. |
| Digital Supply Chain Verification Deployment | Novartis and Cipla pilot blockchain-based provenance documentation to authenticate cultivated versus extracted raw material. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across this study, combining primary interviews with regulatory affairs leads at WHO prequalification units, procurement managers at national malaria control programs, and formulary directors at Global Fund recipient countries with secondary validation from FDA import alert protocols, EMA stability testing guidelines, and ClinicalTrials.gov resistance surveillance entries. Bottom-up manufacturer capacity assessments and top-down public health program procurement forecasts were triangulated to anchor volume estimates.
Calibration approaches anchored CAGRs to historical ACT procurement trajectories and projected seasonal malaria chemoprevention scale-up across the analysis window. Segmentation dimensions modeled include product type, administration route, patient population, and distribution channel. Resistance surveillance data and corresponding treatment policy shifts fed directly into demand elasticity assumptions for severe malaria protocol upgrades.
Stress conditions across artemisinin yield volatility, regulatory approval timeline extensions, and procurement budget reallocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of WHO resistance surveillance bulletins and national malaria control program formulary revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Burns Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Hyperkalemia Treatment Market