
 ALAD Porphyria Treatment Market | 2026-2036
ALAD Porphyria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
ALAD Porphyria Treatment Market Outlook
Academic medical center purchasing for ALAD porphyria therapies is decoupling from general hospital procurement and consolidating within dedicated rare disease institutes. Recordati Rare Diseases Inc. anchors European distribution through its established orphan drug infrastructure. Alnylam Pharmaceuticals Inc. leverages RNA interference expertise to compete in emerging enzyme modulation approaches. Pfizer Inc. sustains manufacturing scale advantages that support clinical-grade hemin production.
ALAD porphyria treatment encompasses therapeutic interventions targeting delta-aminolevulinic acid dehydratase deficiency, a rare hepatic porphyria characterized by neurovisceral attacks and elevated urine ALA levels, with hemin infusion serving as the primary acute intervention to suppress hepatic ALA synthase activity. The product type dimension shows enzyme replacement maintaining current revenue leadership while gene therapy pipelines attract development investment for curative potential. RNA interference technology within the technology dimension differentiates through targeted ALA synthase suppression mechanisms, whereas biologics occupy established clinical positions with well-characterized safety profiles.
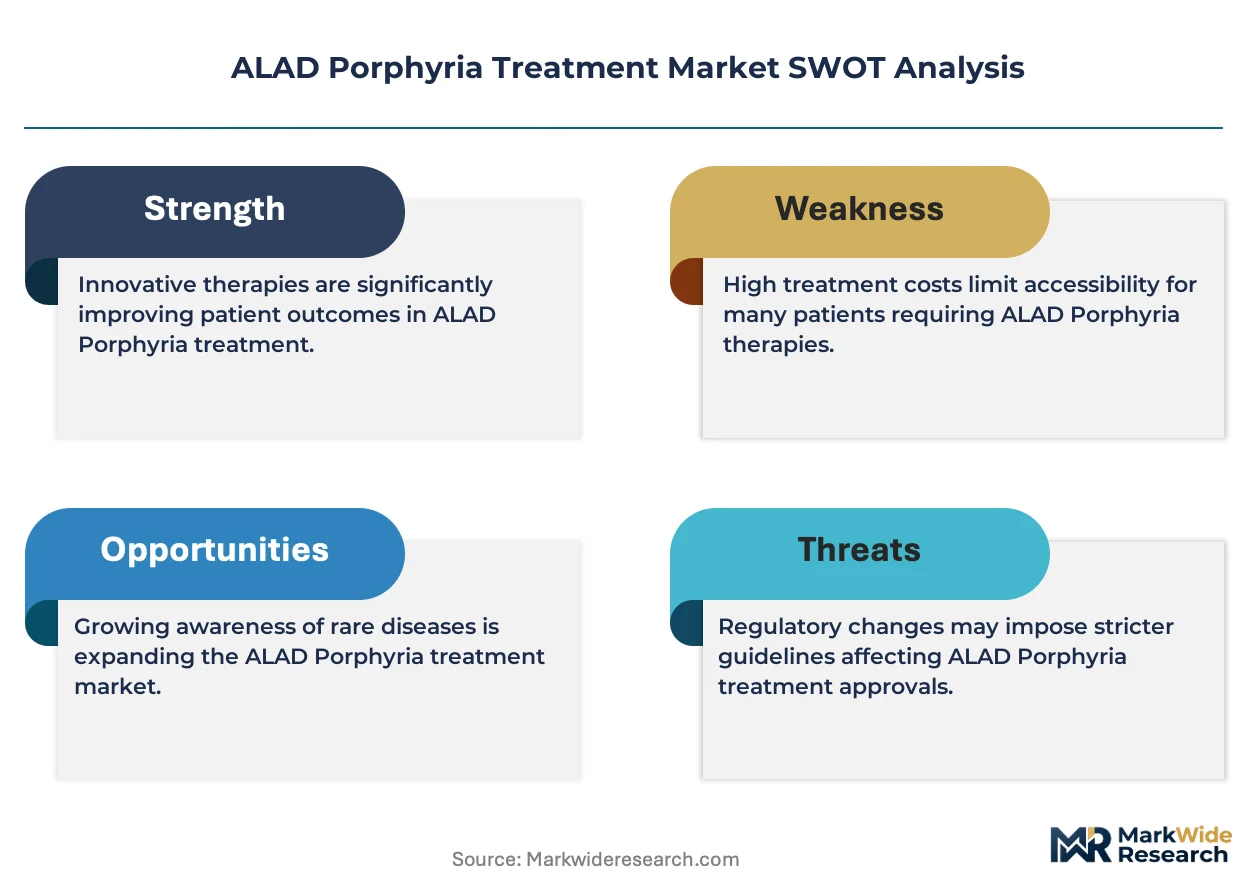
FDA orphan drug exclusivity provisions and EMA rare disease designations shape clinical development economics by extending market protection periods and reducing regulatory fees for ALAD porphyria candidates. The European F-Gas Regulation and US EPA manufacturing standards constrain production site selection for inhalation-sensitive biologic therapies. Stakeholders must monitor gene therapy reimbursement negotiations in Germany and France as these determine sustainable pricing for curative modalities.
Market Dynamics
Academic medical centers are consolidating ALAD porphyria procurement within dedicated rare disease institutes, decoupling purchasing from general hospital systems and creating concentrated demand nodes that reshape competitive access.
Growth Catalysts
- FDA orphan drug exclusivity:Extended market protection periods reduce competitive pressure for developers targeting hepatic porphyria indications. The incentive structure accelerates clinical trial enrollment timelines.
- Enzyme replacement therapy:Established clinical positions with well-characterized safety profiles drive physician confidence in acute neurovisceral attack management. Manufacturing scale supports reliable supply continuity.
- Germany:Specialized porphyria centers aggregate patient volumes into referral networks that concentrate treatment demand and justify dedicated procurement infrastructure.
Market Restraints
- Hemin raw material volatility:Bovine blood sourcing constraints and purification complexity create input cost instability for clinical-grade production.
- European F-Gas Regulation:Manufacturing standards for inhalation-sensitive biologic therapies constrain production site selection and facility qualification timelines.
- Gene therapy reimbursement uncertainty:Curative modality pricing negotiations in France and Germany remain unresolved, delaying commercial launch planning.
Strategic Opportunities
- RNA interference convergence:Combination of ALA synthase suppression mechanisms with established enzyme modulation approaches opens combination therapy pathways.
- EMA rare disease designation:Reduced regulatory fees and accelerated assessment pathways lower development economics for emerging candidates.
- Academic referral networks:Direct-to-specialist-center distribution models bypass general hospital procurement bottlenecks and shorten patient access timelines.
Industry Challenges
- Gene therapy manufacturing talent:Viral vector production and quality control expertise scarcity constrains pipeline advancement for curative candidates.
- Multi-jurisdiction compliance:Divergent hemin storage and handling requirements across FDA, EMA, and national competent authorities fragment regulatory strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ALAD Porphyria Treatment Market |
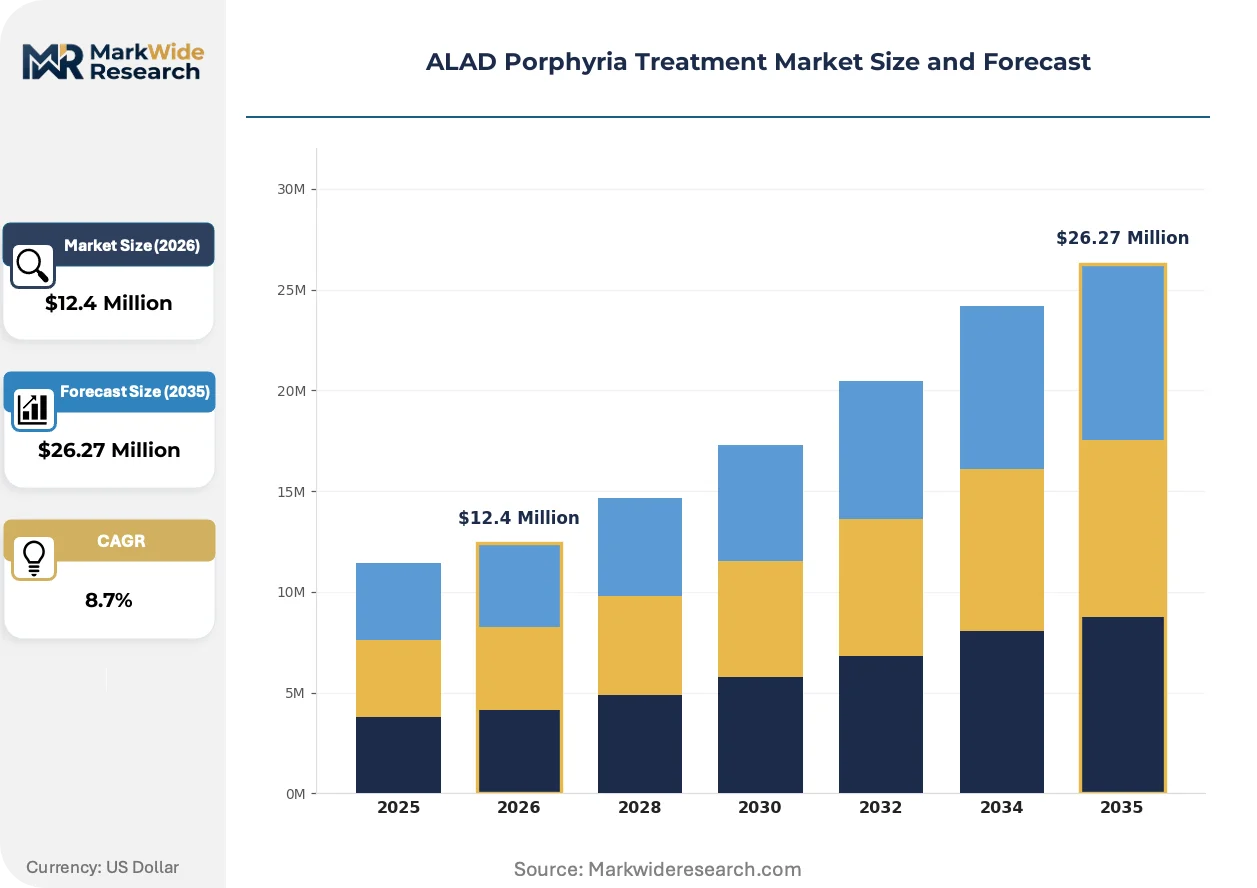
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $26.27 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermediates, Enzyme Replacement, Gene Therapy, Small Molecule Inhibitors Technology: CRISPR, RNA Interference, Biologics, Monoclonal Antibodies End User: Hospitals, Clinics, Laboratories, Research Institutions Delivery Mode: Oral, Injectable, Intravenous, Transdermal |
| Companies Covered | Recordati Rare Diseases Inc., Alnylam Pharmaceuticals Inc., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Novartis AG, AstraZeneca Plc, Johnson & Johnson, Sanofi, BioMarin Pharmaceutical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ALAD Porphyria Treatment Market Strategic Shifts
RNA interference platforms are actively reshaping therapeutic development trajectories for hepatic porphyrias, while regulatory frameworks and procurement models undergo parallel structural evolution.
RNA interference technology is decentralizing treatment administration from infusion centers toward subcutaneous delivery formats. Academic medical centers are piloting home-based administration protocols for stable patients between acute attacks. This shift is compressing hospital bed utilization and reallocating reimbursement toward pharmacy benefit structures.
REACH registration requirements for novel biologic manufacturing inputs are extending supplier qualification timelines for European production sites. The industrial consequence is accelerated backward integration into captive raw material production. Gene therapy developers are responding by consolidating manufacturing within single-jurisdiction facilities to simplify substance registration.
Specialized porphyria centers are consolidating purchasing decisions within dedicated pharmacy and therapeutics committees, displacing decentralized hospital procurement. General hospital formularies are losing influence over rare disease biologic selection. Germany and France exhibit the most pronounced concentration of purchasing authority within institute-level governance structures.
ALAD Porphyria Treatment Market Segmentation
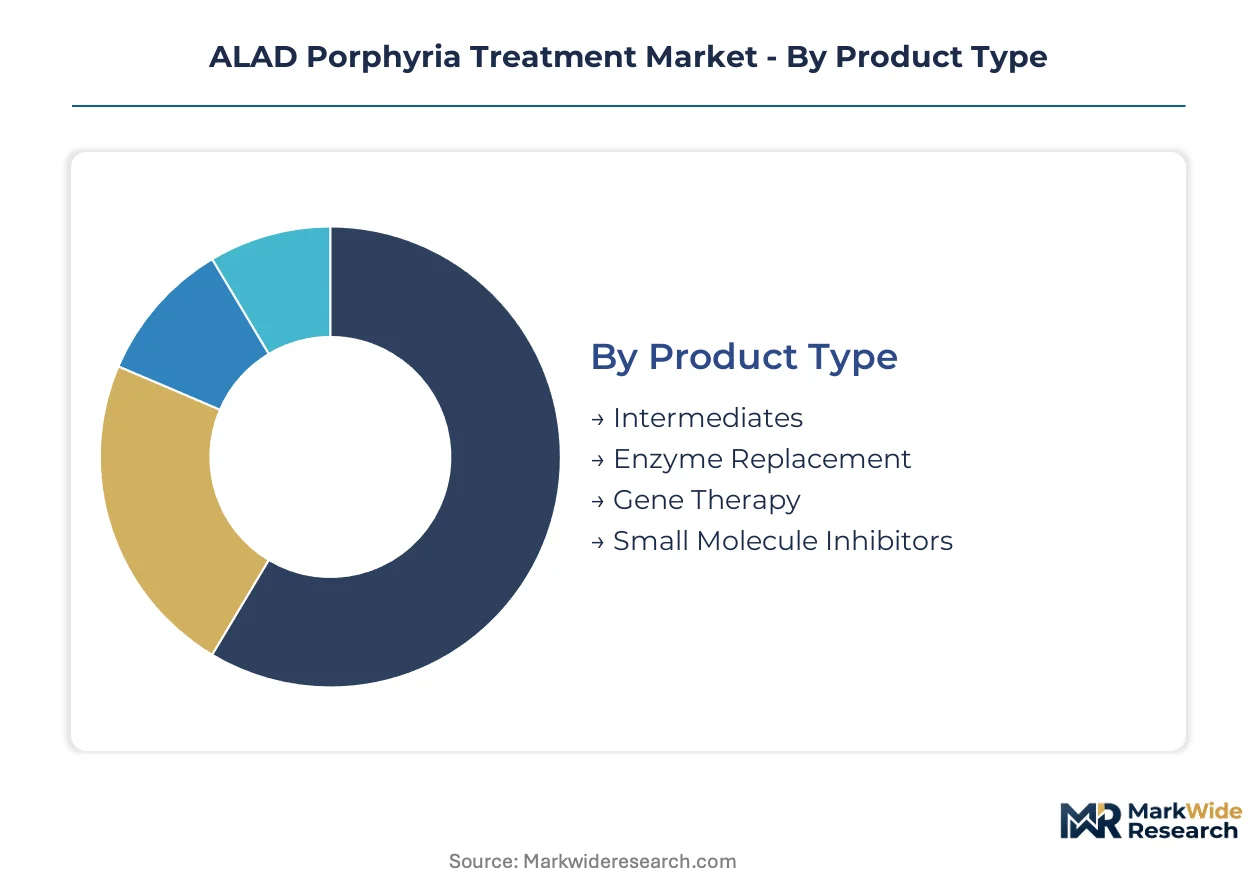
ALAD porphyria treatment segmentation reveals divergent commercialization pathways between acute intervention products and curative modality development. Therapeutic category boundaries are blurring as RNA interference platforms challenge enzyme replacement dominance while gene therapy pipelines advance toward regulatory submission.
Product Type:
Standalone therapeutic agents dominate current clinical practice, while combination-ready platforms and curative modalities embed within long-term treatment ecosystems.
- Intermediates:Hemin and heme arginate formulations serve as first-line acute attack management through hepatic ALA synthase suppression. Demand concentrates in Germany's specialized porphyria centers, where referral networks aggregate neurovisceral attack volumes and justify dedicated infusion infrastructure.
- Enzyme Replacement:Recombinant ALAD protein supplementation targets underlying enzyme deficiency with potential for prophylactic administration. Academic medical centers in France are piloting chronic dosing protocols, though manufacturing scale constraints limit supply expansion.
- Gene Therapy:AAV-mediated ALAD gene delivery offers curative potential through single-administration hepatocyte transduction. Clinical programs remain pre-commercial with unresolved reimbursement frameworks.
- Small Molecule Inhibitors:Oral ALA synthase modulators target chronic attack prevention without infusion requirements. Development pipelines emphasize subcutaneous-ready formulations.
Volume placements concentrate in Enzyme Replacement; the faster expansion belongs to Gene Therapy.
Technology:
Platform selection determines manufacturing complexity, regulatory pathway duration, and reimbursement negotiation positioning across European and North American markets.
- CRISPR:Gene editing approaches target permanent ALAD locus correction in hepatocyte populations. Technical maturity lags behind viral vector delivery for hepatic indications.
- RNA Interference:siRNA constructs achieve durable ALA synthase knockdown through subcutaneous administration. Alnylam's givosiran validates the mechanism in acute hepatic porphyria, with pipeline extension toward ALAD-specific deficiency. German academic centers are adopting home-based injection protocols.
- Biologics:Established recombinant protein manufacturing supports clinical-grade hemin and enzyme replacement supply. FDA and EMA orphan drug frameworks provide extended exclusivity protection.
- Monoclonal Antibodies:Targeted immunomodulation remains exploratory for porphyria-associated inflammatory complications. No advanced candidates in Phase II development.
Biologics capture current revenue concentration; RNA Interference is climbing the fastest toward commercial scale.
End User:
Procurement authority is migrating from general hospital systems toward specialized rare disease institutes with dedicated pharmacy governance.
- Hospitals:Tertiary centers maintain emergency infusion capabilities for acute neurovisceral attacks. General hospital formularies are losing influence as purchasing consolidates within rare disease institutes.
- Clinics:Outpatient settings are expanding chronic management and stable patient monitoring. France's Centre de Référence des Porphyries network demonstrates concentrated clinic-based care models.
- Laboratories:Diagnostic confirmation and biomarker monitoring support treatment initiation decisions. ALA and PBG quantification remains centralized in reference laboratories.
- Research Institutions:Academic medical centers drive clinical trial enrollment and natural history study execution. FDA orphan drug incentives accelerate site activation across US research networks.
Procurement volume clusters in Hospitals; Research Institutions are gaining share fastest through trial expansion.
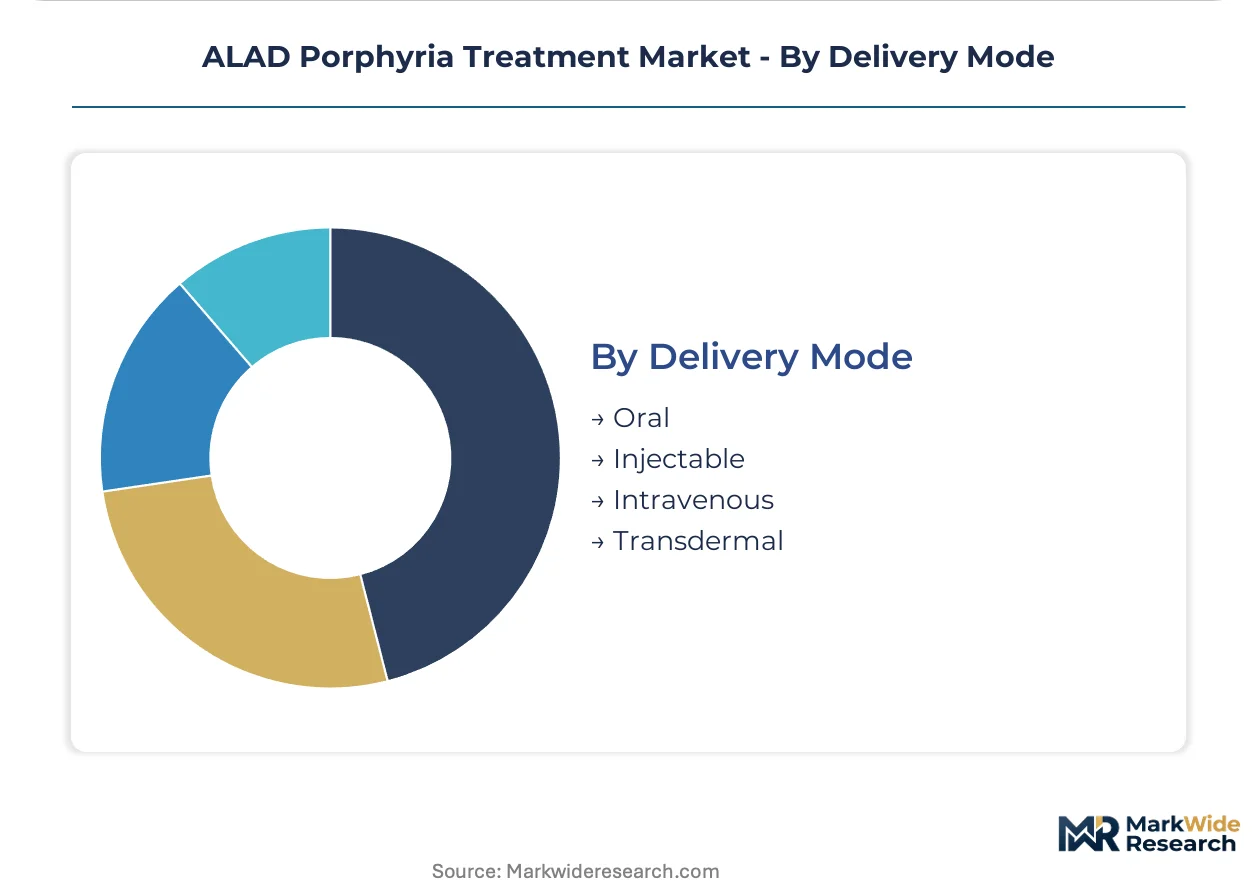
Delivery Mode:
Administration format selection directly impacts site-of-care requirements, reimbursement coding, and patient adherence profiles.
- Oral:Small molecule inhibitors and prophylactic formulations target chronic administration without healthcare facility visits. Bioavailability challenges constrain therapeutic efficacy for hepatic porphyrias.
- Injectable:Subcutaneous RNA interference platforms enable home-based administration between acute attacks. German pilot programs demonstrate reduced hospital bed utilization.
- Intravenous:Hemin infusion remains the standard for severe acute attacks requiring hospitalization. Manufacturing and cold-chain logistics create supply concentration.
- Transdermal:Patch-based delivery remains developmental for continuous prophylactic dosing. No commercial candidates in advanced clinical stages.
Intravenous maintains current placement dominance; Injectable formats show the steepest expansion trajectory toward outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bovine blood sourcing networks in Argentina and Uruguay anchor hemin raw material supply chains for clinical-grade production. Academic medical centers in Germany and France concentrate patient referral volumes. FDA and EMA orphan drug frameworks shape development economics across North American and European markets.
Germany
Specialized porphyria centers in Munich and Düsseldorf aggregate neurovisceral attack volumes into concentrated demand nodes. The F-Gas Regulation constrains biologic manufacturing site selection and facility qualification timelines. Bavaria's academic medical centers pilot home-based RNA interference administration protocols.
United States
FDA orphan drug exclusivity provisions accelerate clinical trial enrollment across research networks in Boston and San Diego. The EPA maintains manufacturing standards for inhalation-sensitive biologic therapies that affect production location decisions. NIH-funded natural history studies concentrate patient recruitment in tertiary referral centers.
France
The Centre de Référence des Porphyries network consolidates chronic management and stable patient monitoring in Paris and Lyon. ANSM regulates gene therapy reimbursement negotiations that remain unresolved for curative modalities. Île-de-France academic hospitals drive clinical trial site activation.
United Kingdom
NHS England specialized commissioning frameworks concentrate ALAD porphyria treatment authority within designated rare disease centers in London and Manchester. The MHRA operates post-Brexit regulatory pathways that diverge from EMA centralized procedures. Oxford and Cambridge research institutions anchor gene therapy development pipelines.
Switzerland
Swissmedic's accelerated assessment pathways for rare disease designation attract development program registration. Basel and Zurich host contract manufacturing organizations serving viral vector production for gene therapy candidates. The country's biologics production infrastructure supports clinical-grade supply continuity.
ALAD Porphyria Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue RNA interference and gene therapy modalities. The market structure consolidates around three strategic archetypes: large-cap pharmaceutical manufacturers with orphan drug infrastructure, RNA platform specialists, and rare disease-focused commercialization firms. Competitive dynamics center on manufacturing scale for hemin production and regulatory exclusivity positioning. Capacity expansion and strategic partnerships dominate competitive moves.
Among North American-based developers, Alnylam Pharmaceuticals Inc. exemplifies the RNA interference platform archetype, while Pfizer Inc. represents large-scale biologics manufacturing capability. Recordati Rare Diseases Inc. occupies a position within the rare disease commercialization tier. These three anchors illustrate divergent strategic pathways: platform technology leverage, manufacturing scale defense, and specialized distribution infrastructure.
| Leading Market Players |
|---|
| Recordati Rare Diseases Inc. |
| Alnylam Pharmaceuticals Inc. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| AstraZeneca Plc |
| Johnson & Johnson |
| Sanofi |
| BioMarin Pharmaceutical Inc. |
| Others |
Value Chain & Pricing Dynamics
Bovine blood sourcing costs from Argentina and Uruguay flow through purification complexity premiums into acute hemin infusion pricing tiers, with clinical-grade manufacturing standards in Germany and Switzerland commanding substantial markups over standard hospital procurement benchmarks.
Pricing Analysis
Service bundling separates acute attack management packages from chronic prophylactic protocols, with infusion center logistics and specialist nursing support unbundled in German academic medical centers. Three-tier pricing structure across premium-certified hemin formulations, standard enzyme replacement, and economy-tier supportive care reflects FDA and EMA orphan drug exclusivity premiums. Cost compression in standard-tier hemin is intensifying because Argentine raw material volatility feeds into manufacturing margin pressure. Academic medical centers exhibit lowest price sensitivity due to dedicated rare disease institute budgets, while general hospital formularies face tightening procurement constraints.
Supply Chain Analysis
Cold-chain freight costs from South American abattoirs to European purification facilities anchor hemin production economics, with temperature-controlled logistics consuming disproportionate share of landed cost. Argentina, Uruguay, and Germany concentrate upstream supply, drawing from bovine hemoglobin extraction, chromatographic purification resins, and viral vector manufacturing inputs. Single-source vulnerability in clinical-grade hemin purification creates structural exposure to Argentine export restrictions. Distribution runs through specialized rare disease institute pharmacy committees, bypassing general hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race, with players pursuing backward integration into bovine blood sourcing and captive viral vector production to secure supply continuity against Argentine raw material volatility.
For Market Incumbents: Lock in bovine hemoglobin supply through long-term offtake agreements with Argentine and Uruguayan abattoir networks before RNA interference platforms displace enzyme replacement volume. Expand manufacturing footprint into Switzerland to exploit Swissmedic accelerated assessment pathways and reduce F-Gas Regulation compliance exposure. Prioritize gene therapy manufacturing talent acquisition to defend against pipeline advancement constraints. For New Entrants and Emerging Players: Begin with subcutaneous RNA interference platform development targeting German home-based administration pilot programs, where academic medical center adoption curves outpace hospital infusion capacity. France's unresolved gene therapy reimbursement framework creates white-space opportunity for curative modality pricing negotiations. Pursue direct-to-specialist-center distribution partnerships bypassing general hospital formulary gatekeepers. For Investors and Strategic Acquirers: Distressed-cycle entries favor rare disease commercialization specialists with established EMA orphan drug infrastructure in France and Germany, where reimbursement uncertainty has compressed valuation multiples. Long-term viability hinges on gene therapy manufacturing capability scarcity resolving over the next decade. Monitor ANSM reimbursement negotiation outcomes as inflection signal for curative modality commercialization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bovine Sourcing | Captive Argentine hemoglobin supply secures hemin production against export volatility. |
| RNA Interference Platform Extension | Alnylam's givosiran mechanism validates subcutaneous ALA synthase suppression for ALAD deficiency. |
| Gene Therapy Manufacturing Scale-Up | Swiss viral vector production addresses EMA rare disease designation pipeline requirements. |
| Academic Referral Network Partnerships | German specialized porphyria centers concentrate demand nodes for direct distribution access. |
| Reimbursement Strategy Development | ANSM and German statutory health insurance negotiations determine curative modality pricing sustainability. |
Study Parameters
Independent corroboration across hospital pharmacy directors, rare disease institute formulary committees, and regulatory affairs specialists at EMA-designated orphan drug developers underwrites the qualitative findings. Primary interviews with clinical trial investigators, hemin manufacturing quality control leads, and German statutory health insurance reimbursement negotiators combined with secondary validation from FDA orphan drug designations, EMA rare disease registries, ClinicalTrials.gov enrollment data, and Bavarian academic medical center procurement disclosures. Bottom-up patient volume estimates and top-down pharmaceutical manufacturer revenue triangulation anchored segmentation sizing.
Rate-of-change decomposition across therapeutic category evolution, technology platform maturation, and end-user procurement authority migration shaped the analytical framework. Segmentation dimensions modeled include product type, technology platform, delivery mode, and regional regulatory cluster, with CAGRs derived from enrollment velocity in ongoing clinical programs and historical orphan drug launch trajectories. Forecast inputs incorporated hemin raw material cost trajectories and gene therapy reimbursement negotiation resolution probabilities.
Underlying measurement precision varies by segment; enzyme replacement and biologics categories carry tighter precision than gene therapy pipelines where commercial timelines remain speculative. Forecasts incorporate assumptions regarding EMA accelerated assessment pathway utilization and FDA orphan drug exclusivity period extensions that could revise if regulatory frameworks shift. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Gangrene Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Kidney Stones Management Market
Medical Treatment
Tetanus Treatment Market