
 Babesiosis Treatment Market | 2026-2036
Babesiosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Babesiosis Treatment Market Outlook
Atovaquone is realigning cost structures across combination therapy protocols as clinicians shift from older azole-based alternatives. Pfizer leverages its antimicrobial manufacturing scale to secure hospital formulary placement for parenteral formulations. 60 Degrees Pharmaceuticals anchors its portfolio on tropical and rare disease indications, sustaining focused clinical development in babesiosis. Novartis competes through global distribution infrastructure that extends reach into endemic regions with limited cold-chain capacity.
Babesiosis treatment encompasses pharmacological intervention against Babesia microti and related intraerythrocytic protozoan parasites, primarily employing antiprotozoal agents such as atovaquone plus azithromycin or clindamycin plus quinine regimens, with exchange transfusion reserved for severe hemolytic complications. The primary purpose is parasite clearance, hemoglobin stabilization, and prevention of relapsing infection in asplenic or immunocompromised hosts. Antiprotozoal drugs dominate current revenue, though monoclonal antibodies represent the fastest-growing product category as developers target complement-mediated parasite lysis mechanisms. Injectable delivery modes command premium positioning in acute hospital settings, while oral formulations occupy the expanding outpatient and post-discharge continuation therapy segments.
FDA orphan drug designations and tropical disease priority review vouchers shape manufacturer investment calculus for babesiosis therapeutics. EPA tick vector control mandates and CDC surveillance reporting requirements indirectly influence treatment demand patterns by altering case detection thresholds. Stakeholders must monitor evolving resistance profiles in Babesia isolates and regulatory guidance on combination therapy endpoints to align pipeline investments with forthcoming clinical evidence standards.
Market Dynamics
Hospital formulary committees are tightening antimicrobial stewardship protocols, forcing manufacturers to demonstrate superior parasite clearance rates against clindamycin-quinine combinations to secure tier-one placement.
Growth Catalysts
- FDA orphan drug incentives:Priority review vouchers for tropical diseases accelerate development timelines for novel antiprotozoal candidates targeting Babesia divergens and B. duncani species.
- Tick surveillance expansion:CDC reporting mandates in Connecticut, Massachusetts, and Wisconsin elevate case detection thresholds and drive diagnostic-linked treatment protocols.
- Exchange transfusion protocols:Critical care units in endemic regions standardize parasite burden thresholds for therapeutic apheresis, expanding addressable patient populations.
Market Restraints
- API supply concentration:Atovaquone active pharmaceutical ingredient production clusters in Indian contract manufacturers, exposing procurement to export restriction volatility.
- Cold-chain infrastructure gaps:Parenteral quinine formulations require continuous temperature monitoring, limiting distribution reach into rural endemic zones with intermittent power reliability.
- Substitution pressure:Generic azithromycin tablets commoditize combination therapy pricing, compressing branded formulation margins in outpatient settings.
Strategic Opportunities
- Monoclonal antibody platforms:Complement-mediated lysis mechanisms targeting merozoite surface proteins offer curative potential in asplenic populations with relapsing infection.
- Point-of-care diagnostics:PCR-based field testing in Minnesota and Rhode Island emergency departments shortens time-to-treatment windows and reduces empiric therapy overuse.
- Post-discharge oral regimens:Extended azithromycin-atovaquone continuation therapy captures revenue from step-down hospital admissions previously managed with observation-only protocols.
Industry Challenges
- Clinical trial recruitment:Rare disease incidence in non-endemic states complicates randomized endpoint studies for severe babesiosis indications.
- Resistance surveillance infrastructure:Reference laboratories lack standardized Babesia isolate banking protocols to track emerging atovaquone tolerance patterns.
- Reimbursement coding alignment:ICD-10 specificity gaps between babesiosis and malaria-like symptom clusters delay prior authorization approvals for branded therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Babesiosis Treatment Market |
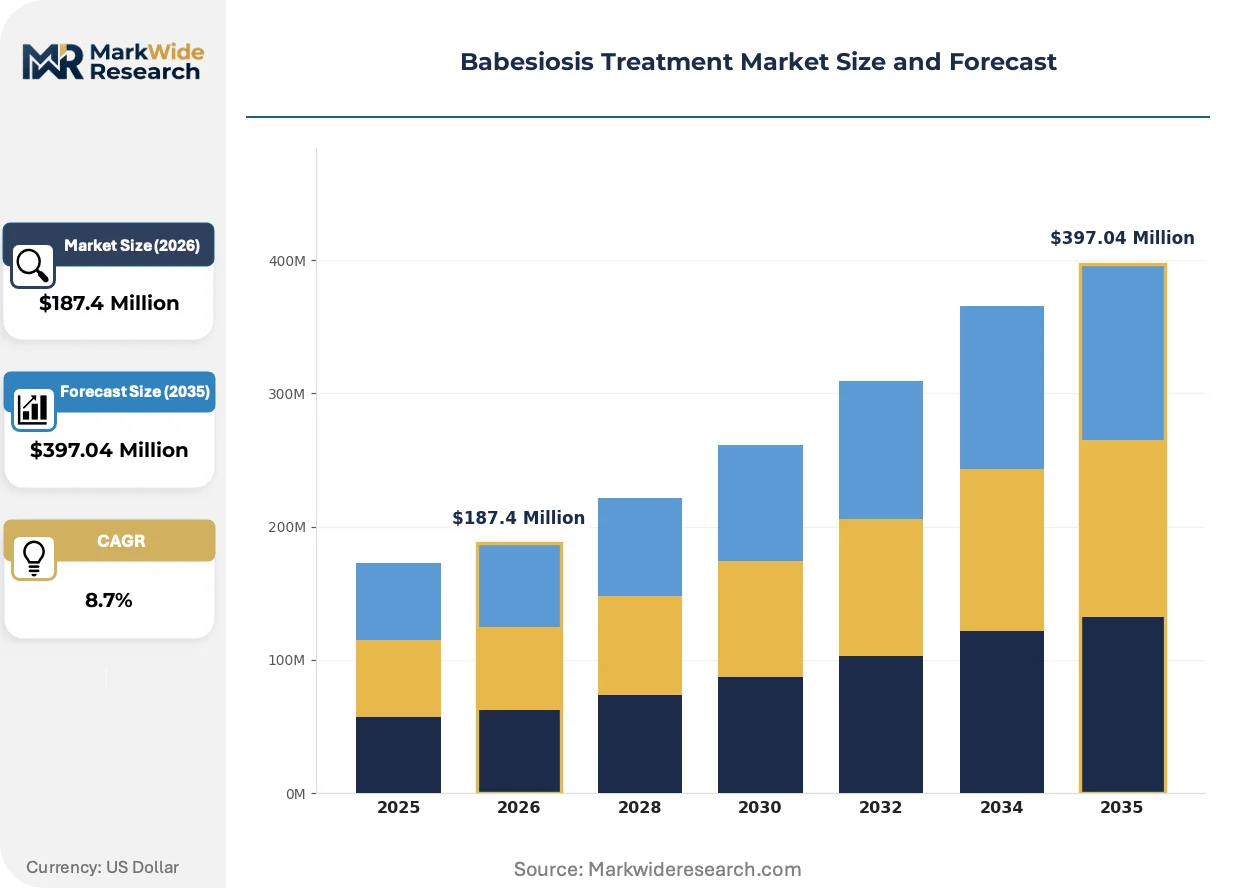
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Antimicrobial Therapy, Supportive Care, Combination Therapy, Clinical Trials Product Type: Antiprotozoal Drugs, Monoclonal Antibodies, Diagnostic Kits, Vaccines End User: Hospitals, Research Laboratories, Home Healthcare, Clinics Delivery Mode: Injectable, Oral, Intravenous, Topical |
| Companies Covered | GlaxoSmithKline, Pfizer, Amneal Pharmaceuticals, Novartis, Merck & Co., 60 Degrees Pharmaceuticals, Apotex, Lupin Pharmaceuticals, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Babesiosis Treatment Market Strategic Shifts
Antiprotozoal development is pivoting toward host-directed immunomodulation alongside direct parasite targeting, reshaping clinical trial endpoint design and regulatory submission strategies.
Monoclonal antibody therapies targeting infected erythrocyte surface antigens are absorbing development resources from small-molecule programs at biotech sponsors with infectious disease portfolios. Academic medical centers in New York and New Jersey are establishing compassionate-use pathways for these candidates in high-parasitemia cases failing standard combination therapy. The structural consequence is a bifurcation in R&D investment between incremental oral regimen improvements and transformative injectable biologics.
EPA vector control mandates expanding permethrin-treated landscape applications in residential zones are reducing per-capita tick exposure in some counties, indirectly pressuring treatment volume forecasts. Manufacturers must model vector intervention efficacy curves alongside climate-driven range expansion to calibrate demand projections. This regulatory overlay most affects strategic planning for hospital systems in Vermont and New Hampshire where land-use patterns concentrate human-tick contact.
Telemedicine triage protocols in rural Maine and upstate New York are compressing time from symptom onset to prescription fulfillment for uncomplicated cases. Primary care networks now coordinate directly with specialty pharmacies for 24-hour oral regimen initiation, bypassing traditional emergency department referral pathways. This channel shift concentrates volume with integrated delivery systems possessing captive pharmacy assets.
Babesiosis Treatment Market Segmentation
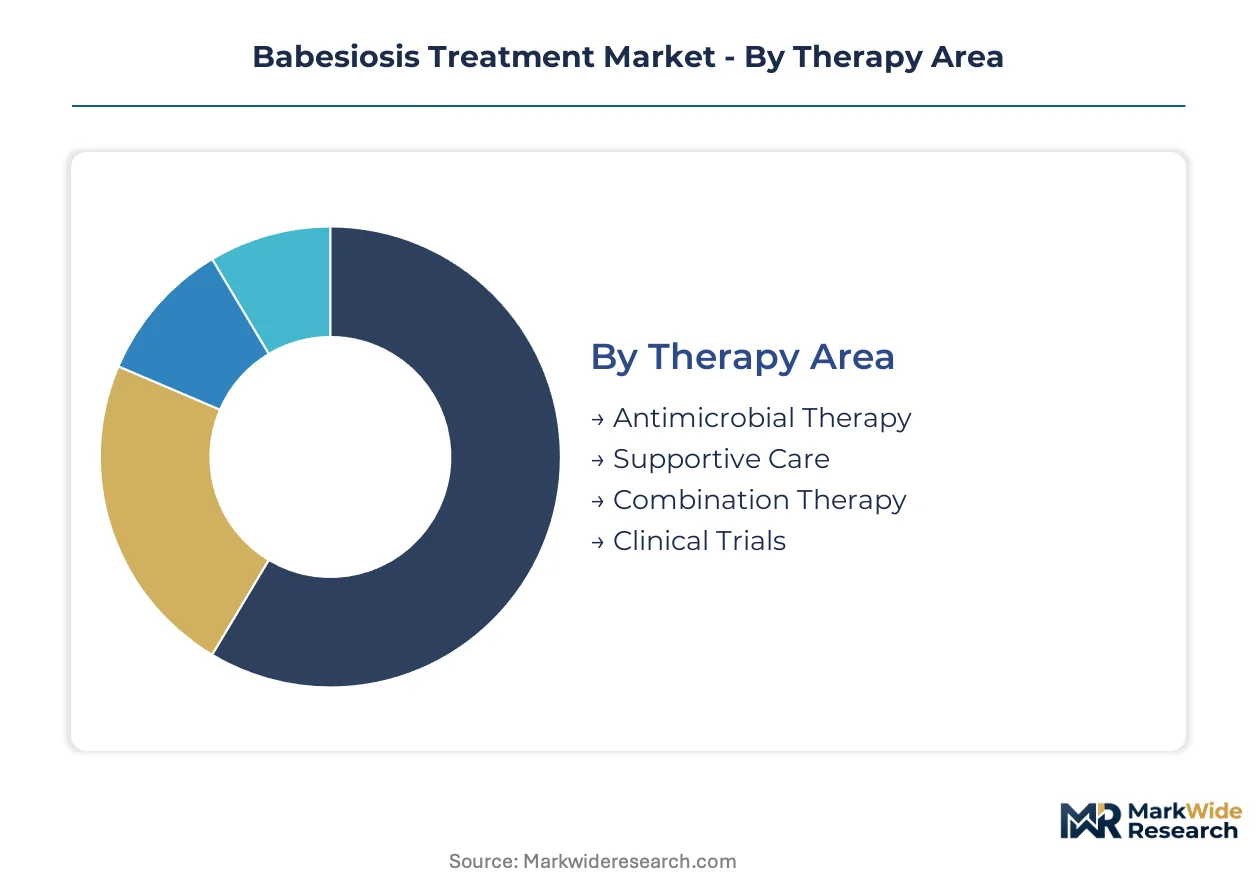
Treatment modality selection in babesiosis hinges on disease severity, patient immunocompetence, and healthcare setting capabilities. Segmentation reveals how acute care protocols diverge from outpatient management pathways across endemic regions.
Therapy Area:
Standalone antimicrobial protocols dominate uncomplicated cases, while embedded combination regimens integrate with transfusion services and critical care monitoring.
- Antimicrobial Therapy:Atovaquone-azithromycin and clindamycin-quinine regimens constitute first-line pharmacological intervention. Hospital formularies in Connecticut and Massachusetts prioritize IV clindamycin for high-parasitemia admissions, driven by FDA orphan drug incentives accelerating antiprotozoal development.
- Combination Therapy:Dual-agent protocols layer antiprotozoals with immunomodulatory adjuncts in asplenic patients. Demand concentrates in tertiary centers managing relapsing infections, constrained by antimicrobial stewardship committees tightening formulary access.
- Supportive Care:Hemodynamic stabilization and hemoglobin monitoring complement drug therapy in severe presentations.
- Clinical Trials:Experimental protocols for novel merozoite-targeting agents recruit through academic medical centers in New York and New Jersey.
Volume placements concentrate in Antimicrobial Therapy; the faster expansion belongs to Combination Therapy.
Product Type:
Cost tier stratification separates premium biologics from commoditized small-molecule generics, with diagnostic kits occupying a mid-tier value position.
- Antiprotozoal Drugs:Small-molecule agents atovaquone, azithromycin, clindamycin, and quinine generate the majority of current revenue. Generic azithromycin tablets compress outpatient pricing, while parenteral formulations command hospital premiums.
- Monoclonal Antibodies:Complement-mediated lysis biologics targeting infected erythrocyte surface antigens represent the steepest expansion trajectory. Development pipelines at infectious disease biotechs absorb resources from traditional chemistry programs.
- Diagnostic Kits:PCR-based field testing shortens time-to-treatment in Minnesota and Rhode Island emergency departments.
- Vaccines:Prophylactic candidates remain preclinical with no near-term commercial pathway.
Revenue gravity sits with Antiprotozoal Drugs; pipeline investment is concentrating in Monoclonal Antibodies.
End User:
Customer type determines procurement scale, with integrated delivery systems capturing post-discharge continuation volumes previously fragmented across settings.
- Hospitals:Acute care units standardize exchange transfusion thresholds and IV antiprotozoal protocols. CDC surveillance mandates in Wisconsin and Vermont elevate diagnostic-linked admission rates.
- Home Healthcare:Specialty pharmacy networks now coordinate 24-hour oral regimen initiation for uncomplicated cases, bypassing traditional emergency department pathways in rural Maine.
- Research Laboratories:Reference labs lack standardized Babesia isolate banking for resistance surveillance.
- Clinics:Primary care triage via telemedicine compresses symptom-to-prescription intervals in upstate New York.
Procurement volume clusters in Hospitals; channel shift momentum favors Home Healthcare.
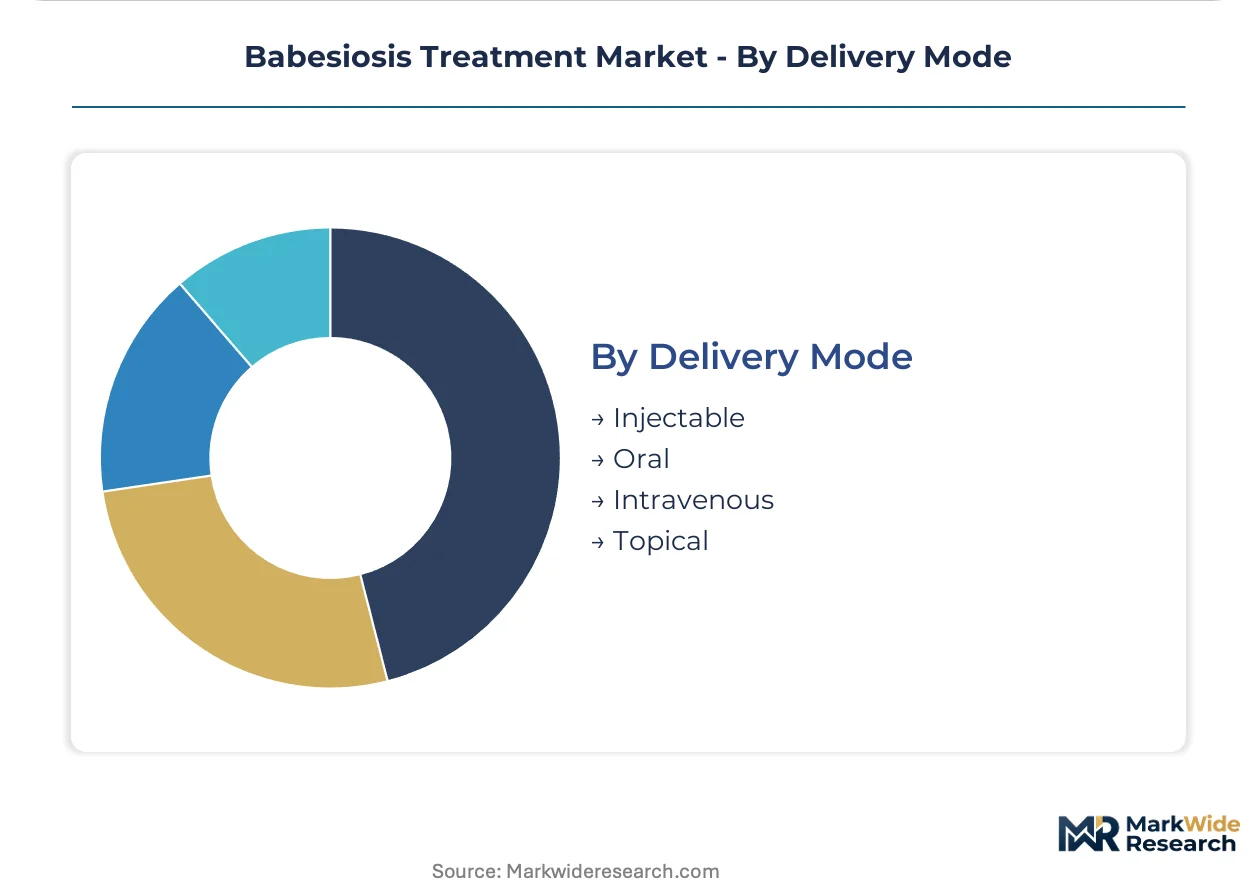
Delivery Mode:
Application severity dictates route selection, with acute hemolytic crises requiring parenteral access and stable outpatients transitioning to oral continuation.
- Injectable:Intramuscular and subcutaneous formulations serve step-down transitions from IV therapy. Cold-chain requirements limit distribution into rural endemic zones with intermittent power reliability.
- Intravenous:Parenteral quinine and clindamycin command premium positioning in critical care units. Hospital formulary committees demand superior parasite clearance data for tier-one placement.
- Oral:Atovaquone tablets and azithromycin capsules dominate outpatient and post-discharge segments.
- Topical:No approved babesiosis indication; vector repellents fall under EPA regulatory jurisdiction.
Utilization concentrates in Intravenous delivery; Oral formulations are climbing the fastest as step-down protocols expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand concentrates in Northeastern and Upper Midwestern states where Ixodes scapularis tick exposure drives case volumes and hospital procurement patterns.
United States
FDA orphan drug incentives and CDC surveillance mandates in Connecticut, Massachusetts, and Wisconsin elevate diagnostic-linked treatment protocols. EPA vector control mandates expanding permethrin-treated landscape applications in residential zones reduce per-capita tick exposure in some counties. Academic medical centers in New York and New Jersey establish compassionate-use pathways for monoclonal antibody candidates in high-parasitemia cases.
Germany
EMA orphan drug designation pathways accelerate development timelines for novel antiprotozoal candidates targeting Babesia divergens species. The country's national pharmaceutical regulator maintains stringent cold-chain requirements for parenteral formulations that limit distribution into rural endemic zones. Clinical research clusters in Berlin and Munich coordinate multicenter trials for host-directed immunomodulation approaches.
Switzerland
Swissmedic accelerated approval mechanisms for tropical diseases reshape manufacturer R&D priorities for rare parasitic indications. Federal vector control programs in the Jura and Ticino regions monitor Babesia venatorum emergence in alpine tick populations. Basel-based pharmaceutical research hubs sustain focused clinical development in babesiosis through partnerships with endemic-region hospitals.
France
ANSM pharmacovigilance requirements for antiprotozoal combinations influence post-market surveillance protocols for atovaquone-azithromycin regimens. National health insurance reimbursement coding alignment for babesiosis versus malaria-like symptom clusters delays prior authorization approvals. The Paris-Saclay biomedical cluster advances PCR-based field testing for emergency department triage.
United Kingdom
MHRA priority review pathways for tropical diseases attract biotech sponsors developing complement-mediated lysis biologics. NHS antimicrobial stewardship committees tighten formulary access for branded formulations against generic azithromycin substitution pressure. London-based reference laboratories develop standardized Babesia isolate banking protocols for resistance surveillance.
Babesiosis Treatment Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents balance small-molecule commoditization against biologic development risks. Market structure exhibits moderate consolidation with three distinct strategic tiers: multinational pharmaceutical conglomerates leveraging global distribution infrastructure, mid-cap infectious disease specialists concentrating on tropical and rare indications, and generic manufacturers competing on outpatient pricing. Dominant competitive moves include geographic expansion into endemic regions with limited cold-chain capacity and technology licensing for monoclonal antibody platforms targeting merozoite surface proteins.
Within the multinational tier, Pfizer and Novartis exemplify scale-driven positioning through antimicrobial manufacturing scale and global distribution reach respectively. 60 Degrees Pharmaceuticals occupies a specialist position anchoring portfolio concentration on tropical and rare disease indications. These three entities represent the competitive spectrum from broad-based hospital formulary placement to focused clinical development in babesiosis, with each archetype responding differently to FDA orphan drug incentives and generic substitution pressures.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Pfizer |
| Amneal Pharmaceuticals |
| Novartis |
| Merck & Co. |
| 60 Degrees Pharmaceuticals |
| Apotex |
| Lupin Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
Specialist pharmaceutical manufacturers rolled up through private-equity consolidation anchor supply behavior in the babesiosis treatment market, translating concentrated API sourcing into disciplined pricing tiers that resist generic commoditization pressures.
Pricing Analysis
High-volume outpatient oral regimens trade on thin margins against generic azithromycin substitution, while intravenous parenteral formulations in acute care command substantial premiums justified by cold-chain integrity and FDA orphan drug exclusivity. Three-tier pricing structure across premium biologics, standard hospital formulations, and economy oral generics separates segments by delivery complexity and regulatory burden. Pricing pressure stems from antimicrobial stewardship committees demanding superior parasite clearance data for tier-one formulary placement. Community health systems exhibit highest price sensitivity, whereas tertiary centers managing severe hemolytic cases prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
FDA and EMA certification requirements for sterile parenteral manufacturing gate supplier entry, concentrating finished-dose production among qualified facilities in the United States, Germany, and Switzerland. Atovaquone API draws from Indian contract manufacturers, while quinine alkaloid extraction rests on Indonesian and Vietnamese botanical supply chains. Single-source vulnerability in atovaquone active pharmaceutical ingredient exposes procurement to export restriction volatility. Distribution runs through hospital GPO contracts and specialty pharmacy networks with temperature-validated logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The babesiosis treatment market functions as a vertical-integration race where control over sterile parenteral manufacturing capacity and cold-chain distribution infrastructure determines who captures premium positioning in hospital formulary decisions.
For Market Incumbents: Deepen backward integration into atovaquone API production to insulate margins from Indian export restriction volatility and secure supply continuity for combination therapy protocols. Fortify hospital formulary relationships through antimicrobial stewardship committee engagement demonstrating superior parasite clearance rates against clindamycin-quinine alternatives. For New Entrants and Emerging Players: Enter via point-of-care diagnostic platforms in Minnesota and Rhode Island emergency departments, where PCR-based field testing shortens time-to-treatment and reduces empiric therapy overuse. Capture post-discharge oral continuation therapy volumes through direct-to-specialty-pharmacy coordination in rural Maine and upstate New York telemedicine networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor monoclonal antibody platform developers in Massachusetts and New Jersey academic medical centers, where compassionate-use pathways validate complement-mediated lysis mechanisms ahead of registrational trials. Long-term viability hinges on regulatory exclusivity durability and vector control mandate efficacy curves in Vermont and New Hampshire. Watch FDA orphan drug priority review voucher issuance velocity as inflection indicator for R&D investment climate.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Host-directed immunomodulation studies in New York academic centers reshape endpoint design for severe babesiosis indications. |
| Regulatory Approval Pathway | FDA orphan drug designation accelerates development timelines for Babesia divergens and B. duncani antiprotozoal candidates. |
| Manufacturing Scale-Up | Sterile parenteral capacity expansion in Connecticut and Massachusetts secures hospital formulary placement for IV clindamycin. |
| Licensing Agreement | Technology partnerships with Basel-based research hubs extend monoclonal antibody development into European endemic regions. |
| Pipeline Diversification | Merozoite-targeting biologics absorb development resources from small-molecule programs at infectious disease biotech sponsors. |
Study Parameters
Multi-period observation of FDA orphan drug designations, CDC surveillance reporting thresholds, and hospital formulary placement patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, ClinicalTrials.gov entries, EMA submissions, and formulary databases. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation converged on segment estimates.
Segment-weighting across therapy area, product type, end user, and delivery mode dimensions structured the analytical framework, with regional regulatory clusters and vector ecology zones incorporated as overlay variables. CAGRs were derived from fitted growth curves applied to base-year estimates across the projection horizon. Forecast inputs included climate-driven tick range expansion models and EPA vector control mandate implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under atovaquone resistance emergence or abrupt antimicrobial stewardship protocol shifts. Assumptions reflect current FDA and CDC guidance trajectories. A model refresh is warranted upon material change in Babesia isolate banking standardization or monoclonal antibody compassionate-use pathway expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Global Leukapheresis Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Skin Grafts Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market