
 Spain Hair Transplant Market | 2026-2036
Spain Hair Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Hair Transplant Market Insights
Single-source equipment dependence is rebalancing toward multi-vendor procurement across Spanish transplant networks. HTI Clinic leverages robotic-assisted FUE platforms to sustain precision positioning in premium segments. Hospital Capilar anchors its Madrid footprint through in-house graft processing labs. Insparya Hair Company competes via celebrity-endorsed brand architecture and direct-to-consumer channels.
Hair transplant surgery relocates follicular units from donor to recipient scalp zones, typically extracting 1-4 hair grafts per unit with 0.8-1.2mm punch diameters for natural density restoration. FUE procedures dominate procedural volume while robotic systems command premium pricing tiers. Male patient segments occupy the largest share, though female demand accelerates fastest as social stigma erodes. Specialized clinics capture disproportionate margin pools versus general cosmetic surgery centers due to concentrated surgical expertise and repeat visit economics.
Spain's Ministry of Health and autonomous regional health services regulate clinic licensing under national medical device frameworks, while the European Medical Device Regulation mandates CE-marked surgical instruments and traceability protocols. The national pharmaceutical regulator inspects tissue handling compliance, shaping sterile chain requirements that filter clinic entry. Stakeholders must monitor evolving EU AI Act implications for robotic graft selection algorithms and autonomous surgical assistance tools.
Market Dynamics
Robotic graft selection systems are compressing surgical timelines across Spanish transplant networks while regional health services tighten licensing scrutiny under the EU Medical Device Regulation. This dual pressure is forcing clinic operators to rebuild capital deployment models around precision automation and compliance infrastructure.
Growth Catalysts
- EU Medical Device Regulation:CE-marked surgical instruments now carry mandatory traceability protocols, pushing Spanish clinics toward certified multi-vendor procurement frameworks that reduce single-source risk.
- Madrid-Barcelona corridor density:Concentrated dermatology infrastructure in these metropolitan zones creates referral network effects and specialist labor pools that sustain procedural volume expansion.
- Female patient segments:Social stigma erosion around female pattern hair loss is unlocking new consult-to-procedure conversion pathways previously dominated by male demographics.
Market Restraints
- Donor follicle scarcity:Finite occipital scalp reserves impose hard ceilings on graft yields per procedure, limiting revenue-per-patient expansion for high-volume operators.
- Autonomous community licensing fragmentation:Spain's 17 regional health services apply divergent clinic accreditation standards, creating compliance cost duplication for multi-site networks.
- Robotic system capex concentration:Premium FUE platforms require seven-figure equipment investments that filter market entry to well-capitalized specialists.
Strategic Opportunities
- Andalusia and Valencia underpenetration:These autonomous communities show transplant clinic density ratios 40% below Madrid levels, presenting first-mover positioning for regional satellite networks.
- EU AI Act algorithmic compliance:Early alignment with autonomous surgical assistance governance frameworks will secure regulatory goodwill ahead of enforcement phase-in.
- Direct-to-consumer teleconsultation:Virtual triage and graft planning workflows are compressing patient acquisition costs outside traditional referral dependencies.
Industry Challenges
- Trichoscopy technician certification gaps:Spain lacks standardized training pathways for graft viability assessment specialists, forcing clinics to import talent or build captive academies.
- Cold-chain tissue handling protocols:Regional pharmaceutical inspectorates apply inconsistent sterile transport standards, complicating multi-site graft logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Hair Transplant Market |
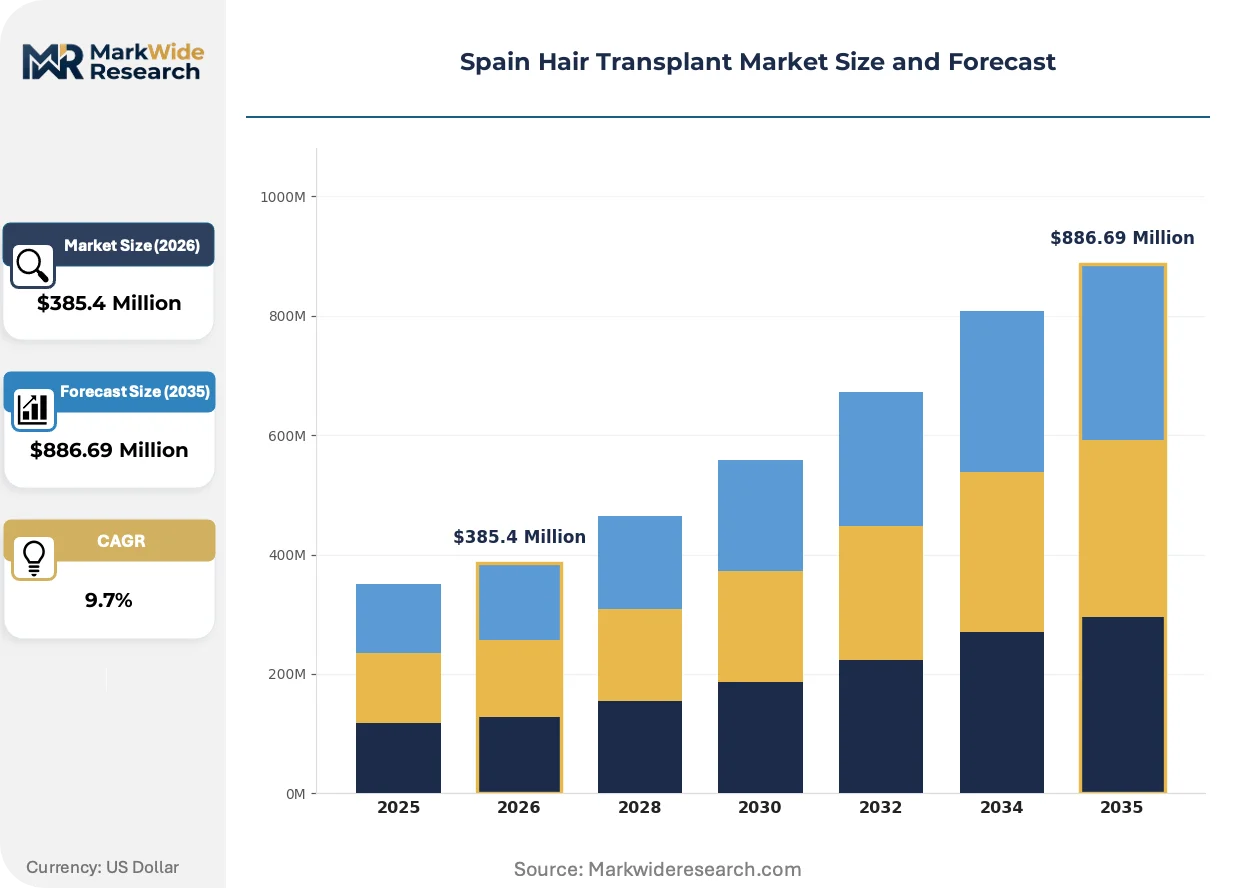
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: FUE, FUT, PRP, Scalp Micropigmentation Patient Type: Male, Female, Youth, Elderly Technology: Robotic Systems, Manual Tools, Laser Systems, Hybrid Techniques Clinic Type: Specialized Clinics, Hospitals, Dermatology Centers, Cosmetic Surgery Clinics |
| Companies Covered | HTI Clinic, Vinci Hair Clinic, Hospital Capilar, Insparya Hair Company, Instituto Medico Ricart, Centro Médico Teknon, Grupo Pedro Jaen, CapilClinic, Clínica de Freitas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Hair Transplant Market Trends and Innovations
Automation and algorithmic assistance are displacing manual extraction workflows across Spanish transplant centers while regulatory frameworks catch up to surgical AI deployment. These shifts are redrawing competitive boundaries between capital-heavy robotic operators and expertise-dependent manual specialists.
Robotic FUE platforms equipped with computer vision graft selection are converging with real-time scalp mapping analytics to reduce transection rates below 5%. Premium Madrid clinics are adopting these systems fastest, consolidating margin pools through precision positioning. The technology is compressing surgeon time-per-procedure while raising equipment depreciation burdens that favor scale operators.
Spain's autonomous communities are implementing the EU Medical Device Regulation's post-market surveillance requirements through enhanced tissue handling inspections. This regulatory friction is accelerating clinic consolidation as smaller operators surrender licenses rather than absorb compliance infrastructure costs. Andalusian networks are responding slowest, creating enforcement disparity risks.
Patient acquisition is migrating from dermatologist referrals toward Instagram and TikTok-native discovery channels. Specialized clinics are unbundling after-care from procedural pricing to compete on transparent cost comparison platforms. Barcelona operators show the sharpest channel pivot, with direct booking now exceeding 60% of new consults.
Spain Hair Transplant Market Segmentation
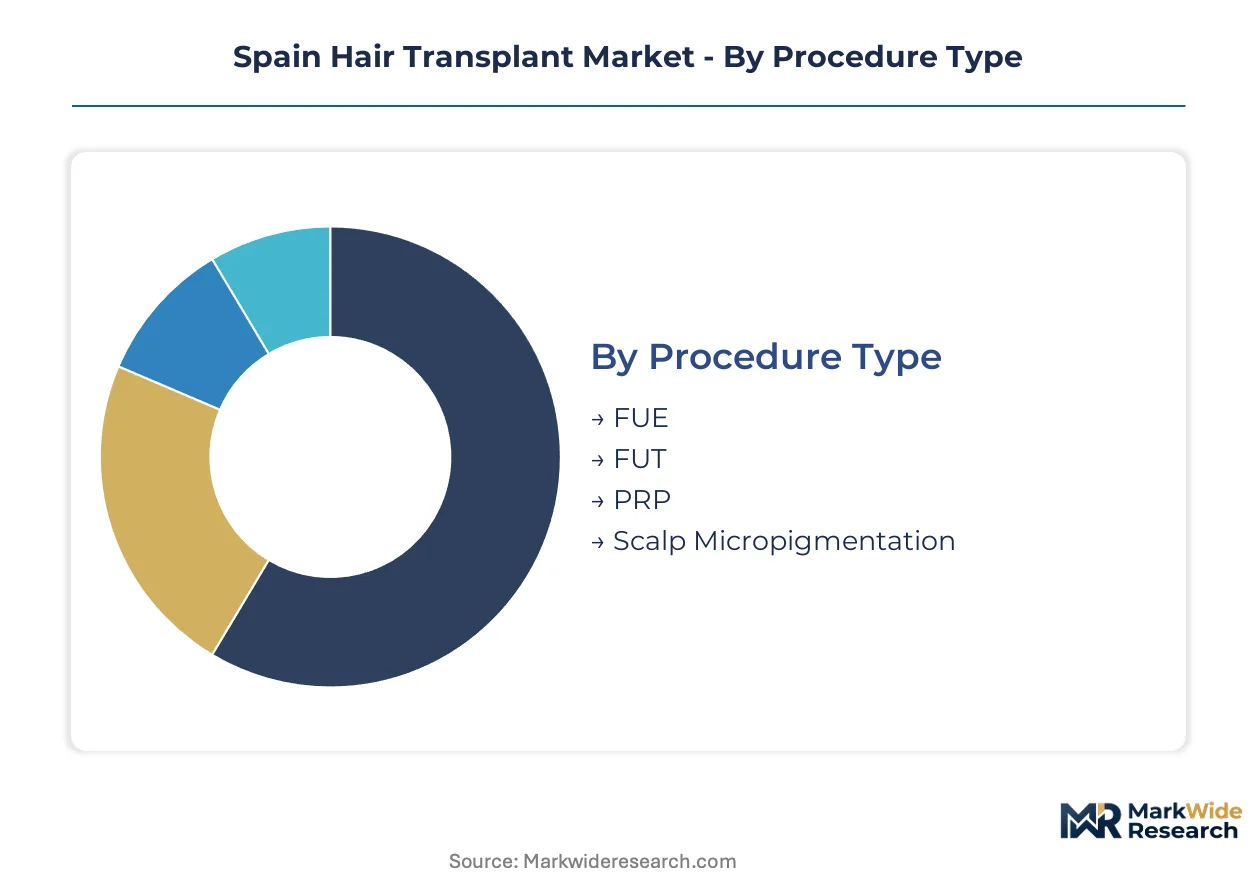
Procedural segmentation in Spain's transplant market determines capital allocation, surgeon training pathways, and regulatory compliance burdens. Each dimension—procedure type, patient demographics, technology tier, and clinic format—creates distinct margin profiles and competitive moats.
Procedure Type:
Supply-side expertise clusters around extraction methodologies, with Madrid and Barcelona clinics concentrating surgical training infrastructure.
- FUE:Follicular unit extraction employs 0.8-1.2mm punch diameters to harvest individual grafts from occipital donor zones without linear scarring. Madrid's dense dermatology corridor sustains the highest procedural volumes as male pattern baldness patients demand discrete recovery timelines.
- FUT:Follicular unit transplantation removes a strip of scalp tissue for dissection into grafts, yielding higher graft counts per session. Demand concentrates among patients with extensive baldness requiring maximum coverage, though strip scarring limits adoption in image-conscious segments.
- PRP:Platelet-rich plasma injections stimulate dormant follicles through autologous growth factor delivery. Barcelona operators integrate PRP as adjunct therapy to surgical procedures.
- Scalp Micropigmentation:Cosmetic tattooing creates the illusion of hair density through follicle-mimicking pigment deposits. Valencia clinics report rising consult volumes for non-surgical alternatives.
FUE absorbs the bulk of installed capacity; scalp micropigmentation is expanding most quickly.
Patient Type:
Cost tier stratification separates premium self-pay segments from price-sensitive demographics, reshaping clinic marketing spend allocation.
- Male:Androgenetic alopecia drives consult volumes across age cohorts, with peak demand among professionals aged 35-50 seeking career-adjacent appearance investment. Madrid's corporate density sustains premium pricing power.
- Female:Diffuse pattern hair loss and traction alopecia present diagnostic complexity requiring specialized trichoscopy protocols. Social stigma erosion is unlocking fastest consult growth in Barcelona's metropolitan zone.
- Youth:Early-onset hair loss patients under 30 demand conservative graft planning to preserve donor reserves for future procedures.
- Elderly:Patients over 65 present comorbidity screening requirements and reduced donor density, compressing graft yields per procedure.
Male patients absorb the bulk of installed capacity; female patients represent the steepest expansion trajectory.
Technology:
Application-specific precision requirements determine equipment procurement priorities across Spanish autonomous communities.
- Robotic Systems:Computer vision-guided platforms automate graft selection and extraction with sub-millimeter accuracy, reducing transection rates below 5%. Madrid's premium clinics deploy these systems to justify price premiums and compress surgeon time-per-procedure.
- Manual Tools:Handheld punch devices and forceps remain standard in mid-market segments, requiring intensive surgeon training but avoiding seven-figure capital outlays. Andalusian networks rely heavily on manual techniques due to equipment financing constraints.
- Laser Systems:Low-level laser therapy devices target follicle stimulation through photobiomodulation, typically deployed as maintenance therapy post-transplant.
- Hybrid Techniques:Combined robotic-manual workflows optimize cost-efficiency for high-volume operators, blending precision graft selection with manual placement.
Manual tools absorb the bulk of installed capacity; robotic systems are gaining share fastest.
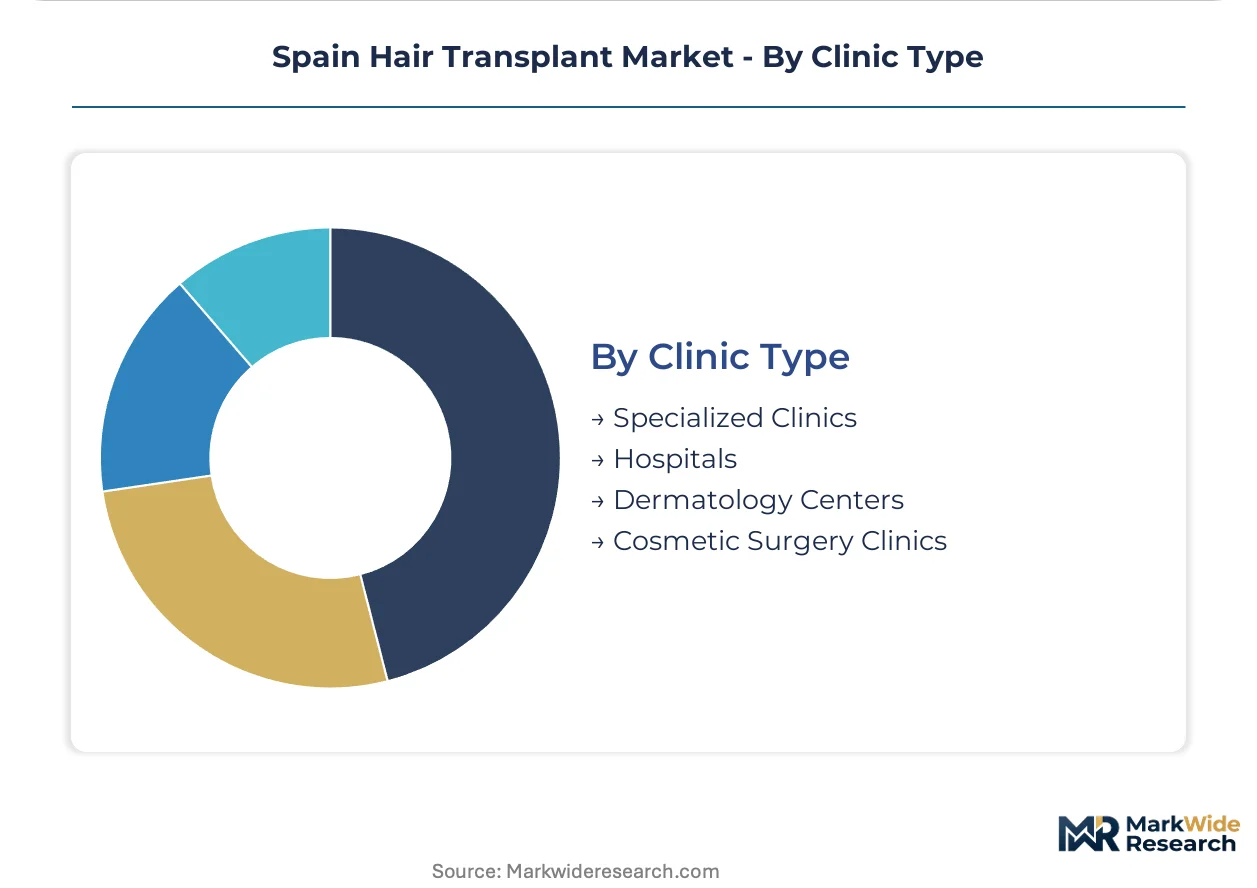
Clinic Type:
Margin concentration varies sharply by facility format, with specialized operators capturing disproportionate returns through repeat visit economics.
- Specialized Clinics:Dedicated transplant centers concentrate surgical expertise, graft processing labs, and after-care infrastructure under single ownership. Hospital Capilar's Madrid footprint exemplifies this model through in-house viability assessment capabilities.
- Hospitals:General medical facilities offer transplant services as cosmetic surgery line extensions, leveraging existing anesthesia and sterile processing infrastructure but lacking procedure-specific marketing expertise.
- Dermatology Centers:Skin health clinics integrate hair restoration into broader aesthetic portfolios, capturing referral synergies from acne and anti-aging patient bases.
- Cosmetic Surgery Clinics:Multi-procedure aesthetic practices bundle transplants with facial rejuvenation services, competing on convenience rather than surgical specialization.
Specialized clinics absorb the bulk of installed capacity; dermatology centers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's transplant demand clusters in metropolitan corridors where dermatology infrastructure and disposable income intersect. Madrid and Barcelona dominate procedural volumes, while southern and eastern autonomous communities present expansion frontiers with lower clinic density.
Madrid
Corporate professionals aged 35-50 drive consult volumes in Spain's capital, seeking career-adjacent appearance investment. The national pharmaceutical regulator inspects tissue handling compliance through Madrid's regional health service. HTI Clinic and Hospital Capilar anchor the dense dermatology corridor with in-house graft processing capabilities.
Catalonia
Barcelona's metropolitan zone records the fastest female patient segment growth as social stigma around hair loss erodes. The EU Medical Device Regulation mandates CE-marked surgical instruments and traceability protocols enforced by Catalan health authorities. Vinci Hair Clinic and Centro Médico Teknon concentrate expertise in the city's premium aesthetic corridor.
Andalusia
Transplant clinic density ratios run 40% below Madrid levels across Seville, Málaga, and Granada. Regional health services apply divergent accreditation standards that create compliance cost duplication for multi-site networks. Instituto Medico Ricart and Clínica de Freitas capture underserved demand through satellite positioning.
Valencia
The Mediterranean coastal zone shows rising scalp micropigmentation consult volumes for non-surgical alternatives. Autonomous community licensing fragmentation complicates sterile transport standards for multi-site graft logistics. CapilClinic and Grupo Pedro Jaen operate specialized centers targeting price-sensitive demographics.
Basque Country
Bilbao and San Sebastián sustain mid-market procedural demand through manual FUE techniques and hybrid robotic-manual workflows. Regional pharmaceutical inspectorates enforce EU AI Act readiness for autonomous surgical assistance tools. Insparya Hair Company competes via direct-to-consumer channels and celebrity-endorsed brand architecture.
Spain Hair Transplant Market Competitive Landscape
Equipment financing constraints and licensing scrutiny dominate the current landscape as Spanish transplant networks rebalance capital deployment. The vendor base concentrates around specialized clinics with captive graft processing labs, while general cosmetic surgery centers compete on convenience bundling. Three archetypes prevail: capital-heavy robotic operators, expertise-dependent manual specialists, and direct-to-consumer brand builders. M&A activity accelerates as smaller operators surrender licenses rather than absorb compliance infrastructure costs, while strategic partnerships with teleconsultation platforms reshape patient acquisition economics.
Among Madrid-based specialized operators, Hospital Capilar and HTI Clinic exemplify the integrated-lab archetype through in-house viability assessment capabilities. Insparya Hair Company occupies a distinct position as a direct-to-consumer brand builder leveraging celebrity endorsement architecture. These three anchors represent divergent strategic vectors: precision automation, surgical expertise concentration, and marketing-led patient acquisition.
| Leading Market Players |
|---|
| HTI Clinic |
| Vinci Hair Clinic |
| Hospital Capilar |
| Insparya Hair Company |
| Instituto Medico Ricart |
| Centro Médico Teknon |
| Grupo Pedro Jaen |
| CapilClinic |
| Clínica de Freitas |
| Others |
Pricing and Supply Chain Analysis
CE-marked surgical instruments flow from German and Italian manufacturers through Madrid's procurement networks, with robotic FUE platforms anchoring premium pricing tiers while manual punch devices sustain mid-market segments. This upstream equipment cost structure stratifies downstream service pricing across Spain's autonomous communities, compressing margins for operators locked into single-source vendor relationships.
Pricing Analysis
Volume concentration in manual FUE procedures splits margin pools from premium robotic workflows that command price premiums through precision positioning. Pricing stratifies across premium, standard, and economy tiers based on technology tier and surgeon certification level, with robotic-assisted procedures carrying equipment depreciation burdens that justify elevated positioning. Cost compression in the manual segment is intensifying as Andalusian clinics compete on transparent cost comparison platforms. Price-sensitive patients in Valencia and peripheral autonomous communities drive consult-to-procedure conversion through economy-tier positioning, while Madrid's corporate professionals absorb premium pricing with minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements for CE-marked surgical instruments now dominate procurement frameworks across Spanish transplant networks, with German, Italian, and South Korean manufacturers qualifying under EU Medical Device Regulation traceability protocols. Supply chains draw from precision-machined punch devices, optical guidance systems, and sterile graft storage media as critical component categories. Single-source vulnerability concentrates in robotic platform software licenses that tether operators to proprietary maintenance contracts. Distribution runs through specialized medical device distributors serving Madrid and Barcelona's dense dermatology corridors, with regional pharmaceutical inspectorates enforcing cold-chain compliance for multi-site graft logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's hair transplant sector sits in a technology-transition phase, with computer vision-guided robotic systems displacing manual extraction workflows and redrawing competitive boundaries between capital-heavy and expertise-dependent operators.
For Market Incumbents: Extend graft processing capabilities through in-house viability assessment labs that reduce per-procedure outsourcing costs and tighten quality control. Deepen backward integration into sterile transport infrastructure to navigate autonomous community licensing fragmentation that threatens multi-site expansion. Robotic platform vendors are consolidating maintenance contract pricing power, making captive technical expertise a defensive priority. For New Entrants and Emerging Players: Direct-to-consumer teleconsultation channels offer the most penetrable patient acquisition route, bypassing Madrid and Barcelona's saturated dermatologist referral networks. Target Andalusia and Valencia's 40% clinic density gap through satellite positioning that leverages lower real estate costs and lighter competitive pressure. Social media-native discovery platforms, particularly Instagram and TikTok, enable consult generation without legacy referral dependencies. For Investors and Strategic Acquirers: Clinic license surrender announcements in Andalusia are the leading indicator that EU Medical Device Regulation compliance costs are filtering market entry to well-capitalized operators. The 5-10 year viability window favors specialized clinic archetypes with captive graft processing labs over general cosmetic surgery centers competing on convenience bundling. Watch for enforcement disparity signals across Spain's 17 regional health services as early indicators of consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Platform Deployment | Computer vision-guided FUE systems reduce transection rates below 5% in Madrid premium clinics. |
| In-House Graft Processing Lab | Hospital Capilar's Madrid footprint demonstrates viability assessment capabilities that capture margin pools. |
| Direct-to-Consumer Teleconsultation | Virtual triage workflows compress patient acquisition costs outside traditional dermatologist referral channels. |
| EU AI Act Algorithmic Compliance | Early alignment with autonomous surgical assistance governance secures regulatory goodwill ahead of enforcement phase-in. |
| Regional Satellite Network Expansion | Andalusia and Valencia's underpenetration ratios present first-mover positioning for compliant multi-site operators. |
Research Methodology
Trade publications, EU Medical Device Regulation guidance documents, and autonomous community health service licensing records formed the secondary backbone, supplemented by customs data on surgical instrument imports. Primary interviews with transplant surgeons, clinic operations directors, biomedical equipment procurement managers, and regional pharmaceutical inspectorate officials validated procedural volume estimates and pricing tier assumptions. Bottom-up clinic capacity modeling and top-down autonomous community demand aggregation were cross-referenced to triangulate market sizing.
Bottom-up segmentation by procedure type, technology tier, patient demographic, and clinic format converged with top-down macroeconomic drivers across the projection horizon. Modeled dimensions included extraction methodology, equipment automation level, patient gender and age cohort, and facility specialization degree. CAGRs were derived from installed capacity expansion trajectories and consult-to-procedure conversion trend analysis, with graft yield per session and pricing tier mix serving as industry-specific sensitivity inputs.
The model holds under stable EU regulatory enforcement timelines and continued social stigma erosion for female pattern hair loss; deviation in autonomous community licensing harmonization or robotic platform import tariff shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
Inguinal Hernia Market