
 Asia Pacific Respiratory Therapeutic Devices Market | 2026-2036
Asia Pacific Respiratory Therapeutic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Respiratory Therapeutic Devices Market Outlook
Modular device bundling is hardening as the dominant procurement pattern across Asia Pacific hospital systems. ResMed Inc. leverages its integrated digital monitoring platforms to anchor long-term service contracts with Australian sleep clinics. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. dominates domestic Chinese tenders for portable oxygen concentrators through manufacturing scale that undercuts imported alternatives. Fisher & Paykel Healthcare Limited differentiates its humidification modules for CPAP devices across Southeast Asian homecare channels.
Respiratory therapeutic devices encompass mechanically or pneumatically powered instruments designed to deliver aerosolized medication, positive airway pressure, or supplemental oxygen at flow rates between 1-15 L/min, depending on clinical indication. These systems serve primarily to manage obstructive and restrictive pulmonary conditions across acute hospital wards and ambulatory settings. Inhalers and nebulizers retain the largest installed base across Asia Pacific, though margin pools are shifting toward smart inhalers where digital monitoring technology enables remote adherence tracking. CPAP devices face accelerating replacement cycles in Japan and South Korea as enhanced nebulization interfaces reduce mask intolerance rates among geriatric users.
Japan's PMDA enforces stringent clinical evidence requirements for software-enabled respiratory devices, while Australia's TGA mandates ISO 13485 quality system certification for all imported therapeutic goods. India's CDSCO has tightened medical device rules under the 2017 Medical Device Rules, creating compliance barriers for unregistered nebulizer and oxygen concentrator imports. Stakeholders must weigh regulatory pathway costs against the pricing power that certified digital monitoring capabilities confer in premium hospital segments.
Market Dynamics
Modular device bundling is hardening as the dominant procurement pattern across Asia Pacific hospital systems, compressing standalone device margins while expanding long-term service contract value pools for integrated platform providers.
Growth Catalysts
- Japan's Aging Demographics:Homecare settings across Japan are expanding device adoption as the geriatric population seeks chronic respiratory management outside hospitals, driving demand for portable oxygen concentrators and nebulizers.
- India's PLI Scheme:The Production Linked Incentive scheme for medical device manufacturing is reshaping local production economics, incentivizing domestic assembly of respiratory therapeutic devices and reducing import dependency.
- Smart Inhaler Technology:Digital monitoring capabilities enabling remote adherence tracking are pulling margin pools toward connected respiratory devices in premium hospital segments across the region.
Market Restraints
- Input Cost Volatility:Semiconductor shortages and polymer price fluctuations for device housings are squeezing manufacturing margins for portable oxygen concentrator producers.
- Regulatory Friction:India's CDSCO tightened medical device rules under the 2017 Medical Device Rules, creating compliance barriers for unregistered nebulizer and oxygen concentrator imports.
- Technical Limitation:Mask intolerance among geriatric CPAP users in Japan and South Korea accelerates replacement cycles but constrains device upgrade revenue timing.
Strategic Opportunities
- Underpenetrated Rural India:Tier-two and tier-three cities present white space for affordable nebulizer distribution through pharmacy-led channels outside hospital procurement systems.
- Australia's TGA Certification:ISO 13485 quality system certification for imported therapeutic goods creates a regulatory tailwind for certified digital monitoring capabilities in premium segments.
- Technology Convergence:Integration of humidification modules with CPAP devices is expanding into Southeast Asian homecare channels, differentiating service offerings beyond hardware sales.
Industry Challenges
- Certification Timeline Compression:Japan's PMDA enforces stringent clinical evidence requirements for software-enabled respiratory devices, extending time-to-market for digital health integrations.
- Supply Chain Reconfiguration:China's tier-one city hospital procurement budget concentration requires localized inventory positioning, fragmenting distribution networks across dispersed demand clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Respiratory Therapeutic Devices Market |
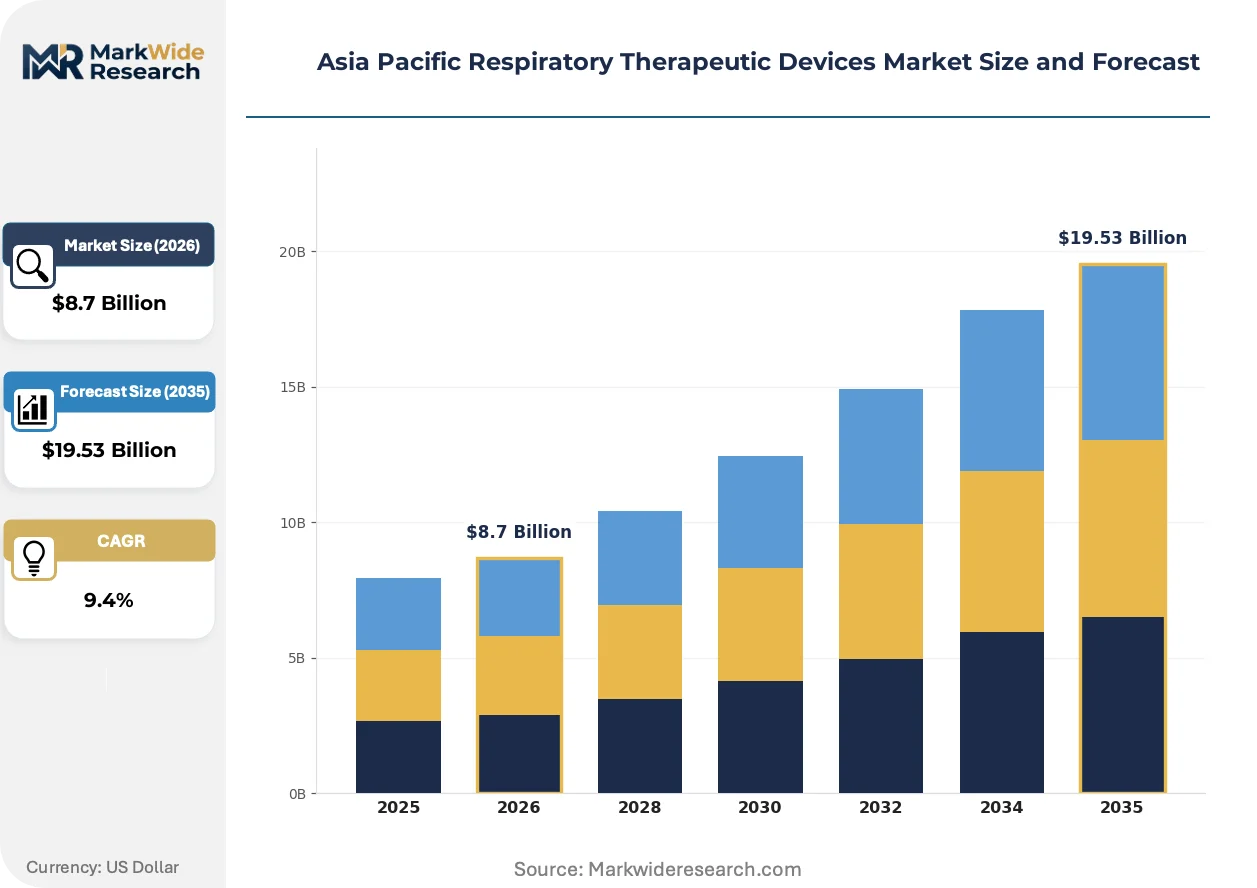
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Concentrators, CPAP Devices Delivery Mode: Metered Dose, Dry Powder, Continuous Flow, Pulsed Dose End User: Hospitals, Homecare Settings, Clinics, Rehabilitation Centers Technology: Digital Monitoring, Smart Inhalers, Enhanced Nebulization, Portable Devices |
| Companies Covered | GE Healthcare, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., ResMed Inc., Medtronic, Invacare Corporation, Koninklijke Philips N.V., Drägerwerk AG & Co. KGaA, Hamilton Medical, Fisher & Paykel Healthcare Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Respiratory Therapeutic Devices Market Strategic Shifts
Digital connectivity and service unbundling are actively reshaping competitive positioning in respiratory therapeutic devices, transforming hardware vendors into platform operators across Asia Pacific care settings.
Smart inhaler systems with embedded sensors and cloud-connected dose tracking are expanding into chronic obstructive pulmonary disease management protocols. Australian sleep clinics and Japanese respiratory wards are adopting these platforms at accelerating pace to reduce hospital readmission rates. The technology is expanding into long-term adherence monitoring contracts that capture recurring revenue streams beyond initial device sales.
Australia's TGA has tightened ISO 13485 enforcement for imported therapeutic goods, elevating quality system documentation requirements for nebulizer and oxygen concentrator manufacturers. This industrial consequence favors established suppliers with captive certification expertise over new market entrants. Southeast Asian distributors are responding by consolidating vendor relationships around pre-certified product portfolios to reduce compliance risk exposure.
Hospital procurement in China's tier-one cities is consolidating around multi-year service agreements that bundle device supply with maintenance and digital monitoring subscriptions. Traditional spot-purchase tenders for standalone nebulizers and oxygen concentrators are losing share to integrated platform contracts. This pattern is most visible in Shanghai and Beijing hospital networks, where procurement committees now weight total cost-of-ownership metrics above upfront capital expenditure.
Asia Pacific Respiratory Therapeutic Devices Market Segmentation
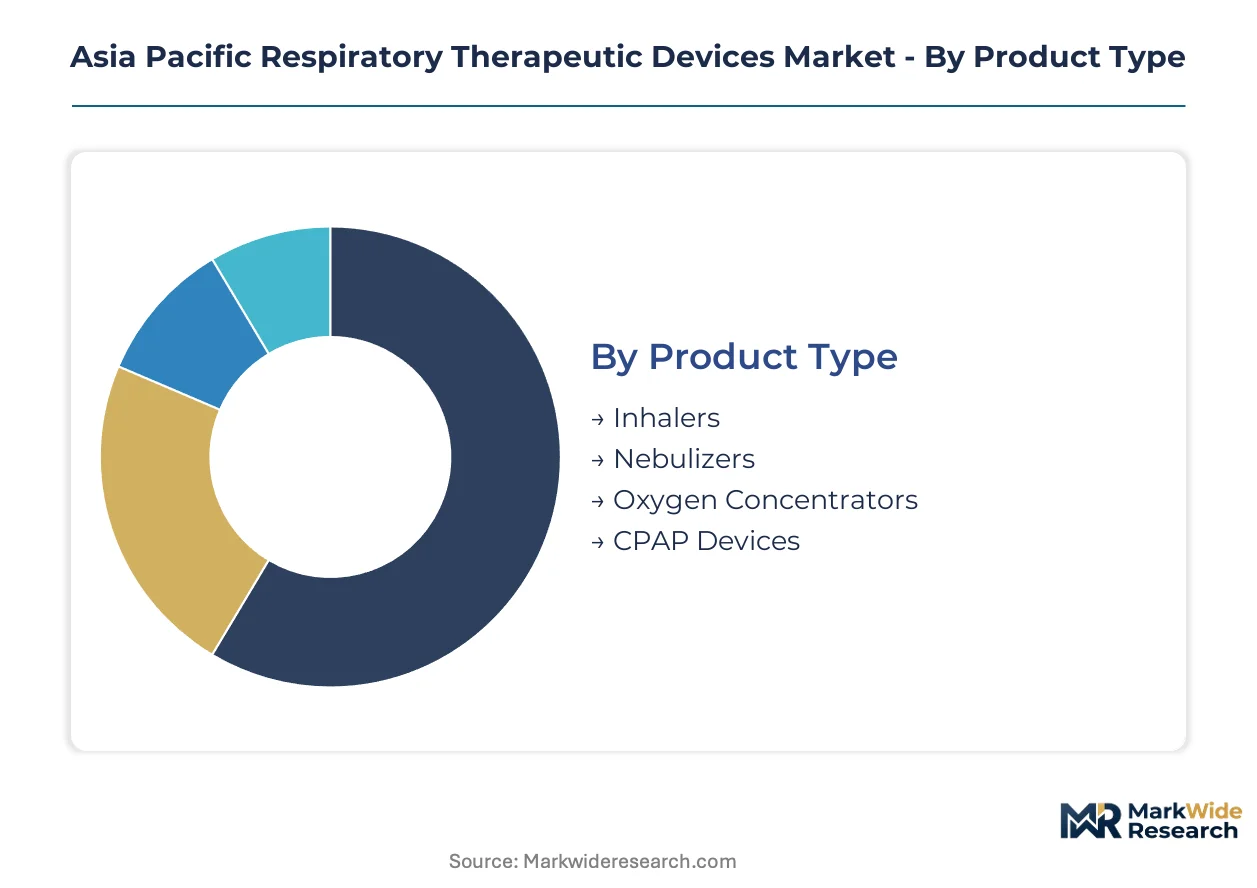
Segmentation in respiratory therapeutic devices reveals how procurement power concentrates across distinct technology tiers and care settings. Supply-side capabilities cluster around digital-enabled platforms while demand fragments across acute hospitals and dispersed homecare networks.
Product Type:
Manufacturing scale and regulatory certification intensity concentrate supply capacity unevenly across device categories.
- Inhalers:Pressurized canister and breath-actuated designs deliver bronchodilators and corticosteroids through portable handheld units. Demand concentrates in Japan's homecare channels where geriatric patients manage chronic obstructive pulmonary disease outside hospital wards, though polymer component costs squeeze margin pools for generic manufacturers.
- Nebulizers:Compressor-driven and ultrasonic systems convert liquid medication into respirable aerosol for patients unable to coordinate inhaler technique. China's tier-one city hospitals anchor procurement volume as respiratory wards upgrade to mesh nebulizers with reduced treatment times, while India's CDSCO registration requirements filter import competition.
- Oxygen Concentrators:Pressure swing adsorption technology separates nitrogen from ambient air to deliver 1-5 L/min continuous flow. Australian sleep clinics and Japanese homecare agencies drive replacement cycles as portable units displace stationary concentrators.
- CPAP Devices:Continuous positive airway pressure systems maintain patent airways in obstructive sleep apnea through mask-delivered airflow. Southeast Asian distributors bundle humidification modules to differentiate service contracts beyond hardware margins.
Today's leader: Inhalers. Tomorrow's challenger: Oxygen Concentrators.
Delivery Mode:
Clinical workflow efficiency and patient compliance rates diverge sharply across aerosol generation mechanisms.
- Metered Dose:Propellant-driven systems deliver fixed medication quantities through hand-breath coordination. Japanese respiratory wards favor these for acute exacerbation management where precise dosing protocols reduce readmission risk.
- Dry Powder:Breath-activated inhalation disperses micronized drug particles without propellant excipients. Australian homecare channels report higher adherence rates among elderly patients who struggle with hand-breath synchronization required by metered dose alternatives.
- Continuous Flow:Uninterrupted oxygen delivery at fixed liter-per-minute rates supports hypoxemic patients in stable condition. India's tier-two city clinics represent white space penetration opportunity as pharmacy-led distribution bypasses hospital procurement systems.
- Pulsed Dose:Breath-synchronized oxygen delivery conserves tank capacity and extends portable device runtime. South Korean manufacturers integrate these sensors into lightweight concentrators targeting mobile geriatric populations.
Continuous Flow commands current installed base. Pulsed Dose gains share fastest among portable device categories.
End User:
Budget authority and procurement sophistication fragment demand across institutional and consumer-directed channels.
- Hospitals:Acute care wards and respiratory departments deploy high-flow systems for critical intervention. Shanghai and Beijing procurement committees now weight total cost-of-ownership metrics above upfront capital expenditure in multi-year service agreements.
- Homecare Settings:Patient-directed environments in Japan and Australia drive demand for portable nebulizers and oxygen concentrators as aging populations seek chronic management outside institutional walls.
- Clinics:Outpatient respiratory facilities concentrate nebulizer utilization for acute exacerbation treatment. India's PLI scheme incentives reshape local production economics for device assembly serving this channel.
- Rehabilitation Centers:Post-acute recovery facilities deploy CPAP and oxygen therapy for pulmonary rehabilitation protocols. Australia's TGA ISO 13485 certification requirements elevate quality system documentation barriers for imported therapeutic goods.
Hospitals retain procurement volume concentration. Homecare Settings expand most quickly as reimbursement shifts favor ambulatory care.
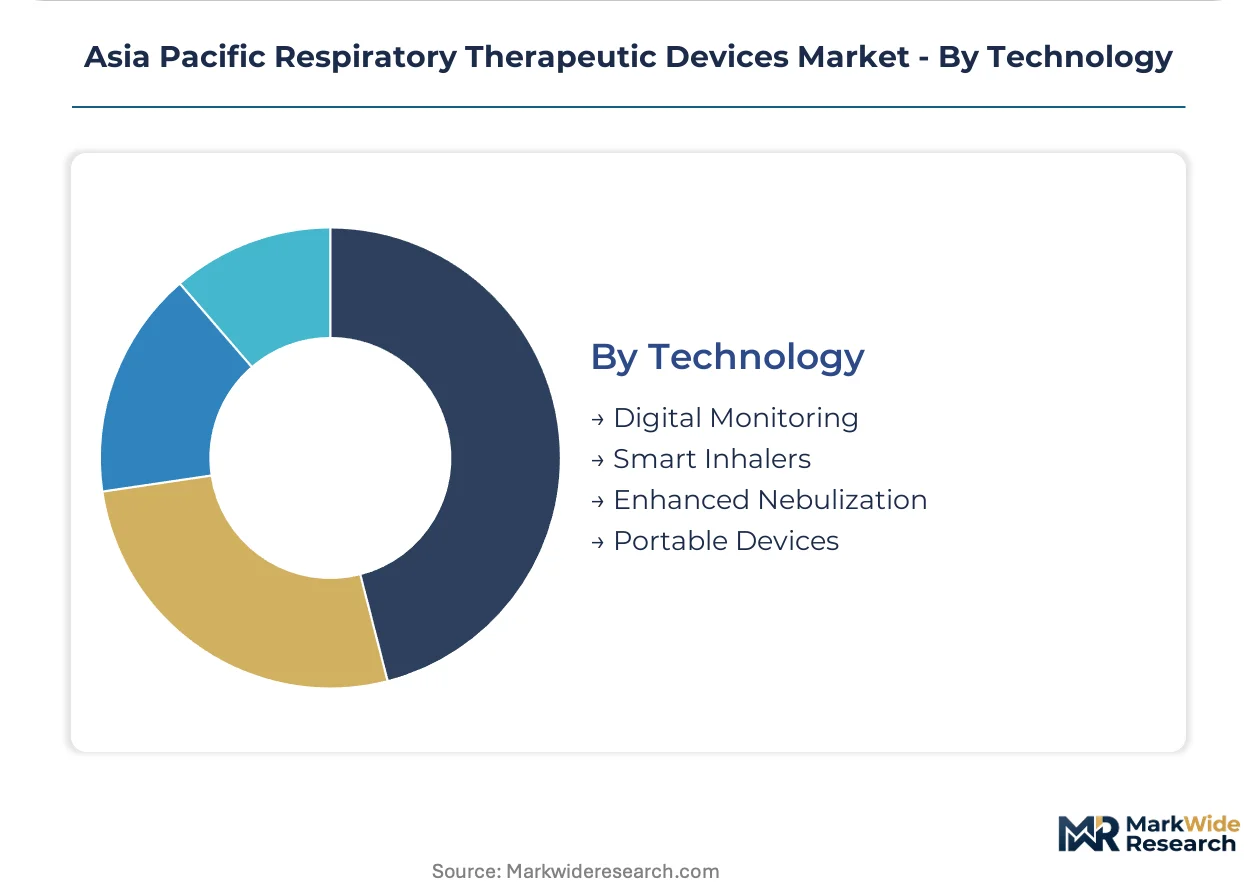
Technology:
Digital integration depth separates premium platform providers from commoditized hardware vendors.
- Digital Monitoring:Cloud-connected sensors track device utilization, adherence patterns, and clinical parameters for remote intervention. Australia's sleep clinics anchor adoption as reduced readmission rates justify subscription pricing models.
- Smart Inhalers:Embedded dose counters and Bluetooth connectivity enable medication tracking and physician alert protocols. Japan's PMDA enforces stringent clinical evidence requirements for software-enabled respiratory devices, extending time-to-market for new entrants.
- Enhanced Nebulization:Vibrating mesh and breath-enhanced aerosol generation reduce treatment duration and improve lung deposition. Southeast Asian distributors consolidate vendor relationships around pre-certified product portfolios to reduce compliance risk exposure.
- Portable Devices:Miniaturized compressor and battery systems enable ambulatory oxygen and nebulization therapy. Shenzhen manufacturing clusters exploit component scale advantages to undercut imported alternatives in domestic Chinese tenders.
Portable Devices dominate unit shipments. Smart Inhalers represent the steepest expansion trajectory as margin pools shift toward connected platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan incubated the modern respiratory device industry through post-war precision manufacturing clusters in the Kanto region. Australian homecare networks later commercialized portable oxygen therapy for dispersed rural populations. Today, manufacturing scale and regulatory certification intensity concentrate competitive advantage unevenly across four national markets.
Japan
Geriatric homecare agencies drive replacement cycles for portable oxygen concentrators as stationary units lose share. The PMDA enforces stringent clinical evidence requirements for software-enabled respiratory devices, extending approval timelines for digital health integrations. Tokyo and Osaka medical device clusters anchor production of nebulizers with enhanced nebulization interfaces that reduce mask intolerance among elderly CPAP users.
China
Hospital procurement committees in tier-one cities now weight total cost-of-ownership metrics above upfront capital expenditure in multi-year service agreements. The NMPA regulates medical device registration through Class II and III pathways that filter import competition for nebulizers and oxygen concentrators. Shenzhen manufacturing clusters exploit component scale advantages to undercut imported alternatives in domestic tenders for portable devices.
India
Pharmacy-led distribution channels in tier-two and tier-three cities present white space for affordable nebulizer penetration outside hospital procurement systems. The CDSCO tightened medical device rules under the 2017 Medical Device Rules, creating compliance barriers for unregistered oxygen concentrator imports. The PLI scheme for medical device manufacturing reshapes local production economics for device assembly serving outpatient respiratory clinics.
Australia
Sleep clinics anchor adoption of cloud-connected dose tracking platforms as reduced readmission rates justify subscription pricing models. The TGA mandates ISO 13485 quality system certification for all imported therapeutic goods, elevating documentation barriers for nebulizer and oxygen concentrator manufacturers. Melbourne and Sydney medical device distributors consolidate vendor relationships around pre-certified product portfolios to reduce compliance risk exposure.
South Korea
Lightweight concentrator manufacturers integrate breath-synchronized sensors targeting mobile geriatric populations with pulsed dose oxygen delivery. The MFDS regulates software-enabled medical devices through clinical trial requirements that parallel Japan's evidence standards. Seoul-based fabricators compete on miniaturized compressor and battery systems for ambulatory therapy devices.
Asia Pacific Respiratory Therapeutic Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across digital integration depth, with certified platform providers capturing recurring service revenue while hardware-only vendors compete on manufacturing scale. The vendor base stratifies into three tiers: integrated digital health platforms, specialized respiratory device manufacturers, and contract assemblers serving price-sensitive procurement channels. Dominant competitive moves include strategic partnerships for regulatory certification acceleration and geographic expansion through distributor consolidation in Southeast Asian markets.
Among diversified healthcare conglomerates, GE Healthcare and Medtronic occupy positions that span acute care systems and ambulatory channels across multiple Asia Pacific markets. ResMed Inc. exemplifies the platform-operator archetype through its integrated digital monitoring capabilities that anchor long-term service contracts. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the scale-driven domestic champion model, leveraging manufacturing concentration to dominate tenders within its home market.
| Leading Market Players |
|---|
| GE Healthcare |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| ResMed Inc. |
| Medtronic |
| Invacare Corporation |
| Koninklijke Philips N.V. |
| Drägerwerk AG & Co. KGaA |
| Hamilton Medical |
| Fisher & Paykel Healthcare Limited |
| Others |
Value Chain & Pricing Dynamics
Precision engineering talent concentration in Japan's Kanto region and Shenzhen's electronics manufacturing workforce anchor labor-cost differentials that widen pricing-tier spreads between premium digital platforms and economy hardware alternatives. Component sourcing from these clusters feeds into three-tier pricing structures across the Asia Pacific respiratory device landscape.
Pricing Analysis
Multi-year service agreements bundling device supply with maintenance and digital monitoring subscriptions now dominate hospital procurement in China's tier-one cities. Price differentiation rests on ISO 13485 certification grade and after-sales service bundling depth. Cost compression in economy nebulizer tiers is intensifying because Shenzhen manufacturing clusters exploit component scale advantages to undercut imported alternatives. Pharmacy-led distribution channels in India's tier-two cities exhibit highest price sensitivity, while Australian sleep clinics show lowest sensitivity due to subscription pricing model acceptance.
Supply Chain Analysis
Workforce availability in precision electronics manufacturing concentrates supply capacity across China, Japan, and South Korea. Semiconductor components for digital monitoring platforms, polymer housings for portable devices, and pressure swing adsorption materials for oxygen concentrators draw from these geographies. Single-source vulnerability in semiconductor inputs creates structural risk exposure for smart inhaler manufacturers. Distribution runs through hospital procurement committees in tier-one cities, pharmacy-led channels in rural India, and sleep clinic networks in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific respiratory therapeutic device market functions as a regulatory compounder where India's 2017 Medical Device Rules and Japan's PMDA software-enabled device requirements continuously elevate compliance barriers that favor certified incumbents.
For Market Incumbents: Lock in long-term service contracts with Australian sleep clinics and Japanese homecare agencies before emerging platform operators achieve regulatory certification. Invest in backward integration into semiconductor component supply to offset input cost volatility threatening portable oxygen concentrator margins. Prioritize ISO 13485 certification maintenance as India's CDSCO tightens import registration requirements. For New Entrants and Emerging Players: Capture white-space opportunity in India's tier-two and tier-three pharmacy-led distribution channels where hospital procurement systems do not dominate. Target affordable nebulizer penetration outside certified hospital networks as the most penetrable segment. Pursue distributor consolidation partnerships in Southeast Asian markets to bypass direct regulatory compliance investments. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with captive regulatory affairs capabilities are the most active acquirer in this space, seeking digital monitoring platform assets. Five-to-ten year viability favors integrated service contract providers over hardware-only vendors. Watch Japan's PMDA approval timelines for software-enabled respiratory devices as the inflection indicator for platform operator valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software Certification Pathway | Japan's stringent clinical evidence requirements extend time-to-market for digital health integrations. |
| Hospital System Partnership | Shanghai and Beijing procurement committees now weight total cost-of-ownership above upfront capital expenditure. |
| Software Companion Development | Cloud-connected dose tracking platforms anchor recurring revenue streams beyond initial device sales. |
| Reimbursement Strategy | Australian sleep clinic adoption of subscription pricing models depends on reduced readmission rate justification. |
| CE Marking Pathway | Southeast Asian distributors consolidate vendor relationships around pre-certified product portfolios to reduce compliance risk. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and respiratory clinic directors combined with secondary validation from CDSCO registration databases, PMDA approval filings, TGA certification records, and NMPA Class II/III pathway documentation. Cross-referencing bottom-up demand signals against top-down supply capacity estimates enables triangulation.
Historical trendline analysis of device replacement cycles and procurement contract structures informs projection modeling across product type, delivery mode, end user, and technology segmentation dimensions. CAGRs derive from fitted growth curves applied to certified versus uncertified device category splits. Forecast inputs incorporate PLI scheme incentive trajectories in India and tier-one city hospital budget concentration patterns in China.
Regulatory timeline delays, semiconductor supply disruptions, and reimbursement policy shifts are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about certification pathway efficiency and procurement pattern continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Human Respiratory Syncytial Virus (RSV) Treatment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market