
 Mesenteric Penniculitis Treatment Market | 2026-2036
Mesenteric Penniculitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mesenteric Penniculitis Treatment Market Foresight
Biologic agents are expanding their role in mesenteric panniculitis management as corticosteroid-sparing alternatives reshape therapeutic economics. Novartis leverages its immunology pipeline depth to sustain development of targeted cytokine inhibitors for refractory cases. Pfizer anchors its position through broad-spectrum anti-inflammatory platforms that compete across autoimmune and fibro-inflammatory indications. AbbVie differentiates via its established gastroenterology franchise and channel control within academic medical centers.
Mesenteric panniculitis treatment encompasses pharmacological and surgical interventions directed at a rare inflammatory-fibrotic disorder of the mesenteric adipose tissue, characterized by fat necrosis, chronic inflammation, and progressive sclerosis that compromises intestinal vascular supply and lymphatic drainage. The primary purpose is symptom palliation, complication prevention, and halting fibrotic progression that leads to bowel obstruction or ischemia. Medication modalities including corticosteroids and antimicrobial agents dominate current prescribing patterns due to established efficacy profiles and broad availability, while intravenous delivery modes capture premium margin pools in acute episode management where rapid immunosuppression is clinically necessary. Chronic management applications within hospital settings represent the most mature revenue segment, whereas ambulatory surgical centers are emerging as faster-growing channels for diagnostic laparoscopy and biopsy.
FDA orphan drug regulations incentivize manufacturers to pursue indications for mesenteric panniculitis despite small patient populations, while EMA's parallel designation framework shapes European development priorities and reimbursement negotiations. The WHO's International Classification of Diseases coding updates for rare fibro-inflammatory disorders influence diagnostic documentation standards and epidemiological tracking capabilities. Stakeholders must monitor evolving biologics reimbursement policies and prioritize evidence generation for corticosteroid-refractory patient stratification.
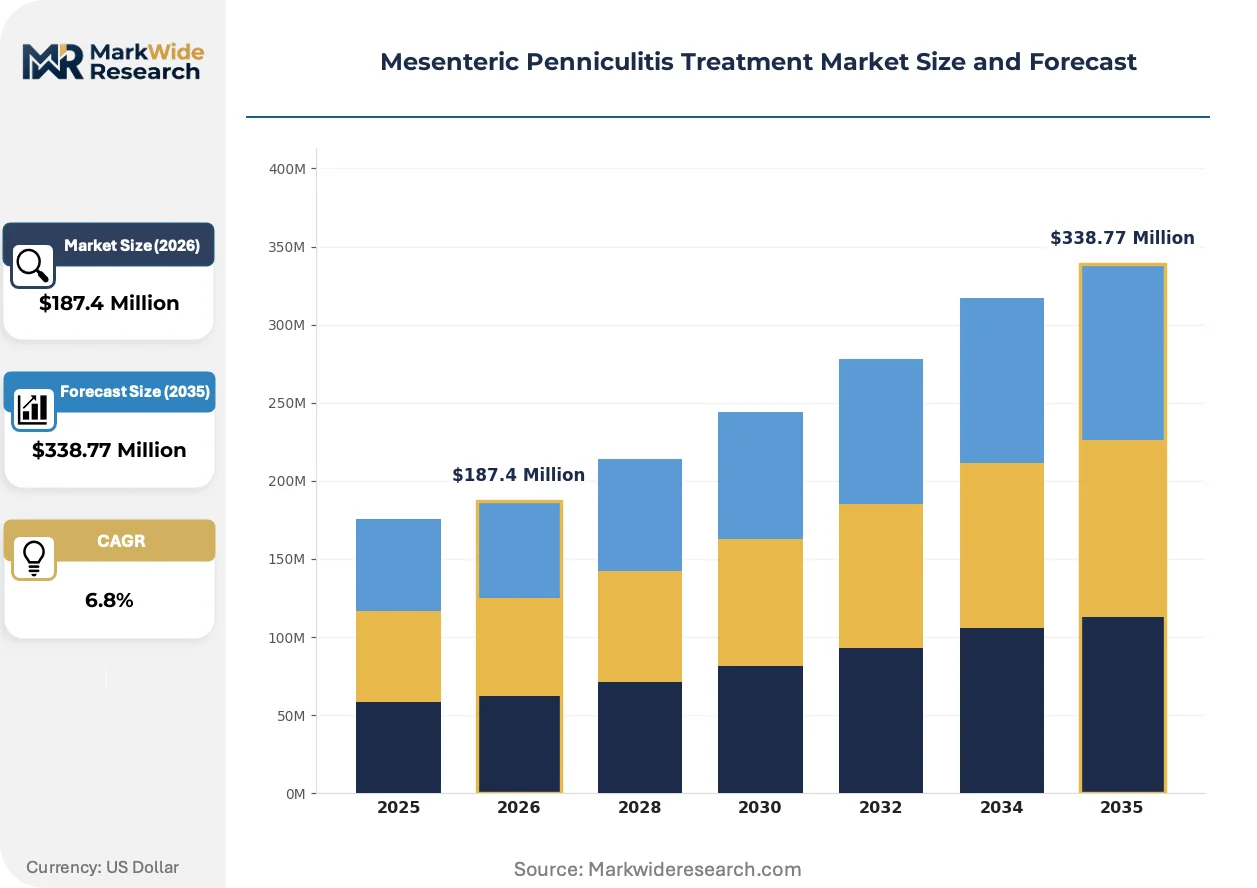
Market Dynamics
Orphan drug economics are restructuring competitive incentives in mesenteric panniculitis therapeutics, as extended exclusivity periods and tax credits offset small addressable populations and attract biologics developers into previously neglected inflammatory-fibrotic indications.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits for clinical trials and seven-year market exclusivity reduce development risk for biologics targeting corticosteroid-refractory patient subsets. Academic medical centers in the United States are prioritizing these protocols.
- Diagnostic Imaging Advances:Contrast-enhanced CT protocols and PET-CT hybrid systems are shortening time-to-diagnosis from months to weeks. Tertiary hospitals are embedding these capabilities within gastroenterology departments.
- Biopsy Channel Expansion:Ambulatory surgical centers are adding laparoscopic mesenteric biopsy capacity to capture referral flows from community gastroenterology practices. This infrastructure buildout extends treatment access beyond academic centers.
Market Restraints
- Plasma-Derived Biologics Input Costs:Immunoglobulin and albumin price volatility compress margins for manufacturers dependent on fractionation supply chains. European plasma collection constraints amplify this pressure.
- Single-Site Production Concentration:Fill-finish capacity for sterile biologics concentrates in contract manufacturers clustered in Switzerland and Germany. Any regulatory action at these sites disrupts global supply.
- Corticosteroid Substitution Threat:Low-cost prednisone and methylprednisolone remain first-line despite toxicity profiles. Payers in public health systems enforce step-therapy protocols that delay biologic access.
Strategic Opportunities
- Brazilian Rare Disease Framework:ANVISA's accelerated pathway for orphan indications opens Latin America's largest market to developers with existing FDA or EMA approvals. Local partnership requirements favor joint-venture structures.
- Companion Diagnostic Convergence:Biomarker stratification for fibrotic progression risk is converging with therapeutic development. Diagnostic-therapeutic bundles command premium reimbursement in German sickness funds.
- Telemedicine Referral Networks:Virtual second-opinion platforms connect community hospitals to academic mesenteric disease specialists. United States-based networks are expanding into Canadian provincial health systems.
Industry Challenges
- Interventional Radiology Skill Scarcity:Percutaneous mesenteric biopsy and drainage procedures require cross-trained specialists. Fellowship programs in the United States graduate fewer than fifty qualified practitioners annually.
- EMA Paediatric Investigation Plan Complexity:Mandatory pediatric study requirements for novel biologics impose timeline extensions despite the condition's adult-onset epidemiology. Waivers require extensive justification.
- Real-World Evidence Collection Infrastructure:Patient registry participation rates lag targets due to fragmented electronic health record systems across hospital networks. Data quality inconsistencies undermine payer negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesenteric Penniculitis Treatment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Medication, Steroids, Antimicrobial Agents End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Delivery Mode: Intravenous, Oral, Injectable, Topical Application: Chronic Management, Acute Episodes, Post-Surgical Recovery, Preventive Care |
| Companies Covered | Novartis, AstraZeneca, Merck & Co., Pfizer, AbbVie, Johnson & Johnson, Roche, Sanofi, GSK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesenteric Penniculitis Treatment Market Shifts & Advancements
Therapeutic development in mesenteric panniculitis is pivoting from broad immunosuppression toward targeted cytokine modulation, with diagnostic and treatment modalities advancing in parallel rather than sequentially.
IL-6 pathway inhibition is converging with JAK-STAT signal blockade in next-generation biologic design. Gastroenterology departments at Cleveland Clinic and Mayo Clinic are early-adopting these combinations for steroid-dependent patients. This convergence is compressing development timelines as manufacturers pursue dual-mechanism approvals under single orphan designations.
EMA's updated guidance on extrapolation of efficacy data for rare fibro-inflammatory disorders reduces redundant trial requirements for second indications. Manufacturers with existing spondyloarthritis approvals are leveraging this to fast-track mesenteric panniculitis labels. German and French reimbursement bodies are accepting these extrapolated packages with post-market confirmatory study commitments.
Academic medical centers are unbundling diagnostic workup from therapeutic management, creating distinct revenue streams for specialized pathology interpretation. Community hospitals in the United States are outsourcing mesenteric biopsy reads to centralized digital pathology platforms. This disintermediation is most visible in the southeastern United States, where rural hospital systems lack on-site gastrointestinal pathology expertise.
Mesenteric Penniculitis Treatment Market Segmentation
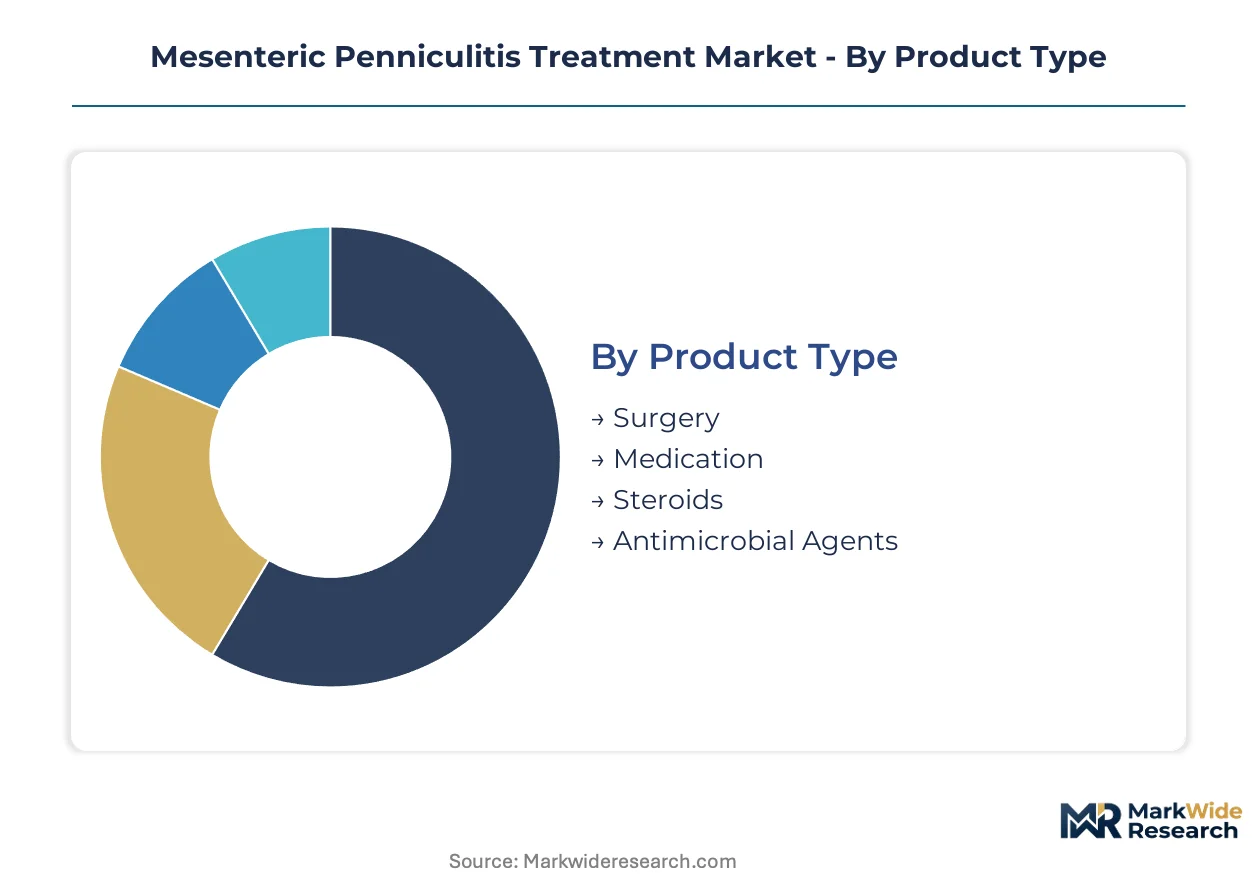
Mesenteric panniculitis treatment modalities span standalone interventions and integrated care pathways that combine diagnostic confirmation with therapeutic escalation. Segment boundaries blur as tertiary hospitals bundle biopsy, imaging, and biologic initiation into single-episode protocols.
Product Type:
Standalone surgical intervention dominates acute complication management, while embedded pharmaceutical protocols govern chronic disease modification and corticosteroid-sparing strategies.
- Surgery:Laparoscopic mesenteric biopsy and bowel resection address fibrotic stricture or ischemic complications. Demand clusters at Cleveland Clinic and Mayo Clinic where interventional gastroenterology fellowship programs feed specialized capacity. Reimbursement complexity limits community hospital adoption despite proven efficacy for refractory obstruction.
- Medication:Systemic immunosuppressants and targeted biologics form the backbone of chronic management. Prescribing concentrates within United States academic medical centers where orphan drug access programs bridge payer gaps. Novartis and AbbVie channel resources into these sites for corticosteroid-refractory patient identification.
- Steroids:Prednisone and methylprednisolone remain first-line for initial inflammatory control due to rapid onset and universal formulary inclusion.
- Antimicrobial Agents:Tetracycline derivatives and metronidazole address infectious mimics and secondary bacterial complications in diagnostic uncertainty.
Surgery leads volumes today; medication is gaining share fastest as biologics expand their labeled indications.
End User:
Cost tier stratification separates capital-intensive inpatient centers from ambulatory facilities competing on episode price and throughput efficiency.
- Hospitals:Tertiary academic centers command premium reimbursement for complex mesenteric resections and biologic infusion suites. United States-based institutions anchor referral networks that capture interstate patient transfers. Infrastructure requirements including PET-CT hybrid imaging and specialized pathology create natural moats against lower-tier competition.
- Ambulatory Surgical Centers:Diagnostic laparoscopy and biopsy are migrating to outpatient settings where facility fees run 40-60% below hospital-based equivalents. Southeastern United States markets show fastest ASC penetration as certificate-of-need restrictions ease. These centers partner with digital pathology platforms to overcome on-site expertise gaps.
- Clinics:Community gastroenterology practices serve as gatekeepers for specialist referral and chronic medication monitoring.
- Research Institutions:NIH-funded centers and European Reference Networks generate natural history data that shapes regulatory approval packages.
Hospitals lead volumes today; ambulatory surgical centers are expanding most quickly as site-of-service economics reshape referral patterns.
Delivery Mode:
Margin concentration follows administration complexity, with parenteral routes capturing value from clinical urgency and monitoring requirements.
- Intravenous:Biologic infusions and high-dose corticosteroid pulses require supervised administration in infusion centers. United States hospital outpatient departments defend this revenue stream against freestanding competitor entry. FDA REMS programs for certain immunosuppressants reinforce site-of-care requirements.
- Oral:Maintenance corticosteroids and immunomodulators dominate prescription volume through retail pharmacy channels. Step-therapy protocols in Medicare Part D and commercial plans delay biologic access, extending oral agent commercial life.
- Injectable:Subcutaneous biologics are penetrating maintenance therapy as patient self-administration programs reduce infusion center dependency.
- Topical:Limited applicability given mesenteric anatomical location; experimental formulations target adjacent cutaneous manifestations.
Oral delivery leads volumes today; intravenous maintains premium positioning despite injectable encroachment.
Application:
Patient stratification by disease trajectory determines intervention intensity, with acute episodes commanding episodic premium pricing against chronic management's subscription-like revenue streams.
- Chronic Management:Long-term immunosuppression and surveillance imaging constitute the most mature revenue segment. German sickness funds and United States Medicare Advantage plans are piloting episode-based payments for stable patients. Biomarker stratification for fibrotic progression risk is converging with therapeutic selection in academic protocols.
- Acute Episodes:Bowel obstruction, ischemia, or sepsis trigger emergency surgical intervention and intensive care utilization. These episodes generate 3-5x per-patient revenue versus chronic management but occur unpredictably. Tertiary hospitals maintain dedicated acute mesenteric ischemia protocols to capture these high-acuity transfers.
- Post-Surgical Recovery:Adjunctive immunosuppression prevents recurrence following resection of fibrotic strictures.
- Preventive Care:Early intervention in subclinical radiographic findings remains investigational with limited reimbursement coverage.
Chronic management leads volumes today; acute episodes show steepest expansion trajectory as diagnostic imaging identifies more incident cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers anchor the mesenteric panniculitis treatment landscape through specialized referral networks and orphan drug access infrastructure that concentrates advanced therapeutic protocols.
United States
Cleveland Clinic and Mayo Clinic gastroenterology departments drive demand for biologic infusion suites and diagnostic laparoscopy. FDA orphan drug tax credits and seven-year exclusivity provisions incentivize Novartis and AbbVie to prioritize corticosteroid-refractory patient trials. The southeastern United States shows fastest ambulatory surgical center penetration as certificate-of-need restrictions ease and rural hospitals outsource pathology reads to digital platforms.
Germany
German sickness funds pilot episode-based payments for stable chronic management patients while accepting EMA extrapolated efficacy packages for biologics with post-market confirmatory commitments. EMA's updated guidance on rare fibro-inflammatory disorder data extrapolation reduces redundant trial requirements for manufacturers holding existing spondyloarthritis approvals. The Rhine-Ruhr metropolitan region concentrates specialized interventional radiology capacity for percutaneous mesenteric procedures.
United Kingdom
NHS England's specialized commissioning frameworks for rare diseases channel mesenteric panniculitis cases toward designated tertiary centers with PET-CT hybrid imaging capabilities. MHRA recognition of FDA orphan drug approvals accelerates market access timelines for biologics already cleared in the United States. London's academic hospital networks generate natural history data that shapes regulatory approval packages for emerging cytokine inhibitors.
Brazil
ANVISA's accelerated pathway for orphan indications opens Latin America's largest market to developers with existing FDA or EMA approvals, though local partnership requirements favor joint-venture structures. Diagnostic imaging infrastructure gaps in northern states delay time-to-diagnosis versus southern metropolitan regions. São Paulo's private hospital networks are building biologic infusion capacity to capture affluent patient segments seeking corticosteroid-sparing alternatives.
Japan
PMDA's Sakigake designation system fast-tracks review for biologics addressing unmet needs in fibro-inflammatory conditions with limited treatment options. METI funding for rare disease research infrastructure supports academic consortia generating epidemiological data on adult-onset mesenteric disorders. The Kanto region surrounding Tokyo concentrates the nation's interventional gastroenterology fellowship programs and specialized biopsy capacity.
Mesenteric Penniculitis Treatment Market Competitive Landscape
Global majors compete with regional champions across biologics development and specialized diagnostic service delivery, producing a tiered structure where scale-driven pharmaceutical conglomerates anchor premium therapeutic segments while regional hospital networks defend procedure-based revenue streams. Market structure consolidates around three strategic archetypes: immunology-focused biologics developers with gastroenterology franchise depth, broad-spectrum anti-inflammatory platform holders, and academic medical center systems with captive referral networks. Dominant competitive moves include strategic partnerships between biologics manufacturers and diagnostic platform developers, plus geographic expansion of telemedicine second-opinion networks into adjacent national health systems.
Among global biologics developers, Novartis, Pfizer, and AbbVie occupy positions exemplifying distinct competitive archetypes within the mesenteric panniculitis treatment space. Novartis represents the immunology pipeline depth model with targeted cytokine inhibitor development for refractory cases. Pfizer anchors the broad-spectrum anti-inflammatory platform approach that competes across autoimmune and fibro-inflammatory indications. AbbVie sits within the gastroenterology franchise control archetype, leveraging established channel relationships within academic medical centers for corticosteroid-refractory patient identification and access program navigation.
| Leading Market Players |
|---|
| Novartis |
| AstraZeneca |
| Merck & Co. |
| Pfizer |
| AbbVie |
| Johnson & Johnson |
| Roche |
| Sanofi |
| GSK |
| Others |
Supply & Pricing Matrix
Step-therapy protocols enforced by United States Medicare Advantage plans and German sickness funds are forcing biologics manufacturers to absorb higher patient access program costs, which compresses net realized prices and pushes supply chain investment toward centralized infusion center networks where site-of-service economics can be optimized.
Pricing Analysis
Plasma-derived input cost pass-through dominates biologic pricing dynamics, with immunoglobulin and albumin fractionation volatility compressing manufacturer margins unevenly across product tiers. Three-tier pricing structure across premium cytokine inhibitors, standard synthetic immunosuppressants, and economy corticosteroid generics reflects reimbursement tiering rather than manufacturing cost. Pricing pressure stems from prednisone substitution in public health systems. Community hospital formularies show highest price sensitivity; academic medical centers with orphan drug access programs demonstrate lowest.
Supply Chain Analysis
Direct-to-hospital channels handle biologic demand from Cleveland Clinic and Mayo Clinic referral networks, while specialty distributors serve ambulatory surgical center expansion. Fill-finish capacity concentrates in Switzerland and Germany, with active pharmaceutical ingredient sourcing drawing from United States, Ireland, and Singapore plasma collection networks. Single-site regulatory vulnerability at Swiss-German contract manufacturers represents the dominant structural risk. Distribution runs through cold-chain logistics partners with REMS-certified handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in mesenteric panniculitis therapeutics rests on corticosteroid-sparing protocol adoption accelerating biologic penetration into previously prednisone-dependent patient flows.
For Market Incumbents: Anticipate biosimilar entry pressure in the IL-6 inhibitor class by deepening captive supply of plasma-derived inputs through backward integration into United States fractionation networks. Defend channel position by embedding diagnostic-therapeutic bundles within German sickness fund episode-based payment pilots before competitors establish formulary anchoring. For New Entrants and Emerging Players: Telemedicine second-opinion platforms offer the lowest-friction entry vector for connecting community gastroenterology practices to academic mesenteric disease specialists. Target southeastern United States ambulatory surgical centers where certificate-of-need deregulation is fastest and digital pathology partnerships can overcome on-site expertise gaps without capital-intensive buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with diagnostic platform developers possessing validated biomarker stratification for fibrotic progression risk, as therapeutic-diagnostic convergence accelerates reimbursement premium capture. Long-term viability hinges on EMA extrapolation pathway utilization and post-market confirmatory study execution. Watch for ANVISA accelerated pathway approvals as inflection signals for Latin American market opening.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and exclusivity reduce development risk for corticosteroid-refractory indications. |
| Companion Diagnostic Development | Biomarker stratification enables premium reimbursement in German sickness fund episode-based pilots. |
| Telemedicine Network Expansion | Virtual second-opinion platforms capture referral flows from underserved rural hospital systems. |
| Ambulatory Surgical Center Partnership | Outpatient biopsy capacity extends geographic reach beyond academic medical center catchment areas. |
| Plasma Supply Integration | Captive fractionation capacity insulates margins against immunoglobulin input price volatility. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down biologics manufacturer shipment tracking forms the analytical core. Primary interviews with gastroenterology department heads, formulary directors at academic medical centers, payer access specialists, and interventional radiology fellowship program directors combined with secondary validation from FDA orphan drug designations, EMA submissions, ClinicalTrials.gov entries, and CMS Medicare Part D formulary databases. Triangulation between demand-side prescribing patterns and supply-side production disclosures ensures coverage integrity.
Input-output matrix framing connects patient incidence assumptions through treatment line penetration rates to biologic volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, application trajectory, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to historical orphan drug adoption patterns, with plasma collection capacity constraints and diagnostic imaging infrastructure buildout serving as industry-specific forecast boundary conditions.
The model assumes a particular technology adoption path; alternative pathways for subcutaneous self-administered biologics would alter the outlook if patient self-injection programs achieve faster penetration than infusion center dependency models assume. Forecasts reflect documented assumptions regarding corticosteroid-refractory patient identification rates and EMA extrapolation pathway acceptance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Burns Treatment Market
Medical Treatment
Uterine Fibroid Treatment Drugs Market
Medical Treatment
Monkeypox Treatment Market
Medical Treatment
Gangrene Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Ventral Hernia Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Aspergillosis Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market