
 Transthyretin Amyloidosis Treatment Market | 2026-2036
Transthyretin Amyloidosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Transthyretin Amyloidosis Treatment Market Analysis
Biopharmaceutical manufacturing capacity in North America and Europe is hardening around gene-silencing platforms for transthyretin amyloidosis. Alnylam Pharmaceuticals leads the RNA interference therapeutic segment with in-house production of lipid nanoparticle formulations. Ionis Pharmaceuticals leverages antisense oligonucleotide chemistry to sustain its position in hereditary ATTR cardiomyopathy. Pfizer competes through tafamidis, a small-molecule stabilizer that anchors the oral therapy segment with established cardiovascular outcomes data.
Transthyretin amyloidosis treatment encompasses pharmacologic interventions that modify disease progression by stabilizing the transthyretin tetramer, silencing TTR gene expression, or disrupting existing amyloid fibrils through monoclonal antibody-mediated clearance. These therapies target systemic extracellular deposition of misfolded transthyretin protein in cardiac tissue and peripheral nerves, with lipid nanoparticle and GalNAc-conjugate delivery systems enabling hepatocyte-specific gene knockdown. Injectable therapies command premium positioning due to manufacturing complexity and clinical efficacy in polyneuropathy endpoints. Oral therapies retain volume leadership through tafamidis access in cardiomyopathy, while monoclonal antibodies represent the emerging margin pool as fibril-clearance mechanisms advance through late-stage development.
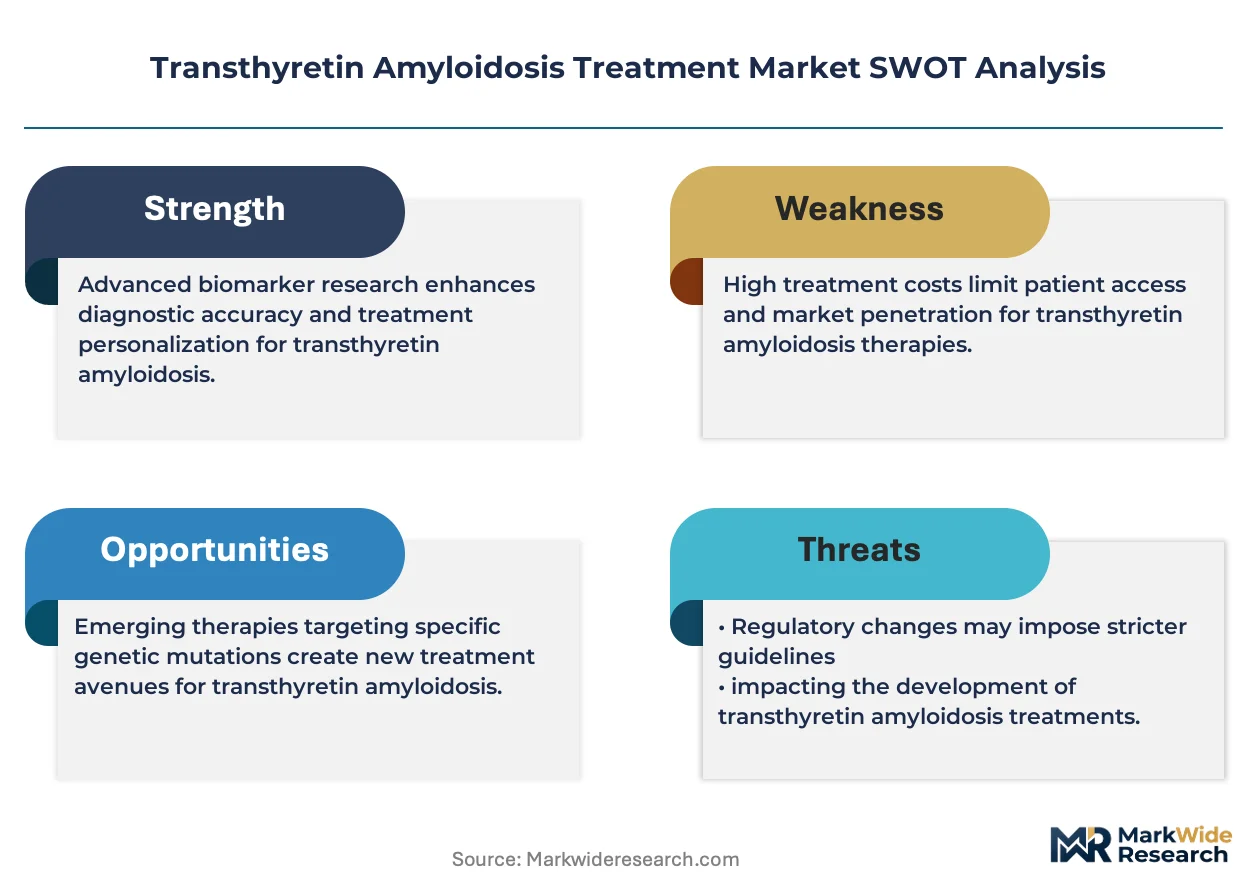
The FDA's Breakthrough Therapy and Priority Review designations compress development timelines for ATTR-modifying drugs, while the EMA's PRIME scheme accelerates European market access for Alnylam and Ionis programs. Japan's PMDA Sakigake designation creates parallel regulatory momentum for Asia-Pacific expansion of RNA-targeted platforms. Stakeholders must monitor evolving biomarker-based diagnostic criteria and payer negotiations for combination therapy sequencing as the therapeutic paradigm shifts from stabilization to disease modification and fibril clearance.
Market Dynamics
RNA-targeted delivery platforms are compressing development timelines and fragmenting the therapeutic paradigm between gene silencing, tetramer stabilization, and fibril clearance mechanisms.
Growth Catalysts
- FDA Accelerated Approval Pathways:The Breakthrough Therapy and Priority Review designations compress clinical development timelines for rare disease modifiers, enabling earlier commercial access for hepatocyte-targeted gene knockdown therapies.
- Diagnostic Infrastructure Expansion:Germany, Japan, and the United States deploy mass spectrometry-based amyloid typing and genetic screening protocols that identify hereditary ATTR carriers before symptomatic progression.
- GalNAc-Conjugate Chemistry Maturation:Liver-targeted ligand delivery systems enable subcutaneous dosing with reduced manufacturing complexity compared to lipid nanoparticle formulations.
Market Restraints
- Specialized Manufacturing Concentration:Lipid nanoparticle production capacity clusters in North American and European contract manufacturing organizations, creating supply bottlenecks for RNA interference therapies.
- Reimbursement Compression:Payer negotiations in Germany and Japan impose outcome-based pricing frameworks that limit premium positioning for injectable disease-modifying therapies.
- Diagnostic Latency:Wild-type ATTR cardiomyopathy remains underdiagnosed due to non-specific symptom overlap with hypertensive heart disease and aortic stenosis.
Strategic Opportunities
- Combination Therapy Sequencing:Stabilizer-to-silencer treatment algorithms create protocol-based revenue streams as clinicians layer tafamidis maintenance with gene knockdown induction.
- Fibril-Clearance Antibody Development:Monoclonal platforms targeting amyloid deposits for macrophage-mediated clearance address the residual disease burden untouched by production-reduction mechanisms.
- Specialty Clinic Integration:Academic medical centers in the United States build dedicated amyloidosis programs that centralize diagnosis, genetic counseling, and therapeutic administration.
Industry Challenges
- Biomarker Standardization Delays:Discordance between N-terminal pro-BNP, troponin thresholds, and disease staging complicates trial endpoint harmonization across regulatory jurisdictions.
- Cold-Chain Distribution Complexity:RNA-based therapeutics require controlled-temperature logistics that strain specialty pharmacy networks in secondary and tertiary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transthyretin Amyloidosis Treatment Market |
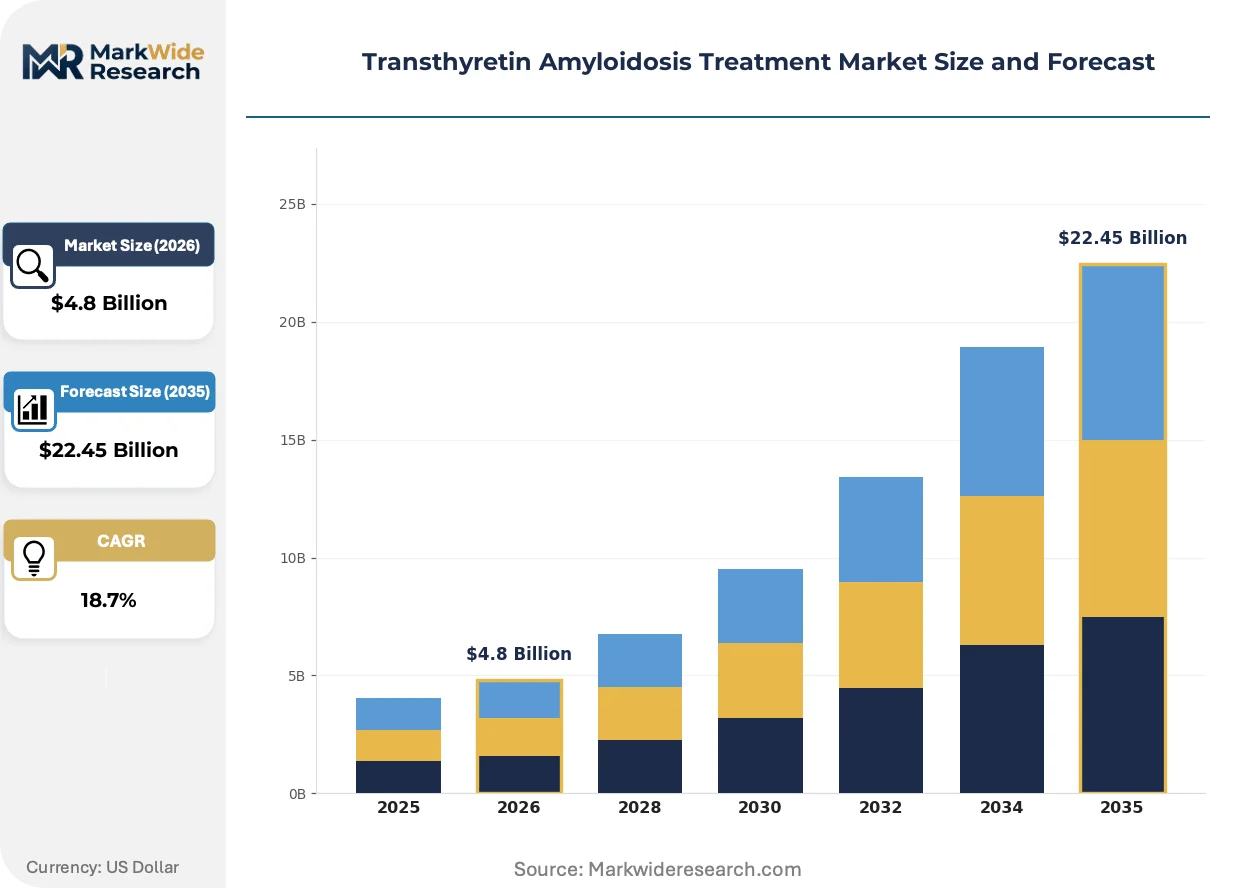
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Therapies, Injectable Therapies, Combination Therapies, Monoclonal Antibodies End User: Hospitals, Specialty Clinics, Treatment Centers, Home Care Disease Stage: Early-Stage, Intermediate-Stage, Late-Stage, Familial Administration Route: Oral, Subcutaneous, Intravenous, Transdermal |
| Companies Covered | Ionis Pharmaceuticals, Intellia Therapeutics, Pfizer, Prothena, Alexion Pharmaceuticals, Alnylam Pharmaceuticals, BridgeBio Pharma, Takeda Pharmaceutical, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transthyretin Amyloidosis Treatment Market Emerging Trajectories
Therapeutic modality convergence is fragmenting the ATTR treatment algorithm across three mechanistic platforms while diagnostic protocols compress the window between genetic risk identification and intervention.
GalNAc-siRNA conjugates are rewriting the competitive architecture of hepatocyte-targeted gene silencing by enabling patient-administered subcutaneous dosing. Specialty clinics in Germany and Japan adopt these platforms for hereditary ATTR polyneuropathy, displacing intravenous lipid nanoparticle regimens that require infusion center infrastructure. The shift compresses per-dose manufacturing costs and expands prescriber access beyond academic tertiary centers.
The EMA's PRIME scheme accelerates European market access for RNA-targeted ATTR programs by providing enhanced scientific dialogue and accelerated assessment pathways. This regulatory architecture prioritizes therapies addressing unmet need in rare disease populations, channeling development resources toward cardiomyopathy indications with larger addressable prevalence than polyneuropathy subtypes. German and French reimbursement authorities respond with parallel health technology assessment frameworks that evaluate cost-effectiveness against stabilized natural history cohorts.
Integrated diagnostic service contracts reshape procurement patterns for amyloidosis care, with United States health systems bundling genetic testing, cardiac imaging, and neurology consultation into episode-based payment structures. Academic medical centers displace community cardiology practices as the primary referral channel for wild-type ATTR suspicion. This concentration is most visible in the Northeast and Midwest corridors where established amyloidosis programs capture regional patient flows.
Transthyretin Amyloidosis Treatment Market Segmentation
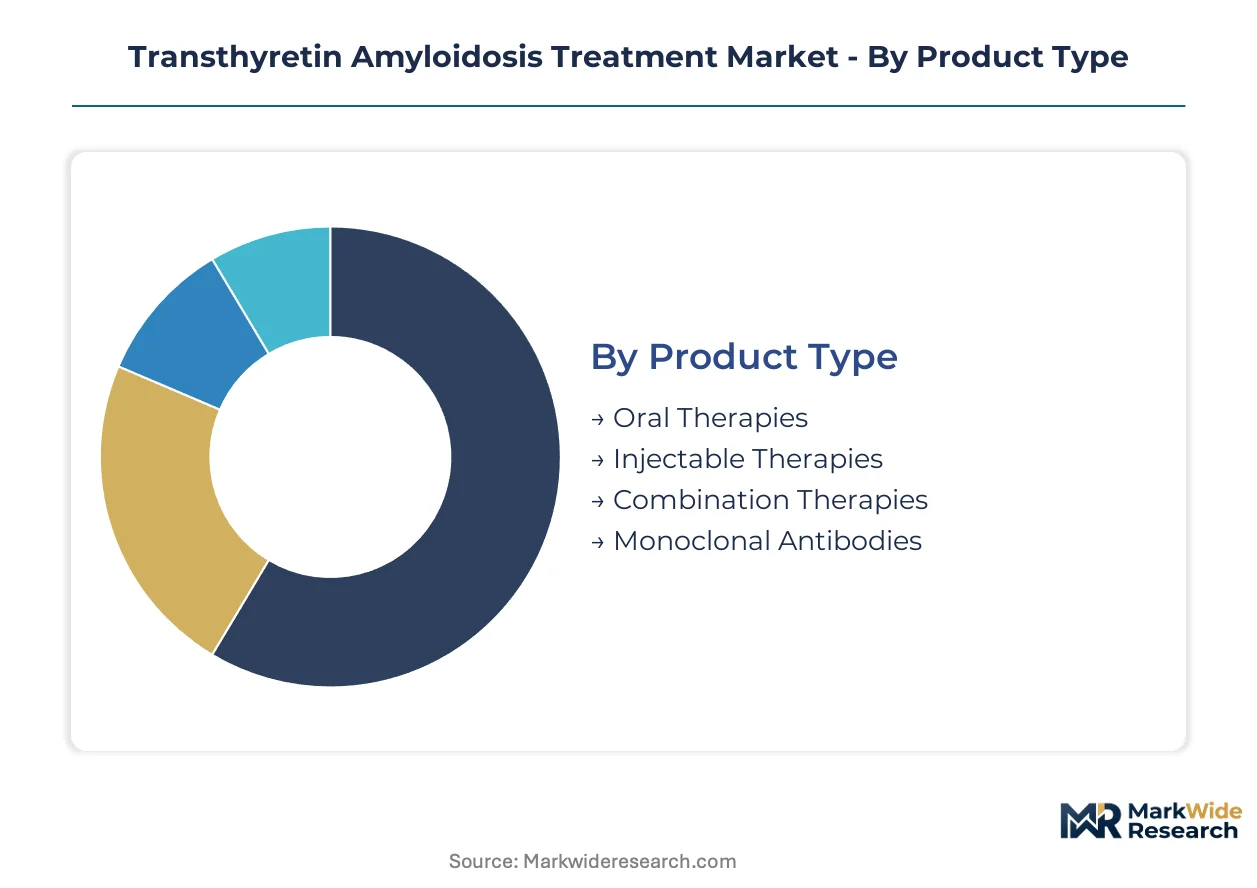
Treatment modality selection in transthyretin amyloidosis follows a progression from oral stabilization to injectable gene silencing, with each segment commanding distinct manufacturing requirements and reimbursement profiles. Patient migration between segments depends on disease stage progression, hepatocyte function, and payer authorization timelines.
Product Type:
Upgrade cycles from oral stabilization to injectable silencing reshape revenue concentration as cardiomyopathy patients exhaust tetramer-binding efficacy.
- Injectable Therapies:Lipid nanoparticle and GalNAc-conjugate formulations enable hepatocyte-specific TTR gene knockdown through RNA interference mechanisms. Demand clusters in United States academic medical centers and German university hospitals where infusion infrastructure and genetic counseling services support intravenous and subcutaneous administration protocols.
- Oral Therapies:Small-molecule tetramer stabilizers bind the thyroxine-binding sites of transthyretin to prevent misfolding and amyloidogenesis. Prescription volumes concentrate in Japan and United States cardiology practices where wild-type ATTR cardiomyopathy diagnosis rates exceed polyneuropathy identification.
- Combination Therapies:Sequential stabilizer-to-silencer protocols address residual disease burden in patients with advanced cardiac involvement.
- Monoclonal Antibodies:Fibril-clearance platforms targeting amyloid deposits for macrophage-mediated removal remain in late-stage development.
Volume placements concentrate in Oral Therapies; the faster expansion belongs to Injectable Therapies.
End User:
Site-of-care migration from inpatient infusion centers to ambulatory settings compresses per-dose reimbursement and expands prescriber access beyond tertiary referral networks.
- Specialty Clinics:Dedicated amyloidosis programs integrate genetic testing, cardiac imaging, and therapeutic administration under unified episode-based payment structures. Concentration is visible in United States Northeast and Midwest corridors where established programs capture regional patient flows.
- Hospitals:Academic medical centers maintain dominance for intravenous lipid nanoparticle administration requiring cold-chain logistics and infusion monitoring capabilities.
- Treatment Centers:Standalone infusion facilities compete on scheduling flexibility and prior authorization support services.
- Home Care:Subcutaneous GalNAc-siRNA conjugates enable self-administration, displacing facility-based care for stable hereditary ATTR polyneuropathy patients.
Revenue concentration tilts toward Specialty Clinics; Home Care is gaining share fastest as subcutaneous platforms mature.
Disease Stage:
Diagnostic protocol expansion compresses the interval between genetic risk identification and therapeutic initiation, shifting volume toward earlier intervention points.
- Early-Stage:Asymptomatic carriers and patients with minimal neuropathy or subclinical cardiac involvement represent the addressable population for disease-modifying intervention. German and Japanese mass spectrometry-based screening programs identify hereditary ATTR carriers before symptomatic progression.
- Intermediate-Stage:Symptomatic polyneuropathy or mild cardiomyopathy with preserved functional status drives stabilizer-to-silencer upgrade decisions.
- Late-Stage:Advanced cardiac or neurologic impairment limits therapeutic options to supportive care and experimental fibril-clearance protocols.
- Familial:Genetic testing of at-risk relatives creates a distinct surveillance and prophylactic treatment population.
Patient identification is climbing the fastest in Early-Stage; therapeutic expenditure per case peaks in Intermediate-Stage.
Administration Route:
Delivery platform innovation restructures manufacturing investment and distribution requirements across parenteral and enteral modalities.
- Subcutaneous:GalNAc-conjugate chemistry enables patient-administered dosing with reduced cold-chain burden compared to lipid nanoparticle formulations. Adoption accelerates in German and Japanese specialty clinics seeking to displace intravenous regimens.
- Intravenous:Lipid nanoparticle encapsulation remains the standard for first-generation RNA interference therapeutics requiring hepatocyte uptake.
- Oral:Small-molecule bioavailability determines dosing frequency and food-effect requirements for tetramer stabilizers.
- Transdermal:No approved transthyretin-directed therapies currently utilize dermal absorption pathways.
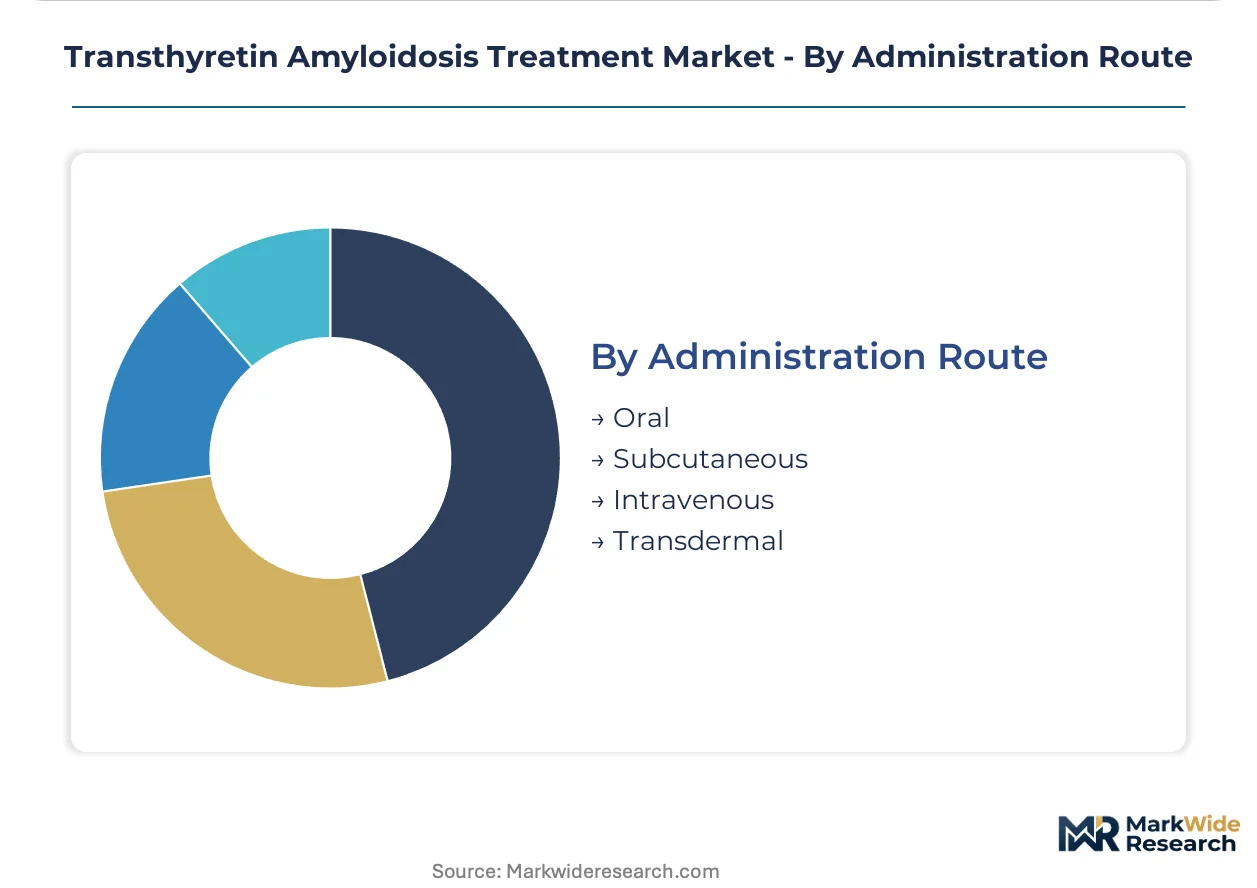
Development pipelines concentrate on Subcutaneous; Intravenous retains volume leadership pending next-generation formulation approvals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass spectrometry-based amyloid typing infrastructure anchors therapeutic demand in the United States, Germany, and Japan. Diagnostic protocol maturation in these markets compresses the interval between genetic risk identification and intervention initiation.
United States
Academic medical centers in Boston and New York Metro deploy integrated amyloidosis programs combining genetic counseling, cardiac imaging, and therapeutic administration. The FDA's Breakthrough Therapy designation accelerates hepatocyte-targeted gene knockdown approvals. Specialty pharmacy networks in the Northeast and Midwest corridors capture regional patient flows through episode-based payment structures.
Germany
University hospitals in Munich and Heidelberg lead European adoption of subcutaneous GalNAc-siRNA platforms for hereditary ATTR polyneuropathy. The EMA's PRIME scheme channels development resources toward cardiomyopathy indications with larger addressable prevalence. German reimbursement authorities apply health technology assessment frameworks evaluating cost-effectiveness against stabilized natural history cohorts.
Japan
Cardiology practices in Tokyo and Osaka drive prescription volumes for oral tetramer stabilizers in wild-type ATTR cardiomyopathy. The PMDA's Sakigake designation creates parallel regulatory momentum for RNA-targeted platform expansion. Mass spectrometry-based screening programs identify hereditary ATTR carriers before symptomatic progression.
United Kingdom
National Health Service tertiary centers in London and Manchester centralize diagnosis and therapeutic administration for familial amyloidosis. The MHRA's post-Brexit regulatory autonomy enables accelerated assessment pathways for rare disease modifiers. Academic research partnerships in Cambridge and Oxford advance biomarker standardization for trial endpoint harmonization.
Switzerland
Specialized amyloidosis clinics in Zurich and Geneva leverage proximity to European pharmaceutical manufacturing clusters. Swissmedic's streamlined rare disease review processes attract clinical trial sponsorship from RNA-targeted therapy developers. The country's diagnostic infrastructure supports early-stage patient identification through genetic screening of at-risk relatives.
Transthyretin Amyloidosis Treatment Market Vendor Landscape
Global majors compete with regional champions across regulatory submission timelines and manufacturing scale. The vendor base stratifies between RNA interference specialists, antisense oligonucleotide developers, and small-molecule stabilizer incumbents. Three archetypes dominate: platform-technology originators with captive lipid nanoparticle capacity, chemistry-focused biotechs with GalNAc-conjugate expertise, and diversified pharmas with cardiovascular commercial infrastructure. Competitive moves center on combination therapy protocol development and fibril-clearance antibody advancement through late-stage pipelines.
Within the platform-technology tier, Alnylam Pharmaceuticals and Ionis Pharmaceuticals exemplify divergent RNA-targeted approaches. Alnylam anchors hepatocyte-specific gene silencing through in-house lipid nanoparticle production. Ionis occupies a position in antisense oligonucleotide chemistry sustaining presence across hereditary ATTR cardiomyopathy. Pfizer represents the small-molecule stabilizer archetype with established cardiovascular outcomes data anchoring oral therapy market presence.
| Leading Market Players |
|---|
| Ionis Pharmaceuticals |
| Intellia Therapeutics |
| Pfizer |
| Prothena |
| Alexion Pharmaceuticals |
| Alnylam Pharmaceuticals |
| BridgeBio Pharma |
| Takeda Pharmaceutical |
| AstraZeneca |
| Others |
Supply Flow & Price Mechanics
Payer mandates for outcome-based contracts in Germany and Japan are forcing manufacturers to unbundle diagnostic services from drug pricing, compressing margins on injectable gene silencing therapies while creating tiered access protocols that favor oral stabilizers in cost-sensitive patient cohorts.
Pricing Analysis
Service bundling separates premium-positioned therapies with integrated genetic counseling and cardiac monitoring from unbundled commodity pricing for maintenance stabilizers. Price differentiation hinges on manufacturing modality—lipid nanoparticle formulations command specialist administration premiums against subcutaneous GalNAc alternatives—and on hepatocyte-targeting specificity. Cost compression in the oral stabilizer segment intensifies as tafamidis faces generic pressure and payer step-therapy requirements. Hospital procurement committees exhibit highest price sensitivity; academic medical centers with dedicated amyloidosis programs demonstrate lowest sensitivity due to episode-based payment insulation.
Supply Chain Analysis
Reverse logistics for temperature-sensitive RNA therapeutics involves specialized cold-chain returns of expired lipid nanoparticle inventory and refurbishment of reusable autoinjector devices for GalNAc-siRNA platforms. Manufacturing concentrates in the United States, Switzerland, and Ireland where contract development organizations cluster around pharmaceutical innovation hubs. Production draws from constrained supplies of ionizable lipids, cholesterol, and polyethylene glycol derivatives. Single-source vulnerability in lipid nanoparticle excipient supply creates exposure to regulatory inspection delays. Distribution runs through specialty pharmacy networks with controlled-temperature last-mile capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transthyretin amyloidosis treatment market sits in a modality-transition phase as subcutaneous GalNAc-conjugate chemistry displaces intravenous lipid nanoparticle platforms and fibril-clearance antibodies advance toward regulatory submission.
For Market Incumbents: Deploy manufacturing scale as the primary defensive lever. Incumbents should expand captive lipid nanoparticle capacity in Switzerland and Ireland to secure supply continuity against contract manufacturing bottlenecks, while accelerating GalNAc-conjugate formulation development to capture site-of-care migration from infusion centers to home administration. The antisense oligonucleotide threat from Ionis Pharmaceuticals demands rapid positioning in cardiomyopathy combination protocols before payer step-therapy algorithms solidify. For New Entrants and Emerging Players: Fibril-clearance monoclonal platforms offer the most penetrable wedge for differentiated entry. New entrants should target the late-stage cardiomyopathy population with residual amyloid burden unaddressed by production-reduction mechanisms, pursuing partnership structures with established cardiovascular commercial infrastructure rather than standalone buildout. Japan's PMDA Sakigake pathway provides the most favorable regulatory geography for accelerated proof-of-concept. For Investors and Strategic Acquirers: The window for entry favors platform-technology originators with hepatocyte-targeting delivery expertise over single-asset developers. Long-term viability hinges on combination therapy positioning across the stabilizer-silencer-clearance algorithm. Investors should monitor biomarker standardization progress—specifically N-terminal pro-BNP and troponin threshold harmonization—as the signal for trial endpoint convergence that will determine competitive differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| GalNAc-Conjugate Manufacturing Scale-Up | Subcutaneous platform expansion reduces cold-chain dependency and enables home administration in German and Japanese markets. |
| Fibril-Clearance Antibody Clinical Advancement | Macrophage-mediated amyloid removal addresses residual disease burden untouched by gene silencing or tetramer stabilization mechanisms. |
| Specialty Clinic Partnership Development | Academic medical center alliances in Boston and New York Metro centralize patient capture through integrated diagnostic and therapeutic protocols. |
| Reimbursement Strategy Optimization | Outcome-based contracting with German G-BA and Japanese Chuikyo secures premium positioning for injectable disease-modifying therapies. |
| Diagnostic Infrastructure Investment | Mass spectrometry-based amyloid typing deployment in United States Northeast corridors compresses time-to-treatment initiation. |
Methodological Framework
Document review covered FDA Breakthrough Therapy designations, EMA PRIME scheme assessments, and PMDA Sakigake approvals, complemented by interviews with drug development executives at RNA-targeted therapy developers, regulatory affairs leads at rare disease specialists, formulary directors at United States payers, and hospital procurement managers at German university hospitals. Secondary validation drew from ClinicalTrials.gov enrollment data, EMA scientific advice letters, and CMS Medicare Part B claims patterns. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market size estimation.
Segment-level outputs across treatment modality, administration route, disease stage, and regional regulatory cluster were generated through patient-based epidemiology linked to pricing assumptions. CAGRs were derived from treatment penetration curves applied to diagnosed prevalence forecasts, with inputs including genetic screening expansion rates in Japan, cardiomyopathy diagnosis protocol maturation in Germany, and RNA therapeutic manufacturing capacity buildout timelines.
Several conditions sit outside the modeled scope, including regulatory rejection of fibril-clearance antibodies, abrupt reimbursement restriction in United States Medicare, and manufacturing contamination events disrupting lipid nanoparticle supply. Forecasts reflect assumptions about diagnostic protocol expansion and payer authorization timelines that could shift with biomarker validation or health technology assessment rulings. Practitioners should monitor FDA advisory committee outcomes for RNA-targeted cardiomyopathy indications and German IQWiG benefit assessments for early signals of access restriction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Brugada Syndrome Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market