
 Biliary Atresia Treatment Market | 2026-2036
Biliary Atresia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Biliary Atresia Treatment Market Analysis
Project finance for rare disease assets is tilting competitive dynamics toward developers with access to venture philanthropy and priority review vouchers. Albireo Pharma leverages its bile acid modulator portfolio to sustain clinical momentum in cholestatic liver diseases. Mirum Pharmaceuticals anchors its position through specialized commercial infrastructure for pediatric hepatology indications. F. Hoffmann-La Roche Ltd. competes via integrated diagnostics-to-therapeutics capabilities across rare liver conditions.
Biliary atresia treatment encompasses surgical intervention, pharmacological management, and supportive modalities aimed at restoring bile flow in infants with fibrotic obstruction of extrahepatic bile ducts; the Kasai portoenterostomy remains the foundational procedure, typically performed within 60 days of birth to achieve bile drainage. The surgery segment dominates procedural volume but yields narrow margins due to standardized reimbursement, while the medication category captures expanding value as novel bile acid therapies and anti-fibrotic agents advance through clinical pipelines. Diagnostics occupies a concentrated margin pool tied to specialized hepatobiliary imaging and genetic screening protocols deployed in neonatal intensive care settings.
The FDA's orphan drug program and EMA's pediatric investigation plans jointly shape development incentives and trial design requirements for biliary atresia therapeutics, with both agencies mandating long-term follow-up data for liver-related clinical endpoints. Japan's PMDA operates a Sakigake designation system that accelerates review timelines for pediatric hepatology innovations meeting unmet need. Stakeholders must monitor evolving biomarker qualification pathways and transplant allocation policy reforms that could redefine treatment sequencing and commercial addressability.
Market Dynamics
The biliary atresia treatment landscape pivots on transplant center concentration, where Kasai procedure volume and post-surgical pharmacological management concentrate within 50 specialized pediatric hepatology units across the United States, creating referral network bottlenecks that determine patient flow and therapeutic sequencing.
Growth Catalysts
- Priority Review Voucher Accumulation:The FDA's rare pediatric disease program generates transferable vouchers that developers monetize to accelerate capital formation for bile acid modulator trials.
- Neonatal Screening Expansion:State-level newborn screening programs in California, Texas, and New York now incorporate direct bilirubin protocols that compress time-to-diagnosis windows.
- Biomarker Qualification Pathways:The FDA's Drug Development Tools program validates surrogate endpoints for liver fibrosis progression, shortening Phase II trial durations.
Market Restraints
- Orphan Population Constraints:Annual incidence of 300-400 US cases limits addressable revenue pools for novel therapeutics.
- Transplant Allocation Rigidities:UNOS pediatric priority scoring systems create unpredictable waitlist dynamics that confound long-term pharmacoeconomic modeling.
- Reimbursement Compression:Medicaid dominates payer mix for neonatal hepatology, yielding narrow margins on standardized Kasai procedural bundles.
Strategic Opportunities
- Anti-Fibrotic Combination Regimens:Pipeline assets targeting TGF-beta signaling pathways create adjacency expansion beyond bile acid modulation monotherapy.
- Pre-Kasai Medical Optimization:Pharmacological bridge-to-surgery protocols represent an undeveloped indication window between diagnosis and operative intervention.
- Telehepatology Networks:Remote consultation infrastructure extends specialist reach into non-transplant center catchment areas across the Mountain West and Great Plains.
Industry Challenges
- Pediatric Trial Recruitment:Single-digit annual case volumes per site necessitate multi-center coordination across 15-20 institutions to achieve statistical powering.
- Longitudinal Endpoint Capture:Native liver survival metrics require 10-15 year follow-up periods that exceed typical venture capital fund lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biliary Atresia Treatment Market |
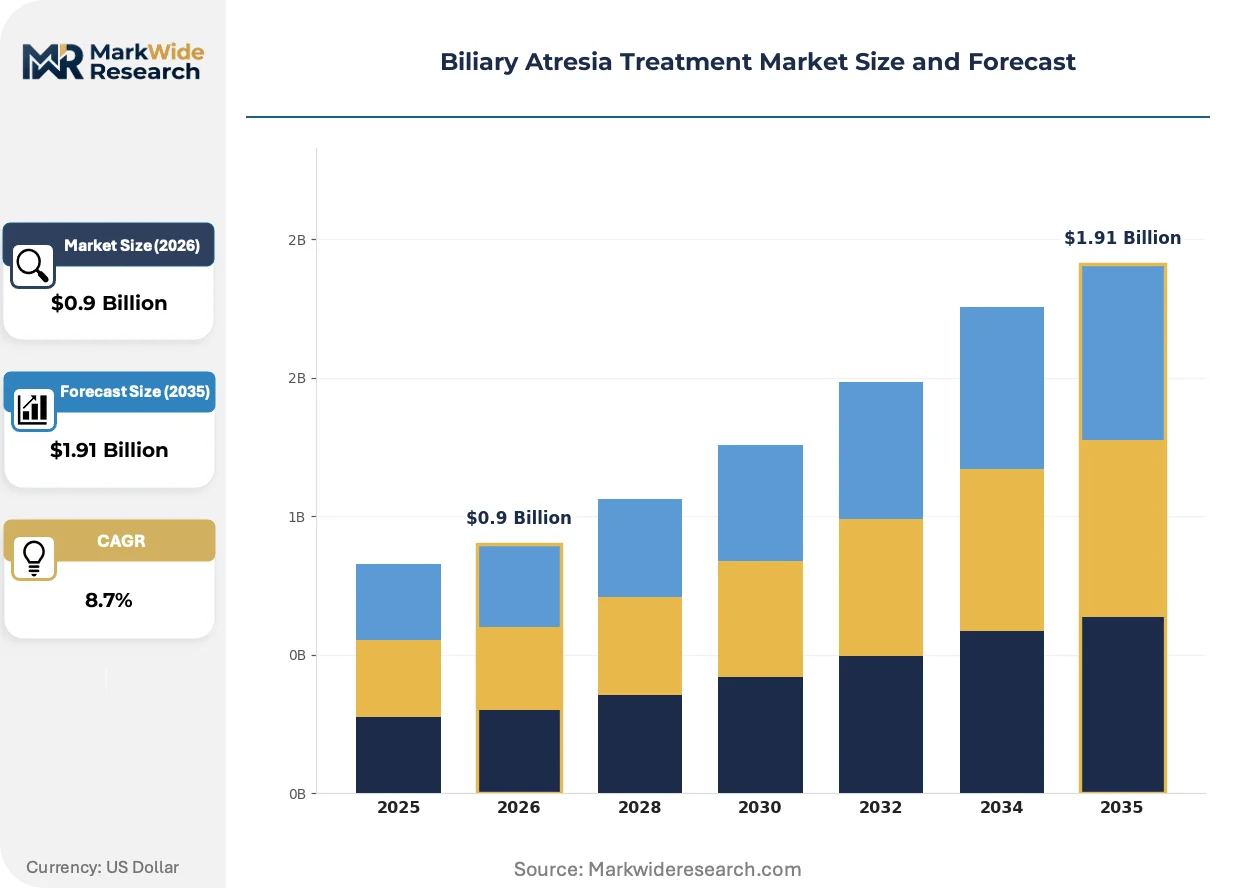
| Market Size in 2026 | $0.9 Billion |
| Market Size in 2035 | $1.91 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Medication, Diagnostics, Supportive Care End User: Hospitals, Clinics, Home Care, Specialized Centers Delivery Mode: Oral, Intravenous, Surgical Procedure, Nutritional Support Age Group: Infants, Children, Adolescents, Adults |
| Companies Covered | F. Hoffmann-La Roche Ltd., Mirum Pharmaceuticals, Inc., Pfizer Inc., Eisai Co., Ltd., Albireo Pharma, Inc., Novartis AG, Johnson & Johnson Private Limited, Bristol-Myers Squibb Company, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biliary Atresia Treatment Market Emerging Trajectories
Neonatal cholangiopathy management is bifurcating into two parallel innovation tracks: molecular diagnostics that stratify surgical candidacy, and pharmacological interventions that extend native liver survival timelines. Both tracks demand specialized commercial infrastructure distinct from adult hepatology.
Next-generation sequencing panels for biliary atresia subtype classification are collapsing the diagnostic uncertainty window that previously delayed Kasai timing decisions. Pediatric hepatology departments at Children's Hospital of Philadelphia and Cincinnati Children's deploy these platforms to differentiate isolated extrahepatic obstruction from syndromic variants. The technology is collapsing inter-hospital referral friction by enabling remote pathology interpretation.
The FDA's 2023 guidance on pediatric rare disease trial design mandates adaptive Bayesian frameworks that permit smaller control arms. This regulatory shift accelerates enrollment timelines for anti-fibrotic agents while maintaining statistical rigor. Developers targeting bile acid metabolism now structure protocols around this framework, compressing Phase II durations.
Parent advocacy organizations now drive care site selection through published outcome transparency databases. Families increasingly bypass local pediatric gastroenterology referrals to access high-volume Kasai centers in Pittsburgh, Houston, and Atlanta. This behavioral shift concentrates surgical volume and post-operative pharmacological management within established transplant corridors.
Biliary Atresia Treatment Market Segmentation
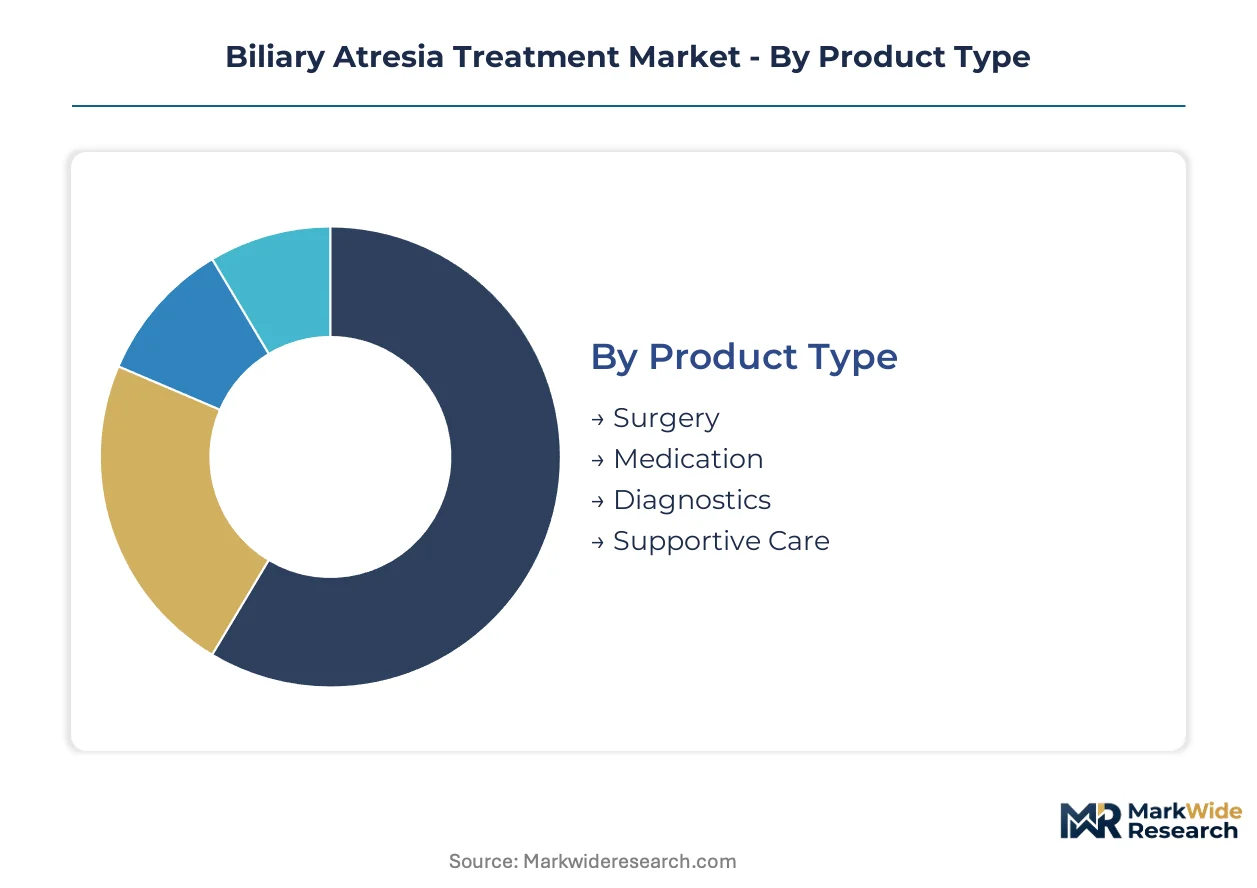
Segmentation in biliary atresia treatment reveals how clinical workflows, reimbursement pathways, and patient acuity stratify across distinct product and service categories. Each dimension carries specific margin profiles and regulatory requirements that shape commercial strategy.
Product Type:
Use cases span acute surgical intervention through chronic disease management, with each product category serving different points in the care continuum.
- Surgery:The Kasai portoenterostomy involves anastomosis of the porta hepatis to a Roux-en-Y jejunal loop to restore bile drainage. Demand concentrates at the 50 specialized pediatric transplant centers across the United States, where procedural volume thresholds correlate with improved native liver survival outcomes.
- Medication:Bile acid modulators, anti-fibrotic agents, and nutritional supplements constitute pharmacological management protocols. Prescription patterns cluster within post-Kasai care pathways at children's hospitals in Pittsburgh, Houston, and Atlanta, driven by hepatologist specialization and formulary access.
- Diagnostics:Hepatobiliary scintigraphy, liver biopsy, and genetic screening panels enable subtype classification and surgical timing decisions.
- Supportive Care:Nutritional optimization, fat-soluble vitamin supplementation, and growth monitoring address cholestasis complications.
Established volume favors Surgery; emerging adoption favors Medication.
End User:
Patient acuity and reimbursement complexity determine where treatment episodes initiate and conclude across the care delivery spectrum.
- Hospitals:Level IV neonatal intensive care units and pediatric transplant centers manage Kasai procedures, liver transplantation, and acute decompensation events. California, Texas, and New York Medicaid programs drive patient volume through designated referral networks.
- Specialized Centers:Dedicated pediatric hepatology programs at freestanding children's hospitals coordinate longitudinal care and clinical trial access. These sites capture the highest-margin medication dispensing and diagnostic interpretation revenue.
- Clinics:Community pediatric gastroenterology practices handle initial suspicion and referral coordination.
- Home Care:Enteral nutrition administration and medication adherence monitoring extend institutional protocols into residential settings.
Revenue concentration sits with Specialized Centers; patient flow origination sits with Hospitals.
Delivery Mode:
Route of administration and intervention intensity map directly to treatment phase and physiological stability requirements.
- Surgical Procedure:Open abdominal intervention under general anesthesia remains the definitive intervention for extrahepatic bile duct obstruction. Volume aggregates at high-throughput centers where anesthesia teams possess neonatal-specific expertise.
- Intravenous:Parenteral nutrition and acute pharmacological management address perioperative decompensation and transplant preparation. Utilization spikes during hospitalization episodes at tertiary pediatric facilities.
- Oral:Bile acid sequestrants and fat-soluble vitamin formulations constitute chronic outpatient therapy.
- Nutritional Support:Specialized formula and medium-chain triglyceride supplementation address malabsorption.
Acute episode dependency favors Surgical Procedure; longitudinal management expansion favors Oral.
Age Group:
Disease natural history and intervention timing create distinct clinical windows across pediatric development stages.
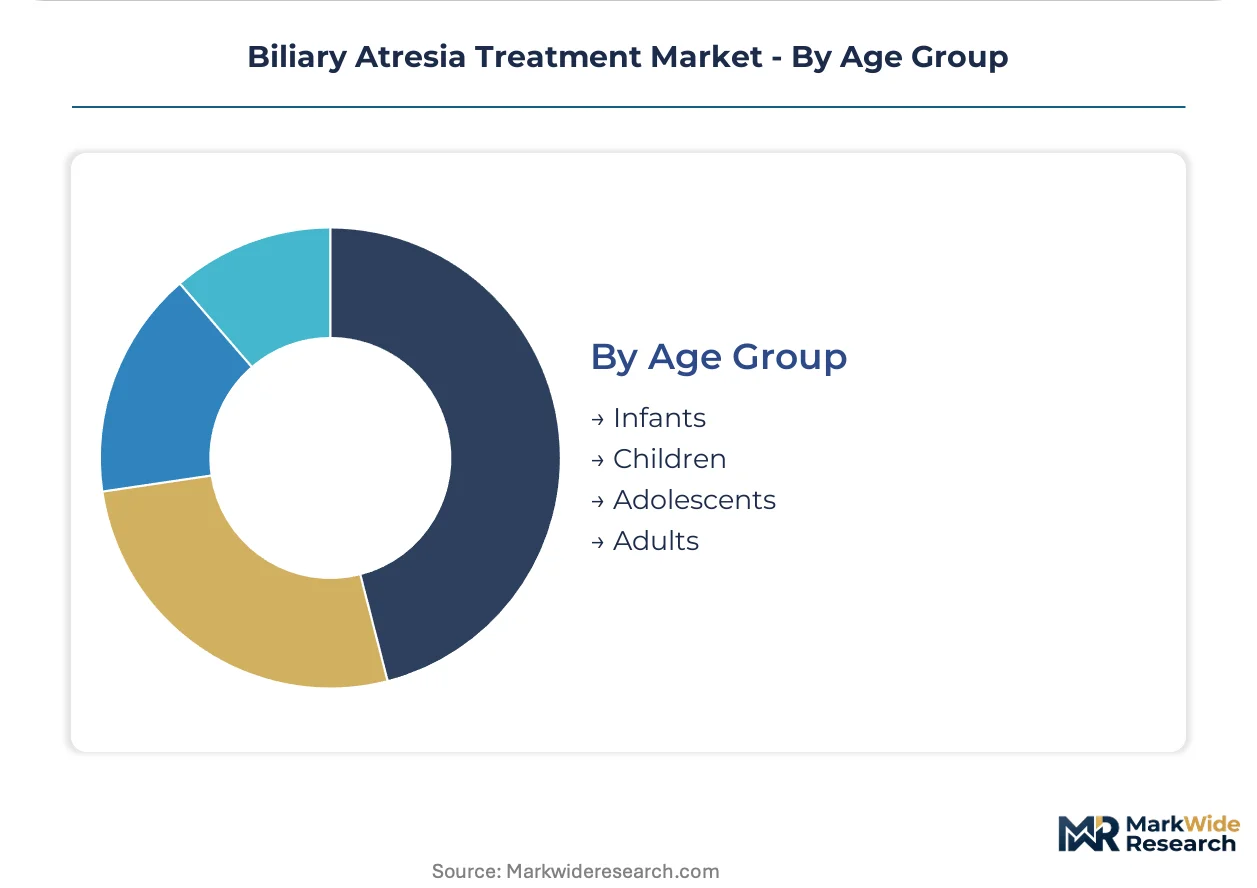
- Infants:Neonates under 60 days of age constitute the critical intervention window for Kasai portoenterostomy success. State newborn screening programs in California, Texas, and New York direct diagnostic urgency through direct bilirubin protocols.
- Children:Patients aged 1-10 years require chronic management of progressive fibrosis and portal hypertension. This population drives anti-fibrotic drug development programs and transplant waitlist dynamics.
- Adolescents:Transition-age patients face graft surveillance and immunosuppression adherence challenges.
- Adults:Long-term survivors of pediatric liver transplantation require specialized transition clinics.
Intervention criticality peaks with Infants; pharmaceutical addressability expands most quickly with Children.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug incentives and pediatric priority review pathways are redrawing commercial geography for biliary atresia therapeutics. The United States, Japan, Germany, United Kingdom, and Australia concentrate the majority of clinical trial infrastructure and regulatory momentum for neonatal cholangiopathy interventions.
United States
Medicaid-funded referral networks to 50 specialized pediatric transplant centers concentrate Kasai procedure volume and post-surgical pharmaceutical management. The FDA's rare pediatric disease priority review voucher program accelerates capital formation for developers targeting bile acid metabolism. Pittsburgh, Houston, and Atlanta anchor high-throughput surgical corridors where hepatologist specialization drives formulary access for novel therapies.
Japan
The PMDA's Sakigake designation system compresses review timelines for pediatric hepatology innovations demonstrating substantial unmet need. Domestic neonatal screening protocols incorporating direct bilirubin measurement narrow diagnostic windows. Tokyo and Osaka metropolitan medical centers coordinate multi-site trial networks for anti-fibrotic agents targeting TGF-beta signaling pathways.
Germany
EMA pediatric investigation plans and national reimbursement frameworks for orphan indications sustain early-access programs for bile acid modulators. The country's university hospital network, particularly Heidelberg and Hamburg, maintains longitudinal native liver survival registries that qualify as external control arms for adaptive trial designs. Bavarian and North Rhine-Westphalian pediatric hepatology units drive European enrollment for Phase II fibrosis studies.
United Kingdom
NHS England's specialized commissioning for rare liver diseases routes biliary atresia cases to designated supra-regional centers in London and Birmingham. The MHRA's reliance on EMA centralized procedures streamlines orphan drug approval pathways. King's College Hospital and Birmingham Children's Hospital anchor the national transplant corridor where pharmacological bridge-to-surgery protocols are entering pilot evaluation.
Australia
The TGA's orphan drug designation parallels FDA incentives, with Melbourne and Sydney pediatric liver units participating in international multi-center trials. State-level newborn screening expansion in Victoria and New South Wales compresses time-to-diagnosis intervals. The Royal Children's Hospital Melbourne coordinates Australasian registry data that supports biomarker qualification submissions to the FDA's Drug Development Tools program.
Biliary Atresia Treatment Market Vendor Landscape
On the supply side, the industry is consolidating around developers possessing integrated diagnostics-to-therapeutics capabilities and specialized pediatric commercial infrastructure. Three archetypes dominate: large-cap pharmaceutical companies with orphan disease divisions, mid-cap biotechs focused on bile acid modulation, and diversified hepatology players leveraging transplant center relationships. Competitive moves center on priority review voucher accumulation and multi-center trial network construction.
Within the mid-cap biotech tier, Albireo Pharma and Mirum Pharmaceuticals exemplify developers anchoring position through bile acid modulator portfolios and dedicated pediatric hepatology sales infrastructure. F. Hoffmann-La Roche Ltd. represents the large-cap archetype, leveraging integrated diagnostics capabilities across rare liver conditions. These three entities occupy distinct competitive positions: the biotechs concentrate clinical momentum in cholestatic diseases, while the Swiss pharmaceutical conglomerate spans broader hepatology indications.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Mirum Pharmaceuticals, Inc. |
| Pfizer Inc. |
| Eisai Co., Ltd. |
| Albireo Pharma, Inc. |
| Novartis AG |
| Johnson & Johnson Private Limited |
| Bristol-Myers Squibb Company |
| AstraZeneca plc |
| Others |
Supply Flow & Price Mechanics
Pittsburgh's concentration of pediatric transplant centers generates asymmetric pricing power for Kasai procedure bundles, with Medicaid reimbursement rates compressing margins at satellite hospitals while specialized centers capture premium pharmacological management fees. This geographic supply clustering shapes downstream cost structures across neonatal hepatology referral networks.
Pricing Analysis
Certification level (FDA orphan drug designation versus standard pediatric indication) creates the primary spread between premium and standard therapeutic tiers. Three-tier pricing structure across premium, standard, and economy levels dominates: novel bile acid modulators command premium positioning, generic nutritional supplements occupy economy tiers, and branded anti-fibrotic agents sit at mid-market price points. Pricing pressure stems from Medicaid's dominance in neonatal payer mix, yielding narrow margins on standardized procedural bundles. Community hospitals exhibit highest price sensitivity due to fixed reimbursement ceilings, while specialized transplant centers demonstrate lowest sensitivity given formulary control and trial revenue offsets.
Supply Chain Analysis
Extended payment terms from specialized children's hospitals to pharmaceutical distributors stretch working capital cycles across the procurement tier. Manufacturing concentration clusters in the United States, Switzerland, and Japan for active pharmaceutical ingredients targeting bile acid metabolism. Raw material dependencies center on synthetic bile acid precursors, specialized excipients for neonatal formulations, and cold-chain logistics infrastructure. Single-source vulnerability persists for pediatric-specific compounding capabilities. Distribution runs through GPO-affiliated hospital procurement networks with formulary committee gatekeeping at major transplant centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating within 50 specialized pediatric transplant centers, fragmenting community hospital influence and reshaping commercial access dynamics for novel therapeutics.
For Market Incumbents: Entrench position through backward integration into diagnostic platform development and captive supply of biomarker qualification data. Priority defensive moves include securing exclusive formulary placement at high-volume Kasai centers and building longitudinal patient registries that serve as external control arms for competitors' trials. The emergence of telehepatology networks threatens traditional referral capture, demanding investment in remote consultation infrastructure to maintain patient funnel control. For New Entrants and Emerging Players: Build out specialized commercial infrastructure targeting the pre-Kasai pharmacological optimization window, currently undeveloped by established bile acid modulator portfolios. White-space opportunities concentrate in anti-fibrotic combination regimens and bridge-to-surgery protocols at mid-tier children's hospitals lacking integrated hepatology programs. Go-to-market execution should anchor in telehepatology partnerships that extend specialist reach into Mountain West and Great Plains catchment areas. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with validated surrogate endpoints and adaptive trial frameworks already deployed. Long-term viability across the analysis window hinges on biomarker qualification success and priority review voucher accumulation. Acquisition target archetype: mid-cap biotechs with Phase II anti-fibrotic assets and established pediatric hepatology sales infrastructure. The signal to watch is FDA Drug Development Tools program qualification for liver fibrosis progression markers, which would compress trial timelines and revalue pipeline stage gates.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Framework Deployment | FDA's 2023 pediatric rare disease guidance permits smaller control arms, accelerating enrollment for anti-fibrotic agents. |
| Biomarker Qualification Pathway | Drug Development Tools program validation for liver fibrosis surrogates shortens Phase II durations and reduces capital requirements. |
| Telehepatology Network Construction | Remote consultation infrastructure extends specialist reach into non-transplant center catchment areas across underserved regions. |
| Priority Review Voucher Accumulation | Rare pediatric disease program generates transferable vouchers that monetize to accelerate capital formation for pipeline assets. |
| Pre-Kasai Protocol Development | Pharmacological bridge-to-surgery indication represents undeveloped commercial window between diagnosis and operative intervention. |
Methodological Framework
Desk research of FDA orphan drug designations, EMA pediatric investigation plans, and ClinicalTrials.gov protocols preceded structured interviews with pediatric hepatologists, formulary directors at children's hospitals, regulatory affairs specialists, and payer access managers. Secondary validation drew from hospital procurement databases, Medicaid reimbursement schedules, and transplant center outcome registries. Bottom-up demand modeling triangulated against top-down market sizing from priority review voucher transaction data and venture philanthropy flows.
Assumptions held fixed across the modeling period include current FDA and EMA regulatory frameworks, existing UNOS pediatric priority scoring systems, and stable Medicaid funding levels for neonatal intensive care. Segmentation dimensions encompassed treatment modality, delivery route, patient age cohort, and regional regulatory cluster. CAGRs derived from procedure volume trends at high-throughput centers, pharmaceutical pricing trajectories for bile acid modulators, and diagnostic adoption curves for next-generation sequencing panels. Forecast inputs incorporated state-level newborn screening expansion timelines and transplant allocation policy reform probabilities.
Stress conditions across regulatory approval delays, biomarker qualification failures, and transplant center consolidation scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding referral network stability and orphan drug incentive continuity. Macroeconomic shifts in Medicaid funding, disruptive changes to pediatric priority review voucher mechanics, or breakthrough non-transplant therapeutic modalities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Subdural Haematoma Market