
 North America Precision Medicine Market | 2026-2036
North America Precision Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Precision Medicine Market Insights
Project finance partnerships between health systems and diagnostic platform vendors is reconfiguring capital deployment across the competitive landscape. Illumina leverages its installed base of sequencing instruments to sustain recurring consumable revenue. Thermo Fisher Scientific anchors its position through integrated workflow solutions spanning sample preparation to data interpretation. Pfizer competes by aligning therapeutic development with companion diagnostic strategies.
Precision medicine encompasses individualized therapeutic and diagnostic approaches guided by patient-specific genetic, biomarker, and phenotypic profiles, utilizing next-generation sequencing with read depths exceeding 30x for clinical-grade variant detection to match treatments to molecular subtypes. Genomics occupies the largest value pool given sequencing infrastructure investments, while data analytics represents the fastest-expanding segment as real-world evidence platforms integrate multi-omics datasets. Therapeutics commands premium pricing power where biomarker-defined indications secure targeted reimbursement.
FDA oversight of companion diagnostics through the Center for Devices and Radiological Health shapes product development requirements, while HIPAA governs genomic data exchange constraints across health networks. The IRA's drug pricing provisions are influencing precision therapy commercialization strategies. Stakeholders must monitor evolving coverage determinations from CMS and private payers for molecular testing categories.
Market Dynamics
Project finance partnerships between health systems and diagnostic platform vendors are reconfiguring capital deployment across the competitive landscape. The FDA's accelerated approval pathways for companion diagnostics are shortening development timelines while concentrating demand in California's Bay Area biotech corridor.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's Center for Devices and Radiological Health streamlines companion diagnostic submissions, compressing time-to-market for oncology biomarker tests.
- Molecular Profiling Expansion:Academic medical centers in Boston and Houston are scaling next-generation sequencing programs to 30x read depths for clinical-grade variant detection.
- IRA Provisions:The Inflation Reduction Act's drug pricing frameworks are incentivizing biomarker-defined therapeutic development with targeted reimbursement pathways.
Market Restraints
- HIPAA Compliance Burden:Genomic data exchange constraints across multi-state health networks impose interoperability friction on real-world evidence platforms.
- Sequencing Reagent Concentration:Consumable supply chains for flow-cell chemistry concentrate among a limited vendor base, creating input cost volatility.
- Reimbursement Uncertainty:CMS coverage determinations for novel molecular testing categories lag FDA approvals by 18-24 months on average.
Strategic Opportunities
- Midwest Health System Penetration:Underpenetrated markets in Ohio and Michigan present white space for integrated diagnostic-therapeutic platforms.
- Multi-Omics Convergence:Integration of proteomic and metabolomic datasets with genomic baselines is opening new indication categories in immunology.
- State Medicaid Expansion:California and New York are extending molecular testing coverage to underserved populations through supplemental payment programs.
Industry Challenges
- Bioinformatics Talent Scarcity:Variant interpretation pipelines require computational biologists with dual training in clinical genetics and machine learning.
- CAP/CLIA Certification Timelines:Laboratory accreditation for clinical-grade sequencing extends validation cycles by 12-18 months.
- EHR Integration Complexity:Legacy electronic health record systems require costly middleware development to ingest structured genomic data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Precision Medicine Market |
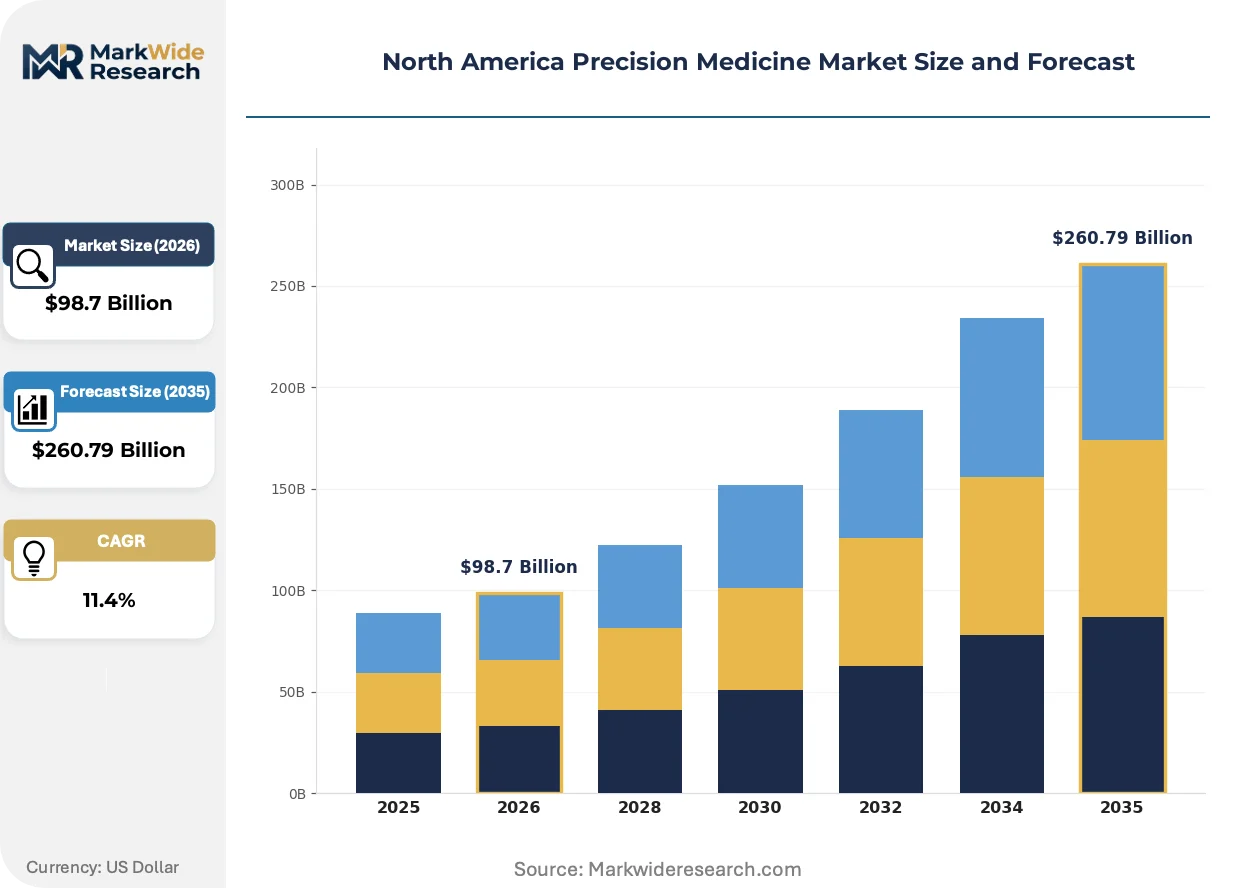
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genomics, Diagnostics, Therapeutics, Data Analytics End User: Hospitals, Research Laboratories, Biotechnology Companies, Pharmaceutical Firms Delivery Mode: Online Platforms, Laboratory Services, Mobile Applications, Clinical Settings Technology: Next-Generation Sequencing, CRISPR, Bioinformatics, Personalized Vaccines |
| Companies Covered | Illumina, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, Pfizer, Novartis, QIAGEN, AstraZeneca, Bristol-Myers Squibb, Guardant Health, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Precision Medicine Market Trends and Innovations
Artificial intelligence is reshaping how multi-omics datasets translate into actionable therapeutic decisions. Three developments are compressing development cycles and reconfiguring competitive positioning across the value chain.
Liquid biopsy technology is hybridizing with circulating tumor DNA detection to enable real-time treatment monitoring without invasive tissue sampling. Community oncology practices in Texas and Florida are adopting these platforms at twice the rate of academic centers. The technology is compressing the feedback loop between therapeutic intervention and molecular response assessment.
The FDA's draft guidance on artificial intelligence-enabled diagnostic devices is mandating predetermined change control plans for algorithm updates. Device manufacturers must now lock training datasets and performance specifications prior to submission. Oncology companion diagnostics with adaptive algorithms face the steepest compliance burden.
Health system procurement committees are consolidating molecular testing contracts under single-source agreements with integrated workflow vendors. Independent reference laboratories are losing access to hospital outpatient departments as capital equipment leases bundle consumables and interpretation services. This concentration is most visible in the Philadelphia and Baltimore hospital networks.
North America Precision Medicine Market Segmentation
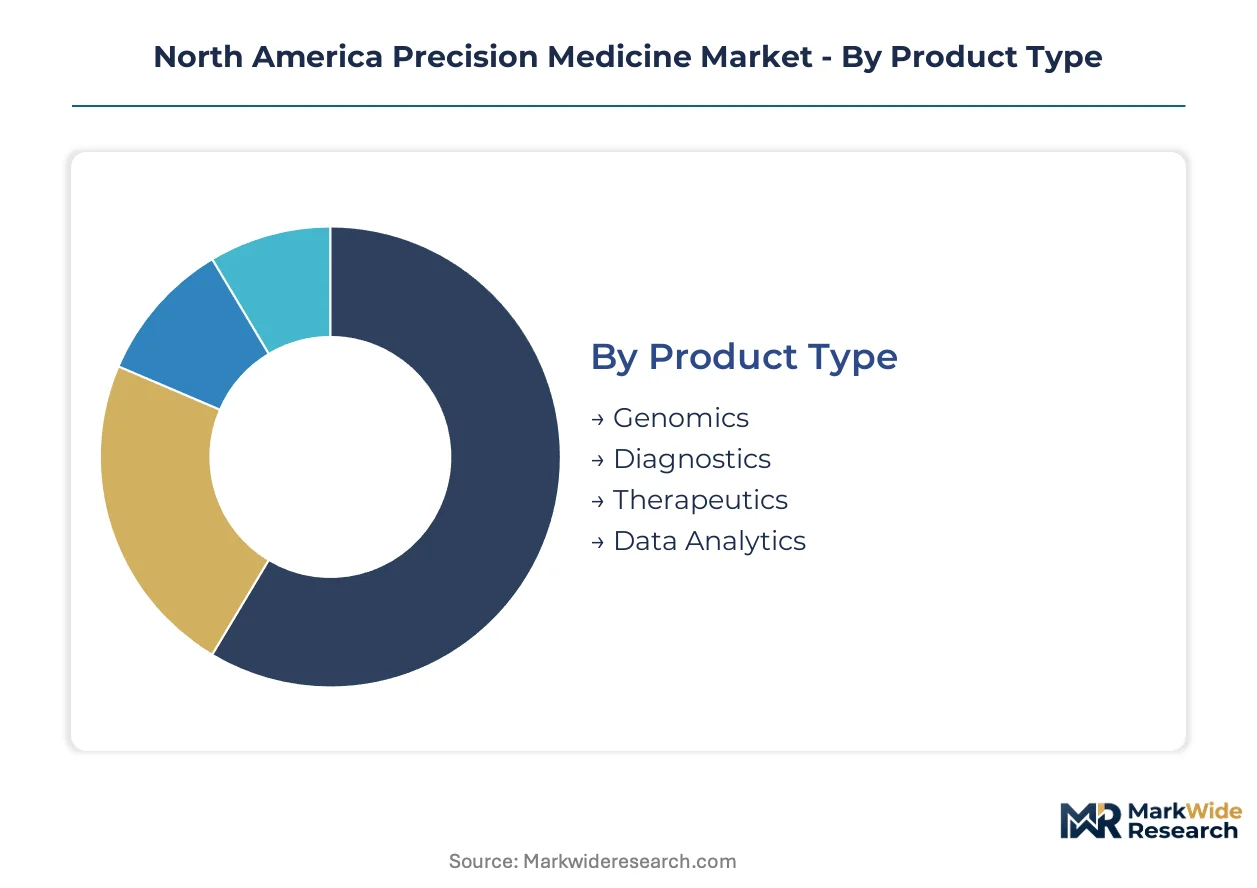
Segmentation in precision medicine reveals how value flows through distinct technical and commercial channels. Each category exposes different margin structures, regulatory exposure, and capital intensity requirements that shape competitive positioning across the value chain.
Product Type:
The use-case spectrum spans from infrastructure-heavy sequencing platforms to software-driven interpretation layers, with each tier demanding different partnership models between vendors and health systems.
- Genomics:Sequencing infrastructure and reagent consumables form the foundational layer of molecular profiling. California's Bay Area biotech corridor concentrates demand for Illumina and Thermo Fisher instrument installations, driven by academic medical center expansion of 30x read depth clinical programs.
- Diagnostics:Companion diagnostic assays link biomarker detection to therapeutic selection, requiring FDA Center for Devices and Radiological Health premarket approval. The IRA's drug pricing provisions are accelerating biomarker-defined indication development, concentrating demand in oncology practices seeking targeted reimbursement pathways.
- Therapeutics:Biomarker-directed drug development commands premium pricing where molecular subtypes secure coverage.
- Data Analytics:Real-world evidence platforms integrate multi-omics datasets for treatment optimization.
The dominant share belongs to Genomics, while Data Analytics is closing the gap fastest.
End User:
Customer type determines contract structure, with capital equipment leases bundling consumables differently than fee-for-service arrangements.
- Hospitals:Academic medical centers in Boston and Houston anchor molecular profiling program expansion, deploying next-generation sequencing for clinical-grade variant detection. Procurement committees in Philadelphia and Baltimore networks are consolidating testing contracts under single-source integrated workflow agreements.
- Research Laboratories:CAP/CLIA certification requirements extend validation cycles by 12-18 months for clinical-grade sequencing.
- Biotechnology Companies:Platform developers seek project finance partnerships with health systems to reconfigure capital deployment.
- Pharmaceutical Firms:Therapeutic developers align pipeline strategies with companion diagnostic regulatory pathways.
Hospitals command the largest procurement volume, though Biotechnology Companies are expanding their share through platform-as-a-service models.
Delivery Mode:
Channel selection shapes patient access patterns and reimbursement complexity across the care continuum.
- Online Platforms:Patient-facing portals for genetic risk assessment and pharmacogenomic reporting. Direct-to-consumer penetration remains constrained by HIPAA compliance burdens on genomic data exchange across multi-state networks.
- Laboratory Services:Centralized processing of tissue and liquid biopsy specimens with interpretive reporting.
- Mobile Applications:Point-of-care interfaces for real-time treatment decision support.
- Clinical Settings:Integrated delivery within oncology practices and specialty clinics.
Laboratory Services retains the highest transaction volume, while Clinical Settings are gaining share through embedded workflow integration.
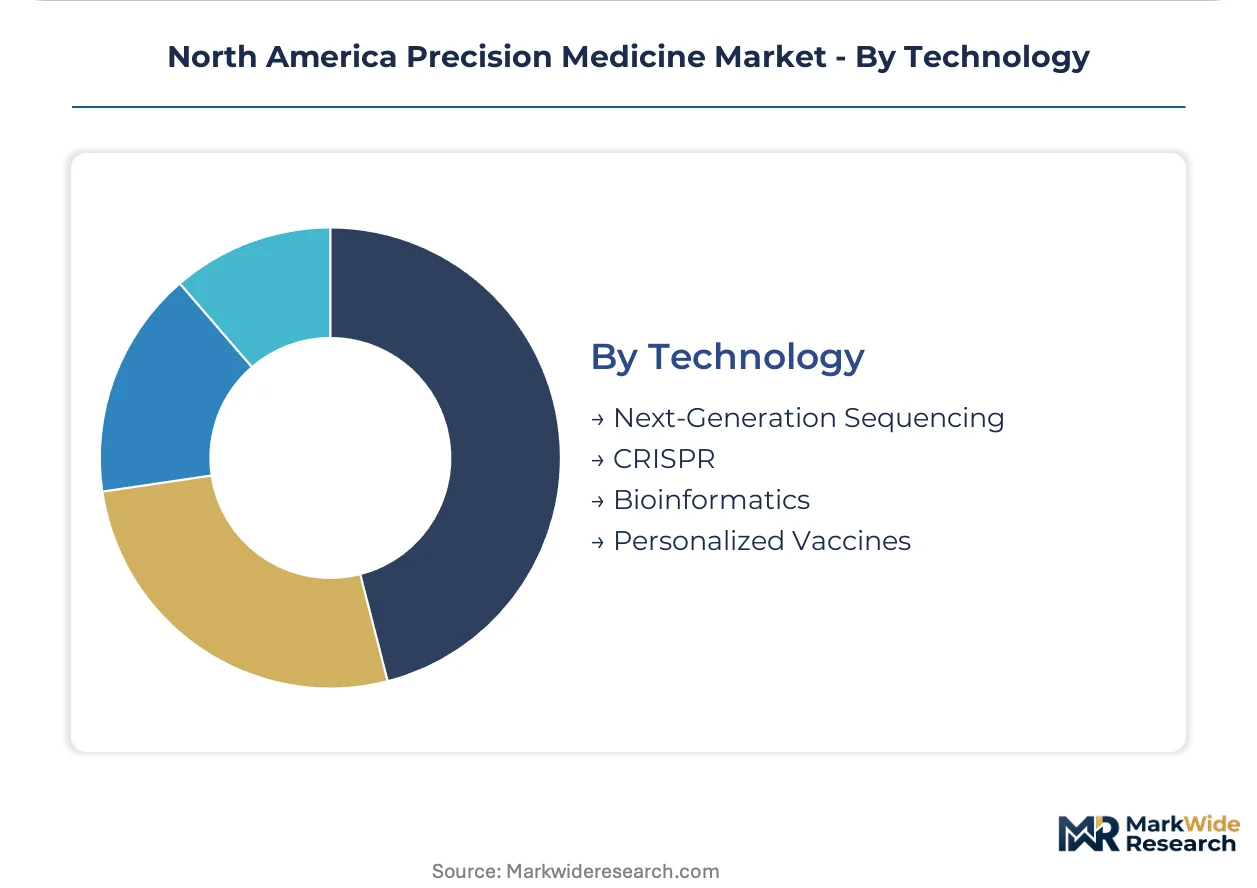
Technology:
Technology maturity curves separate platforms with established reimbursement from emerging modalities facing validation timelines.
- Next-Generation Sequencing:Short-read and long-read platforms achieving 30x coverage depths for clinical-grade detection. Community oncology practices in Texas and Florida are adopting these platforms at twice the rate of academic centers for real-time treatment monitoring.
- CRISPR:Gene editing applications in therapeutic development and functional genomics research.
- Bioinformatics:Variant interpretation pipelines require computational biologists with dual training in clinical genetics and machine learning, creating talent scarcity constraints.
- Personalized Vaccines:Neoantigen-directed immunotherapy development leveraging tumor sequencing data.
Next-Generation Sequencing holds the installed base advantage, yet Bioinformatics is expanding most quickly as real-world evidence platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRA's drug pricing provisions and FDA accelerated approval pathways are redirecting investment toward biomarker-defined therapeutic development across North American jurisdictions. Federal and provincial incentive structures are reshaping where sequencing infrastructure and companion diagnostic programs concentrate.
United States
California's Bay Area biotech corridor anchors instrument demand from Illumina and Thermo Fisher as academic medical centers expand 30x read depth clinical programs. The FDA's Center for Devices and Radiological Health streamlines companion diagnostic submissions, compressing time-to-market for oncology biomarker tests. Texas and Florida community oncology practices are adopting liquid biopsy platforms at twice the rate of academic centers.
Canada
Ontario and Quebec health systems are consolidating molecular testing procurement under provincial laboratory services frameworks, creating volume concentration for integrated workflow vendors. Health Canada's regulatory alignment with FDA premarket approval pathways reduces validation duplication for cross-border diagnostic submissions. Toronto's MaRS Discovery District clusters precision medicine startups alongside hospital-affiliated research institutes.
Mexico
Private hospital chains in Mexico City and Monterrey are deploying next-generation sequencing for oncology patient stratification, driven by medical tourism demand and domestic affluent patient segments. COFEPRIS regulatory modernization is shortening import authorization timelines for FDA-approved companion diagnostics. Guadalajara's pharmaceutical manufacturing corridor is attracting contract research organizations for biomarker-directed clinical trials.
North America Precision Medicine Market Competitive Landscape
On the supply side, the industry is consolidating around integrated workflow vendors that bundle capital equipment, consumables, and interpretation services under multi-year health system contracts. Three strategic archetypes dominate: sequencing platform manufacturers with installed base leverage, diagnostic-therapeutic alliance builders, and liquid biopsy specialists with community oncology penetration. Competitive moves center on project finance partnerships with health systems and single-source procurement consolidation.
Within the platform manufacturer tier, Illumina and Thermo Fisher Scientific occupy positions defined by recurring consumable revenue models and sequencing infrastructure lock-in. Among therapeutic-diagnostic alliance builders, Pfizer exemplifies the strategy of aligning pipeline development with companion diagnostic regulatory pathways. These three companies represent how vertical control over sequencing-to-therapy workflows is displacing point-solution vendors in hospital procurement decisions.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| Pfizer |
| Novartis |
| QIAGEN |
| AstraZeneca |
| Bristol-Myers Squibb |
| Guardant Health |
| Others |
Pricing and Supply Chain Analysis
California's Bay Area biotech corridor concentrates sequencing instrument manufacturing and consumable production, translating capacity scarcity into sustained pricing leverage for platform vendors across North American health system procurement cycles.
Pricing Analysis
Certification level (FDA-grade CLIA/CAP versus research-use-only) creates the primary spread between premium clinical-grade sequencing services and economy-tier reference laboratory offerings. Three-tier pricing structure across premium, standard, and economy levels dominates, with volume scale and after-sales interpretation bundling as secondary differentiation drivers. Pricing pressure stems from CMS coverage determination lags for novel molecular test categories, compressing margins in the standard tier. Community oncology practices exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize workflow integration over unit cost.
Supply Chain Analysis
Contract manufacturing for flow-cell chemistry concentrates with Thermo Fisher Scientific and Illumina captive production facilities, supplemented by specialized reagent formulators in Massachusetts and North Carolina. Geographic supply concentration centers on the United States, Germany, and Singapore for precision optics and semiconductor components essential to sequencing platforms. Raw material dependencies include high-purity silicon wafers, fluorescent nucleotides, and polymerase enzymes. Single-source vulnerability in specialized enzyme supply creates exposure to batch contamination risks. Distribution runs through direct health system contracts and group purchasing organization frameworks, with independent reference laboratories increasingly excluded from hospital outpatient department access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from artificial intelligence-enabled diagnostic platforms that promise equivalent clinical utility without capital-intensive sequencing infrastructure.
For Market Incumbents: Entrench installed base leverage by extending consumable lock-in through multi-year reagent supply agreements with academic medical centers. Deepen backward integration into proprietary enzyme manufacturing to insulate against supplier concentration risk. Prioritize CAP/CLIA certification investment for variant interpretation pipelines to maintain regulatory moats against algorithmic substitutes. For New Entrants and Emerging Players: Pursue white-space penetration in Ohio and Michigan health systems where molecular testing infrastructure remains underdeveloped relative to coastal corridors. Target community oncology practices in Texas and Florida with liquid biopsy platforms that bypass capital equipment requirements. Deploy platform-as-a-service models bundling sequencing access with interpretation software to reduce customer capital barriers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because health system procurement committees are consolidating contracts under single-source integrated workflow vendors, compressing independent laboratory valuations. Acquisition target archetype: mid-cap bioinformatics specialists with FDA-aligned quality management systems and hospital system reference contracts. Signal to watch: CMS national coverage determination velocity for multi-cancer early detection assays as inflection indicator for reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Regulatory Alignment | FDA Center for Devices and Radiological Health premarket approval compresses therapeutic-diagnostic co-development timelines. |
| Health System Partnership Consolidation | Single-source procurement agreements in Philadelphia and Baltimore networks displace independent reference laboratory access. |
| Liquid Biopsy Platform Expansion | Community oncology practices in Texas and Florida adopt circulating tumor DNA monitoring at twice academic center rates. |
| Multi-Omics Data Integration | Real-world evidence platforms combining proteomic and metabolomic datasets open immunology indication categories. |
| State Medicaid Coverage Expansion | California and New York supplemental payment programs extend molecular testing access to underserved populations. |
Research Methodology
Desk research of FDA premarket approval filings, CMS national coverage determinations, and hospital procurement databases preceded structured interviews with molecular pathology laboratory directors, health system supply chain executives, companion diagnostic regulatory affairs leads, and payer medical policy specialists. Primary fieldwork across Boston, Houston, and California's Bay Area biotech corridor validated secondary estimates of sequencing infrastructure deployment and consumable utilization patterns. Bottom-up health system contract analysis triangulated against top-down market sizing from instrument installation bases and reagent throughput estimates.
Assumptions held fixed include FDA accelerated approval pathway continuity, IRA biomarker-defined reimbursement incentive structures, and HIPAA genomic data exchange constraint persistence across the projection horizon. Segmentation dimensions modeled encompass product type (genomics, diagnostics, therapeutics, data analytics), end user (hospitals, research laboratories, biotechnology companies, pharmaceutical firms), delivery mode (online platforms, laboratory services, mobile applications, clinical settings), and technology (next-generation sequencing, CRISPR, bioinformatics, personalized vaccines). CAGRs derived from logistic diffusion curves fitted to sequencing adoption S-cycles, adjusted for health system capital budget cyclicality and companion diagnostic approval velocity.
Macroeconomic conditions sit as an overlay; deviation in NIH research funding allocations, hospital capital expenditure cycles, or pharmaceutical R&D prioritization would shift the trajectory. Forecasts reflect assumptions regarding regulatory pathway stability and reimbursement expansion velocity. Quarterly review of FDA companion diagnostic approval cadence, CMS coverage determination timelines, and health system procurement committee consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market