
 Cardiomyopathy Medication Market | 2026-2036
Cardiomyopathy Medication Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiomyopathy Medication Market Analysis
Small molecule active pharmaceutical ingredients are shifting toward synthetic biology-derived production platforms, reducing cost volatility in upstream supply. Bristol Myers Squibb leverages its integrated cardiovascular franchise to sustain manufacturing scale across beta blocker and anticoagulant portfolios. Cytokinetics anchors its position through specialized development of cardiac myosin inhibitors for hypertrophic cardiomyopathy. Pfizer Inc. competes via global distribution infrastructure that controls hospital and clinic channel access across multiple therapy areas.
Cardiomyopathy medication encompasses pharmaceutical agents designed to modulate cardiac contractility, reduce afterload, prevent thromboembolic events, or slow disease progression in structurally abnormal myocardium, with formulations typically requiring precise dosing titration based on ejection fraction and NYHA functional class. These therapies serve the primary commercial purpose of reducing heart failure hospitalizations and extending survival in patients with dilated, hypertrophic, restrictive, or ischemic cardiomyopathy subtypes. Beta blockers occupy the largest volume position due to decades of mortality data and guideline endorsement, while anticoagulants capture disproportionate margin pools in atrial fibrillation comorbidity segments. Injectable delivery modes are expanding fastest in acute decompensated settings, though oral formulations dominate maintenance therapy economics across outpatient cardiology practices.
The FDA's Breakthrough Therapy designation and EMA's PRIME scheme are compressing regulatory timelines for novel cardiomyopathy mechanisms, reshaping how developers prioritize pivotal trial endpoints. REACH compliance and ISO 13485 standards govern excipient sourcing and device-drug combination manufacturing for infusion and transdermal formats, respectively. Stakeholders must monitor how CMS national coverage determinations and NICE technology appraisals diverge on novel therapy value thresholds, as this will dictate geographic launch sequencing and access negotiations.
Market Dynamics
Hospital systems are consolidating cardiovascular service lines around dedicated heart failure units, creating concentrated purchasing power that reshapes how manufacturers negotiate formulary placement and infusion capacity contracts.
Growth Catalysts
- FDA Accelerated Approval:The FDA's Breakthrough Therapy designation compresses pivotal trial timelines for novel cardiac myosin inhibitors. Developers redirect R&D budgets toward mechanism-first cardiovascular programs.
- Medicare Reimbursement Structures:CMS national coverage determinations for specialty cardiology procedures sustain premium therapy access in United States outpatient practices. Hospital systems expand dedicated heart failure units to capture this reimbursement.
- Synthetic Biology Platforms:Small molecule API production shifts toward engineered microbial systems. Cost volatility in upstream supply chains diminishes as manufacturers internalize fermentation capacity.
Market Restraints
- API Supply Concentration:Beta blocker and anticoagulant active pharmaceutical ingredients concentrate among Asian fermentation specialists. Geopolitical friction threatens just-in-time inventory models for chronic therapy maintenance.
- REACH Compliance Burden:European excipient sourcing faces ECHA scrutiny on novel chemical entities. Registration timelines extend 18-24 months for infusion-grade polymers and transdermal adhesives.
- Generic Substitution Pressure:Guideline-endorsed beta blockers face commoditization as patent cliffs mature. Formulary managers at United States pharmacy benefit managers drive toward therapeutic equivalence protocols.
Strategic Opportunities
- Injectable Home Infusion:Subcutaneous loop diuretic formulations enable acute decompensated heart failure management outside hospital walls. United States home health agencies build cardiovascular nursing capacity to capture this shift.
- EMA PRIME Scheme:European priority medicines status offers conditional approval pathways for rare cardiomyopathy subtypes. Developers sequence EU launches ahead of NICE technology appraisals.
- Device-Drug Combinations:Wearable sensors integrated with implantable cardioverter-defibrillators enable closed-loop medication titration. Cardiac electrophysiology labs become the channel for these convergence products.
Industry Challenges
- NYHA Functional Class Stratification:Clinical trial enrollment requires precise ejection fraction categorization and symptom severity documentation. Contract research organizations struggle to recruit sufficiently granular patient cohorts.
- ISO 13485 Device Integration:Combination product manufacturing demands dual compliance with pharmaceutical GMP and medical device quality standards. Facility retrofitting timelines extend validation cycles.
- Specialty Pharmacy Distribution:Oral maintenance therapies fragment across limited-distribution networks. Manufacturers manage channel conflict between hospital outpatient departments and mail-order dispensers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiomyopathy Medication Market |
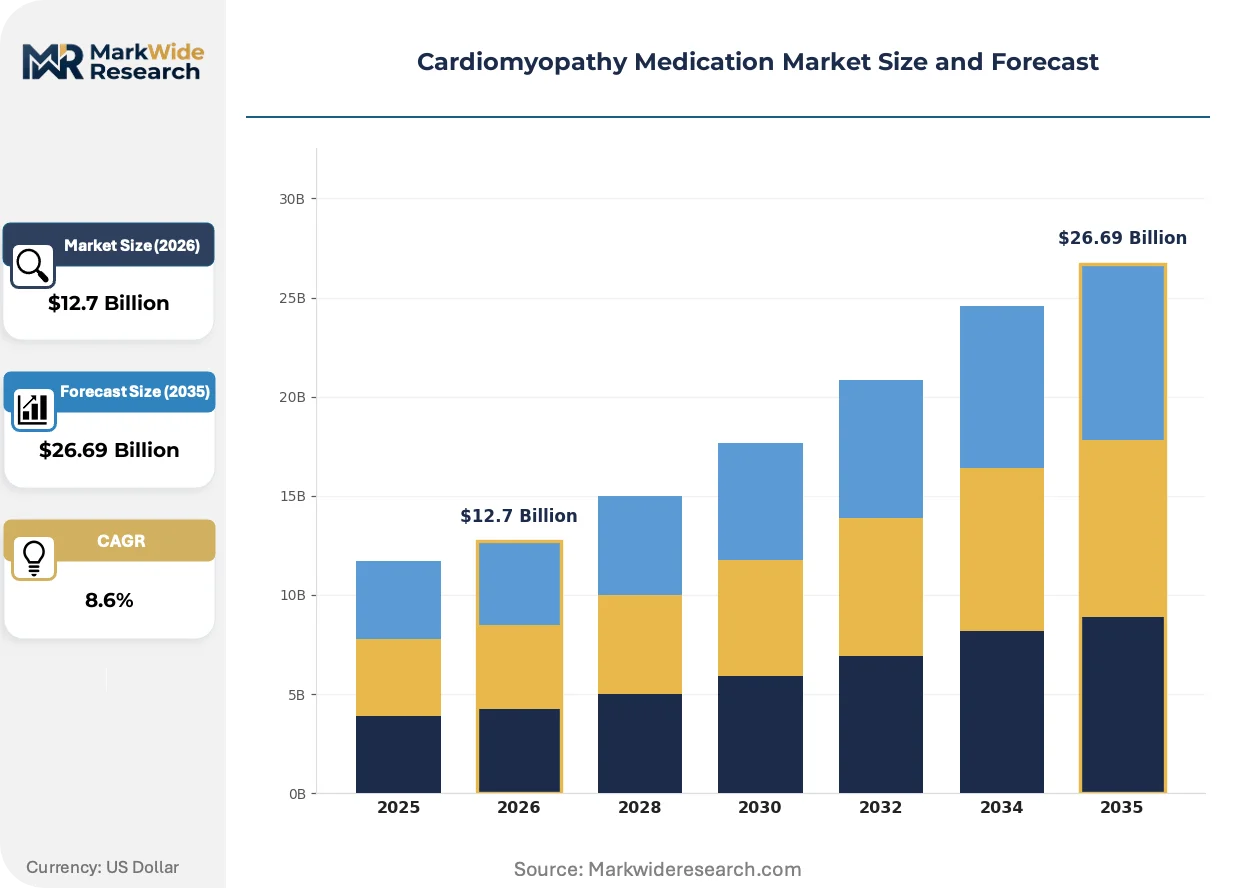
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta Blockers, ACE Inhibitors, Angiotensin Receptor Blockers, Anticoagulants Therapy Area: Ischemic Cardiomyopathy, Hypertrophic Cardiomyopathy, Dilated Cardiomyopathy, Restrictive Cardiomyopathy Delivery Mode: Oral, Injectable, Infusion, Transdermal End User: Hospitals, Clinics, Homecare, Long-term Care Facilities |
| Companies Covered | Bristol Myers Squibb, Cytokinetics, Pfizer Inc., AstraZeneca, Novartis AG, Merck & Co., Inc., Sanofi, Boehringer Ingelheim, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiomyopathy Medication Market Emerging Trajectories
Cardiomyopathy therapeutics are converging around precision dosing algorithms and care delivery models that compress the interval between decompensation detection and intervention.
Artificial intelligence-enabled echocardiography interpretation is automating ejection fraction quantification and strain analysis. United States academic medical centers deploy these tools in emergency departments to triage acute dyspnea presentations. The technology is automating referral decisions to heart failure specialists, compressing time-to-therapy initiation.
EMA's PRIME scheme and FDA's Breakthrough Therapy designation are compressing regulatory timelines for novel mechanisms. Developers prioritize surrogate endpoints like N-terminal pro-BNP reduction over hard mortality outcomes. Hypertrophic cardiomyopathy specialists in European reference centers accelerate patient access through compassionate use pathways.
Integrated practice units are consolidating cardiovascular care around condition-specific value metrics. United States accountable care organizations bundle heart failure hospitalization rates with outpatient medication adherence scores. Specialty cardiology referral networks in Medicare Advantage plans now compete on total cost of care rather than procedural volume alone.
Cardiomyopathy Medication Market Segmentation
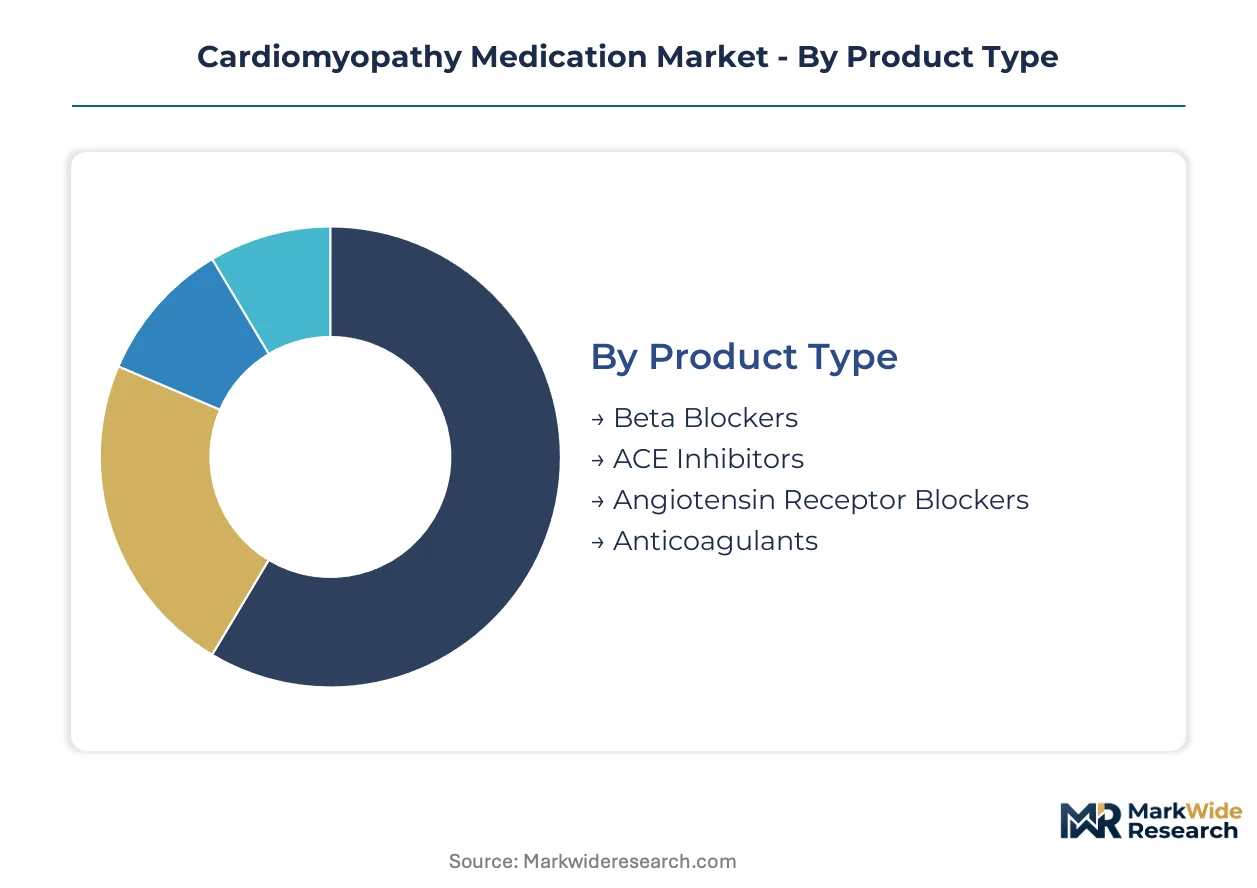
Cardiomyopathy medication markets fragment across mechanism of action, disease substrate, and care setting. Each dimension carries distinct margin profiles and regulatory pathways that reshape competitive positioning.
Product Type:
Beta blockers anchor volume economics while anticoagulants command premium positioning in comorbid atrial fibrillation segments.
- Beta Blockers:Carvedilol, metoprolol succinate, and bisoprolol formulations reduce sympathetic drive and reverse adverse remodeling. United States Medicare Part D formularies prioritize these agents for NYHA Class II-III patients, though generic substitution erodes branded pricing power.
- Anticoagulants:Direct oral anticoagulants and warfarin derivatives prevent thromboembolic events in dilated cardiomyopathy with reduced ejection fraction. Hospital outpatient departments in the United States capture disproportionate margin pools when atrial fibrillation complicates the primary cardiomyopathy diagnosis.
- ACE Inhibitors:Ramipril and lisinopril remain foundational for afterload reduction in systolic dysfunction.
- Angiotensin Receptor Blockers:Losartan and valsartan serve as ACE inhibitor alternatives in intolerant patients.
Today's leader: Beta Blockers. Tomorrow's challenger: Anticoagulants.
Therapy Area:
Disease substrate determines trial design complexity and addressable patient pools.
- Hypertrophic Cardiomyopathy:Cardiac myosin inhibitors target sarcomeric protein mutations with precision mechanisms. FDA Breakthrough Therapy designations compress development timelines for novel agents in this historically underserved population.
- Ischemic Cardiomyopathy:Post-infarction remodeling drives the largest absolute patient volume. United States hospital systems bundle revascularization procedures with guideline-directed medical therapy to capture accountable care organization bonuses.
- Dilated Cardiomyopathy:Genetic and idiopathic forms require chronic neurohormonal blockade.
- Restrictive Cardiomyopathy:Amyloidosis and fibrotic subtypes present limited pharmacologic options.
Hypertrophic cardiomyopathy attracts R&D investment fastest. Ischemic cardiomyopathy sustains revenue scale.
Delivery Mode:
Route of administration separates acute intervention economics from chronic maintenance margins.
- Injectable:Subcutaneous loop diuretics and inotropic agents enable acute decompensated heart failure management outside hospital walls. United States home health agencies build cardiovascular nursing capacity to capture this shift from inpatient admissions.
- Oral:Once-daily beta blocker and ACE inhibitor formulations dominate maintenance therapy economics across outpatient cardiology practices.
- Infusion:Inotropes and vasodilators require hospital-based administration.
- Transdermal:Nitroglycerin patches serve residual angina symptoms.
Oral formulations defend volume leadership. Injectable modalities are expanding most quickly.
End User:
Care setting concentration shapes contracting leverage and patient monitoring intensity.
- Hospitals:Dedicated heart failure units consolidate purchasing power for infusion therapies and device-drug combinations. CMS reimbursement for acute decompensated episodes incentivizes readmission reduction programs.
- Homecare:Telemonitoring-enabled medication titration extends specialist reach into rural United States markets.
- Clinics:Outpatient cardiology practices manage stable chronic therapy.
- Long-term Care Facilities:Polypharmacy management challenges dominate this segment.
Hospitals control premium access. Homecare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialty cardiology referral networks concentrate demand for premium cardiomyopathy therapies, with Medicare reimbursement structures sustaining access to novel cardiac myosin inhibitors and device-drug combinations.
United States
Hospital systems in Boston and Cleveland expand dedicated heart failure units to capture CMS accountable care organization bonuses. FDA Breakthrough Therapy designations compress development timelines for hypertrophic cardiomyopathy candidates. The Mayo Clinic Rochester anchors a Midwest referral cluster that triages complex cases from rural catchment areas.
Germany
EMA PRIME scheme accelerates conditional approval for rare cardiomyopathy subtypes, positioning Munich and Heidelberg university hospitals as early-access centers. REACH compliance governs excipient sourcing for infusion-grade polymers. The Rhine-Main biotech corridor concentrates contract manufacturing for cardiac myosin inhibitor APIs.
Japan
PMDA's Sakigake designation fast-tracks novel cardiovascular mechanisms, with Tokyo and Osaka academic centers enrolling precision-medicine trials. METI subsidizes domestic fermentation capacity for beta blocker active pharmaceutical ingredients. The Kansai region hosts specialized pharmacovigilance operations for aging-population dosing studies.
Switzerland
Swissmedic's proximity to EMA enables parallel regulatory submissions for hypertrophic cardiomyopathy therapies. Basel's pharmaceutical cluster integrates precision diagnostics with therapeutic development. Geneva university hospitals pilot device-drug combination protocols for implantable cardioverter-defibrillator integration.
India
CDSCO's accelerated approval pathway for unmet cardiovascular needs attracts contract research organizations to Hyderabad and Bengaluru. The PLI scheme incentivizes domestic API production for beta blockers and anticoagulants. Maharashtra's specialty hospital networks build heart failure units to manage rising ischemic cardiomyopathy burdens.
Cardiomyopathy Medication Market Vendor Landscape
Global majors compete with regional champions across regulatory access and hospital channel control. The market structures around three tiers: integrated pharmaceutical conglomerates with cardiovascular franchises, specialized biotech developers focused on rare cardiomyopathy mechanisms, and generic manufacturers capturing commoditized beta blocker volume. Dominant competitive moves include strategic partnerships for device-drug combination development and backward integration into synthetic biology-derived API production.
Within the integrated pharmaceutical tier, Bristol Myers Squibb and Pfizer Inc. occupy positions sustained by global distribution infrastructure and hospital formulary relationships. Cytokinetics exemplifies the specialized biotech archetype, anchoring its competitive position through cardiac myosin inhibitor development for hypertrophic cardiomyopathy. These three companies represent distinct strategic approaches: scale-driven channel control, mechanism-first specialization, and portfolio breadth across cardiovascular therapy areas.
| Leading Market Players |
|---|
| Bristol Myers Squibb |
| Cytokinetics |
| Pfizer Inc. |
| AstraZeneca |
| Novartis AG |
| Merck & Co., Inc. |
| Sanofi |
| Boehringer Ingelheim |
| Amgen Inc. |
| Others |
Supply Flow & Price Mechanics
REACH compliance gates qualified excipient supply and premium-tier pricing access for infusion-grade polymers and transdermal adhesives in European markets. Manufacturers bearing ECHA registration costs pass these through to hospital formulary contracts, while Asian fermentation specialists without equivalent environmental mandates capture commoditized beta blocker volume at lower price points.
Pricing Analysis
Input-cost pass-through from synthetic biology platform investments is reshaping contract structures for cardiac myosin inhibitors. Three-tier pricing structure across premium, standard, and economy levels separates FDA Breakthrough-designated therapies from guideline-endorsed beta blockers and mature generic anticoagulants. Price differentiation hinges on NYHA functional class stratification and ejection fraction monitoring requirements. Pricing pressure stems from pharmacy benefit manager therapeutic equivalence protocols in United States Medicare Part D, with generic substitution most intense in chronic maintenance segments.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate qualified backup suppliers for beta blocker and anticoagulant active pharmaceutical ingredients. Manufacturing concentrates in India, China, and Switzerland for fermentation-derived small molecules and synthetic cardiac myosin inhibitor precursors. Raw material dependencies include engineered microbial strains, chromatography resins, and infusion-grade polymers. Single-source vulnerability threatens just-in-time inventory models when geopolitical friction disrupts Asian fermentation specialist output. Distribution runs through specialty pharmacy networks and hospital outpatient departments for oral maintenance therapies, with home health agencies capturing expanding injectable volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardiomyopathy medication market compounds steadily as aging demographics expand the addressable heart failure population. Hospital system consolidation around dedicated heart failure units creates predictable demand anchors for manufacturers with established formulary positions.
For Market Incumbents: Extend manufacturing scale advantages through backward integration into synthetic biology-derived API production. Bristol Myers Squibb and Pfizer Inc. should lock in fermentation capacity ahead of CDSCO PLI scheme expansions in India. Defend channel control by embedding cardiovascular nursing capacity within United States home health agency partnerships, neutralizing mail-order pharmacy fragmentation.
For New Entrants and Emerging Players: FDA Breakthrough Therapy designation in the United States opens a window for mechanism-first developers to command premium pricing before generic substitution pressures mature. Target hypertrophic cardiomyopathy as the most penetrable precision-medicine segment with historically underserved sarcomeric mutation populations. Pursue compassionate use pathway enrollment at Mayo Clinic Rochester and Cleveland Clinic to generate real-world evidence ahead of formal reimbursement negotiations.
For Investors and Strategic Acquirers: Roll-up economics work for specialized cardiac myosin inhibitor developers because FDA accelerated approval pathways compress development timelines and create near-term value inflection points. Focus acquisition screening on biotechs with Phase II hypertrophic cardiomyopathy data and existing EMA PRIME scheme engagement. Watch CMS national coverage determinations for novel therapy categories as the signal indicating when premium pricing power will stabilize or erode.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Compresses pivotal trial timelines for cardiac myosin inhibitors in hypertrophic cardiomyopathy. |
| Backward Integration into Synthetic Biology Platforms | Reduces cost volatility for small molecule API production in beta blocker portfolios. |
| Hospital System Partnership for Heart Failure Units | Secures concentrated purchasing power for infusion therapies and device-drug combinations. |
| EMA PRIME Scheme Engagement | Enables conditional approval pathways for rare cardiomyopathy subtypes in European reference centers. |
| Home Health Agency Nursing Capacity Buildout | Captures shift from inpatient admissions to subcutaneous loop diuretic administration. |
Methodological Framework
Bottom-up hospital and clinic demand modeling reconciled against top-down API production capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers informed market structure assumptions. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Cross-referencing manufacturer capacity disclosures with hospital system expansion announcements enabled supply-demand balance assessment across the projection horizon.
Input-output matrices mapped cardiac myosin inhibitor development pipelines against heart failure unit bed expansion plans in United States academic medical centers. Segmentation modeling covered mechanism of action, disease substrate, delivery mode, and care setting dimensions. CAGRs were derived from patient volume epidemiology and therapy penetration assumptions. Forecast inputs included NYHA functional class distribution shifts and Medicare Advantage plan concentration trends.
Revisions become necessary when FDA accelerated approval pathways expand to additional cardiomyopathy mechanisms or when REACH compliance timelines extend beyond current ECHA projections. Deviation in CMS national coverage determination thresholds for novel cardiac therapies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiology Equipment
Cardiotoxicity Market
Cardiology Equipment
Global Extracorporeal Membrane Oxygenation Machine Market
Cardiology Equipment
Intracardiac Echocardiography (ICE) Market
Cardiology Equipment
Arrhythmia Market
Cardiology Equipment
Europe Cardiac Monitoring Market
Cardiology Equipment
Medical Smart Stethoscopes Market
Cardiology Equipment
North America Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Monitoring Market
Cardiology Equipment
Global Cardiac Mapping Market
Cardiology Equipment
Asia-Pacific Cardiac Monitoring Market
Cardiology Equipment
Cardiac Ultrasound Systems Market
Cardiology Equipment
Europe Electrophysiology Market
Cardiology Equipment
Cardiac Marker Analyzer Market
Cardiology Equipment
Global Stethoscope Market
Cardiology Equipment
Wireless Cardiac Monitoring Systems Market
Cardiology Equipment
Global Cardiology Electrodes Market