
 Global Autism Spectrum Disorders Treatment Market | 2026-2036
Global Autism Spectrum Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autism Spectrum Disorders Treatment Market Foresight
The split between premium biologic interventions and commodity behavioral protocols is realigning how providers structure care pathways. Johnson & Johnson Services Inc. leverages its neuroscience portfolio to anchor premium positioning in pharmaceutical interventions. Otsuka Pharmaceutical Co., Ltd. competes through specialized psychiatric expertise in pediatric formulations. Bristol-Myers Squibb Company differentiates via extended R&D pipelines targeting comorbid conditions alongside core ASD symptoms.
Autism spectrum disorders treatment encompasses pharmacological, behavioral, and technology-mediated interventions designed to modify neurodevelopmental trajectories, improve adaptive functioning, and reduce core deficits in social communication and restricted or repetitive behaviors. Medication segments targeting irritability and attention deficits sustain mature revenue bases, while behavioral therapy occupies the largest service volume share across institutional and home settings. Teletherapy platforms within the technology segment represent the fastest-growing delivery mechanism, though margin pools remain concentrated in wearable devices that generate continuous biometric data streams for personalized intervention adjustment.
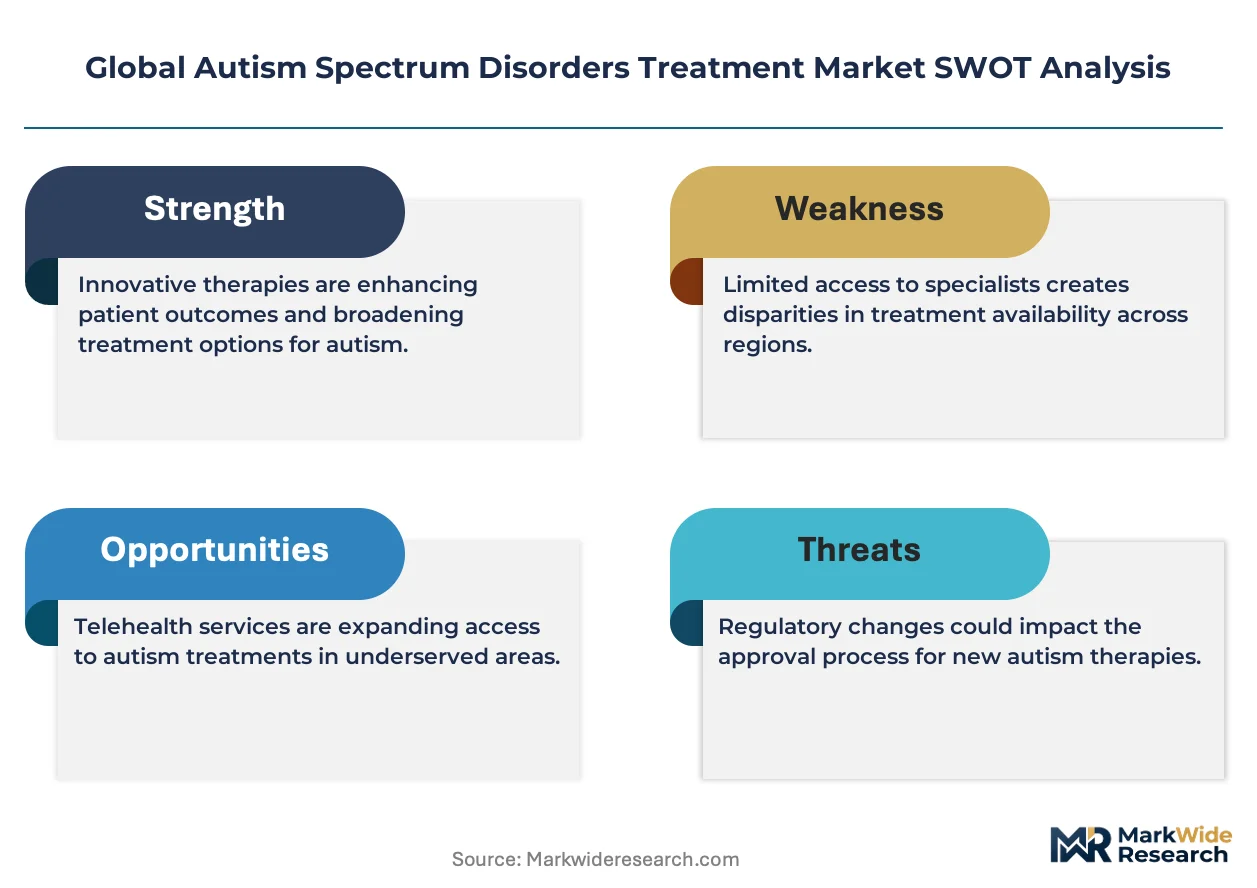
FDA breakthrough therapy designations and EMA pediatric investigation plans are compressing development timelines for novel ASD therapeutics, while HIPAA compliance requirements shape how digital platforms collect and share patient data across care teams. WHO neurodevelopmental disorder classification updates and national insurance parity mandates in Germany, Japan, and Australia are expanding reimbursable service categories. Stakeholders must monitor evolving regulatory distinctions between wellness applications and clinical-grade digital therapeutics as enforcement priorities shift.
Market Dynamics
FDA breakthrough therapy designations and EMA pediatric investigation plans are compressing development timelines for novel ASD therapeutics, while HIPAA compliance requirements shape how digital platforms collect and share patient data across care teams. This regulatory acceleration is colliding with capacity constraints in specialized behavioral therapy delivery.
Growth Catalysts
- Insurance Parity Mandates:Germany, Japan, and Australia have expanded reimbursable service categories for neurodevelopmental interventions. Commercial payers in these markets now cover behavioral therapy protocols previously excluded from standard benefits.
- Pediatric Clinic Expansion:Specialized academic medical hubs in California and regional autism center networks are adding behavioral therapy capacity to serve rising patient volumes. These institutional investments create fixed infrastructure for sustained service delivery.
- Teletherapy Platform Maturation:HIPAA-compliant digital delivery mechanisms are extending reach into rural and underserved geographies. Platform providers are integrating continuous biometric data streams from wearable devices to enable personalized intervention adjustment.
Market Restraints
- Specialized Workforce Scarcity:Board-certified behavior analysts and developmental pediatricians remain concentrated in urban academic medical centers. Training pipeline limitations constrain service expansion regardless of capital availability.
- Reimbursement Rate Compression:Medicaid programs in multiple US states have reduced per-session behavioral therapy rates. Public payer constraints limit provider margin sustainability and capital reinvestment capacity.
- Diagnostic Bottlenecks:Wait times for comprehensive developmental evaluations exceed twelve months in multiple metropolitan areas. Delayed diagnosis postpones treatment initiation and compresses effective intervention windows.
Strategic Opportunities
- Comorbidity-Targeted Development:Extended R&D pipelines addressing anxiety, sleep disturbance, and gastrointestinal symptoms alongside core ASD deficits represent underserved clinical need. Regulatory pathways for these indications remain less crowded than irritability-focused submissions.
- Home-Based Technology Integration:Wearable devices generating continuous biometric data streams are enabling remote monitoring and intervention adjustment. This convergence of hardware and clinical service delivery opens new reimbursement categories.
- EU Pediatric Investigation Plans:EMA incentives for early pediatric study design are accelerating orphan indication approvals. Sponsors leveraging these frameworks gain competitive positioning in European markets with harmonized national reimbursement.
Industry Challenges
- Interoperability Standards Fragmentation:Digital therapeutic platforms lack unified data exchange protocols with electronic health record systems. Integration complexity increases implementation costs and limits care coordination effectiveness.
- Regulatory Classification Uncertainty:Enforcement priorities are shifting between wellness applications and clinical-grade digital therapeutics. Platform developers face compliance risk from evolving FDA and EMA distinctions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autism Spectrum Disorders Treatment Market |
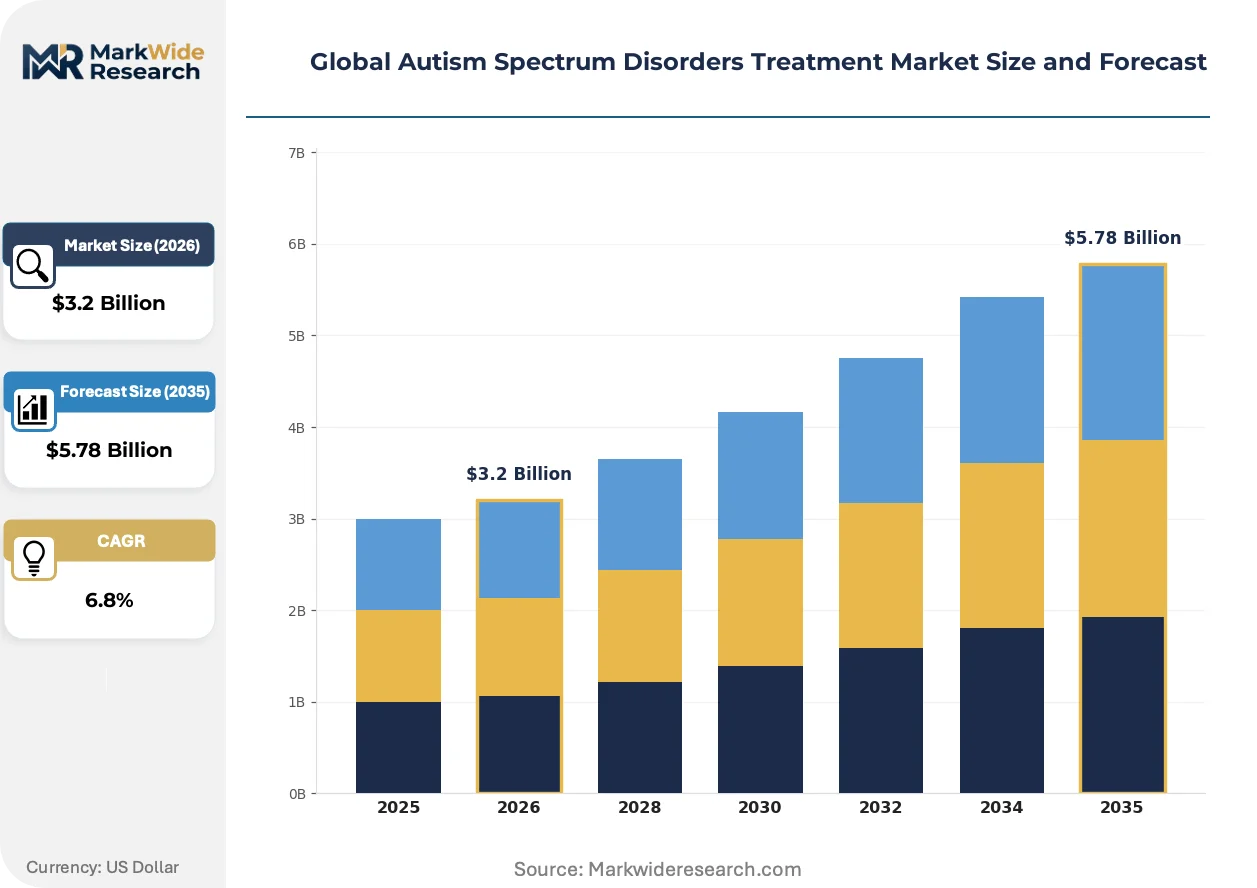
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Behavioral Therapy, Speech Therapy, Occupational Therapy End User: Hospitals, Clinics, Home Care, Educational Institutions Delivery Mode: Oral, Injectable, Inhalation, Transdermal Technology: Teletherapy, Mobile Applications, Wearable Devices, Digital Platforms |
| Companies Covered | Johnson & Johnson Services Inc., Otsuka Pharmaceutical Co., Ltd., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd., Novartis AG, Merck & Co., Inc., Pfizer Inc., Eli Lilly and Company, Curemark LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autism Spectrum Disorders Treatment Market Shifts & Advancements
Teletherapy platforms are modularizing service delivery architecture while regulatory frameworks accelerate therapeutic development timelines. These shifts are compressing traditional care pathway structures and enabling new competitive entry points.
Artificial intelligence-driven adaptive learning systems are modularizing behavioral intervention protocols. Pediatric clinics and home-based service providers are adopting these platforms to extend therapist capacity and standardize protocol fidelity. The technology is modularizing previously labor-intensive components of applied behavior analysis delivery, enabling non-specialist personnel to execute supervised intervention elements under remote clinical oversight.
EMA pediatric investigation plans and FDA breakthrough therapy designations are compressing neurodevelopmental drug development timelines. Sponsors receiving these designations gain accelerated review access and enhanced regulatory engagement, reducing time-to-market for novel mechanisms. Small-molecule and biologic developers targeting irritability and social communication deficits are prioritizing these pathways, with European and North American applications dominating current submissions.
Caregiver-directed intervention models are displacing clinic-exclusive delivery in early childhood segments. Medicaid programs and commercial payers in the United States are expanding reimbursement for parent-mediated protocols delivered through telehealth platforms. This behavioral shift is most visible in California's regional autism center networks, where hybrid models combining digital coaching with periodic in-person assessment are replacing traditional weekly clinic visits.
Global Autism Spectrum Disorders Treatment Market Segmentation
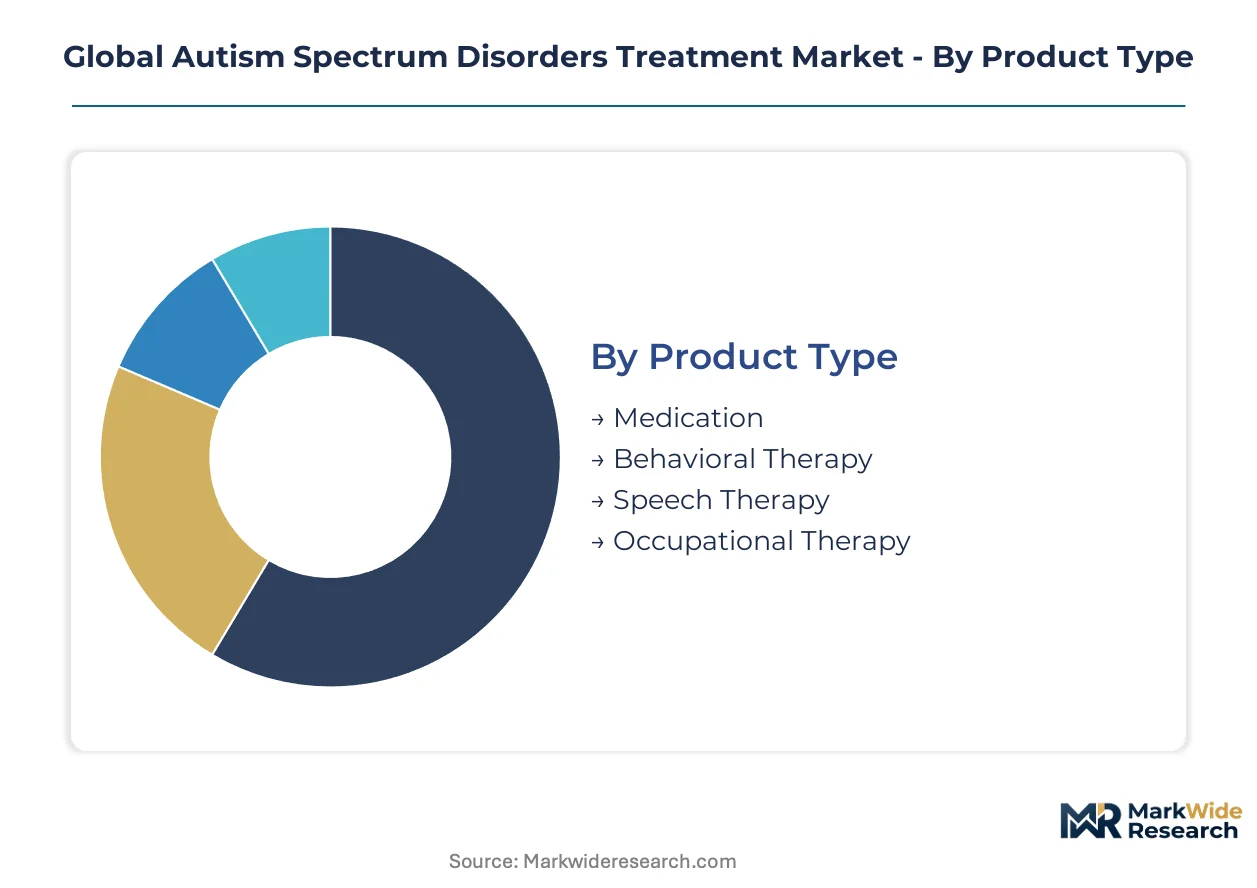
ASD treatment segmentation reveals how therapeutic modalities, delivery settings, and digital infrastructure compete for patient access and reimbursement dollars. Product type and technology dimensions show the clearest divergence between pharmaceutical margin pools and service volume expansion.
Product Type:
Formulation chemistry and mechanism of action separate maintenance therapies from breakthrough candidates in clinical pipelines.
- Medication:Small-molecule and biologic formulations targeting irritability, hyperactivity, and core social communication deficits. FDA breakthrough therapy designations are compressing review timelines for novel mechanisms. Demand concentrates in academic medical centers with specialized psychopharmacology units, though Medicaid rate compression constrains provider margin sustainability.
- Behavioral Therapy:Applied behavior analysis and developmental relationship-based interventions delivered through structured protocols. Board-certified behavior analysts execute discrete trial training and naturalistic developmental behavioral interventions. California's regional autism center networks and pediatric clinics across the United States are expanding capacity to serve rising patient volumes.
- Speech Therapy:Communication-focused interventions addressing receptive and expressive language deficits.
- Occupational Therapy:Sensory integration and adaptive skill development for daily living functions.
Behavioral therapy leads on scale; teletherapy-integrated medication protocols lead on momentum.
End User:
Site-of-care economics and regulatory jurisdiction create distinct operational requirements for service delivery.
- Hospitals:Inpatient and outpatient psychiatric units managing severe behavioral crises and medication initiation. Comprehensive medical infrastructure supports complex comorbidity management. Demand concentrates in specialized academic medical hubs with dedicated neurodevelopmental disorder programs.
- Clinics:Outpatient behavioral health centers and developmental pediatric practices. Pediatric clinics leverage standardized assessment protocols and therapist supervision hierarchies. Wait times for comprehensive evaluations exceed twelve months in multiple metropolitan areas, compressing effective intervention windows.
- Home Care:Caregiver-directed interventions and telehealth-supported protocols.
- Educational Institutions:School-based services mandated under individualized education programs.
Clinics lead on scale; home care leads on momentum.
Delivery Mode:
Pharmacokinetic profiles and patient compliance requirements determine route selection for psychotropic and adjunctive therapies.
- Oral:Tablets, capsules, and liquid formulations for daily maintenance dosing. Immediate-release and extended-release profiles address attention deficits and irritability across pediatric and adult populations. Commercial payers in Germany, Japan, and Australia have expanded reimbursable categories for oral neurodevelopmental medications.
- Injectable:Long-acting formulations reducing adherence barriers for patients with severe behavioral disturbances.
- Inhalation:Pulmonary delivery for acute agitation management.
- Transdermal:Patch-based delivery for steady-state plasma levels with reduced gastrointestinal side effects.
Oral formulations lead on scale; long-acting injectables lead on momentum.
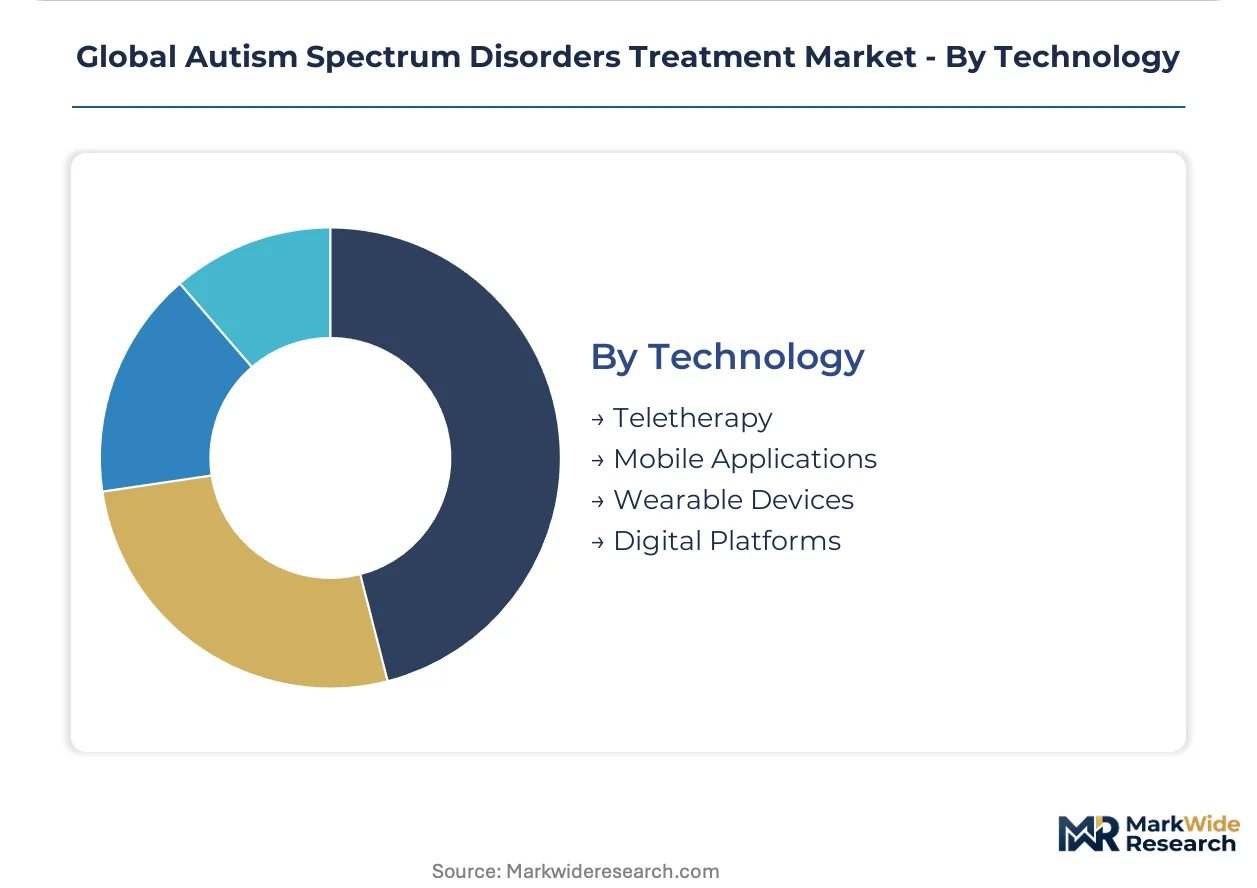
Technology:
Hardware-software integration depth separates wellness applications from clinical-grade digital therapeutics under evolving FDA and EMA enforcement priorities.
- Teletherapy:HIPAA-compliant video platforms extending behavioral intervention reach into rural and underserved geographies. Modular service delivery architecture enables remote clinical oversight of caregiver-directed protocols. California's regional autism center networks are replacing traditional weekly clinic visits with hybrid digital coaching models.
- Wearable Devices:Continuous biometric monitoring hardware generating data streams for personalized intervention adjustment. Accelerometers and heart rate sensors capture physiological stress indicators during daily activities. Margin pools concentrate in devices with validated clinical endpoints rather than consumer wellness positioning.
- Mobile Applications:Smartphone-based skill-building and communication support tools.
- Digital Platforms:Integrated care coordination systems linking patients, therapists, and prescribing clinicians.
Teletherapy leads on scale; wearable devices lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified behavior analysts and developmental pediatricians cluster in urban academic medical centers across the United States, Germany, and Japan, anchoring regional service capacity and shaping cross-border referral patterns for complex neurodevelopmental cases.
United States
Pediatric clinics in California and Texas are expanding applied behavior analysis capacity to serve rising patient volumes. FDA breakthrough therapy designations compress review timelines for novel neurodevelopmental drugs, while Medicaid programs in multiple states reduce per-session behavioral therapy rates. The regional autism center networks in California's Bay Area and Los Angeles County are replacing traditional weekly clinic visits with hybrid digital coaching models.
Germany
Specialized academic medical hubs in Bavaria and North Rhine-Westphalia manage severe behavioral crises through dedicated neurodevelopmental disorder programs. National insurance parity mandates expanded reimbursable service categories for behavioral therapy protocols previously excluded from standard benefits. EMA pediatric investigation plans accelerate orphan indication approvals, with sponsors in Frankfurt and Munich gaining competitive positioning in harmonized national reimbursement frameworks.
Japan
Developmental pediatricians concentrate in Tokyo and Osaka metropolitan areas, creating diagnostic bottlenecks with wait times exceeding twelve months. METI incentives support teletherapy platform maturation extending behavioral intervention reach into rural prefectures. PMDA regulatory pathways prioritize pediatric formulations, with pharmaceutical sponsors in Kansai and Kanto regions targeting irritability and social communication deficits.
Australia
Commercial payers expanded reimbursable categories for behavioral therapy and oral neurodevelopmental medications under national insurance parity reforms. TGA compliance requirements shape how digital platforms collect and share patient data across care teams. Specialized service delivery clusters in Sydney and Melbourne are integrating wearable devices generating continuous biometric data streams for personalized intervention adjustment.
United Kingdom
NHS England wait times for comprehensive developmental evaluations compress effective intervention windows in Greater London and Manchester. MHRA regulatory alignment with EMA pediatric investigation plans accelerates neurodevelopmental drug development timelines. Academic medical centers in Cambridge and Oxford anchor extended R&D pipelines addressing anxiety and sleep disturbance alongside core ASD symptoms.
Global Autism Spectrum Disorders Treatment Market Competitive Landscape
Capital-heavy pharmaceutical producers compete with asset-light digital therapeutic developers for patient access and reimbursement dollars. The vendor base separates into three tiers: diversified multinational conglomerates with neuroscience portfolios, specialized psychiatric pharmaceutical firms with pediatric formulation expertise, and emerging technology platforms with HIPAA-compliant delivery infrastructure. Dominant competitive moves include strategic partnerships between hardware wearable manufacturers and behavioral therapy providers, plus portfolio diversification into comorbidity-targeted indications beyond core ASD symptoms.
Within the diversified pharmaceutical tier, Johnson & Johnson Services Inc. and Bristol-Myers Squibb Company exemplify capital-intensive players leveraging extended R&D pipelines. Otsuka Pharmaceutical Co., Ltd. occupies a specialized position emphasizing psychiatric expertise in pediatric formulations. These three entities represent contrasting archetypes: the neuroscience-anchored conglomerate, the comorbidity-focused developer, and the pediatric formulation specialist.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Otsuka Pharmaceutical Co., Ltd. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Eli Lilly and Company |
| Curemark LLC |
| Others |
Supply & Pricing Matrix
Backward integration into behavioral therapy workforce development anchors both supply security and pricing power for institutional providers. California's regional autism center networks and pediatric clinics across the United States leverage captive training pipelines to offset Medicaid rate compression and sustain margin sustainability.
Pricing Analysis
The bundled-vs-unbundled service split separates medication management from behavioral therapy protocols in reimbursement frameworks. Three-tier pricing structure across premium biologic interventions, standard behavioral protocols, and economy telehealth coaching reflects FDA breakthrough therapy designations and workforce scarcity gradients. Price differentiation hinges on certification level of board-certified behavior analysts and geographic delivery cost to rural versus urban catchments. Pricing pressure stems from Medicaid per-session rate reductions in multiple US states, compressing provider margins. Public payer segments exhibit highest price sensitivity; self-funded employer plans and commercial insurers in Germany, Japan, and Australia show lowest sensitivity under expanded parity mandates.
Supply Chain Analysis
Specialized workforce supply rests on university training programs in the United States, Germany, and Japan, with board-certified behavior analyst pipelines concentrated in urban academic medical centers. Raw material dependencies include psychotropic active pharmaceutical ingredients, wearable sensor components, and HIPAA-compliant cloud infrastructure. Single-source vulnerability characterizes developmental pediatrician availability, with diagnostic wait times exceeding twelve months in Tokyo, Osaka, and multiple US metropolitan areas. Distribution runs through pediatric clinic networks, regional autism centers, and telehealth platforms extending into rural geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autism spectrum disorders treatment market functions as a regulatory compounder, with FDA breakthrough therapy designations and EMA pediatric investigation plans compressing development timelines and expanding reimbursable categories.
For Market Incumbents: Acquire teletherapy platform capabilities to offset workforce scarcity constraints and extend behavioral therapy reach into underserved geographies. Integrate wearable device data streams into clinical workflows to enable personalized intervention adjustment and defend against digital therapeutic entrants. Prioritize comorbidity-targeted R&D in anxiety and sleep disturbance to access less crowded regulatory pathways than irritability-focused submissions. For New Entrants and Emerging Players: Begin with caregiver-directed intervention models in early childhood segments, where Medicaid programs and commercial payers are expanding reimbursement for parent-mediated protocols delivered through telehealth platforms. Target California's regional autism center networks and hybrid digital coaching models as the most penetrable delivery architecture. Pursue strategic partnerships with hardware wearable manufacturers to access continuous biometric data streams and differentiate from commodity telehealth offerings. For Investors and Strategic Acquirers: Roll-up economics work for specialized psychiatric pharmaceutical firms with pediatric formulation expertise because EMA pediatric investigation plans and harmonized European reimbursement create scalable value-creation templates. Five-to-ten year viability hinges on regulatory exclusivity maintenance and pipeline diversification beyond core ASD symptoms. Monitor FDA enforcement priorities distinguishing wellness applications from clinical-grade digital therapeutics as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Accelerates review timelines for novel neurodevelopmental mechanisms targeting irritability and social communication deficits. |
| Behavioral Therapy Workforce Expansion | Pediatric clinics in California and Texas add capacity to serve rising patient volumes and reduce diagnostic bottlenecks. |
| Teletherapy Platform Integration | HIPAA-compliant digital delivery extends reach into rural geographies and enables remote clinical oversight of caregiver protocols. |
| Comorbidity-Targeted Pipeline Development | Extended R&D in anxiety and sleep disturbance accesses less crowded regulatory pathways than core ASD symptom submissions. |
| EU Pediatric Investigation Plan Leverage | EMA incentives accelerate orphan indication approvals with competitive positioning in harmonized national reimbursement frameworks. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged drug development executives at pharmaceutical sponsors, regulatory affairs leads navigating FDA and EMA pathways, formulary directors at commercial payers, and board-certified behavior analysts at pediatric clinics. Secondary sources included FDA breakthrough therapy designation filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov protocol registries, and national insurance parity mandate documentation. Bottom-up service volume estimates triangulated against top-down pharmaceutical revenue projections.
Rate-of-change decomposition separated volume growth from price and mix effects across the projection horizon. Segmentation dimensions modeled included product type, end user site-of-care, delivery mode, and technology integration depth, with regional regulatory clusters as an additional cross-cutting dimension. CAGRs derived from fitted trend analysis applied to historical reimbursement data and pipeline advancement timelines. Forecast inputs incorporated Medicaid rate compression trajectories and teletherapy platform adoption curves.
Several conditions sit outside the modeled scope, including unforeseen regulatory reclassification of digital therapeutics, abrupt shifts in commercial payer coverage policies, and disruptive therapeutic mechanisms advancing outside current pipeline visibility. Forecasts reflect documented assumptions about workforce training pipeline expansion and insurance parity mandate durability. A small set of named triggers warrants ongoing watch: FDA enforcement actions distinguishing wellness from clinical-grade applications, EMA pediatric investigation plan approval velocities, and state-level Medicaid behavioral therapy rate adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hidradenitis Suppurativa (HS) Treatment Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Narcolepsy Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Gallbladder Cancer Therapeutics Market
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Global Eye Allergy Therapeutics Market