
 Hereditary Amyloidosis Treatment Market | 2026-2036
Hereditary Amyloidosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hereditary Amyloidosis Treatment Market Foresight
The EU Green Deal is rebalancing investment priorities across European biopharma, pushing capital toward sustainable manufacturing for rare disease therapies. Alnylam Pharmaceuticals anchors its competitive position through deep RNA interference expertise and integrated supply chains for transthyretin-targeted drugs. Pfizer leverages global distribution infrastructure to sustain commercial reach across cardiology and neurology indications. Ionis Pharmaceuticals specializes in antisense oligonucleotide platforms, competing on mechanism diversity rather than manufacturing scale alone.
Hereditary amyloidosis treatment encompasses therapeutic interventions targeting transthyretin, apolipoprotein, or fibrinogen mutations that drive systemic amyloid deposition, with RNA-based modalities requiring cold-chain logistics and subcutaneous administration protocols to preserve molecular stability. The primary purpose centers on halting disease progression, reducing organ dysfunction, and extending survival in patients with familial ATTR, AFib, or AApoAI variants. Gene therapy segments attract the deepest R&D commitments due to curative intent, though monoclonal antibodies currently occupy the largest revenue share through established infusion infrastructure. Small molecules in the supportive care category face margin compression as payers scrutinize cost-effectiveness against disease-modifying alternatives.
The FDA's accelerated approval pathway and the EMA's PRIME designation framework both shape clinical trial design and commercial access timelines for developers in this space, while the EU MDR imposes escalating quality system requirements on device-drug combination products. Japan's PMDA orphan drug incentives further fragment regulatory strategy, forcing sponsors to maintain parallel submission tracks. Stakeholders must monitor how CMS and national European payers calibrate gene therapy reimbursement models against lifetime cost offsets.
Market Dynamics
RNA-targeted modalities are compressing clinical development timelines while fragmenting manufacturing requirements across cold-chain and ambient-stable formats, forcing sponsors to rebuild supply infrastructure around molecular stability rather than scale economics.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase 2-to-commercial timelines for transthyretin-directed therapies, enabling earlier revenue recognition and expanded patient access before confirmatory trials conclude.
- Specialty Clinic Expansion:Dedicated amyloidosis centers in the United States concentrate diagnosis and infusion capacity, creating captive demand channels for disease-modifying therapies.
- Antisense Platform Maturation:Chemically stabilized oligonucleotide backbones now support subcutaneous self-administration, reducing site-of-care burden and expanding addressable patient populations beyond infusion-capable centers.
Market Restraints
- Plasmid DNA Supply Concentration:GMP-grade plasmid manufacturing clusters in North American and European contract facilities, creating single-source vulnerability for gene therapy raw materials.
- EMA MDR Compliance Costs:Device-drug combination products face escalating quality system audits and notified body backlogs, delaying European launches by 12-18 months relative to FDA approvals.
- Small Molecule Substitution Pressure:Tafamidis and diflunisal remain accessible at lower out-of-pocket cost in markets with limited orphan drug reimbursement, constraining RNA therapy penetration in price-sensitive segments.
Strategic Opportunities
- Japan PMDA Orphan Incentives:Tax credits and priority review vouchers for familial ATTR therapies create favorable economics for dedicated Japanese development programs and local partnership structures.
- Gene Therapy Curative Positioning:Single-administration AAV vectors targeting hepatic TTR production offer lifetime cost-offset arguments against chronic RNA therapy, reshaping payer value frameworks.
- Home Infusion Channel Development:Subcutaneous RNAi formulations enable specialty pharmacy distribution direct to patients, bypassing hospital outpatient department markup and site capacity constraints.
Industry Challenges
- Oligonucleotide Manufacturing Talent Scarcity:Synthetic chemistry and analytical method development expertise concentrates at a handful of contract manufacturers, constraining sponsor capacity to insource production.
- Cross-Border Cold-Chain Integrity:Temperature excursions during international shipment of lipid nanoparticle formulations require redundant monitoring infrastructure and contingency inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hereditary Amyloidosis Treatment Market |
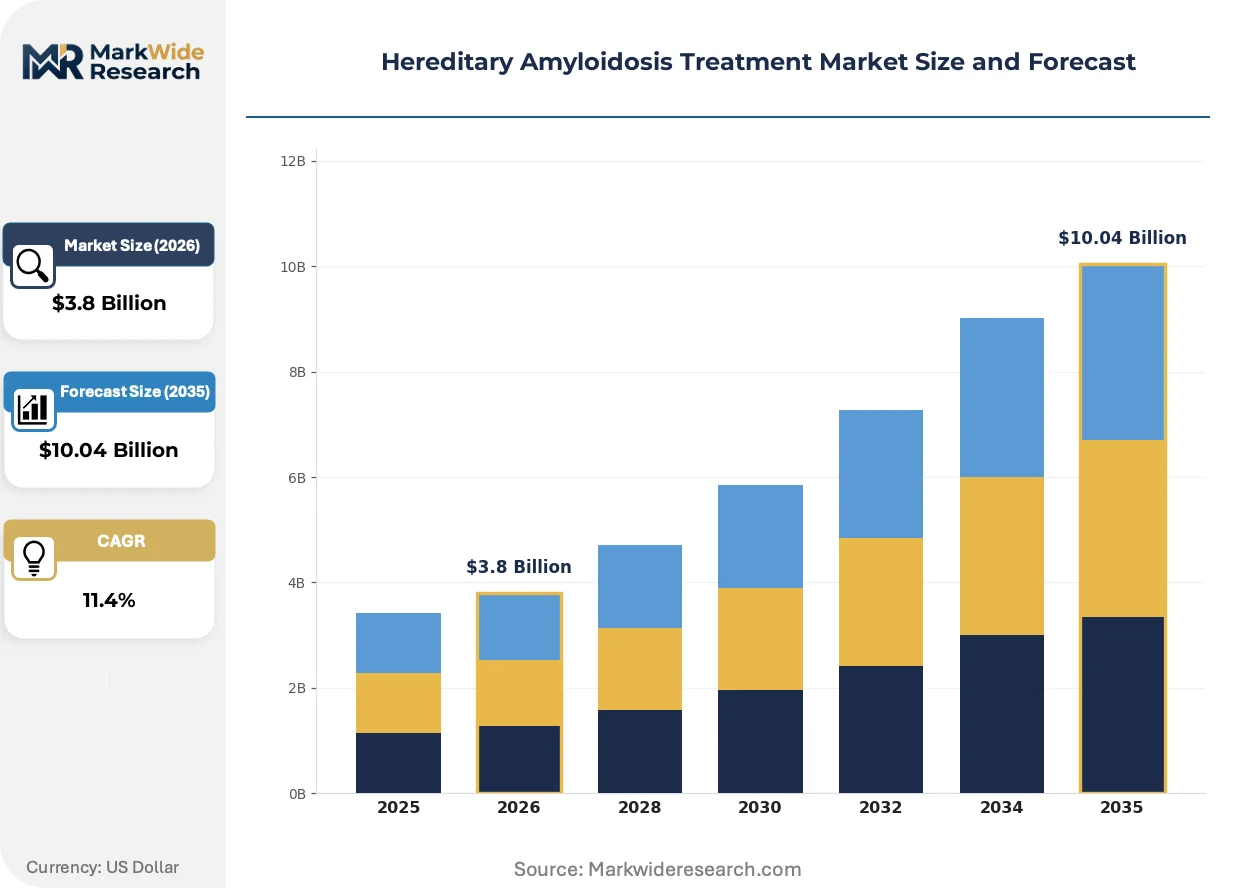
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Gene Therapy, Small Molecules, Supportive Care Therapy Area: Cardiology, Neurology, Nephrology, Gastroenterology Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal End User: Hospitals, Specialty Clinics, Home Care, Research Labs |
| Companies Covered | Alnylam Pharmaceuticals, Inc., Pfizer Inc., Ionis Pharmaceuticals, Inc., Prothena Corporation plc, AstraZeneca, Akcea Therapeutics, Inc., Eidos Therapeutics, Inc., Intellia Therapeutics, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hereditary Amyloidosis Treatment Market Shifts & Advancements
Next-generation delivery modalities are dissolving the boundary between genetic medicine and conventional biologics, with manufacturing and regulatory frameworks adapting in real time to accommodate novel molecular formats.
CRISPR-based gene editing is converging with lipid nanoparticle delivery to enable in vivo correction of TTR mutations without ex vivo cell manipulation. Early-stage sponsors are advancing liver-directed base editing programs toward IND-enabling studies. This convergence is compressing the perceived risk premium between gene therapy and small molecule development, attracting capital from cardiology-focused investors previously excluded from genetic medicine.
The EU Green Deal is mandating sustainable manufacturing audits for pharmaceutical production facilities, with EMA guidance incorporating carbon footprint disclosure into marketing authorization applications. Sponsors must now document solvent recovery rates and energy sourcing for oligonucleotide synthesis. European manufacturing investment is shifting toward continuous flow chemistry platforms that reduce organic solvent intensity while improving batch-to-batch consistency.
Patient advocacy organizations are consolidating procurement influence through centralized registry databases that track real-world outcomes across treatment modalities. These registries in the United States and Germany are becoming gatekeepers for formulary placement, with aggregated survival and quality-of-life data substituting for traditional clinical trial endpoints in payer negotiations. Specialty pharmacies are responding by unbundling clinical support services from drug distribution, creating outcome-contingent fee structures tied to registry-reported adherence metrics.
Hereditary Amyloidosis Treatment Market Segmentation
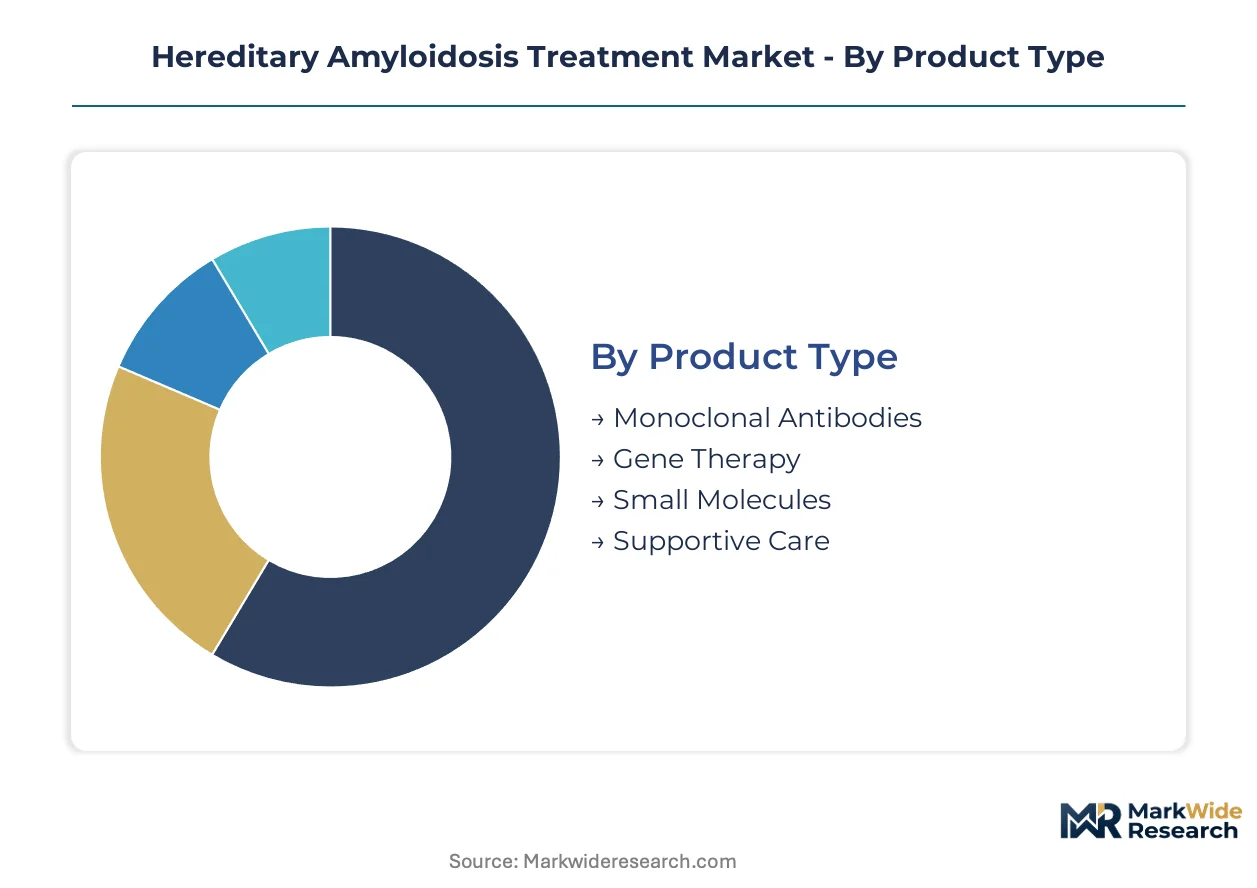
Segmentation in hereditary amyloidosis treatment reveals how therapeutic modality, organ involvement, and care setting interact to determine pricing power and access pathways. RNA-targeted platforms fragment across delivery formats while gene therapy concentrates investment in curative positioning.
Product Type:
Cost tier separates chronic administration from one-time intervention, with manufacturing complexity and reimbursement duration driving portfolio prioritization decisions.
- Monoclonal Antibodies:Engineered immunoglobulins targeting amyloid fibrils or circulating precursor proteins, administered via hospital infusion suites. Demand clusters in United States academic medical centers with established amyloidosis programs, constrained by site capacity and prior authorization requirements for biologic therapies.
- Gene Therapy:Adeno-associated viral vectors delivering CRISPR machinery or gene silencing constructs to hepatocytes for permanent transthyretin suppression. Investment concentrates in Massachusetts and California biotech clusters, propelled by CMS gene therapy reimbursement pilots and lifetime cost-offset modeling against chronic RNAi regimens.
- Small Molecules:Tafamidis and diflunisal stabilizers targeting tetrameric transthyretin conformation.
- Supportive Care:Diuretics, analgesics, and organ-specific management without disease-modifying mechanism.
Volume sits with Monoclonal Antibodies; growth tilts toward Gene Therapy.
Therapy Area:
Organ system involvement dictates clinical trial endpoints and specialist prescriber access, with cardiology commanding the deepest payer investment in disease modification.
- Cardiology:Transthyretin cardiac amyloidosis interventions targeting heart failure with preserved ejection fraction. United States cardiology practices drive adoption through integrated diagnostic pathways combining PYP scintigraphy and genetic testing, supported by American College of Cardiology guideline recognition of RNAi therapies.
- Neurology:Familial amyloid polyneuropathy treatments addressing progressive sensorimotor and autonomic dysfunction. German and French neuromuscular centers concentrate European demand, where EMA orphan drug exclusivity and national compassionate use programs accelerate access ahead of formal reimbursement.
- Nephrology:Renal amyloidosis management addressing proteinuria and progressive kidney dysfunction.
- Gastroenterology:Hepatic and gastrointestinal amyloid deposition with motility and malabsorption complications.
Revenue concentrates in Cardiology; expansion is steepest in Neurology.
Delivery Mode:
Patient autonomy and site-of-care economics reshape competitive positioning as subcutaneous formats bypass hospital markup.
- Intravenous:Infusion-dependent biologics requiring certified center administration with cardiac monitoring capabilities.
- Subcutaneous:Self-administered RNAi formulations using autoinjector devices. Specialty pharmacy networks in United States and United Kingdom are building direct-to-patient cold-chain distribution, reducing total cost of care by eliminating facility fees.
- Oral:Small molecule stabilizers with ambient storage and retail pharmacy fulfillment.
- Transdermal:Experimental patches for localized symptom management without systemic exposure.
Patient preference is shifting toward Subcutaneous; Oral retains volume in price-sensitive segments.
End User:
Care setting determines reimbursement pathway and clinical support intensity, with site-neutral payment reforms redistributing volume.
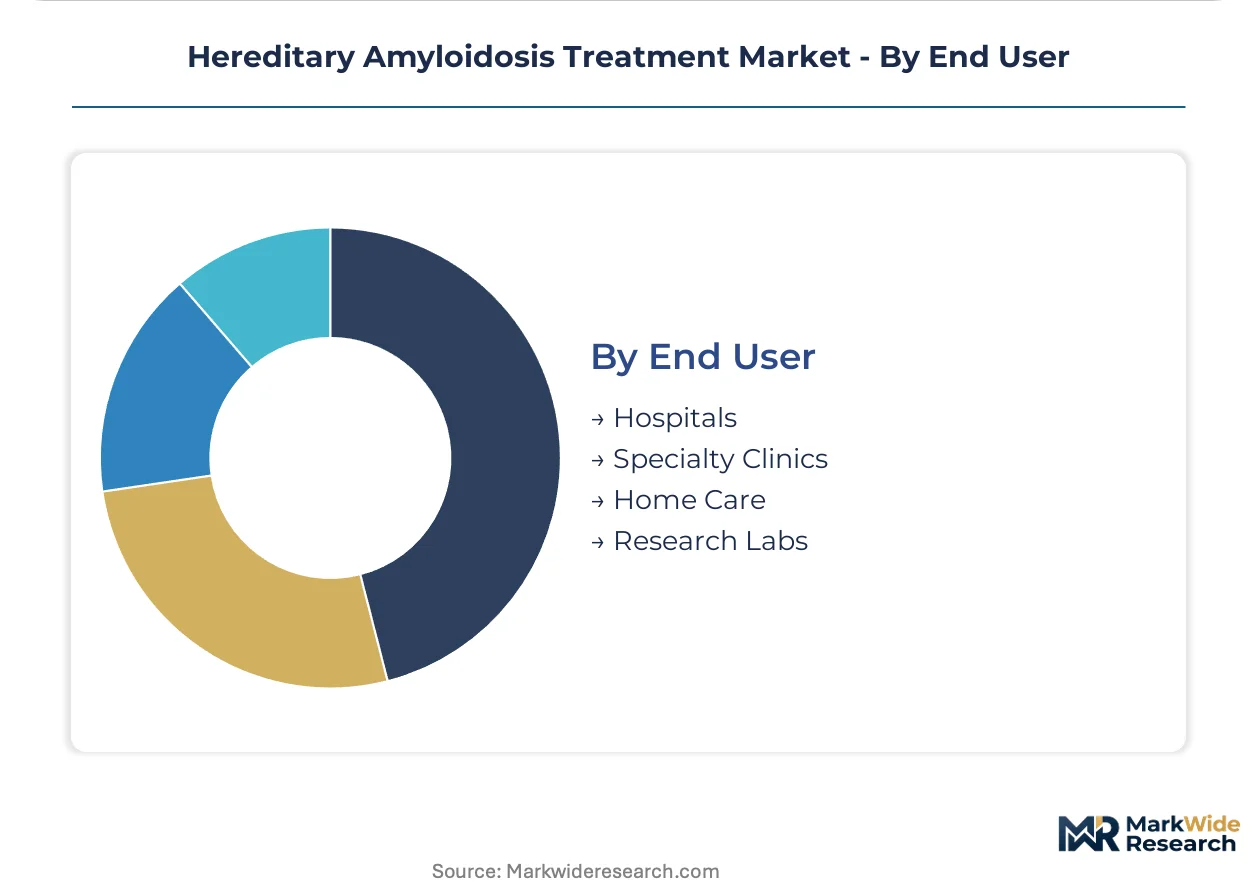
- Specialty Clinics:Dedicated amyloidosis centers consolidating diagnosis, genetic counseling, and infusion administration. United States metropolitan clusters in Boston, New York, and San Francisco concentrate prescriber expertise and patient registry enrollment.
- Hospitals:Academic medical centers managing complex multi-organ involvement and clinical trial access.
- Home Care:Subcutaneous self-administration supported by nursing visits and telemedicine monitoring.
- Research Labs:Preclinical and biomarker development services for sponsor pipeline programs.
Procedure volume centers on Specialty Clinics; Home Care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial density and payer sophistication concentrate in the United States and Western Europe, while manufacturing capacity clusters near GMP-grade plasmid suppliers in North America. Consumption patterns diverge sharply between markets with established orphan drug frameworks and those where small molecule stabilizers dominate.
United States
Specialty amyloidosis centers in Boston, New York, and San Francisco concentrate prescriber expertise and patient registry enrollment. FDA accelerated approval pathways compress Phase 2-to-commercial timelines for transthyretin-directed RNA therapies. CMS gene therapy reimbursement pilots in Massachusetts and California reshape lifetime cost-offset modeling against chronic RNAi regimens.
Germany
Neuromuscular centers in Munich and Heidelberg drive familial amyloid polyneuropathy treatment adoption through integrated diagnostic pathways. EMA orphan drug exclusivity and national compassionate use programs accelerate access ahead of formal reimbursement decisions. The EU Green Deal mandates sustainable manufacturing audits for pharmaceutical production facilities in Bavaria and Baden-Württemberg.
Japan
PMDA orphan drug incentives including tax credits and priority review vouchers create favorable economics for dedicated Japanese development programs. METI funding supports local partnership structures for gene therapy manufacturing. Clinical trial activity concentrates in Tokyo and Osaka academic medical centers with established amyloidosis registries.
United Kingdom
Specialty pharmacy networks in London and Manchester build direct-to-patient cold-chain distribution for subcutaneous RNAi formulations. NICE technology appraisals scrutinize cost-effectiveness of disease-modifying therapies against tafamidis and diflunisal. The NHS England specialized commissioning framework concentrates infusion capacity in designated amyloidosis centers.
Switzerland
Swissmedic marketing authorization processes attract sponsor submissions for gene therapy programs targeting hepatic TTR production. Basel and Zurich host contract manufacturing organizations with oligonucleotide synthesis expertise. The country's orphan drug reimbursement framework supports premium pricing for curative intent therapies.
Hereditary Amyloidosis Treatment Market Competitive Landscape
The competitive structure tilts toward RNA interference specialists with integrated manufacturing capabilities. Two tiers have emerged: platform technology developers controlling molecular design and delivery, and commercial-stage operators leveraging global distribution infrastructure. Archetypes include deep RNAi expertise holders, antisense oligonucleotide platform builders, and gene therapy vector developers. Dominant competitive moves center on manufacturing capacity expansion for lipid nanoparticle formulations and strategic partnerships for plasmid DNA supply security.
Among RNA-targeted therapy developers, Alnylam Pharmaceuticals, Ionis Pharmaceuticals, and Pfizer occupy distinct positioning vectors. Alnylam Pharmaceuticals exemplifies the integrated platform archetype with captive supply chain control over transthyretin-directed drug substance. Ionis Pharmaceuticals represents mechanism diversity specialization through chemically stabilized oligonucleotide backbone development. Pfizer anchors the commercial scale tier, leveraging cardiology and neurology infrastructure for therapy distribution. These three entities collectively illustrate how competitive advantage fragments across molecular design expertise, manufacturing integration, and therapeutic area reach.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals, Inc. |
| Pfizer Inc. |
| Ionis Pharmaceuticals, Inc. |
| Prothena Corporation plc |
| AstraZeneca |
| Akcea Therapeutics, Inc. |
| Eidos Therapeutics, Inc. |
| Intellia Therapeutics |
| GlaxoSmithKline plc |
| Others |
Supply & Pricing Matrix
The EU Green Deal's carbon footprint disclosure mandate gates qualified supply and premium-tier pricing access for hereditary amyloidosis therapies, forcing sponsors to document solvent recovery rates and energy sourcing before securing marketing authorization. Compliance with EMA sustainability audits separates manufacturers eligible for orphan drug premium pricing from those relegated to cost-competitive small molecule segments.
Pricing Analysis
Value-based pricing anchored to lifetime cost-offset against chronic RNAi regimens dominates gene therapy positioning, while RNA-targeted modalities command premium tiers through demonstrated survival extension. Price differentiation separates FDA-accelerated approval pathways from standard review timelines, with cardiology indications showing lowest price sensitivity due to bundled diagnostic-therapeutic pathways. Cost compression in neurology segments intensifies as tafamidis and diflunisal retain formulary placement through lower out-of-pocket exposure. Home care channels demonstrate highest price sensitivity where site-of-care markups disappear.
Supply Chain Analysis
Regional distribution centers in Massachusetts, California, and Basel anchor hub-and-spoke patterns for lipid nanoparticle formulations requiring redundant cold-chain monitoring. GMP-grade plasmid manufacturing concentrates in the United States, Germany, and Switzerland, creating single-source vulnerability for gene therapy raw materials. Synthetic chemistry expertise for oligonucleotide backbones rests on contract manufacturers in Basel and Research Triangle Park. Tariff exposure on European-sourced analytical reagents threatens batch release timelines. Distribution runs through specialty pharmacy networks bypassing hospital outpatient markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hereditary amyloidosis treatment market functions as a cost-of-compliance story where EMA MDR quality system requirements create a barrier-to-entry moat for sponsors with notified body relationships and device-drug combination expertise.
For Market Incumbents: Hedge against plasmid DNA supply concentration by securing dual-source agreements with North American and European contract manufacturers. Expand captive lipid nanoparticle production capacity in Switzerland to satisfy EU Green Deal carbon disclosure mandates. Patent cliff exposure for antisense backbone chemistries demands accelerated next-generation platform investment. For New Entrants and Emerging Players: Specialty pharmacy networks represent the most penetrable channel for subcutaneous RNAi formulations, bypassing hospital capacity constraints that limit infusion-dependent competitors. Target United Kingdom and German home care segments where NICE technology appraisals and national compassionate use programs accelerate access ahead of formal reimbursement. Pursue white-label manufacturing partnerships with established oligonucleotide synthesis providers rather than greenfield facility investment. For Investors and Strategic Acquirers: CMS gene therapy reimbursement pilot expansion in Massachusetts and California is the leading indicator that lifetime cost-offset modeling is achieving payer traction. Five-to-ten year viability favors platform technology developers with integrated manufacturing capabilities over pure commercial-stage operators. Acquisition target archetypes include CRISPR-based gene editing programs advancing liver-directed base editing toward IND-enabling studies. Watch for PMDA orphan drug tax credit announcements as Japan market entry signals.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive lipid nanoparticle capacity in Basel satisfies EMA carbon disclosure requirements for marketing authorization. |
| Regulatory Approval Pathway | FDA accelerated approval compresses Phase 2-to-commercial timelines for transthyretin-directed RNA therapies. |
| Licensing Agreement | Plasmid DNA supply partnerships with European contract manufacturers mitigate single-source vulnerability. |
| Clinical Trial Advancement | Liver-directed base editing programs attract cardiology-focused investors previously excluded from genetic medicine. |
| Pipeline Diversification | Antisense platform maturation supports subcutaneous self-administration beyond infusion-capable centers. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, combined with primary interviews involving drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Bottom-up patient population modeling and top-down revenue triangulation validated segmentation outputs across therapy area, delivery mode, and end user dimensions.
Historical trendline analysis of RNA-targeted therapy adoption patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated treatment line, administration route, patient population, and regional regulatory cluster dimensions. CAGRs derived from epidemiological prevalence data and pricing elasticity assumptions specific to orphan drug reimbursement pathways. Forecast inputs included specialty clinic expansion rates and CMS gene therapy pilot program geographic coverage.
Several conditions sit outside the modeled scope, including regulatory approval delays beyond standard review timelines and manufacturing scale-up failures at contract facilities. Forecasts reflect documented assumptions regarding payer acceptance of lifetime cost-offset arguments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Chagas Disease Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Transplantation Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
North America Chronic Disease Management Market