
 Multiple Endocrine Neoplasia Market | 2026-2036
Multiple Endocrine Neoplasia Market Size, Share, and Industry Trends Forecast 2026-2036
Multiple Endocrine Neoplasia Market Foresight
The capability gap between integrated biopharma conglomerates and focused oncology specialists is unwinding as targeted therapy pipelines deepen. Novartis AG leverages its radioligand therapy infrastructure to anchor supply across North American and European treatment centers. Ipsen Pharma differentiates through somatostatin analog specialization in neuroendocrine tumor portfolios. Bristol Myers Squibb Company sustains broad immuno-oncology competencies that extend into rare endocrine malignancy indications.
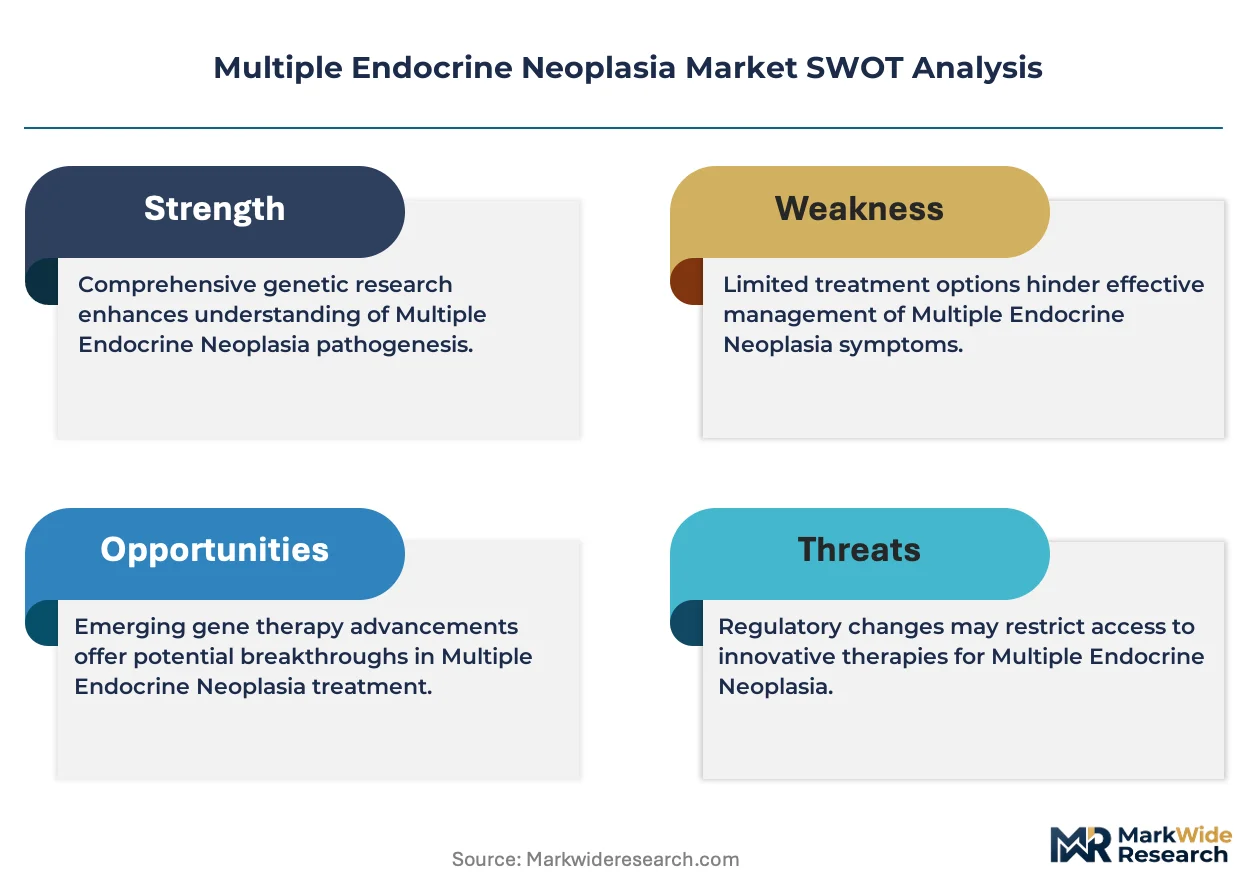
Multiple Endocrine Neoplasia denotes a group of autosomal dominant syndromes characterized by hyperplasia and neoplasia across multiple endocrine glands, with MEN1 mutations triggering parathyroid, pancreatic, and pituitary tumors and RET proto-oncogene alterations driving MEN2-related medullary thyroid carcinoma and pheochromocytoma. Diagnostics and targeted therapies capture concentrated investment as next-generation sequencing panels and RET inhibitor development reshape clinical management of hereditary endocrine neoplasms. Surgery retains foundational positioning in localized disease, though watchful waiting protocols expand for indolent phenotypes detected through cascade genetic screening programs.
FDA orphan drug incentives and EMA's PRIME designation framework for rare diseases accelerate product development timelines and market access for MEN-directed therapies. The EPA and OSHA regulate radiopharmaceutical manufacturing environments where radioligand therapies are produced, adding compliance layers to supply chain configuration. Stakeholders must monitor evolving reimbursement pathways for companion diagnostic testing and gene therapy interventions as precision medicine architectures mature.
Market Dynamics
The convergence of precision oncology platforms with hereditary cancer screening programs is restructuring how Multiple Endocrine Neoplasia cases are identified and channeled into treatment pathways. Molecular diagnostic laboratories and tertiary endocrine surgery centers are consolidating referral networks around next-generation sequencing capabilities.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug designation pathway accelerates development timelines for RET inhibitors and radioligand therapies targeting medullary thyroid carcinoma. Developers gain tax credits and extended exclusivity periods.
- Cascade Screening Expansion:First-degree relatives of confirmed MEN probands now undergo systematic genetic testing in integrated health systems across Germany, France, and the United Kingdom. Early detection protocols expand addressable patient pools.
- Ga-68 DOTATATE PET:This radiopharmaceutical imaging agent is decomposing traditional anatomical staging approaches by enabling whole-body neuroendocrine tumor visualization at lower radiation doses than conventional modalities.
Market Restraints
- Radiopharmaceutical Supply Concentration:Production of Lutetium-177 and Gallium-68 isotopes concentrates at five commercial cyclotron facilities in Belgium, the Netherlands, and the United States. Geopolitical disruptions or reactor maintenance cycles create acute shortages.
- Reimbursement Friction:Germany's G-BA and France's HAS impose staggered evidence requirements for companion diagnostics paired with targeted therapies. Payers demand progression-free survival data that extended trial timelines delay.
- Specialized Surgical Capacity:Parathyroid and pancreatic neuroendocrine resections require endocrine surgeons with annual case volumes exceeding fifty procedures. Training pipeline constraints limit center expansion.
Strategic Opportunities
- Direct-to-Patient Genetic Testing:Consumer-initiated hereditary cancer panels in the United States bypass traditional referral pathways. Positive MEN1 or RET findings create capture opportunities for integrated specialty networks.
- Subcutaneous Somatostatin Formulations:Depot injections administered at home displace hospital-based infusions. Patient preference for reduced clinic visits drives formulary positioning in Italian and Spanish markets.
- EMA PRIME Designation:This accelerated assessment framework compresses market access timelines for biologics addressing unmet needs in MEN2-associated pheochromocytoma. Early engagement with the European Medicines Agency reduces regulatory risk.
Industry Challenges
- Genetic Counseling Workforce Gap:Certified genetic counselors with endocrine oncology specialization number fewer than four hundred across the United States. Patient-to-counselor ratios exceed recommended thresholds in rural catchment areas.
- Cold Chain Complexity:Temperature-controlled logistics for short-half-life radiopharmaceuticals require validated packaging and real-time monitoring. Last-mile delivery failures in decentralized imaging networks generate wastage costs.
- Data Interoperability:Electronic health record systems lack standardized fields for hereditary syndrome tracking. Cascade screening completion rates suffer when proband notifications fail to reach at-risk relatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiple Endocrine Neoplasia Market |
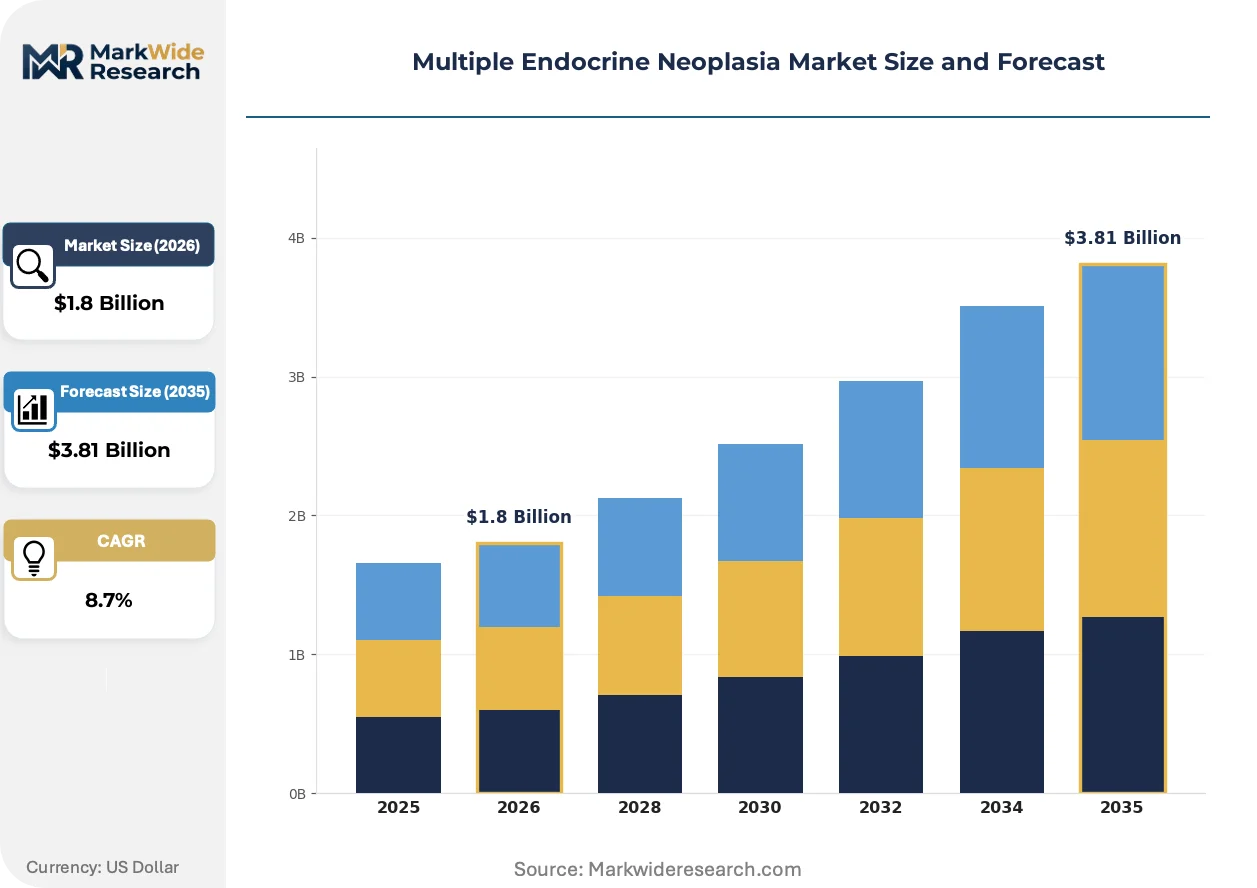
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostics, Biologics, Targeted Therapies, Hormone Replacement Treatment Approach: Surgery, Chemotherapy, Radiotherapy, Watchful Waiting End User: Hospitals, Specialty Clinics, Outpatient Facilities, Research Laboratories Stage of Disease: Early Stage, Advanced Stage, Recurrent, Metastatic |
| Companies Covered | Pfizer Inc, Novartis AG, Ipsen Pharma, Bristol Myers Squibb Company, Amgen Inc, GSK plc, Regeneron Pharmaceuticals Inc, Sanofi, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiple Endocrine Neoplasia Market Shifts & Advancements
Digital pathology and artificial intelligence are penetrating hereditary endocrine tumor diagnostics, compressing histopathological review timelines while introducing new validation requirements for algorithmic decision support.
Liquid biopsy platforms analyzing circulating tumor DNA are decomposing tissue-dependent diagnostic workflows. Academic medical centers in Boston and Heidelberg deploy multi-gene panels detecting MEN1 and RET alterations from plasma samples. Community oncology practices without on-site pathology infrastructure gain molecular characterization capabilities previously restricted to reference laboratories.
The FDA's Breakthrough Therapy designation pathway is compressing review timelines for RET-selective inhibitors. Sponsors submit rolling data packages rather than complete dossiers. Medullary thyroid carcinoma indications receive priority scheduling, though post-marketing confirmatory trials impose contingent reimbursement obligations.
Specialty pharmacy distribution is displacing traditional wholesale channels for high-cost oral oncology agents. Patients with MEN-associated neuroendocrine tumors receive coordinated benefits investigation and adherence monitoring through hub services. This model concentrates in United States commercial payer networks where prior authorization complexity demands dedicated navigation support.
Multiple Endocrine Neoplasia Market Segmentation
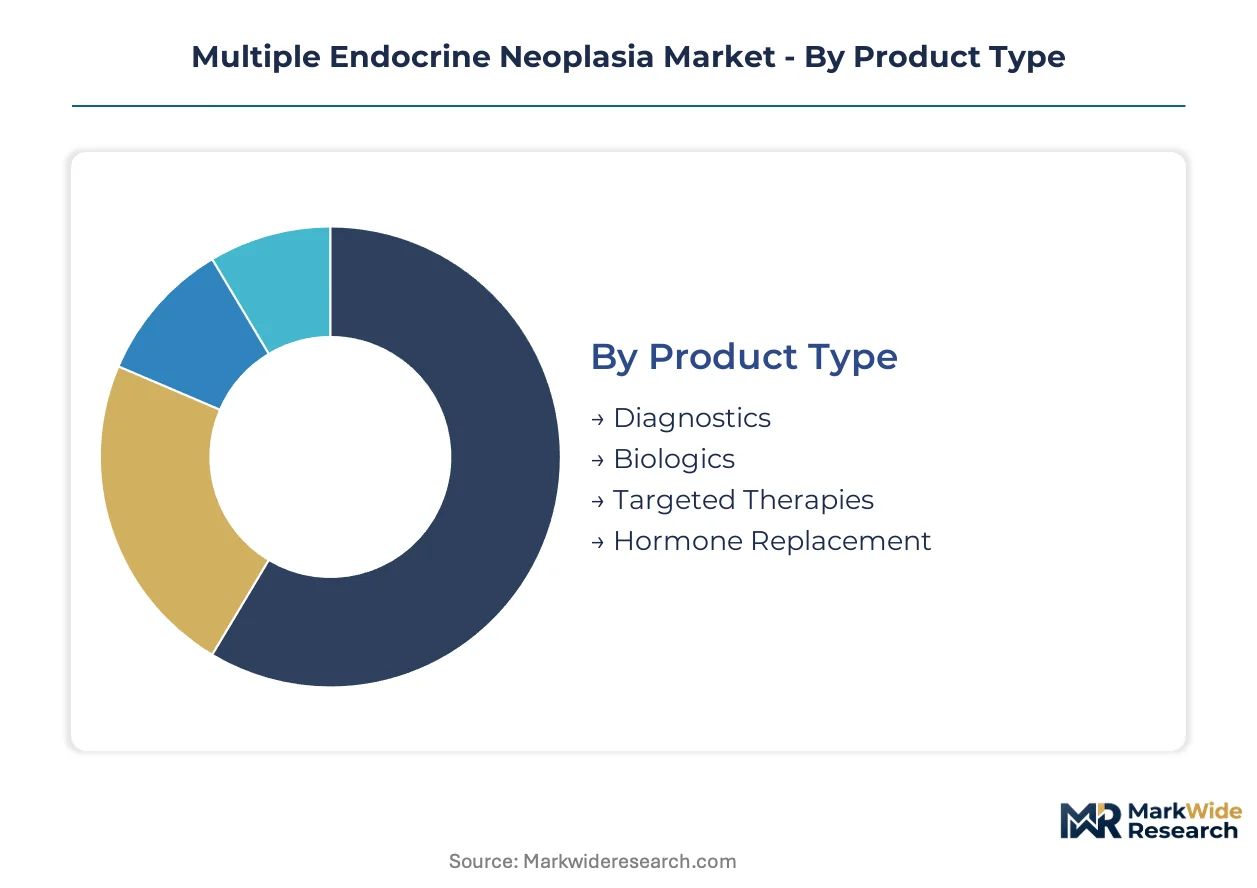
Multiple Endocrine Neoplasia market segmentation reveals distinct procurement patterns across hereditary cancer care networks. Product type distribution concentrates in tertiary centers with integrated genetic counseling, while treatment approach selection varies sharply by disease stage and RET mutation status.
Product Type:
Diagnostics and biologics concentrate in domestic referral networks anchored by academic medical centers in Boston and Heidelberg. Targeted therapies and hormone replacement flow through specialized pharmacy distributors serving export-led markets in Switzerland and Singapore.
- Diagnostics:Next-generation sequencing panels and Ga-68 DOTATATE PET imaging dominate initial staging workflows. German and French cascade screening programs drive concentrated demand in centralized molecular laboratories with CAP accreditation.
- Biologics:Somatostatin analogs and radioligand therapies require cold chain infrastructure validated to -80°C. Production of Lutetium-177 concentrates at cyclotron facilities in Belgium and the Netherlands, creating supply bottlenecks for North American treatment centers.
- Targeted Therapies:RET-selective inhibitors flow through specialty pharmacy hubs with prior authorization navigation.
- Hormone Replacement:Parathyroid and pituitary hormone analogs serve chronic maintenance protocols in outpatient settings.
Diagnostics commands the established base. The steepest expansion runs through Targeted Therapies.
Treatment Approach:
Cost tier stratification separates curative-intent surgical interventions from chronic management protocols. High-acuity procedures concentrate at centers exceeding fifty annual parathyroid resections, while watchful waiting spreads through community endocrinology practices.
- Surgery:Parathyroidectomy and pancreatic neuroendocrine resection require endocrine surgeons with subspecialty fellowship training. Annual case volume thresholds at MD Anderson and Memorial Sloan Kettering create referral concentration in Texas and New York corridors.
- Chemotherapy:Cytotoxic regimens retain niche positioning for aggressive pancreatic neuroendocrine phenotypes. Dosing protocols concentrate at academic centers with phase I trial infrastructure in Boston and San Francisco.
- Radiotherapy:Peptide receptor radionuclide therapy demands proximity to cyclotron facilities.
- Watchful Waiting:Active surveillance protocols expand for indolent MEN1-associated pituitary adenomas detected through cascade screening.
Surgery anchors revenue concentration. Watchful Waiting is climbing the fastest as early detection protocols expand.
End User:
Customer type fragmentation splits procurement between integrated delivery networks and independent specialty practices. Hospital systems leverage centralized purchasing for high-cost biologics, while outpatient facilities drive volume for chronic hormone replacement.
- Hospitals:Tertiary centers with endocrine surgery divisions capture complex resections and radionuclide therapy administration. German university hospitals in Munich and Hamburg anchor European referral networks with embedded genetic counseling.
- Specialty Clinics:Dedicated neuroendocrine tumor centers in London and Paris coordinate multidisciplinary care with centralized molecular tumor boards.
- Outpatient Facilities:Subcutaneous somatostatin depot administration shifts volume from infusion centers.
- Research Laboratories:Academic biobanks at Dana-Farber and Karolinska Institute drive companion diagnostic development.
Hospitals command the established base. Specialty Clinics are gaining share fastest through integrated care model differentiation.
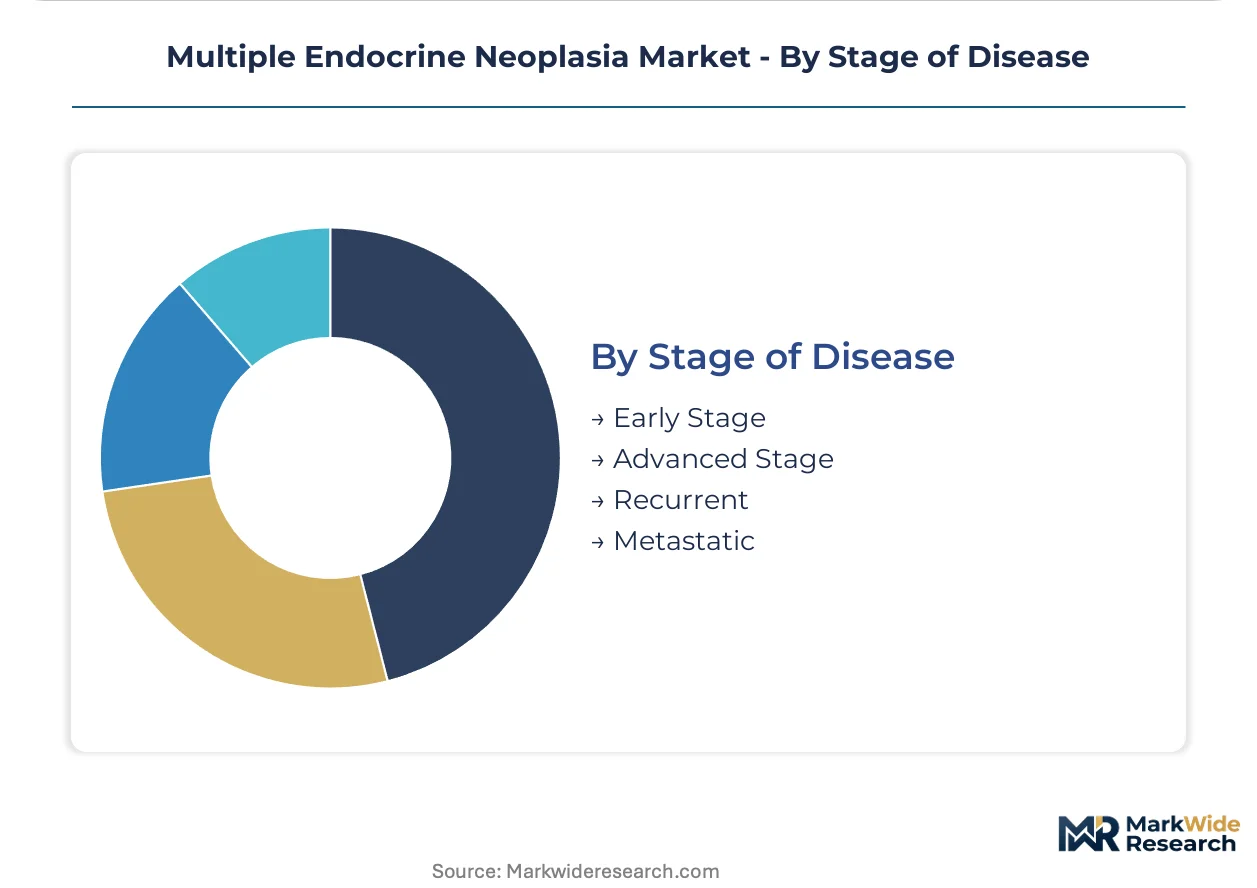
Stage of Disease:
Application urgency creates stark segmentation between localized disease management and metastatic care pathways. Early stage protocols emphasize surgical cure and genetic cascade screening, while advanced stage demand concentrates on radioligand therapy and RET inhibition.
- Early Stage:Screen-detected MEN1 and MEN2 probands undergo prophylactic thyroidectomy or parathyroid exploration. German and UK cascade screening programs create concentrated patient capture at designated reference centers.
- Advanced Stage:Metastatic medullary thyroid carcinoma and pheochromocytoma drive demand for selpercatinib and pralsetinib. FDA Breakthrough Therapy designations compress access timelines at US comprehensive cancer centers.
- Recurrent:Second-line surgical salvage and systemic rechallenge protocols concentrate at high-volume centers.
- Metastatic:Peptide receptor radionuclide therapy with Lutetium-177 DOTATATE requires cyclotron proximity.
Early Stage commands the established base. Advanced Stage shows the steepest expansion trajectory as targeted therapy pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across MEN treatment markets. United States commercial payers absorb premium RET inhibitor pricing with minimal resistance. German statutory insurers impose stringent cost-effectiveness hurdles that compress reimbursement rates for radioligand therapies.
United States
MD Anderson and Memorial Sloan Kettering anchor concentrated demand for complex parathyroid and pancreatic neuroendocrine resections. FDA orphan drug tax credits accelerate biologics development timelines. Boston's Dana-Farber Cancer Institute drives companion diagnostic validation for liquid biopsy MEN1 detection.
Germany
University hospitals in Munich and Hamburg coordinate European referral networks for hereditary endocrine tumor syndromes. G-BA evidence requirements for companion diagnostics create staggered market access timelines. Heidelberg's National Center for Tumor Diseases deploys Ga-68 DOTATATE PET imaging for cascade screening completion tracking.
France
Parisian neuroendocrine tumor centers capture multidisciplinary care coordination with embedded genetic counseling. HAS imposes progression-free survival thresholds for targeted therapy reimbursement. Lyon-based cyclotron facilities supply Lutetium-177 isotopes to decentralized imaging networks.
United Kingdom
NHS England's specialized commissioning framework concentrates MEN surgery at designated tertiary centers. NICE technology appraisals for selpercatinib and pralsetinib establish conditional reimbursement with real-world evidence collection. London's Royal Marsden Hospital anchors molecular tumor board networks for RET-mutant medullary thyroid carcinoma.
Switzerland
Swissmedic's expedited review pathway compresses timelines for radioligand therapy approvals. University Hospital Zurich integrates genetic counseling into endocrine surgery workflows. Basel's proximity to Novartis radiopharmaceutical manufacturing anchors supply chain coordination across Alpine treatment centers.
Multiple Endocrine Neoplasia Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the MEN therapeutic space. Radioligand therapy infrastructure demands concentrated capital investment that favors integrated biopharma conglomerates with cyclotron access. Smaller oncology specialists compete through RET inhibitor specialization and accelerated regulatory pathways. Three archetypes dominate: radiopharmaceutical-integrated conglomerates, targeted therapy specialists, and immuno-oncology platform extenders. Competitive moves center on specialty pharmacy hub consolidation and companion diagnostic co-development partnerships.
Within the radiopharmaceutical-integrated tier, Novartis AG anchors North American and European supply networks through cyclotron infrastructure control. Ipsen Pharma occupies a position exemplifying somatostatin analog specialization. Bristol Myers Squibb Company represents the immuno-oncology platform extension archetype, leveraging broad competencies into rare endocrine malignancy indications.
| Leading Market Players |
|---|
| Pfizer Inc |
| Novartis AG |
| Ipsen Pharma |
| Bristol Myers Squibb Company |
| Amgen Inc |
| GSK plc |
| Regeneron Pharmaceuticals Inc |
| Sanofi |
| Teva Pharmaceutical Industries Ltd |
| Others |
Supply & Pricing Matrix
FDA orphan drug designation and EMA PRIME certification simultaneously gate supply qualification for radioligand therapies and enable premium price positioning for RET inhibitors across North American and European treatment centers.
Pricing Analysis
Service contracts for cyclotron maintenance and isotope replenishment drive lifetime value for radiopharmaceutical-integrated conglomerates. Three-tier pricing structure across premium, standard, and economy levels separates Ga-68 DOTATATE imaging protocols from Lutetium-177 therapy courses from hormone replacement maintenance regimens. Cost compression in chemotherapy tiers is intensifying because subcutaneous somatostatin formulations displace hospital-based infusion revenues. Community endocrinology practices exhibit highest price sensitivity; comprehensive cancer centers absorb premium targeted therapy pricing with minimal formulary resistance.
Supply Chain Analysis
Inventory buffers for short-half-life isotopes rarely exceed seventy-two hours across Belgian, Dutch, and United States cyclotron facilities. Production of Lutetium-177 and Gallium-68 concentrates at five commercial facilities in Belgium, the Netherlands, and the United States. Raw material dependencies span enriched molybdenum targets, specialized chelating agents, and cold chain packaging validated to -80°C. Single-source vulnerability at reactor facilities in Petten and Fleurus creates acute shortage risk during maintenance cycles. Distribution runs through specialty pharmacy hubs with prior authorization navigation for oral oncology agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cascade screening completion rates and genetic counseling capacity creates niche capture opportunities for integrated specialty networks addressing hereditary endocrine tumor syndromes.
For Market Incumbents: Fortify cyclotron infrastructure control through long-term isotope supply agreements with Belgian and Dutch reactor facilities. Expand embedded genetic counseling into endocrine surgery workflows at designated tertiary centers to preempt direct-to-patient testing disruption. Vertical integration into companion diagnostic co-development partnerships secures prior authorization leverage against emerging liquid biopsy specialists. For New Entrants and Emerging Players: Remote genetic counseling capacity shortages in rural United States catchment areas represent immediate service-layer white space. Target subcutaneous somatostatin depot administration protocols in Italian and Spanish outpatient markets where hospital-based infusion displacement accelerates. Pursue EMA PRIME designation pathway for RET-selective inhibitors addressing MEN2-associated pheochromocytoma unmet needs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across radioligand therapy manufacturing infrastructure as cyclotron deployment costs escalate. Five-to-ten year viability favors acquisition of molecular diagnostic laboratories with CAP accreditation and embedded hereditary cancer screening programs. Monitor FDA Breakthrough Therapy designation grants for medullary thyroid carcinoma indications as pipeline maturity signal.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Liquid biopsy MEN1 detection at Dana-Farber accelerates targeted therapy patient identification. |
| Radiopharmaceutical Manufacturing Scale-Up | Cyclotron capacity expansion in Basel anchors Novartis supply coordination across Alpine centers. |
| EMA PRIME Designation Pursuit | Early European Medicines Agency engagement compresses market access timelines for rare disease biologics. |
| Specialty Pharmacy Hub Consolidation | Prior authorization navigation services reduce reimbursement friction for high-cost oral oncology agents. |
| Cascade Screening Program Partnership | German and UK reference center alliances expand addressable proband pools through systematic relative testing. |
Research Methodology
A spread of perspectives from endocrine surgeons, molecular diagnostic laboratory directors, genetic counselors, and specialty pharmacy hub operators converged on the working assumptions for patient flow modeling and treatment pathway economics. Primary interviews with tertiary center procurement managers and payer access specialists combined with secondary validation against FDA orphan drug filings, EMA PRIME designation records, ClinicalTrials.gov entries, and German G-BA reimbursement assessments. Bottom-up patient volume estimates triangulated against top-down pharmaceutical revenue disclosures.
Segmentation dimensions modeled span product type, treatment approach, end user category, and disease stage severity across the projection horizon. CAGRs were derived from fitted growth curves applied to baseline prevalence data and pipeline maturation timelines. Forecast inputs incorporated cascade screening penetration rates, cyclotron capacity expansion schedules, and RET inhibitor regulatory approval trajectories without year-specific anchoring.
Underlying assumptions cover stable orphan drug incentive continuity and isotope supply reliability, with deviation risk concentrated in radiopharmaceutical production disruptions and companion diagnostic reimbursement delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market