
 RNA-Targeted Small Molecules Market | 2026-2036
RNA-Targeted Small Molecules Market Size, Share, and Industry Trends Forecast 2026-2036
RNA-Targeted Small Molecules Market Analytics
Platform unbundling into discrete discovery modules is realigning how pharmaceutical buyers evaluate RNA-targeted partnerships. Arrakis Therapeutics leverages structure-based RNA degradation tools to anchor its position in oncology-focused discovery. Ionis Pharmaceuticals Inc. dominates antisense chemistry through sustained investment in ligand-conjugated delivery. F. Hoffmann-La Roche Ltd extends its reach across the value chain through integrated diagnostic-therapeutic development.
RNA-targeted small molecules comprise synthetic compounds engineered to bind specific RNA secondary structures and modulate gene expression through splicing correction, translation inhibition, or targeted degradation. These agents typically range from 300 to 700 Daltons and penetrate cellular membranes to access previously undruggable transcriptomic targets. Small molecules within the product type category lead current development pipelines due to their established manufacturing scalability and oral bioavailability, while RNA interference segments command premium valuations owing to durable gene silencing mechanisms. Oncology as a therapy area concentrates the largest margin pools, though genetic disorders represent the fastest-expanding addressable population as rare disease designations accumulate.
FDA accelerated approval frameworks and EMA adaptive pathway programs are compressing development timelines for RNA-targeted candidates while elevating post-market evidence requirements. The EPA and OSHA jointly govern manufacturing facility standards for oligonucleotide synthesis, particularly around solvent handling and nucleotide precursor containment. Stakeholders must monitor how emerging pharmacovigilance databases track off-target RNA binding events across diverse patient genomes.
Market Dynamics
Platform unbundling into discrete discovery modules is realigning how pharmaceutical buyers evaluate RNA-targeted partnerships, fragmenting integrated service contracts into component-based procurement. Contract structures now separate target identification, lead optimization, and delivery chemistry into standalone purchasing decisions.
Growth Catalysts
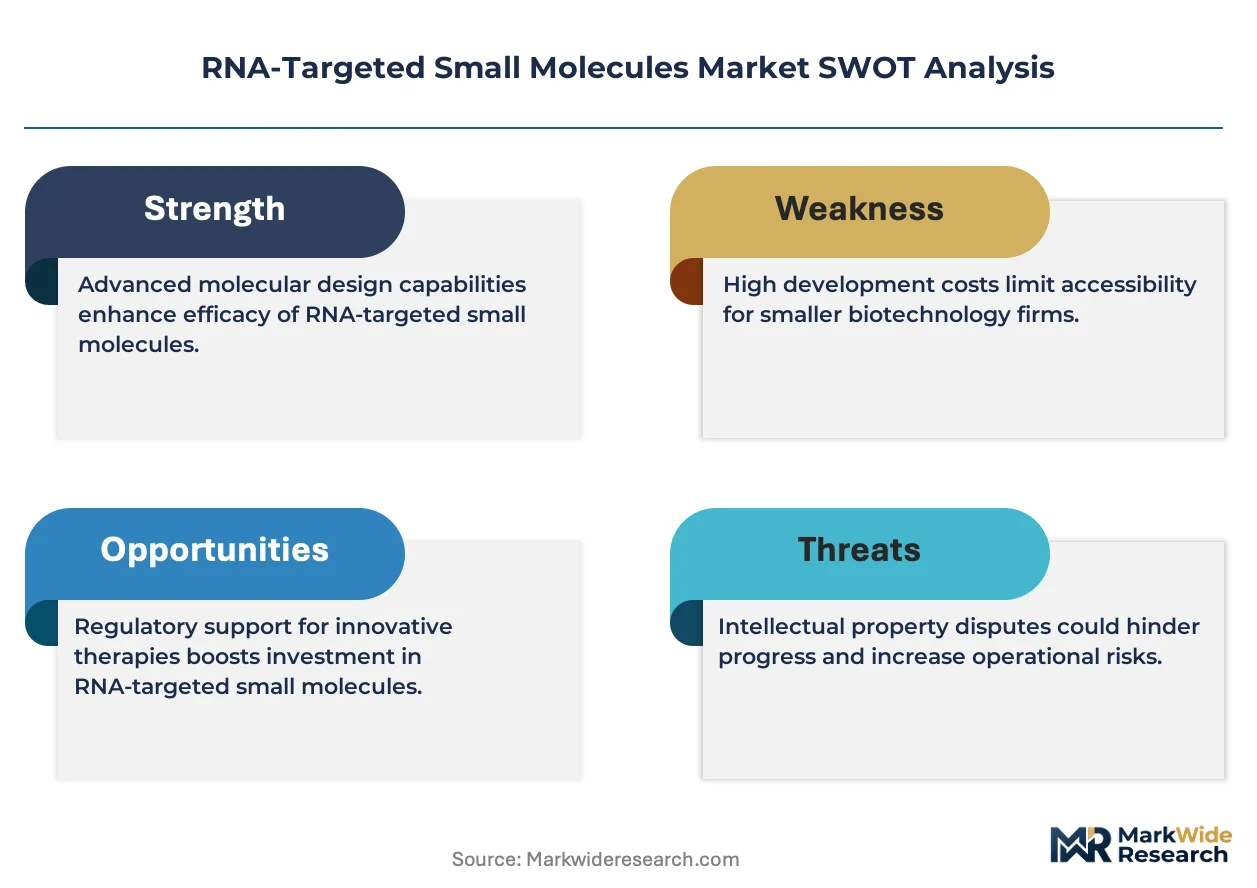
- FDA Accelerated Approval:Compressed development timelines for nucleic acid therapies reduce capital lock-up periods and improve venture returns for early-stage platforms.
- Structure-Based Degradation:Computational tools for predicting RNA small-molecule binding are shortening hit-to-lead cycles in oncology discovery programs.
- Boston-San Francisco Biocluster Concentration:Geographic proximity of academic medical centers to venture capital is funneling Series A funding into RNA-targeted startups.
Market Restraints
- Oligonucleotide Precursor Supply:Solvent handling requirements under EPA and OSHA standards limit contract manufacturing capacity expansion.
- Off-Target Binding Liability:Pharmacovigilance databases struggle to capture RNA binding events across diverse patient genomes, elevating post-market risk.
- Antisense Chemistry Concentration:Dominant market position of ligand-conjugated delivery specialists creates bottleneck pricing for access to validated platforms.
Strategic Opportunities
- Genetic Disorder Designations:Orphan drug pathways for rare transcriptomic diseases offer expedited review and extended exclusivity periods.
- Diagnostic-Therapeutic Integration:Companion biomarker development creates captive demand for RNA-targeted agents in precision oncology protocols.
- Oral Bioavailability Gap:Small molecule formats under 700 Daltons address unmet need for patient-administered alternatives to injectable RNA interference.
Industry Challenges
- RNA Structural Biology Talent:Shortage of specialists capable of interpreting secondary structure data for druggable target identification.
- GMP Oligonucleotide Synthesis Scale-Up:Capital intensity of nucleotide precursor containment infrastructure constrains manufacturing flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RNA-Targeted Small Molecules Market |
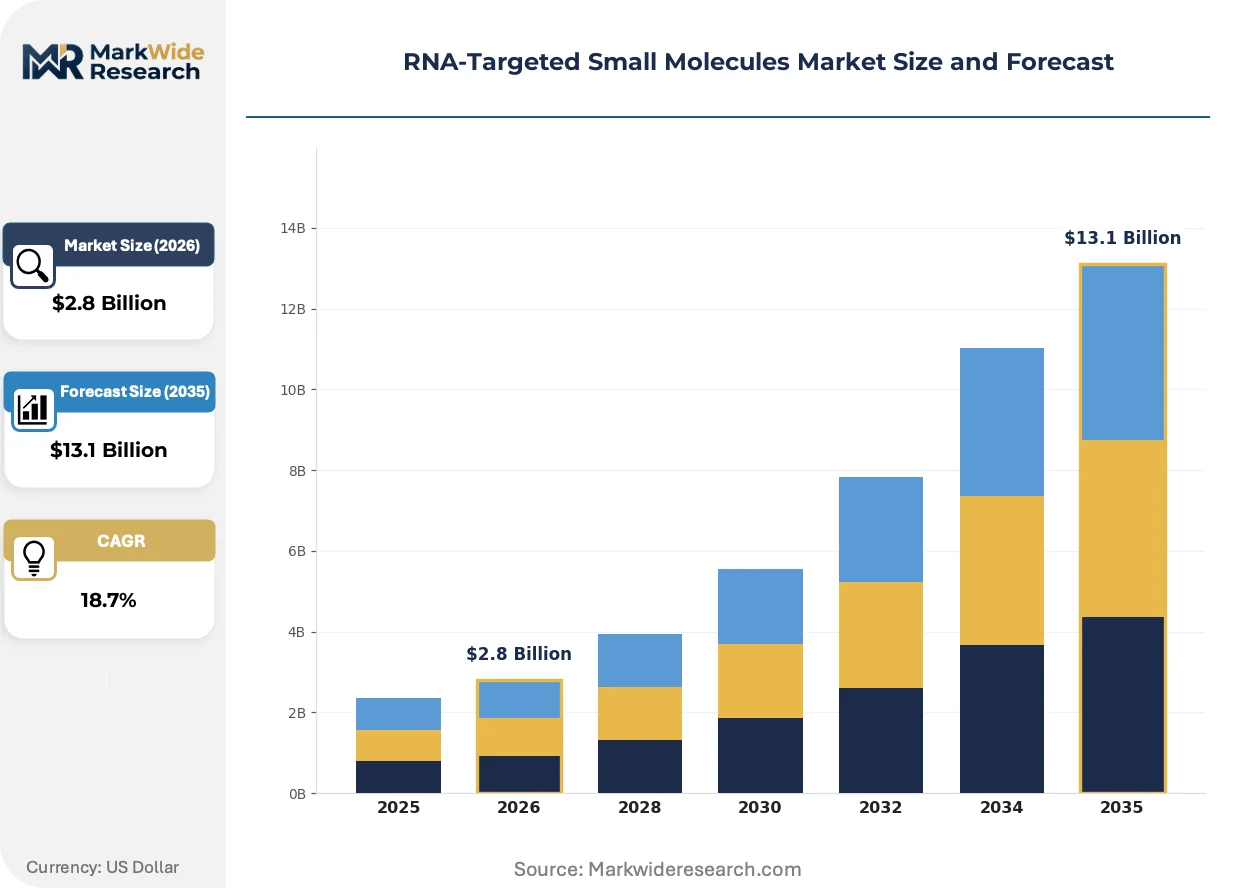
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.1 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Oligonucleotides, RNA Interference, Antisense Therapies Therapy Area: Oncology, Cardiovascular Diseases, Infectious Diseases, Genetic Disorders End User: Pharmaceutical Companies, Research Institutions, Clinics, Biotechnology Firms Administration Route: Intravenous, Subcutaneous, Oral, Inhalation |
| Companies Covered | Arrakis Therapeutics, Ionis Pharmaceuticals Inc., F. Hoffmann-La Roche Ltd, Accent Therapeutics Inc., Anima Biotech Inc., Novartis AG, Alnylam Pharmaceuticals Inc., Expansion Therapeutics, Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RNA-Targeted Small Molecules Market Evolving Landscape
Computational target discovery and modular platform architectures are compressing traditional pharmaceutical timelines. Three converging developments are reconfiguring competitive positioning in RNA-directed therapeutics.
Structure-based RNA degradation tools are overtaking empirical screening as the dominant discovery paradigm. Oncology-focused academic medical centers are adopting these platforms within 18-month procurement cycles. The shift is collapsing the historical advantage of large compound libraries in favor of physics-driven binding prediction.
EMA adaptive pathway programs are harmonizing with FDA frameworks to create transatlantic accelerated review corridors. Post-market evidence requirements are elevating investment in real-world data infrastructure. Genetic disorder applications are capturing disproportionate regulatory attention due to unmet need designations.
Buyer concentration among integrated health systems is fragmenting historical blockbuster contracting models. Massachusetts General Hospital and UCSF Medical Center are unbundling discovery partnerships into milestone-based component agreements. Geographic procurement gravity is concentrating in US academic medical centers with embedded venture arms.
RNA-Targeted Small Molecules Market Segmentation
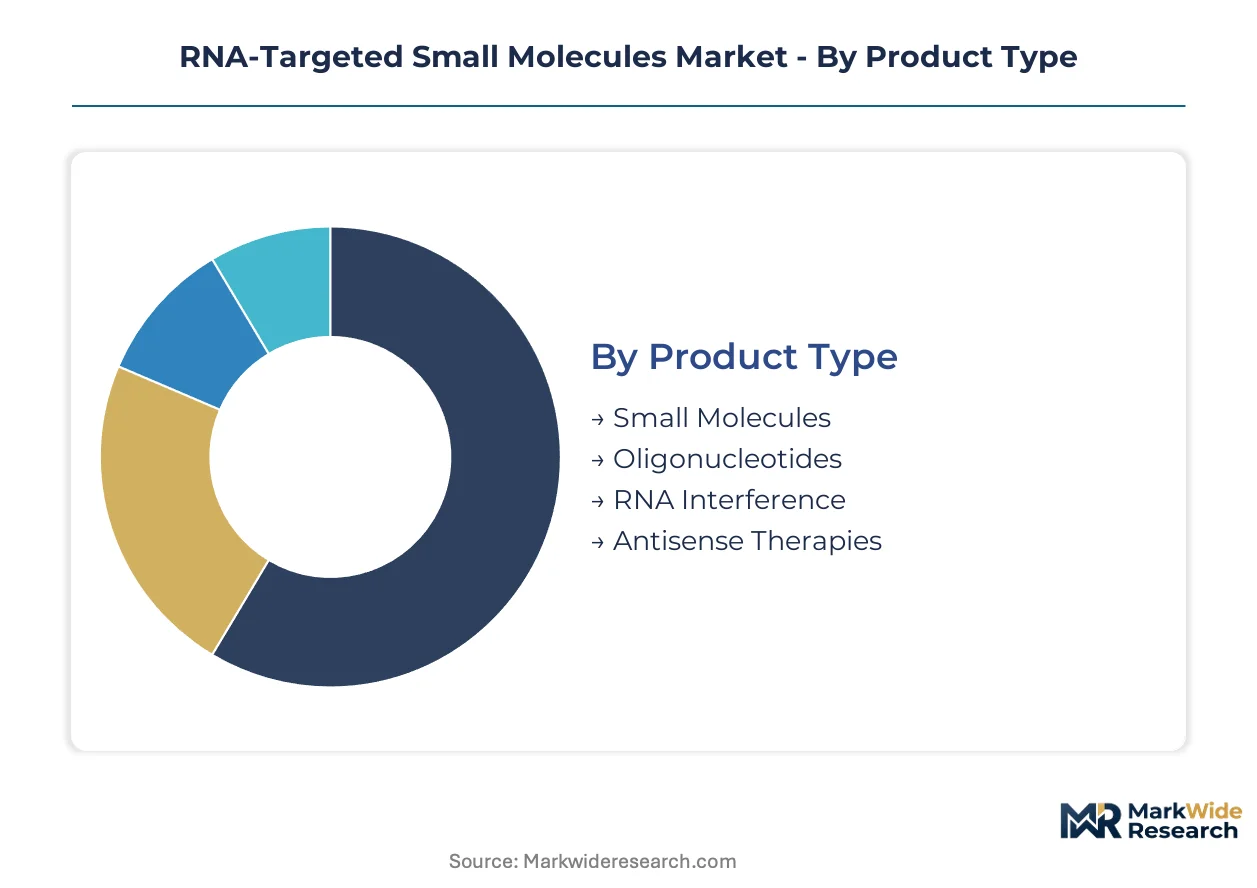
RNA-targeted therapeutics fragment across multiple technical and commercial dimensions. Procurement patterns diverge sharply between established small molecule formats and emerging biological modalities.
Product Type:
Standalone synthesis platforms dominate high-volume manufacturing, while embedded delivery systems anchor partnership structures for complex modalities.
- Small Molecules:Synthetic compounds between 300-700 Daltons engineered for oral bioavailability and membrane penetration. Demand concentrates in Boston and San Francisco bioclusters where venture-backed startups prioritize scalable chemistry. FDA accelerated approval pathways favor these formats for rapid clinical entry.
- RNA Interference:Double-stranded RNA constructs enabling durable gene silencing through RISC-mediated mRNA cleavage. Academic medical centers in the United States are expanding procurement of these platforms for precision oncology, though manufacturing complexity limits contract manufacturing options.
- Oligonucleotides:Short synthetic nucleic acid sequences with established GMP synthesis infrastructure.
- Antisense Therapies:Single-stranded DNA or RNA analogs modulating splicing or translation through steric blocking.
Small molecules lead volumes today; RNA interference is gaining share fastest.
Therapy Area:
Margin pools concentrate where diagnostic-therapeutic integration creates captive demand and extended exclusivity pathways.
- Oncology:Transcriptomic targets in solid and hematologic malignancies drive the largest development pipelines. Massachusetts General Hospital and UCSF Medical Center are unbundling discovery partnerships into milestone-based agreements for cancer applications. Structure-based degradation tools are compressing hit-to-lead cycles in this segment.
- Genetic Disorders:Rare disease designations offer expedited FDA review and orphan drug exclusivity. Patient advocacy networks in the United States are funneling foundation funding toward transcriptomic targets for monogenic conditions. EMA adaptive pathway programs are harmonizing with FDA frameworks for these indications.
- Cardiovascular Diseases:Antisense-mediated reduction of circulating lipoproteins represents the most advanced clinical application.
- Infectious Diseases:RNA-targeted approaches against viral genomes and host dependency factors.
Oncology commands the largest revenue pools; genetic disorders show the steepest expansion trajectory.
End User:
Customer concentration among integrated health systems is fragmenting historical blockbuster contracting models.
- Pharmaceutical Companies:Large-cap developers with in-house oligonucleotide synthesis capabilities and established regulatory affairs infrastructure. These buyers are separating target identification, lead optimization, and delivery chemistry into standalone purchasing decisions.
- Biotechnology Firms:Venture-backed platforms leveraging structure-based tools and modular architectures. Geographic proximity to Boston and San Francisco academic medical centers determines Series A funding access for these entities.
- Research Institutions:Academic laboratories with NIH and foundation funding for target validation.
- Clinics:Early-adopter sites within academic medical centers running sponsored trials.
Pharmaceutical companies anchor procurement volumes today; biotechnology firms are expanding their share most rapidly.
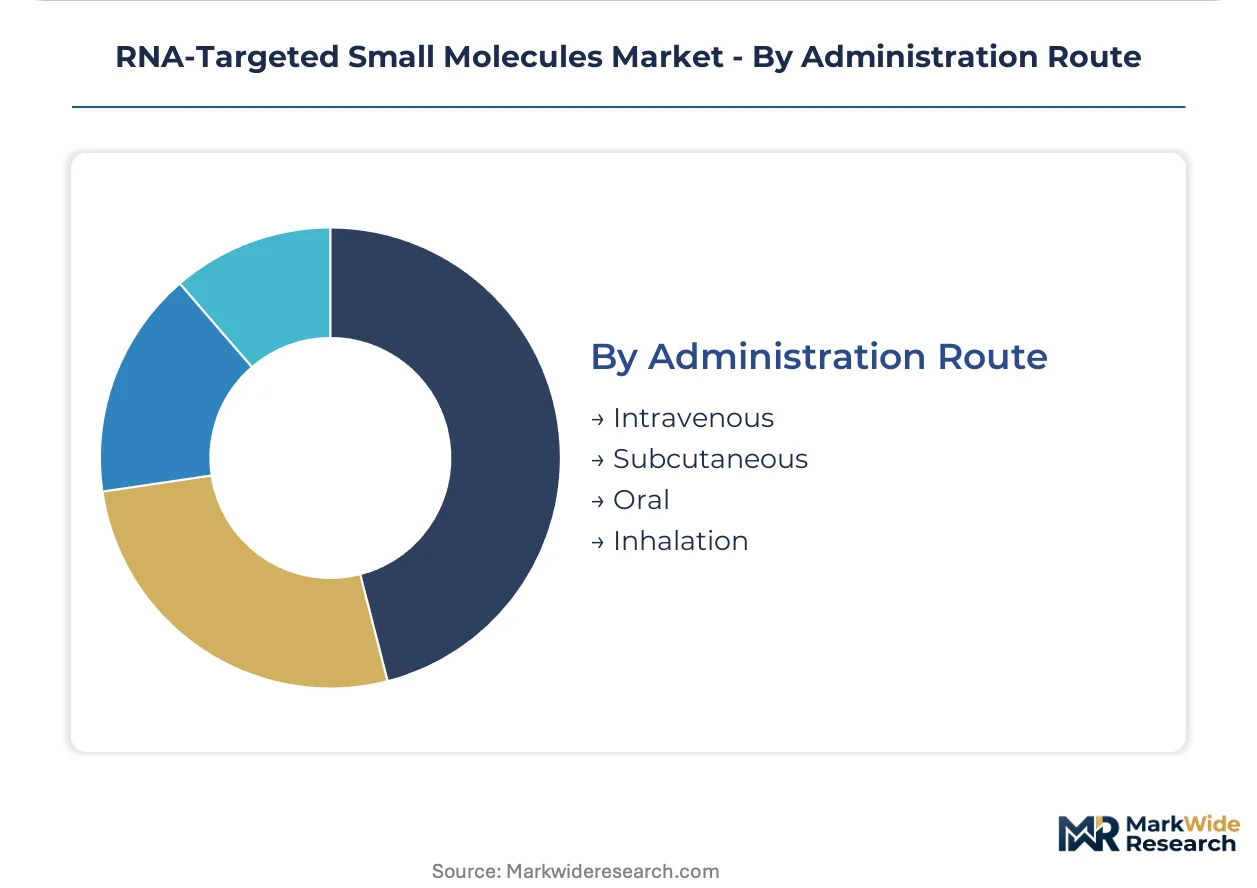
Administration Route:
Patient-administered formats command premium pricing against clinic-dependent alternatives.
- Oral:Small molecule formats under 700 Daltons address the unmet need for home administration. FDA bioequivalence pathways for these agents are well-established, reducing regulatory risk for developers.
- Subcutaneous:Self-injectable oligonucleotide formulations with emerging auto-injector compatibility. Biotechnology firms in the United States are prioritizing these formats for chronic disease management to reduce healthcare system burden.
- Intravenous:Hospital-administered infusion for complex biologics and acute indications.
- Inhalation:Pulmonary delivery for respiratory transcriptomic targets.
Intravenous dominates current clinical use; oral formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RNA-targeted small molecule research originated in United States academic medical centers during the early 2000s, with Boston and San Francisco bioclusters pioneering structure-based discovery platforms before European and Asian institutions established comparable capabilities.
United States
FDA accelerated approval pathways and NIH funding concentration drive platform development. The EPA and OSHA jointly govern oligonucleotide manufacturing standards for solvent handling. Massachusetts General Hospital and UCSF Medical Center anchor procurement unbundling into milestone-based discovery contracts.
Germany
EMA adaptive pathway harmonization with FDA frameworks attracts transatlantic clinical trial coordination. The country's national pharmaceutical regulator enforces GMP standards for nucleotide precursor containment. Heidelberg and Munich academic clusters specialize in RNA structural biology talent development.
Switzerland
Diagnostic-therapeutic integration investments concentrate in precision oncology applications. Swissmedic maintains alignment with EMA accelerated review corridors for rare disease designations. Basel anchors integrated pharmaceutical development with embedded venture financing.
United Kingdom
Genetic disorder foundation networks funnel capital toward monogenic transcriptomic targets. The MHRA operates post-Brexit recognition agreements with FDA for nucleic acid therapy approvals. London and Cambridge bioclusters prioritize computational binding prediction tools.
Japan
PMDA orphan drug pathways for rare diseases expedite RNA-targeted agent review. METI funding programs support domestic oligonucleotide synthesis infrastructure scale-up. Tokyo and Osaka academic medical centers expand procurement of structure-based degradation platforms.
RNA-Targeted Small Molecules Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chemistry validation and delivery technology ownership. The vendor base stratifies between integrated pharmaceutical developers with captive manufacturing and venture-backed discovery platforms licensing modular toolkits. Three archetypes dominate: structure-based degradation specialists, antisense chemistry incumbents, and diagnostic-therapeutic integrators. Capacity expansion in GMP oligonucleotide synthesis and strategic partnerships for target identification modules represent the primary competitive moves.
Within the structure-based degradation tier, Arrakis Therapeutics occupies a position exemplifying oncology-focused platform architecture. Ionis Pharmaceuticals Inc. and F. Hoffmann-La Roche Ltd sit within the antisense and integrated development tiers respectively, representing contrasting scale advantages in ligand-conjugated delivery and value-chain coordination. These three entities anchor the competitive spectrum from specialized discovery through full-stack therapeutic development.
| Leading Market Players |
|---|
| Arrakis Therapeutics |
| Ionis Pharmaceuticals Inc. |
| F. Hoffmann-La Roche Ltd |
| Accent Therapeutics Inc. |
| Anima Biotech Inc. |
| Novartis AG |
| Alnylam Pharmaceuticals Inc. |
| Expansion Therapeutics |
| Bristol-Myers Squibb Company |
| Others |
Value Network & Pricing Analysis
Capability stratification between structure-based discovery platforms and commodity oligonucleotide synthesis services manifests in divergent margin structures and procurement configurations. Premium-tier platform access commands milestone-based contracting with embedded diagnostic rights, while standardized synthesis services compete on batch turnaround and EPA compliance documentation.
Pricing Analysis
Project-based milestone contracting with royalty appendages dominates partnership structures for RNA-targeted discovery platforms. Price differentiation rests on proprietary degradation tool ownership and companion biomarker bundling. Cost compression in standardized oligonucleotide synthesis is intensifying because contract manufacturers face solvent containment capital requirements. Biotechnology firms with embedded venture financing show lowest price sensitivity; generic synthesis buyers exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with specialized nucleotide precursor suppliers concentrated in the United States and Germany. Raw material dependencies include phosphoramidite monomers, solid-phase synthesis resins, and high-purity solvents. Regulatory restriction on EPA-permitted facility expansion creates persistent capacity constraints. Distribution runs through GMP-certified contract manufacturers with captive quality assurance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RNA-targeted therapeutics represent a late-cycle quality story as procurement gravity shifts toward platforms with validated structure-based prediction capabilities and integrated diagnostic development.
For Market Incumbents: Anticipate margin compression from modular platform unbundling by securing exclusive access to RNA structural biology talent pools in Boston and Heidelberg. Prioritize backward integration into GMP oligonucleotide synthesis to reduce dependency on EPA-constrained contract manufacturing capacity. For New Entrants and Emerging Players: The premium-to-economy gap in oral bioavailability-enabled small molecules offers white-space entry between injectable RNA interference incumbents and generic antisense providers. Target genetic disorder designations with expedited FDA orphan pathways. Lead with patient-administered format development to differentiate from clinic-dependent alternatives. For Investors and Strategic Acquirers: Consolidation pressure builds where platform unbundling fragments discovery contracts into subscale component purchases. Five-to-ten-year viability favors entities with captive diagnostic-therapeutic integration and validated structure-based tools. Watch FDA accelerated approval pathway expansion rates as inflection signal for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Structure-Based Platform Licensing | Arrakis Therapeutics anchors oncology partnerships through physics-driven binding prediction capabilities. |
| GMP Oligonucleotide Scale-Up | Ionis Pharmaceuticals reduces manufacturing risk through in-house ligand-conjugated synthesis infrastructure. |
| Diagnostic-Therapeutic Integration | F. Hoffmann-La Roche captures companion biomarker demand within precision oncology protocols. |
| FDA Accelerated Pathway Navigation | Alnylam Pharmaceuticals compresses development timelines through nucleic acid therapy regulatory expertise. |
| Orphan Disease Designation Pursuit | Expansion Therapeutics accesses expedited review and extended exclusivity for rare transcriptomic targets. |
Research Methodology
Coverage spans the United States, Germany, Switzerland, the United Kingdom, and Japan, with primary inputs from each market cluster. Drug development executives, regulatory affairs leads at FDA and EMA, hospital procurement managers at Massachusetts General Hospital and UCSF Medical Center, and formulary directors provided structured interviews. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and SEC 10-K disclosures. Bottom-up platform revenue aggregation triangulated against top-down therapy area spending estimates.
Granularity-level modeling addressed product type, therapy area, end user archetype, and administration route dimensions. CAGRs were derived from segment-level growth trajectory analysis across the projection horizon. Forecast inputs incorporated FDA accelerated approval pathway utilization rates, EMA adaptive pathway harmonization progress, and academic medical center procurement cycle timing.
The model assumes a particular technology adoption path; alternative pathways for structure-based RNA degradation would alter the outlook. Forecasts reflect assumptions regarding regulatory framework stability, oligonucleotide precursor supply capacity expansion, and pharmacovigilance database maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Galculus Bovis and Metronidazole Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
US Pharmaceutical CMO Market