
 Partial Onset Seizures Market | 2026-2036
Partial Onset Seizures Market Size, Share, and Industry Trends Forecast 2026-2036
Partial Onset Seizures Market Analytics
The EU Green Deal's pharmaceutical sustainability framework is rebalancing procurement criteria across European hospital networks. UCB SA leverages its Belgian manufacturing base to sustain supply chain advantages for central nervous system therapies. Pfizer Inc. competes through geographic diversification of its active pharmaceutical ingredient sourcing.
Partial onset seizures, also known as focal seizures, originate in a discrete region of one cerebral hemisphere and may present with or without impaired awareness depending on the affected cortical area. These neurological events require precise electroencephalographic localization and targeted pharmacological intervention to prevent secondary generalization and preserve patient function. Oral medications dominate prescription volumes due to established bioavailability profiles and patient adherence convenience, while devices represent the fastest-expanding segment as responsive neurostimulation and closed-loop seizure detection systems gain clinical validation. Injectable therapies retain concentrated margin pools in acute hospital settings where rapid seizure cessation is critical.
The FDA maintains stringent efficacy and safety benchmarks for antiepileptic drug approvals through its Division of Neurology, while the EMA's Committee for Medicinal Products for Human Use enforces centralized pediatric investigation plans across European markets. Japan's PMDA operates accelerated review pathways for orphan neurological indications, compressing timelines for novel mechanisms of action. Stakeholders must monitor evolving biomarker-based patient stratification approaches that promise to reshape trial design and reimbursement negotiations.
Market Dynamics
Responsive neurostimulation systems are decentralizing seizure management from centralized epilepsy centers toward ambulatory and home-based monitoring environments. This structural shift compresses hospital dependency while elevating demand for closed-loop algorithm validation and remote clinical oversight infrastructure.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Accelerated review timelines compress development cycles for novel antiepileptic compounds targeting drug-resistant populations.
- Hospital Neurology Expansion:United States academic medical centers are scaling continuous EEG monitoring protocols, creating pull-through demand for adjunctive device therapies.
- Japan PMDA Orphan Acceleration:Compressed regulatory timelines for rare neurological indications incentivize mechanism-of-action innovation in focal epilepsy subtypes.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Central nervous system compound synthesis depends on specialized contract manufacturers concentrated in India and China.
- EMA Pediatric Investigation Mandates:Required juvenile safety studies extend development timelines and inflate trial costs for novel antiepileptic entrants.
- Generic Oral Substitution:Established bioequivalent formulations capture maintenance therapy volumes, compressing branded prescription margins.
Strategic Opportunities
- Germany Epilepsy Center Networks:Underpenetrated referral pathways in eastern federal states present whitespace for integrated device-pharmaceutical bundled protocols.
- Closed-Loop AI Convergence:Machine learning seizure prediction algorithms merging with implantable pulse generators enable preemptive intervention before clinical manifestation.
- Remote Patient Monitoring Channels:Telehealth reimbursement expansion creates direct-to-clinician distribution models bypassing traditional hospital pharmacy procurement.
Industry Challenges
- Electroencephalography Specialist Scarcity:Board-certified epileptologist training programs produce insufficient clinicians to interpret ambulatory monitoring data streams.
- Biomarker Validation Timelines:FDA qualification of pharmacodynamic endpoints for patient stratification requires multi-year prospective cohort studies.
- Legacy EMR Integration:Seizure detection devices must interface with heterogeneous hospital information systems, elevating implementation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Partial Onset Seizures Market |
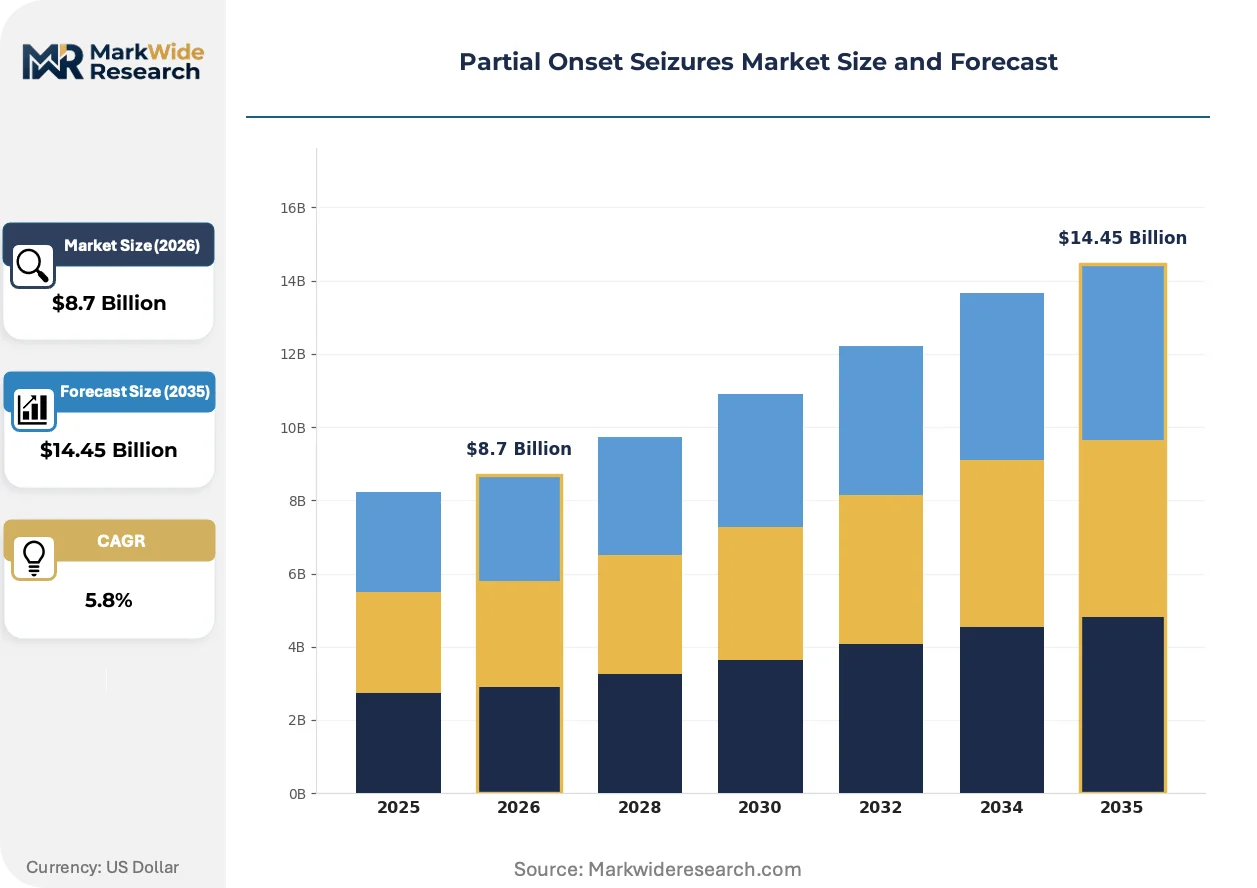
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Medications, Injectable Therapies, Devices, Complementary Therapies End User: Hospitals, Ambulatory Surgical Centers, Home Care, Rehabilitation Centers Delivery Mode: Intravenous, Subcutaneous, Oral, Transdermal Application: Therapeutic, Diagnostic, Monitoring, Research |
| Companies Covered | UCB SA, Pfizer Inc., Novartis AG, GlaxoSmithKline plc, Eisai Co., Ltd., SK Biopharmaceuticals, Jazz Pharmaceuticals, Supernus Pharmaceuticals, Xenon Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Partial Onset Seizures Market Evolving Landscape
Algorithmic seizure forecasting is compressing the therapeutic window from reactive to preemptive intervention. Three convergent developments are restructuring competitive advantage in focal epilepsy management.
Subcutaneous EEG monitoring arrays are decentralizing diagnostic localization from inpatient video-telemetry suites toward outpatient longitudinal recording. Academic epilepsy centers in the United States are deploying these devices for pre-surgical candidacy assessment, reducing hospital bed days while accumulating higher-fidelity cortical mapping data. This modality is decentralizing the economics of epilepsy surgery programs toward ambulatory revenue models.
EMA's Medical Device Regulation (MDR) is elevating clinical evidence requirements for neurostimulation implantables, forcing manufacturers to generate post-market surveillance data through patient registries. The regulation compresses product lifecycle planning horizons and elevates real-world evidence generation costs. German notified bodies are experiencing backlog-induced certification delays, pushing launch timelines for next-generation responsive stimulation systems.
Epilepsy center procurement committees are unbundling device servicing contracts from hardware acquisition, creating standalone after-market revenue pools for algorithm update subscriptions. This purchasing pattern disrupts traditional capital equipment vendors and elevates software-centric competitors. The shift is most pronounced in Japan, where national health insurance reimbursement reforms incentivize outcome-linked payment structures over fee-for-service device implantation.
Partial Onset Seizures Market Segmentation
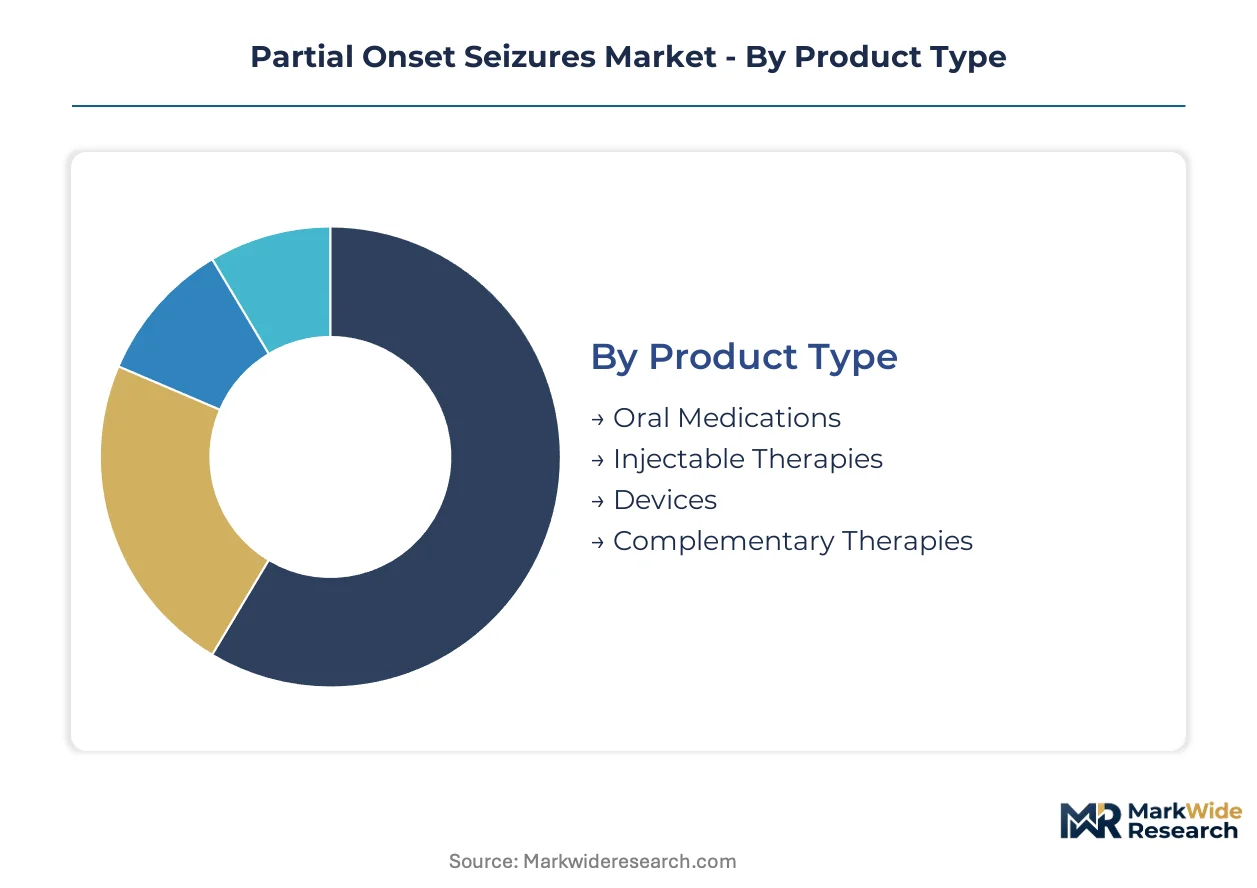
Partial onset seizure management requires precise matching of intervention modality to clinical setting and patient acuity. Segmentation reveals how oral maintenance therapies, acute injectables, and implantable devices occupy distinct economic and utilization tiers across the care continuum.
Product Type:
Standalone pharmaceutical formulations dominate prescription volumes, while embedded neurostimulation systems integrate hardware-software stacks for chronic disease management.
- Oral Medications:Small-molecule antiepileptic compounds formulated for extended-release bioavailability profiles. Demand concentrates in United States maintenance therapy protocols where patient adherence programs drive formulary placement; generic substitution compresses branded margin pools.
- Devices:Responsive neurostimulation implants and closed-loop seizure detection systems requiring surgical placement. Germany's epilepsy center networks generate concentrated procurement volumes; remote algorithm updates create recurring revenue streams detached from hardware replacement cycles.
- Injectable Therapies:Parenteral formulations for acute seizure cessation in controlled settings.
- Complementary Therapies:Adjunctive nutritional and behavioral interventions prescribed alongside pharmacological protocols.
Volume placements concentrate in Oral Medications; the faster expansion belongs to Devices.
End User:
Cost tier stratification separates capital-intensive institutional settings from distributed home-based monitoring environments.
- Hospitals:Academic medical centers with continuous EEG monitoring capabilities and neurosurgical departments. United States tertiary referral networks absorb the highest per-patient intervention costs; FDA Breakthrough Therapy designations accelerate formulary adoption for novel compounds.
- Home Care:Ambulatory settings where subcutaneous EEG arrays and remote clinical oversight replace inpatient telemetry. Japan's reimbursement reforms incentivize outcome-linked payment structures over facility-based fee schedules; patient registries satisfy EMA MDR post-market surveillance mandates.
- Ambulatory Surgical Centers:Outpatient facilities performing device implantation and battery replacement procedures.
- Rehabilitation Centers:Post-acute facilities managing seizure recurrence risk during cognitive and motor recovery protocols.
Revenue concentration sits with Hospitals; Home Care is climbing the fastest.
Delivery Mode:
Application context determines route selection, with acute intervention favoring parenteral administration and chronic management defaulting to enteral absorption pathways.
- Oral:Enteral administration via tablet, capsule, or liquid suspension formulations. United States retail pharmacy networks handle the majority of dispensed volumes; established bioequivalence standards enable rapid generic substitution upon patent expiry.
- Intravenous:Direct vascular delivery for emergency seizure cessation in hospital emergency departments and intensive care units. Germany's hospital procurement frameworks bundle IV antiepileptics into acute neurological care protocols; rapid infusion requirements limit ambulatory deployment.
- Subcutaneous:Depot formulations and implantable drug delivery systems.
- Transdermal:Patch-based administration for patients with swallowing difficulties or adherence challenges.
Prescription volumes flow through Oral delivery; Subcutaneous modalities are gaining share fastest.
Application:
Maturity gradients separate established therapeutic categories from emerging diagnostic and monitoring segments requiring biomarker validation.
- Therapeutic:Pharmacological and device-based interventions targeting seizure frequency reduction and secondary generalization prevention. United States neurologist prescribing patterns favor broad-spectrum antiepileptics with favorable cognitive side-effect profiles; prior authorization requirements stratify access across commercial and public payers.
- Monitoring:Continuous and intermittent electroencephalographic surveillance for seizure detection and pre-surgical localization. Japan's PMDA orphan acceleration pathways compress timelines for novel monitoring algorithms; cloud-based data platforms face HIPAA compliance architecture requirements.
- Diagnostic:Electrophysiological and neuroimaging procedures for seizure classification and etiology determination.
- Research:Clinical trial infrastructure and biomarker development programs.
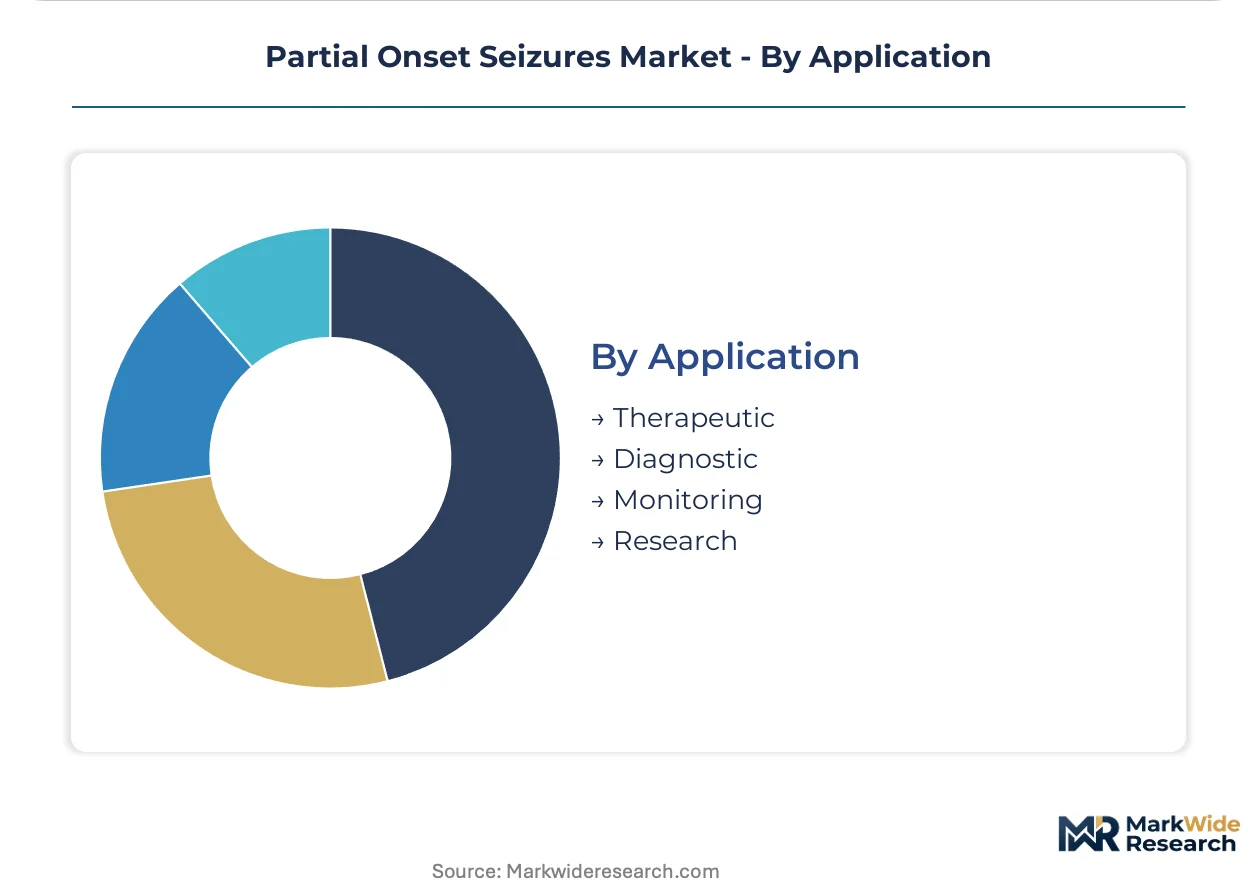
Spending weight rests in Therapeutic applications; Monitoring demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors the highest concentration of academic epilepsy centers in North America, with Massachusetts General Hospital and Brigham and Women's Hospital driving continuous EEG monitoring protocol development. These institutions generate pull-through demand for advanced antiepileptic therapies and implantable neurostimulation systems.
United States
Academic medical centers in Boston, Baltimore, and Cleveland scale continuous EEG monitoring protocols, creating institutional demand for adjunctive device therapies. FDA Breakthrough Therapy designations accelerate formulary adoption for novel compounds targeting drug-resistant focal epilepsy. The Cleveland Clinic epilepsy center network in Ohio generates concentrated procurement volumes for responsive neurostimulation systems.
Germany
Epilepsy center networks in Bavaria and North Rhine-Westphalia absorb the majority of European neurostimulation implant volumes. EMA Medical Device Regulation elevates clinical evidence requirements, forcing manufacturers to generate post-market surveillance data through patient registries. Berlin-based notified bodies experience backlog-induced certification delays for next-generation responsive stimulation systems.
Japan
PMDA orphan acceleration pathways compress regulatory timelines for novel antiepileptic mechanisms targeting rare focal epilepsy subtypes. National health insurance reimbursement reforms incentivize outcome-linked payment structures over fee-for-service device implantation. Tokyo's National Center of Neurology and Psychiatry anchors clinical trial infrastructure for closed-loop seizure detection algorithms.
United Kingdom
NHS England's specialized commissioning framework concentrates epilepsy surgery referrals to 25 designated centers across Greater London, Oxford, and Manchester. NICE technology appraisals determine reimbursement eligibility for novel antiepileptic drugs, creating formulary gatekeeping dynamics. The National Hospital for Neurology and Neurosurgery in London generates the highest surgical candidacy assessment volumes in Europe.
Switzerland
Swissmedic maintains accelerated review pathways for pediatric neurological indications, compressing timelines for juvenile safety study submissions. University Hospital Zurich and Geneva University Hospital anchor German-speaking and French-speaking referral networks respectively. Basel's pharmaceutical manufacturing corridor supplies active pharmaceutical ingredients for central nervous system compound synthesis.
Partial Onset Seizures Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established neurology franchises. Consolidation around mid-sized biotechnology specialists and legacy antiepileptic manufacturers creates a tiered vendor ecosystem. Three archetypes dominate: Belgian-Swiss central nervous system specialists, diversified American pharmaceutical conglomerates, and Korean-Japanese mechanism-of-action innovators. Capacity expansion in continuous manufacturing and strategic partnerships for algorithm development represent the dominant competitive vectors.
Among the established central nervous system specialists, UCB SA anchors the Belgian manufacturing base for neurology therapies, while Pfizer Inc. exemplifies geographic diversification of active pharmaceutical ingredient sourcing. Novartis AG occupies a position within the diversified pharmaceutical conglomerate tier. These three entities represent distinct strategic postures: captive European manufacturing, distributed global supply chains, and integrated research-to-commercialization platforms.
| Leading Market Players |
|---|
| UCB SA |
| Pfizer Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Eisai Co., Ltd. |
| SK Biopharmaceuticals |
| Jazz Pharmaceuticals |
| Supernus Pharmaceuticals |
| Xenon Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Outcome-linked reimbursement tiers separate premium closed-loop neurostimulation systems from commodity oral antiepileptic generics, with this bifurcation manifesting in divergent supply chain configurations across branded device manufacturers and API-dependent pharmaceutical formulators. Japan's national health insurance reforms reward algorithm-validated seizure reduction rates, while United States payers impose prior authorization barriers that concentrate margin pools among vertically integrated neurology specialists.
Pricing Analysis
Value-based pricing anchors on seizure freedom rates and hospitalization avoidance metrics, with responsive neurostimulation systems commanding three-tier pricing structure across premium, standard, and economy levels based on algorithm sophistication and remote monitoring bundling. Price differentiation stems from FDA Breakthrough Therapy designation tier and geographic delivery cost to epilepsy center networks. Cost compression in oral maintenance therapy intensifies because generic substitution erodes branded compound margins. Hospital procurement committees exhibit lowest price sensitivity for implantable devices, while retail pharmacy channels face highest pressure from bioequivalent substitution.
Supply Chain Analysis
Domestic-content mandates in the EU Green Deal pharmaceutical sustainability framework are reshaping active pharmaceutical ingredient sourcing toward European contract manufacturing. Central nervous system compound synthesis draws from specialized manufacturers concentrated in India, China, and Switzerland. Raw material dependencies include specialized neurotransmitter analog precursors, implantable pulse generator batteries, and biocompatible electrode arrays. Single-source vulnerability sits with concentrated epileptologist training programs limiting device interpretation capacity. Distribution runs through hospital pharmacy procurement committees in academic medical centers and direct-to-clinician telehealth channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EMA Medical Device Regulation compliance costs and post-market surveillance mandates force subscale device manufacturers toward strategic exits.
For Market Incumbents: Anchor market position through backward integration into continuous manufacturing of antiepileptic active pharmaceutical ingredients and captive supply of implantable pulse generator components. UCB SA's Belgian manufacturing base exemplifies supply chain control insulating against API concentration risk. Defend against algorithm-centric competitors by accelerating real-world evidence generation through patient registry investments satisfying EMA MDR mandates. For New Entrants and Emerging Players: Machine learning seizure prediction algorithms offer technology-first wedge into underpenetrated eastern German federal states where epilepsy center referral networks remain fragmented. Target ambulatory surgical centers performing device battery replacements as lowest-barrier entry point. Pursue direct-to-clinician distribution models leveraging Japan's telehealth reimbursement expansion to bypass entrenched hospital pharmacy procurement. For Investors and Strategic Acquirers: Re-rating potential sits with closed-loop AI convergence specialists given FDA qualification of pharmacodynamic biomarker endpoints compressing trial timelines. Long-term viability favors vertically integrated neurology platforms with captive manufacturing and algorithm development capabilities. Watch for inflection signals in closed-loop algorithm validation timelines as predictive seizure intervention gains reimbursement traction.| Strategic Initiative | Industry Significance |
|---|---|
| Patient Registry Investment | EMA MDR post-market surveillance mandates elevate real-world evidence generation as competitive barrier. |
| Algorithm Licensing Agreement | Machine learning seizure prediction partnerships compress development timelines for preemptive intervention systems. |
| Manufacturing Scale-Up | Continuous manufacturing investments in Belgian and Swiss corridors secure API supply chain advantages. |
| Reimbursement Strategy | Japan's outcome-linked payment reforms reward seizure reduction metrics over device implantation fees. |
| Hospital System Partnership | Cleveland Clinic and Massachusetts General networks generate pull-through demand for integrated device-pharmaceutical protocols. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database audits and CMS Medicare reimbursement records. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated quantitative assumptions. Bottom-up prescription volume modeling and top-down neurology therapeutic area spending estimates were triangulated against epilepsy center capacity data.
Bottom-up modeling anchored on continuous EEG monitoring protocol expansion across academic medical centers, cross-referenced against neurostimulation implant procedure volumes. Segmentation dimensions included treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from longitudinal patient registry data and epidemiological prevalence projections. Forecast inputs incorporated FDA Breakthrough Therapy designation timelines and PMDA orphan acceleration pathway compression effects.
Several conditions sit outside the modeled scope, including geopolitical disruption to API supply corridors and unforeseen biomarker qualification failures. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement parity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Zygomycosis Treatments Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Brugada Syndrome Market