
 Progressive Multifocal Leukoencephalopathy Treatment Market | 2026-2036
Progressive Multifocal Leukoencephalopathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Progressive Multifocal Leukoencephalopathy Treatment Market Analytics
FDA accelerated approval pathways for rare neurological diseases is restructuring the cost-of-entry calculus for developers targeting progressive multifocal leukoencephalopathy. Pfizer Inc. leverages its infectious disease franchise to sustain research commitments in polyomavirus-directed therapies. Merck & Co., Inc. anchors its position through established antiviral platforms with demonstrated CNS penetration capabilities. Biogen Inc. differentiates via neuroimmunology expertise that aligns with the JC virus-mediated demyelination mechanism underlying this condition.
Progressive multifocal leukoencephalopathy treatment encompasses therapeutic interventions targeting JC virus replication and immune reconstitution in patients with compromised cellular immunity, primarily utilizing monoclonal antibodies engineered for blood-brain barrier transit and immunomodulators that restore pathogen-specific T-cell responses without triggering immune reconstitution inflammatory syndrome. The primary purpose centers on halting oligodendrocyte destruction and neurological deterioration in immunosuppressed populations, including HIV/AIDS patients and multiple sclerosis recipients of natalizumab. Monoclonal antibodies command the dominant margin pool due to manufacturing complexity and orphan pricing dynamics, while intrathecal delivery modes represent the fastest-growing structural segment as clinicians pursue direct CNS drug concentration. Oral formulations remain the most mature category, constrained by blood-brain barrier limitations that reduce therapeutic efficacy in established disease.
FDA orphan drug designation and EMA priority medicines frameworks shape demand by granting market exclusivity and protocol assistance that de-risk development programs for ultra-rare indications. WHO essential medicines criteria and national health technology assessment bodies in Germany, France, and England subsequently determine reimbursement access and real-world utilization thresholds. Stakeholders must monitor evolving JC virus seroprevalence data and next-generation sequencing diagnostics that could redefine addressable patient populations and shift treatment initiation criteria.
Market Dynamics
FDA orphan drug incentives and EMA priority medicines frameworks are restructuring development economics for ultra-rare neurological therapeutics, concentrating investment toward monoclonal antibody platforms with demonstrated blood-brain barrier transit.
Growth Catalysts
- Orphan drug exclusivity provisions:FDA grants seven-year market exclusivity and tax credits for clinical trial costs, de-risking investment in polyomavirus-directed therapies. Developers file accelerated approval pathways to compress time-to-market for immunocompromised populations.
- JC virus seroprevalence monitoring:Expanded screening protocols among natalizumab-treated multiple sclerosis patients identify at-risk individuals before neurological symptom onset. Diagnostic expansion enlarges the addressable patient pool for preemptive intervention.
- Intrathecal delivery infrastructure:Hospital-based neurointerventional suites install specialized administration capabilities for direct CNS drug concentration. Academic medical centers build referral networks capturing complex neuroinfectious cases.
Market Restraints
- Plasma-derived raw material volatility:Monoclonal antibody manufacturing depends on fractionated plasma supply concentrated in United States collection centers. Input cost fluctuations compress margin pools for developers without captive plasma sourcing.
- Blood-brain barrier pharmacokinetics:Oral antiviral formulations demonstrate limited CNS penetration, reducing therapeutic efficacy in established demyelination. Clinicians default to invasive delivery modes with higher complication profiles.
- Reimbursement fragmentation across EU member states:Germany's G-BA, France's HAS, and England's NICE apply divergent health technology assessment criteria for ultra-rare indications. Parallel submission requirements extend market access timelines.
Strategic Opportunities
- Next-generation sequencing diagnostics:Viral load quantification and JC virus variant identification enable precision treatment initiation. Laboratory-developed tests create companion diagnostic revenue streams.
- Immune reconstitution without inflammatory syndrome:Cell therapy platforms targeting pathogen-specific T-cell responses address the fundamental immunological deficit. Adoptive transfer protocols from HIV/AIDS research migrate into PML applications.
- Swissmedic and TGA early access schemes:Switzerland and Australia operate compassionate use frameworks with streamlined regulatory review. These jurisdictions serve as launch pads for clinical data generation preceding FDA submission.
Industry Challenges
- Neuroimmunology specialist scarcity:Qualified investigators capable of managing immune reconstitution inflammatory syndrome remain concentrated at academic medical centers. Site activation for clinical trials encounters principal investigator bottlenecks.
- Good Manufacturing Practice compliance for intrathecal formulations:Sterile processing requirements for CNS-directed biologics demand specialized facility investment. Contract manufacturing organizations with neurointerventional drug capabilities command premium pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Progressive Multifocal Leukoencephalopathy Treatment Market |
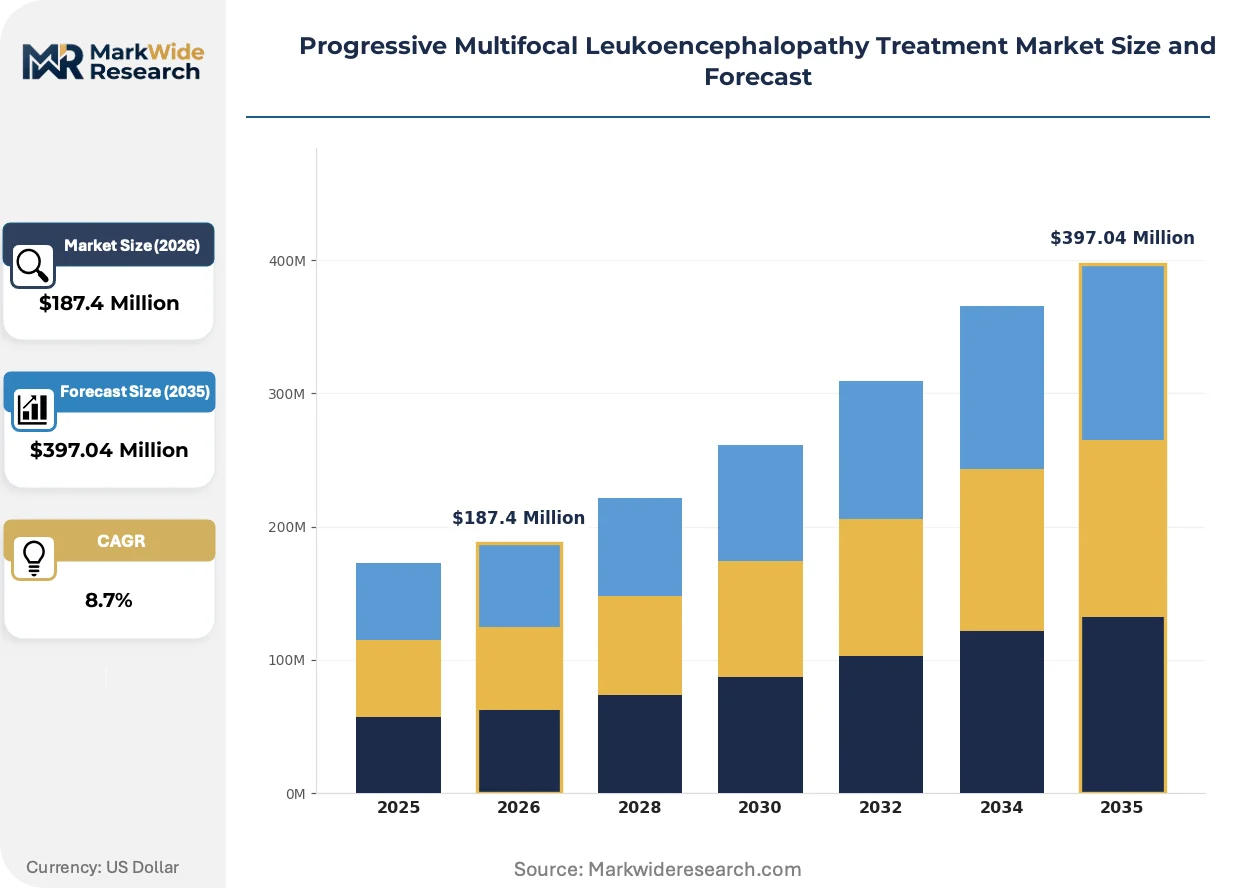
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Antiviral Agents, Immunomodulators, Supportive Care Delivery Mode: Intravenous, Subcutaneous, Oral, Intrathecal Application: Clinical Trials, Off-label Use, Compassionate Use, Routine Treatment End User: Hospitals, Specialty Clinics, Research Institutions, Home Care |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Roche Holding AG, Novartis AG, Biogen Inc., Bristol-Myers Squibb Company, Gilead Sciences, Inc., AbbVie Inc., NeoImmuneTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Progressive Multifocal Leukoencephalopathy Treatment Market Evolving Landscape
Antiviral mechanism innovation and diagnostic modality advancement are compressing treatment windows and reshaping prescriber decision criteria across immunocompromised patient management.
Bispecific antibody engineering is rewriting therapeutic possibilities for JC virus-mediated demyelination. These constructs simultaneously engage viral epitopes and facilitate blood-brain barrier transit through receptor-mediated transport. Academic medical centers in the United States and Germany are adopting bispecific platforms for compassionate use protocols. The technology is compressing development timelines for next-generation PML therapeutics by validating dual-target mechanisms in parallel.
EMA's priority medicines scheme and FDA's breakthrough therapy designation are creating parallel regulatory tracks for rare neurological diseases. These frameworks permit rolling review and accelerated assessment based on surrogate endpoints. Developers targeting polyomavirus infections file coordinated submissions across both agencies to maximize protocol assistance benefits. The policy shift is compressing regulatory lag for monoclonal antibody candidates with demonstrated CNS penetration.
Specialized infectious disease pharmacies are displacing traditional hospital procurement for high-complexity neurointerventional biologics. These distributors provide cold-chain logistics, patient registry management, and outcomes tracking required for risk evaluation and mitigation strategies. The channel shift concentrates purchasing power among three national specialty pharmacy networks in the United States. Academic medical centers in Boston, San Francisco, and Baltimore have transitioned the majority of intrathecal therapy procurement to these specialized intermediaries.
Progressive Multifocal Leukoencephalopathy Treatment Market Segmentation
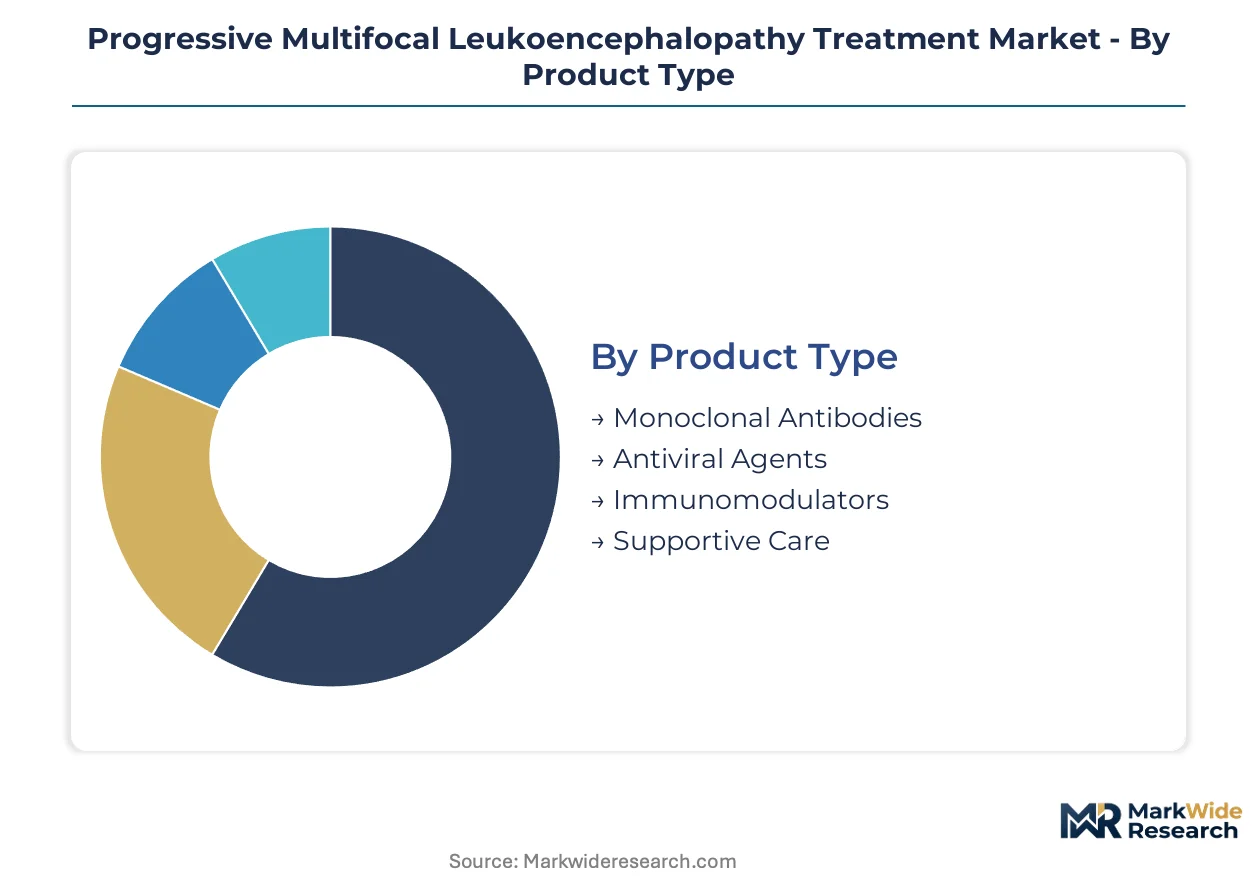
Therapeutic modality selection in progressive multifocal leukoencephalopathy hinges on blood-brain barrier penetration requirements and immune reconstitution risk profiles. Segmentation reveals how manufacturing complexity, delivery infrastructure, and regulatory pathway shape competitive positioning across patient access tiers.
Product Type:
Clinicians weigh manufacturing reliability against CNS penetration efficacy when selecting therapeutic class.
- Monoclonal Antibodies:Engineered immunoglobulins with Fc-modified regions enabling receptor-mediated blood-brain barrier transit. Demand concentrates at academic medical centers in the United States and Germany where neurointerventional suites support intrathecal administration; orphan pricing dynamics sustain premium positioning despite plasma-derived raw material volatility.
- Antiviral Agents:Small-molecule inhibitors targeting JC virus DNA polymerase and helicase enzymes. Oral formulations dominate outpatient prescribing in HIV/AIDS treatment networks, though limited CNS bioavailability constrains efficacy in established demyelination cases.
- Immunomodulators:Therapeutics restoring pathogen-specific T-cell responses without triggering immune reconstitution inflammatory syndrome.
- Supportive Care:Palliative interventions addressing neurological symptom progression and quality-of-life maintenance.
Monoclonal antibodies lead on scale through orphan exclusivity margins; immunomodulators lead on momentum via cell therapy platform migration from HIV research.
Delivery Mode:
Route selection reflects disease stage, CNS involvement depth, and site-of-care capabilities.
- Intravenous:Systemic administration leveraging established oncology infusion infrastructure. United States hospital networks with infectious disease specialty pharmacies command volume concentration; cold-chain logistics requirements favor centralized procurement through national specialty distributors.
- Intrathecal:Direct cerebrospinal fluid delivery bypassing blood-brain barrier constraints. Neurointerventional suites at Boston, San Francisco, and Baltimore academic centers drive adoption; specialized sterile processing capabilities limit manufacturing site qualification.
- Subcutaneous:Patient-administered alternative reducing hospital dependency for maintenance dosing.
- Oral:Convenience-first administration constrained by pharmacokinetic limitations in neuroinfectious indications.
Intravenous delivery dominates current volume through infrastructure ubiquity; intrathecal administration climbs fastest as prescriber confidence in direct CNS concentration builds.
Application:
Regulatory pathway determines reimbursement eligibility and prescriber liability exposure.
- Clinical Trials:Investigational protocols under FDA or EMA oversight with protocol assistance frameworks. Principal investigator scarcity at qualified neuroimmunology sites constrains site activation; academic medical centers in Germany and Switzerland leverage early access schemes for data generation.
- Compassionate Use:Pre-approval access for patients failing standard interventions. Swissmedic and TGA frameworks enable streamlined regulatory review; these jurisdictions serve as launch pads preceding FDA submission.
- Off-label Use:Prescriber-directed administration outside approved indications.
- Routine Treatment:Standard-of-care protocols following regulatory approval and health technology assessment clearance.
Clinical trials anchor current development investment; compassionate use programs expand most quickly as regulatory agencies streamline ultra-rare disease access.
End User:
Care setting selection tracks disease complexity, reimbursement mechanics, and specialist availability.
- Hospitals:Inpatient and outpatient facilities with neurointerventional capabilities and infectious disease specialist coverage. United States demand concentrates at tertiary centers with risk evaluation and mitigation strategy infrastructure; Medicare reimbursement rates for complex neuroinfectious interventions exceed European benchmarks.
- Specialty Clinics:Outpatient facilities focused on neuroimmunology and infectious disease management. Multiple sclerosis treatment centers with natalizumab monitoring programs identify at-risk patients through JC virus seroprevalence screening.
- Research Institutions:Academic medical centers conducting investigator-initiated trials and compassionate use protocols.
- Home Care:Subcutaneous and oral administration settings reducing hospital dependency.
Hospitals retain volume leadership through intrathecal delivery requirements; specialty clinics gain share fastest via screening protocol expansion among immunosuppressed populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neuroimmunology specialists concentrate at academic medical centers in the United States, Germany, and Switzerland, anchoring clinical trial infrastructure for JC virus-directed therapies. These talent clusters attract pharmaceutical investment and shape regional adoption patterns for intrathecal delivery modalities.
United States
FDA orphan drug exclusivity provisions and accelerated approval pathways de-risk development economics for polyomavirus-directed monoclonal antibodies. Medicare reimbursement rates for complex neuroinfectious interventions exceed European benchmarks, concentrating hospital-based demand. Boston, San Francisco, and Baltimore academic medical centers operate specialized neurointerventional suites for direct CNS drug administration.
Germany
G-BA health technology assessment frameworks determine reimbursement access for ultra-rare neurological therapeutics, extending market access timelines relative to FDA pathways. JC virus seroprevalence screening protocols among natalizumab-treated multiple sclerosis patients expand the addressable at-risk population. Heidelberg and Munich academic clusters lead investigator-initiated trials for bispecific antibody platforms.
Switzerland
Swissmedic early access schemes enable streamlined compassionate use frameworks for pre-approval therapies, serving as launch pads for clinical data generation. Basel and Zurich pharmaceutical research corridors host specialized infectious disease units with risk evaluation and mitigation strategy infrastructure. The country's national pharmaceutical regulator prioritizes ultra-rare disease protocols.
United Kingdom
NICE health technology assessment criteria apply stringent cost-effectiveness thresholds for orphan neurological indications, constraining routine treatment adoption. London and Cambridge neuroimmunology centers leverage EMA priority medicines frameworks for parallel regulatory submissions. NHS specialized commissioning processes concentrate intrathecal therapy access at designated tertiary centers.
Japan
PMDA orphan drug designation provides tax incentives and protocol assistance for developers targeting JC virus replication mechanisms. Tokyo and Osaka academic medical centers build referral networks for immunocompromised patient populations with progressive multifocal leukoencephalopathy. The country's national pharmaceutical regulator emphasizes surrogate endpoint validation for accelerated assessment.
Progressive Multifocal Leukoencephalopathy Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the therapeutic modality spectrum, creating a tiered structure where infectious disease franchises anchor investment while biotechnology startups pioneer cell therapy platforms. The vendor base organizes around three strategic archetypes: large-cap pharmaceutical houses with antiviral portfolios, mid-cap neuroimmunology specialists, and emerging biotechnology firms with adoptive T-cell platforms. Consolidation pressure intensifies as plasma-derived raw material volatility favors backward integration into captive plasma sourcing. Strategic partnerships between academic medical centers and developers accelerate site activation for clinical trials.
Among large-cap pharmaceutical houses, Pfizer Inc. and Merck & Co., Inc. occupy positions reflecting established infectious disease franchises, while Biogen Inc. sits within the neuroimmunology specialist tier leveraging demyelination mechanism expertise. These three entities exemplify divergent strategic anchors: antiviral platform breadth versus CNS-focused immunology depth. Roche Holding AG and Novartis AG represent diversified conglomerates with oncology infrastructure adaptable to neurointerventional biologics. The competitive dynamic centers on blood-brain barrier transit capabilities and orphan pricing sustainability rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Roche Holding AG |
| Novartis AG |
| Biogen Inc. |
| Bristol-Myers Squibb Company |
| Gilead Sciences, Inc. |
| AbbVie Inc. |
| NeoImmuneTech |
| Others |
Value Network & Pricing Analysis
Academic medical center procurement concentration in the United States and Germany anchors orphan drug pricing power for monoclonal antibody therapies, with hospital-based neurointerventional suites capturing volume through risk evaluation and mitigation strategy infrastructure. This buyer archetype concentration enables premium positioning for intrathecal formulations despite plasma-derived input volatility.
Pricing Analysis
Bundled service contracts combining drug acquisition with neurointerventional administration dominate hospital procurement, while unbundled per-dose pricing persists in compassionate use channels. Three-tier pricing structure across orphan-premium, standard-intravenous, and economy-supportive care levels reflects blood-brain barrier penetration efficacy and manufacturing complexity. Cost compression in intrathecal manufacturing is intensifying because sterile processing facility scarcity limits contract manufacturing organization capacity. Price sensitivity concentrates among European hospital networks facing divergent health technology assessment timelines, while United States academic centers demonstrate lowest sensitivity due to Medicare reimbursement premiums for complex neuroinfectious interventions.
Supply Chain Analysis
Reverse logistics for temperature-controlled biologics—cold-chain returns, expired lot refurbishment, and remanufacturing of plasma-derived intermediates—operates through specialized infectious disease pharmacy networks. Manufacturing draws from United States plasma collection centers, Swiss sterile processing facilities, and German academic medical center compounding sites. Supply chain risk centers on single-source vulnerability for Fc-modified antibody engineering platforms. Distribution runs through three national specialty pharmacy networks with patient registry management capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways in the United States compress development timelines relative to EMA parallel submission requirements, creating cost arbitrage for developers prioritizing North American market entry first. This regulatory differential rewards strategic sequencing across jurisdictions.
For Market Incumbents: Extend manufacturing capacity into captive plasma sourcing to offset fractionated raw material volatility threatening margin pools. Secure neurointerventional suite partnerships at Boston, San Francisco, and Baltimore academic medical centers to lock in channel control against emerging bispecific antibody competitors. For New Entrants and Emerging Players: Enter via Swissmedic early access schemes and TGA compassionate use frameworks to generate clinical data preceding FDA submission. Target cell therapy platforms for immune reconstitution without inflammatory syndrome as the most penetrable white space, leveraging adoptive T-cell transfer protocols migrating from HIV/AIDS research. For Investors and Strategic Acquirers: Large-cap pharmaceutical houses with infectious disease franchises are the most active acquirers in this space, seeking monoclonal antibody platforms with demonstrated CNS penetration. Long-term viability over the next decade hinges on blood-brain barrier transit capabilities rather than manufacturing scale alone. Watch for JC virus seroprevalence screening protocol expansion among natalizumab-treated multiple sclerosis patients as the signal indicating addressable patient pool inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Bispecific antibody platforms at Heidelberg and Munich academic clusters validate dual-target mechanisms in parallel. |
| Regulatory Approval Pathway | FDA orphan drug designation with EMA priority medicines parallel submission maximizes protocol assistance benefits. |
| Manufacturing Scale-Up | Sterile processing investment for intrathecal formulations addresses CMO capacity bottlenecks. |
| Companion Diagnostic Development | Next-generation sequencing viral load quantification creates laboratory-developed test revenue streams. |
| Specialty Pharmacy Partnership | National distributor networks with cold-chain logistics capture hospital procurement channel shift. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation anchored market size estimation.
Segment-weighting across therapeutic modality, delivery mode, application pathway, and end-user setting shaped the analytical framework over the projection horizon. CAGRs derived from epidemiological trend extrapolation, pricing trajectory modeling, and adoption curve analysis for intrathecal administration. Forecast inputs incorporated JC virus seroprevalence screening expansion rates and neurointerventional suite installation timelines.
Inputs from clinical trial registries and health technology assessment body determinations were available through the study window; gaps in real-world utilization data for compassionate use programs introduce uncertainty bands around adoption curve assumptions. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement clearance probabilities. Practitioners should monitor evolving JC virus variant identification through next-generation sequencing diagnostics and immune reconstitution inflammatory syndrome incidence rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Mucinoses Management Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Axillary Hyperhidrosis Treatment Market
Specialty Medicine
Mantle Cell Lymphoma Market