
 Adenomyosis Market | 2026-2036
Adenomyosis Market Size, Share, and Industry Trends Forecast 2026-2036
Adenomyosis Market Analysis
Asset-light licensing and royalty-based partnership structures is fragmenting competitive dynamics across the adenomyosis treatment landscape. AbbVie Inc. leverages its endometriosis-drug infrastructure to cross-sell into adenomyosis protocols. Bayer AG anchors its position through sustained investment in hormonal therapy platforms. Pfizer Inc. competes by extending its pain-management portfolio into gynecological indications.
Adenomyosis is a benign gynecological condition characterized by ectopic endometrial tissue within the myometrium, causing diffuse uterine enlargement, dysmenorrhea, and menorrhagia; diagnosis relies on transvaginal ultrasound or MRI with junctional zone thickness exceeding 12 millimeters as a key imaging parameter. The primary clinical purpose centers on symptom alleviation, fertility preservation, and surgical intervention when conservative measures fail. Hormonal therapy dominates current prescribing patterns due to established efficacy profiles and reversibility, while surgical solutions command premium positioning where pharmacological control proves inadequate. Diagnostic tools represent an emerging margin pool as non-invasive imaging protocols displace hysterectomy-based confirmation.
The FDA maintains stringent premarket review pathways for novel gynecological devices, extending development timelines but elevating clinical evidence standards that shape physician trust. EMA's MDR framework imposes additional post-market surveillance obligations on manufacturers seeking European access, creating compliance differentiation among multinational suppliers. Stakeholders must monitor evolving reimbursement policies for fertility-sparing procedures versus hysterectomy alternatives, as payer decisions will determine which technology investments yield sustainable returns.
Market Dynamics
The FDA's evolving premarket review pathways for gynecological devices are compressing development timelines while elevating clinical evidence standards, forcing manufacturers to front-load investment in longitudinal efficacy data before commercialization.
Growth Catalysts
- Minimally invasive surgical protocols:Outpatient clinics across the United States are expanding hysteroscopic and laparoscopic capacity, reducing recovery times and facility costs for adenomyosis intervention.
- EMA MDR framework:Post-market surveillance obligations are creating compliance differentiation that rewards manufacturers with robust clinical infrastructure, accelerating consolidation among well-capitalized suppliers.
- Junctional zone imaging:Transvaginal ultrasound protocols with 12-millimeter threshold standardization are expanding diagnostic access beyond tertiary centers into community radiology practices.
Market Restraints
- Specialist workforce concentration:Fellowship-trained minimally invasive gynecologic surgeons cluster in urban academic medical centers, limiting procedure access in rural and exurban United States markets.
- Reimbursement uncertainty:Payer categorization of fertility-sparing procedures versus hysterectomy alternatives remains inconsistent across commercial insurers and Medicaid programs.
- Hormonal therapy substitution:Endometriosis-focused pharmacological platforms absorb R&D investment that might otherwise target adenomyosis-specific mechanisms.
Strategic Opportunities
- Integrated health system standardization:United States-based IDNs with centralized purchasing are creating fast-track evaluation pathways for devices demonstrating protocol compatibility.
- Remote patient monitoring convergence:Wearable menstrual tracking combined with telemedicine triage is opening channel access for pharmaceutical adherence programs.
- Diagnostic imaging AI:Machine learning classification of junctional zone heterogeneity on standard ultrasound is reducing MRI dependency and cost barriers.
Industry Challenges
- Clinical trial recruitment:Patient heterogeneity in adenomyosis phenotype expression complicates endpoint standardization for FDA premarket approval studies.
- Legacy EHR integration:Gynecology-specific workflow modules within dominant United States hospital information systems require costly customization for device connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adenomyosis Market |
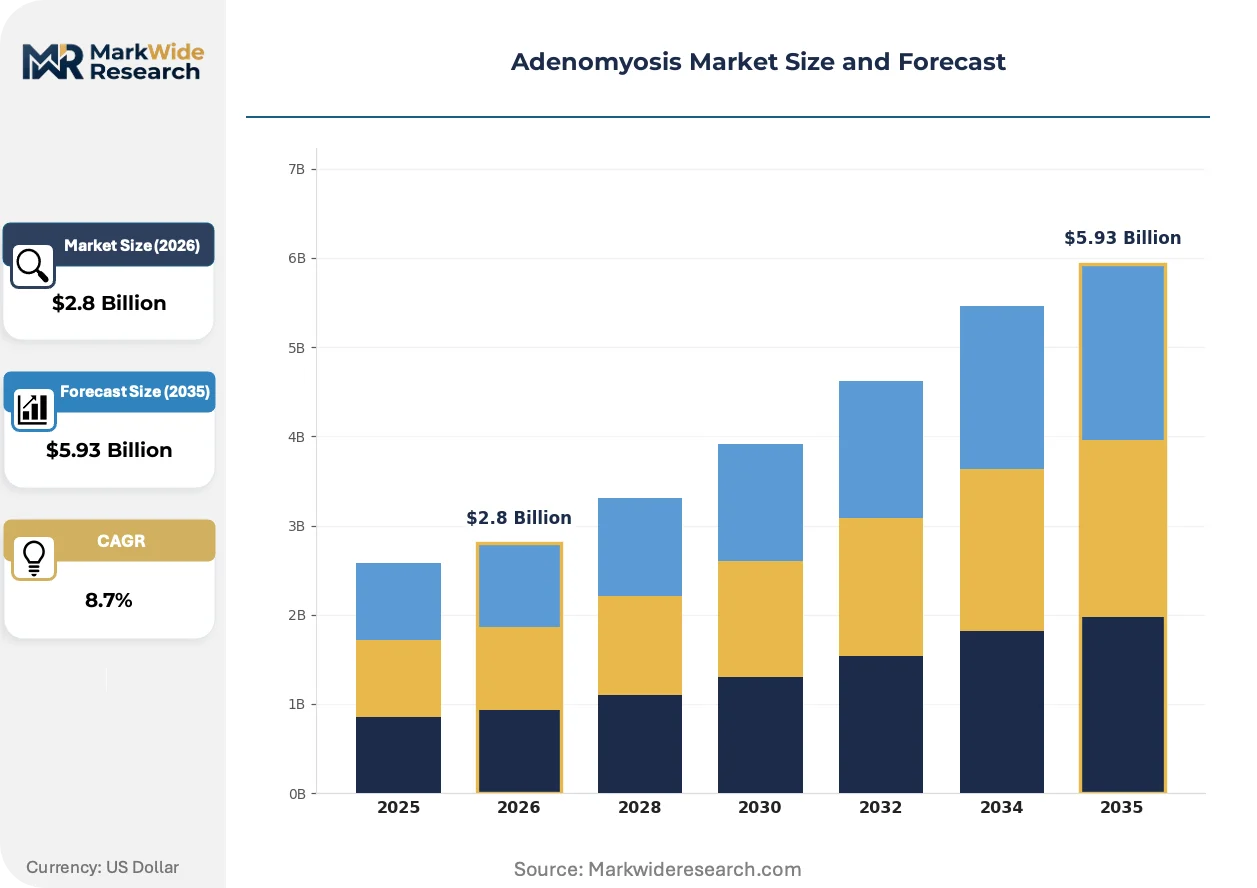
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Pain Relief Medications, Surgical Solutions, Diagnostic Tools End User: Hospitals, Outpatient Clinics, Specialty Clinics, Home Healthcare Technology: Laparoscopic Techniques, Ultrasound Imaging, Hormone Therapy, Medication Delivery Systems Application: Symptom Management, Fertility Preservation, Surgical Treatment, Diagnostic Assessment |
| Companies Covered | Bayer AG, AbbVie Inc., Pfizer Inc., Merck KGaA, Novartis AG, Johnson & Johnson Services, Inc., Ferring B.V., Teva Pharmaceutical Industries Ltd., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adenomyosis Market Emerging Trajectories
Non-invasive diagnostic protocols and digital therapeutics are compressing the traditional care pathway from symptom onset to definitive management, reducing hysterectomy rates and shifting economic value toward upstream intervention.
High-resolution transvaginal ultrasound with automated junctional zone measurement is replacing MRI as the first-line diagnostic standard in United States outpatient settings. Community radiology groups are adopting this technology to retain gynecology referral volumes. The shift is rendering obsolete the historical requirement for surgical confirmation before treatment initiation.
FDA guidance on gynecological device clinical trial design now mandates longer follow-up periods for fertility-sparing interventions. Manufacturers must demonstrate sustained symptom control across menstrual cycles rather than acute procedural success. United States-based sponsors are responding by restructuring study protocols to capture real-world evidence alongside pivotal trials.
Patient-initiated care pathways through direct-to-consumer menstrual health platforms are disrupting traditional OB-GYN gatekeeper relationships. These channels capture symptom data upstream and route appropriate cases to specialized adenomyosis clinics. The pattern is most visible in United States metropolitan markets with high digital health literacy and employer-sponsored fertility benefits.
Adenomyosis Market Segmentation
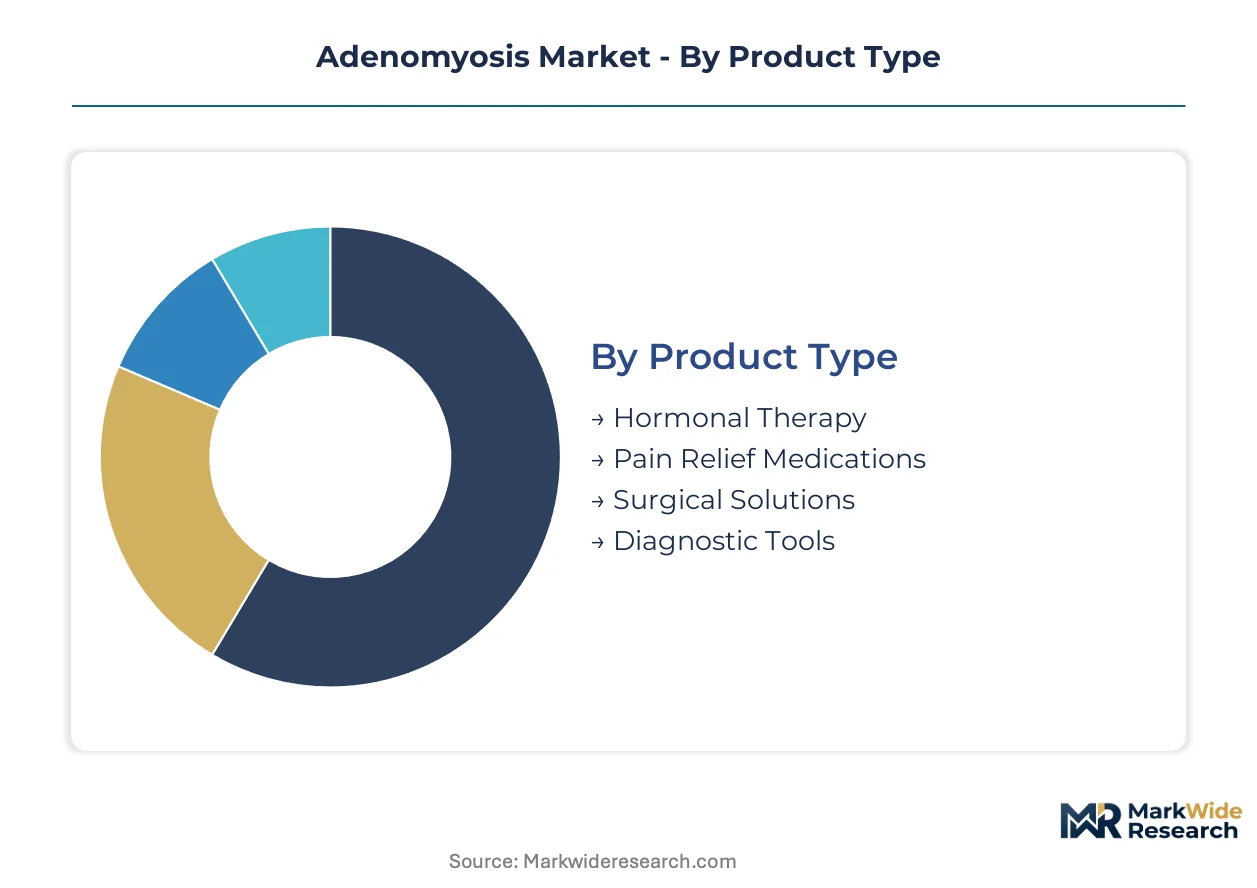
Adenomyosis treatment pathways diverge sharply across patient phenotypes, clinical settings, and intervention goals. Segmentation reveals where pharmaceutical platforms command recurring revenue versus where surgical and diagnostic technologies capture episodic premium. Understanding these divisions clarifies which product architectures align with shifting care delivery models.
Product Type:
Cost tier stratification separates chronic management solutions from capital-intensive interventions and disposable diagnostics.
- Hormonal Therapy:GnRH agonists and progestin-releasing intrauterine systems deliver reversible symptom suppression through endocrine pathway modulation. United States integrated delivery networks prioritize these agents for their protocol standardization and outpatient dispensing economics.
- Surgical Solutions:Hysteroscopic endometrial ablation and laparoscopic myometrial excision address pharmacological failures with definitive tissue removal. Fellowship-trained surgeons in urban academic centers drive demand concentration despite limited rural availability.
- Pain Relief Medications:NSAIDs and targeted analgesics provide adjunctive control for dysmenorrhea flares.
- Diagnostic Tools:Transvaginal ultrasound platforms with automated junctional zone measurement displace MRI in community radiology practices.
Hormonal Therapy commands the established base. The steepest expansion runs through Diagnostic Tools.
End User:
Volume concentration tracks the migration of adenomyosis care from inpatient surgical suites toward ambulatory and remote settings.
- Outpatient Clinics:Minimally invasive hysteroscopic and laparoscopic capacity expansion reduces recovery times and facility overhead. United States metropolitan markets with employer-sponsored fertility benefits show fastest procedure volume growth.
- Hospitals:Tertiary centers retain complex fertility-sparing surgeries and adenomyosis-endometriosis overlap cases requiring multidisciplinary coordination.
- Specialty Clinics:Dedicated adenomyosis centers capture referrals from direct-to-consumer menstrual health platforms.
- Home Healthcare:Self-administered hormonal regimens and remote monitoring support chronic management outside clinical facilities.
Hospitals anchor the revenue base. Outpatient Clinics are climbing the fastest as procedural economics shift.
Technology:
Application focus distinguishes imaging modalities from therapeutic delivery mechanisms and surgical instrumentation.
- Ultrasound Imaging:High-resolution transvaginal protocols with 12-millimeter junctional zone threshold standardization enable community-based diagnosis without MRI referral. United States radiology groups adopt this to retain gynecology referral volumes.
- Laparoscopic Techniques:Robotic-assisted and conventional minimally invasive approaches reduce hysterectomy rates through targeted myometrial intervention.
- Hormone Therapy:Long-acting reversible formulations improve adherence compared to daily oral regimens.
- Medication Delivery Systems:Intrauterine and subcutaneous depot technologies extend dosing intervals for chronic suppression.
Ultrasound Imaging dominates diagnostic workflows. Laparoscopic Techniques show the steepest capability investment from device manufacturers.
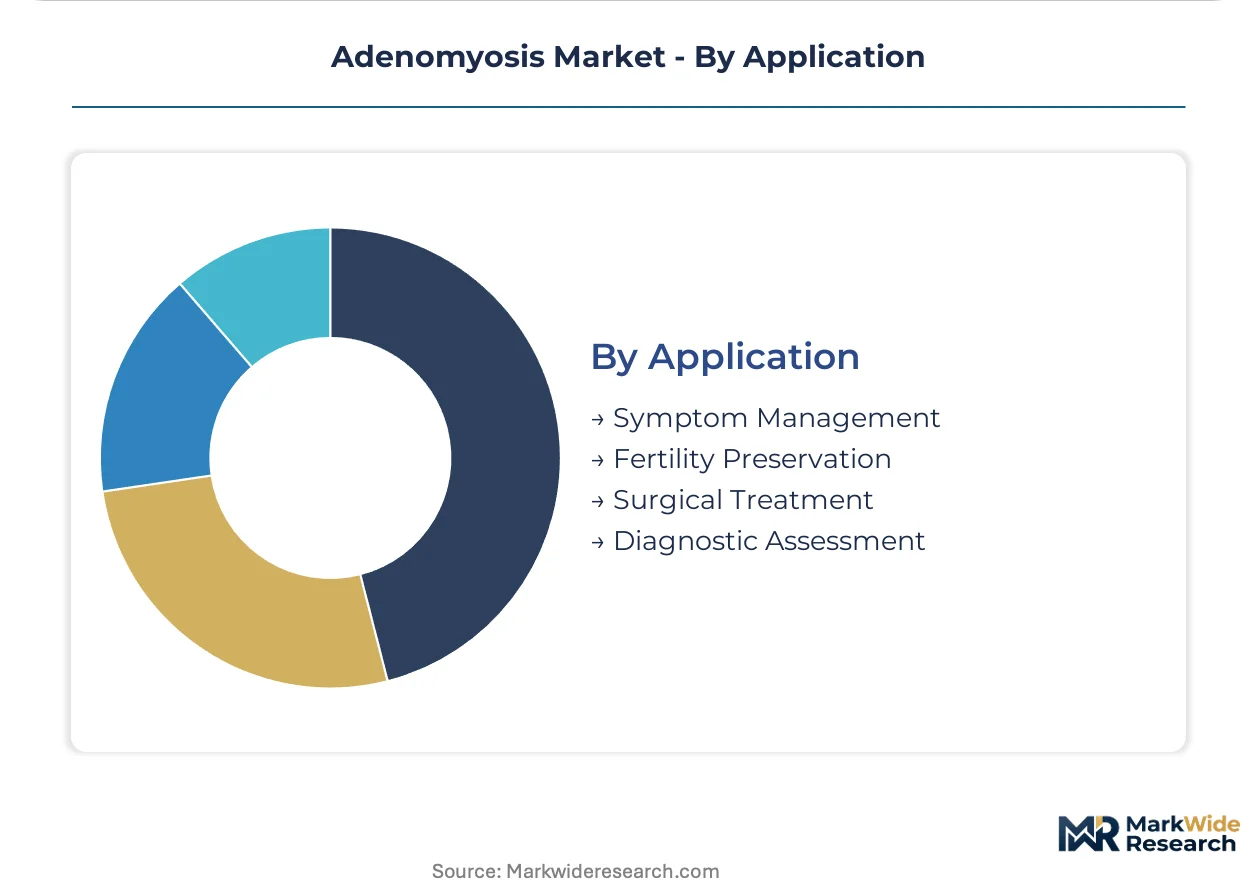
Application:
Customer type segmentation aligns with distinct clinical objectives: symptom control versus fertility preservation versus definitive tissue removal.
- Symptom Management:Pharmacological and non-surgical interventions target dysmenorrhea and menorrhagia reduction while preserving uterine anatomy. United States payers favor this pathway for its lower per-episode cost profile.
- Fertility Preservation:Conservative surgical and targeted medical approaches address adenomyosis in patients pursuing conception.
- Surgical Treatment:Definitive hysterectomy or fertility-sparing excision resolves refractory cases.
- Diagnostic Assessment:Non-invasive imaging confirmation precedes all therapeutic decisions.
Symptom Management represents the volume base. Fertility Preservation is gaining share fastest as delayed childbearing trends intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in hormonal therapies and diagnostic devices shape regional market positions. The United States runs a substantial trade surplus in gynecological pharmaceuticals. Germany and Switzerland anchor European device exports to Asia-Pacific markets.
United States
Integrated delivery networks in Texas and California drive standardized adenomyosis protocols across outpatient clinics. FDA premarket review timelines for fertility-sparing devices now extend to 18-24 months for novel submissions. The Boston-Cambridge corridor concentrates digital health startups developing AI-powered junctional zone measurement tools for community radiology deployment.
Germany
Baden-Württemberg's precision engineering clusters manufacture high-resolution transvaginal ultrasound platforms for export to European and Middle Eastern markets. EMA MDR post-market surveillance obligations create compliance barriers for non-EU device manufacturers seeking German distribution. Munich-based university hospitals lead European adoption of minimally invasive myometrial excision techniques.
Japan
PMDA's streamlined review pathway for diagnostic imaging software accelerates AI-enabled ultrasound classification tools into clinical practice. Tokyo metropolitan hospitals report rising fertility-preservation procedure volumes among women over 35. Osaka-Kobe industrial zones produce specialized laparoscopic instrumentation for domestic gynecological surgery markets.
United Kingdom
NHS England's specialized commissioning frameworks concentrate complex adenomyosis surgeries in London and Manchester tertiary centers. MHRA post-Brexit regulatory autonomy permits faster adoption of CE-marked devices with established European safety profiles. Cambridge medical technology incubators develop wearable menstrual tracking platforms for remote patient monitoring integration.
India
CDSCO's accelerated approval pathway for orphan gynecological indications attracts multinational hormonal therapy licensing deals. Maharashtra's Mumbai-Pune corridor hosts contract manufacturing organizations producing generic GnRH agonists for export to African and Southeast Asian markets. Delhi-NCR specialty clinics report growing demand for fertility-sparing interventions among urban professional women delaying childbirth.
Adenomyosis Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying imaging hardware and pharmaceutical APIs. The adenomyosis treatment landscape fragments across three distinct capability layers: multinational pharmaceutical conglomerates with endocrinology portfolios, medical device manufacturers with gynecological surgery platforms, and diagnostic imaging technology developers. Three archetypes dominate competitive positioning: hormone therapy platform owners leveraging endometriosis infrastructure, surgical device specialists capturing premium intervention economics, and diagnostic AI developers extracting value from imaging workflow automation. Consolidation pressure intensifies through strategic licensing arrangements and royalty-based partnership structures that reduce capital intensity for market entry.
Among diversified pharmaceutical conglomerates, Bayer AG, AbbVie Inc., and Pfizer Inc. occupy positions exemplifying distinct competitive vectors. Bayer AG anchors the hormonal therapy platform archetype through sustained investment in progestin-releasing intrauterine systems and long-acting reversible formulations. AbbVie Inc. represents cross-indication leverage strategy, extending endometriosis-drug infrastructure into adenomyosis protocols without dedicated R&D expenditure. Pfizer Inc. sits within the pain-management extension archetype, repositioning analgesic portfolios toward gynecological indications through indication expansion rather than novel mechanism development.
| Leading Market Players |
|---|
| Bayer AG |
| AbbVie Inc. |
| Pfizer Inc. |
| Merck KGaA |
| Novartis AG |
| Johnson & Johnson Services, Inc. |
| Ferring B.V. |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's precision engineering clusters anchor European ultrasound platform manufacturing, where capacity tightness in high-resolution transvaginal probe production translates directly into pricing leverage for diagnostic device makers serving United States outpatient clinics.
Pricing Analysis
Hospital purchasing committees anchor three-tier pricing structure across premium, standard, and economy levels for hormonal therapy platforms, with FDA certification tier and volume scale driving differentiation. Pricing pressure stems from Medicaid reimbursement compression on fertility-sparing procedures. Community radiology groups exhibit highest price sensitivity due to capital budget constraints.
Supply Chain Analysis
Export-control restrictions on semiconductor components for imaging AI processors limit flows from Taiwan and South Korea into German and Japanese device assembly. Active pharmaceutical ingredient production draws from India and China for GnRH agonist synthesis. Single-source vulnerability concentrates in specialty progestin raw materials. Distribution runs through United States-based GPO contracts and European hospital procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adenomyosis market rewards service-attach strategies where remote patient monitoring subscriptions and adherence program licensing expand faster than capital equipment sales.
For Market Incumbents: Entrench protocol standardization within United States integrated delivery networks before diagnostic AI disrupts imaging workflows. Secure backward integration into junctional zone measurement algorithm development. Invest in CE marking pathways ahead of EMA MDR surveillance escalation. For New Entrants and Emerging Players: Community radiology practices in exurban United States markets represent the most penetrable entry point for ultrasound platform displacement. Direct-to-consumer menstrual health platforms offer channel partnership routes bypassing traditional OB-GYN gatekeepers. Target fertility-benefit employers for bundled diagnostic-therapeutic contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents seeking to divest gynecological device portfolios lacking endocrinology synergy. Five-to-ten year viability hinges on AI diagnostic workflow capture rather than hardware margins. Watch FDA breakthrough device designation velocity as inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Workflow Integration | FDA breakthrough designation accelerates community radiology adoption of automated junctional zone measurement. |
| Hospital System Partnership | United States IDN standardization creates fast-track evaluation for protocol-compatible device platforms. |
| Reimbursement Strategy | Medicaid fertility-sparing procedure coding determines sustainable returns on conservative surgical investment. |
| Software Companion Development | Remote menstrual tracking integration opens pharmaceutical adherence program revenue streams. |
| CE Marking Pathway | EMA MDR post-market surveillance compliance differentiates well-capitalized European device suppliers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with gynecologic surgeons, hospital procurement managers, regulatory affairs specialists, and radiology practice administrators; and secondary validation through FDA 510(k) filings, ClinicalTrials.gov records, CMS Medicare reimbursement databases, and EMA MDR compliance disclosures. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Forecast inputs incorporated treatment line progression, delivery mechanism format, end-user facility type, and regional regulatory cluster across the projection horizon. CAGRs derived from procedure volume elasticity to reimbursement changes and technology substitution curves for imaging modalities. Fertility preservation demand intensity and outpatient clinic capacity expansion served as adenomyosis-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in Medicaid funding levels and employer-sponsored fertility benefit penetration would shift the trajectory. Material shifts in FDA premarket review timelines or EMA MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Quadriplegia Treatment Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market