
 Nanodiamond Market | 2026-2036
Nanodiamond Market Size, Share, and Industry Trends Forecast 2026-2036
Nanodiamond Market Foresight
Biomedical applications is shifting toward nanodiamond-enabled drug delivery platforms and implant surface engineering. Adámas Nanotechnologies leverages its detonation synthesis expertise to anchor North American supply for life science researchers. Carbodeon Ltd. Oy competes through surface-functionalized dispersions that dominate European thermal coating formulations. Daicel Corporation sustains its position in high-purity grades for electronics polishing through captive process controls in Japan.
Nanodiamonds are synthetic diamond particles typically measuring 4–6 nanometers in diameter, produced through detonation of carbon-based explosives or high-pressure high-temperature methods, valued for exceptional hardness, thermal conductivity, and biocompatibility in precision industrial and medical systems. Detonation nanodiamonds occupy the largest production volume tier due to mature Soviet-era process heritage and scalable reactor infrastructure. Chemical vapor deposition grades command premium positioning in optical and quantum sensing applications where crystallinity tolerances tighten. The biomedical application segment leads value generation as surface-functionalized particles enable targeted therapeutic loading with minimal cytotoxicity profiles.
EPA oversees environmental discharge thresholds for detonation synthesis facilities operating in the United States, while REACH registration requirements in Europe constrain import volumes of uncharacterized nanodiamond powders. Japan's METI promotes nanomaterial safety characterization protocols that shape product qualification timelines for Asian suppliers seeking market access. Stakeholders must monitor evolving biocompatibility certification standards across multiple jurisdictions to secure priority positioning in regulated medical device supply chains.
Market Dynamics
Detonation synthesis capacity concentration in former Soviet industrial zones is creating supply bottlenecks as microwave-assisted purification upgrades lag demand expansion from biomedical coating qualification pipelines.
Growth Catalysts
- FDA biocompatibility pathway clarification:Accelerated 510(k) review timelines for nanodiamond-enabled implant surfaces are pulling medical device manufacturers toward active coating development programs.
- Quantum sensing crystallinity standards:Chemical vapor deposition grades meeting ISO 11298 optical tolerances are opening procurement channels for defense and research instrumentation buyers.
- German precision polishing clusters:Concentrated demand from automotive powertrain component manufacturers is anchoring European volume commitments for thermal management formulations.
Market Restraints
- Feedstock cost volatility:Explosive-grade carbon precursor prices fluctuate with defense sector procurement cycles, compressing detonation synthesis margins during raw material spikes.
- Supplier geographic concentration:Legacy reactor infrastructure in Belarus and Russia exposes buyers to trade sanction friction and logistics disruption.
- High-purity grade yield limits:Current purification protocols cap electronics-grade output at sub-commercial volumes, constraining optical and quantum application scaling.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO accelerated approval pathways for nanodiamond drug delivery platforms position domestic formulation houses for export qualification.
- Carbon capture convergence:Integration of detonation synthesis with industrial CO2 feedstock streams is unifying waste valorization with nanomaterial production economics.
- Direct-to-researcher distribution:Surface-functionalized dispersion kits bypassing traditional chemical distributor markups are capturing life science laboratory procurement budgets.
Industry Challenges
- Surface chemistry expertise scarcity:Functionalization protocol development requires rare combinations of diamond materials science and bioconjugation chemistry training.
- Multi-jurisdiction certification timelines:Parallel REACH registration, EPA discharge permitting, and PMDA safety characterization create 18-24 month market access delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanodiamond Market |
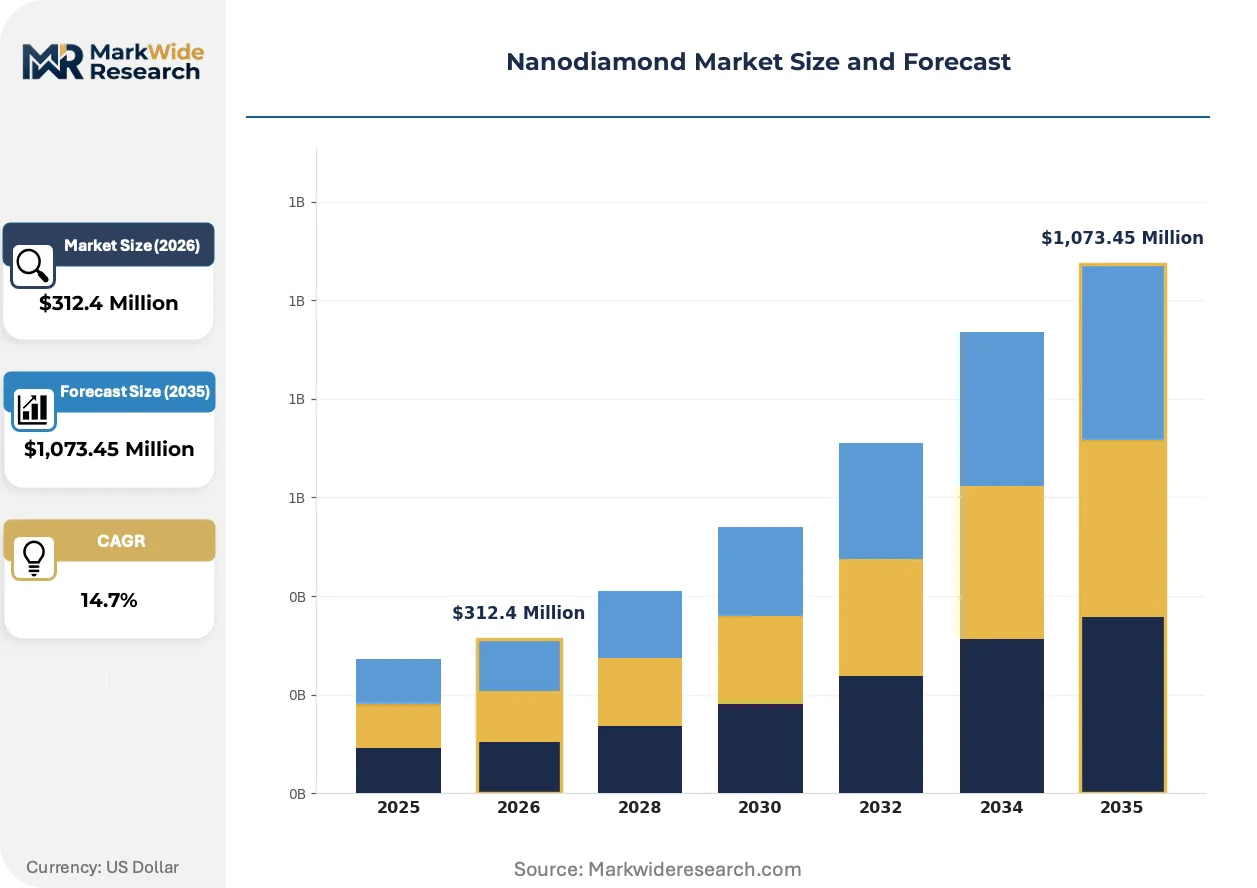
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,073.45 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure High-Temperature, Detonation Nanodiamonds, Chemical Vapor Deposition, Others Application: Biomedical, Electronics, Optical Devices, Coatings End User: Healthcare, Aerospace, Manufacturing, Defense Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Adámas Nanotechnologies, Sinta, Carbodeon Ltd. Oy, Kerridge Commercial Systems Limited, FND Biotech, Daicel Corporation, Sino-Crystal Micro-Diamond, Columbus NanoWorks Inc, Ray Techniques Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanodiamond Market Shifts & Advancements
Microwave-assisted purification breakthroughs are compressing process economics while regulatory clarity across three major jurisdictions is standardizing qualification protocols for medical-grade supply chains.
Fluorinated surface functionalization chemistry is unifying hydrophobic drug loading capacity with aqueous dispersion stability. Cardiovascular stent manufacturers in Germany and Japan are adopting these grades at pilot scale ahead of full production qualification. This unification is collapsing the traditional trade-off between therapeutic payload retention and manufacturing handleability that previously segmented the biomedical supply base.
REACH registration requirements for uncharacterized nanodiamond powders are tightening import documentation standards across European customs checkpoints. ECHA substance evaluation protocols now mandate specific surface area and zeta potential reporting that many legacy suppliers cannot satisfy. Medical device compounders in France and Switzerland are responding by qualifying pre-registered dispersion intermediates rather than raw powders.
Specification-driven purchasing contracts are displacing spot-market procurement for electronics polishing applications. Japanese semiconductor equipment manufacturers now require locked purity certifications across 24-month supply agreements, forcing traders to hold certified inventory. This compression is most visible in Tokyo-Osaka industrial corridors where captive supply relationships are replacing open-market transactions.
Nanodiamond Market Segmentation
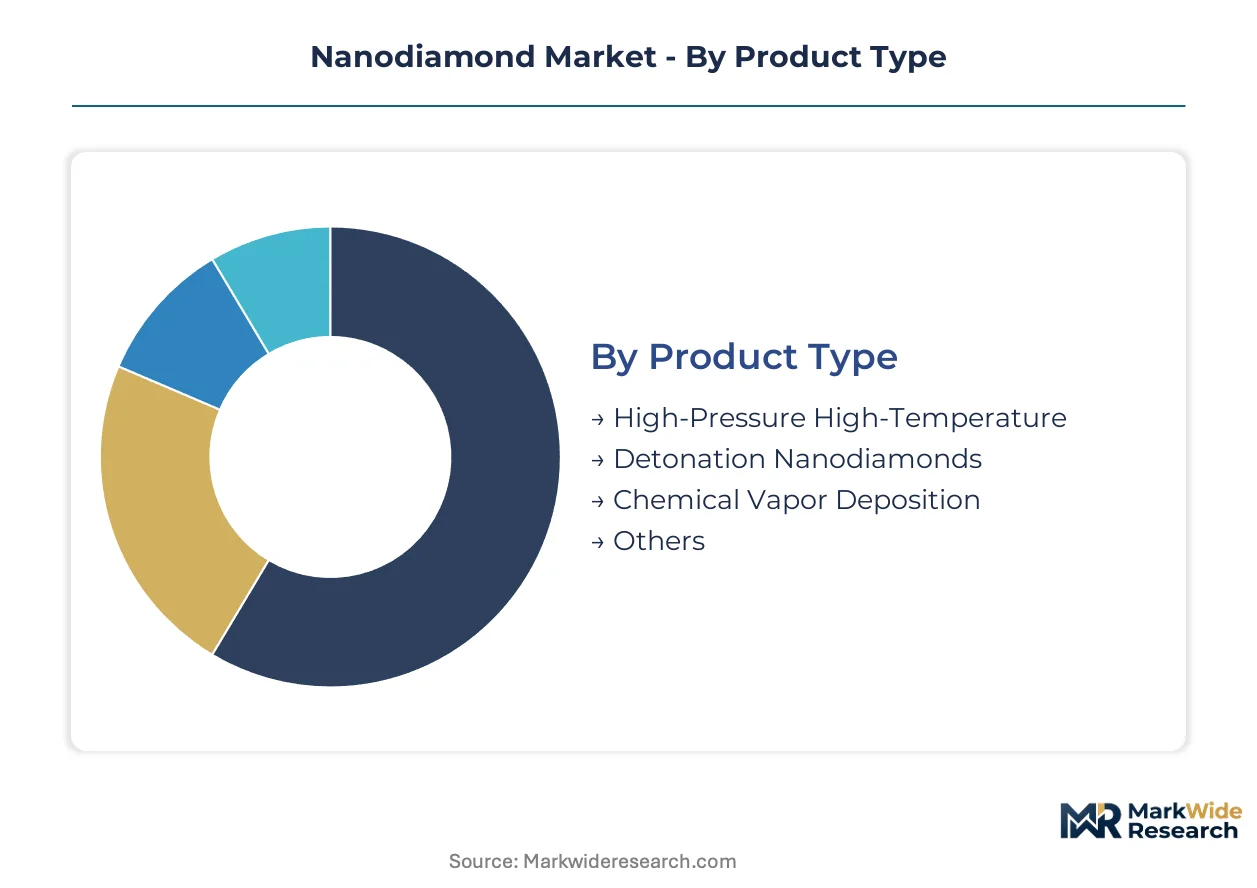
Nanodiamond procurement patterns diverge sharply across synthesis routes and functionalization requirements. Medical device qualification timelines and electronics purity thresholds create distinct purchasing behaviors that suppliers must navigate simultaneously.
Product Type:
Customization intensity spans from commodity detonation output to precision-tuned CVD crystallinity, with cost structures and lead times diverging by an order of magnitude across this spectrum.
- Detonation Nanodiamonds:Produced through controlled explosive detonation of carbon-based charges, yielding 4–6 nanometer primary particles with inherent surface functional groups. Demand concentrates in German automotive powertrain polishing and Japanese thermal coating formulations where microwave-assisted purification upgrades are compressing unit economics.
- Chemical Vapor Deposition:Gas-phase synthesis delivering superior crystallinity and optical transparency for quantum sensing and precision optics. Japanese semiconductor equipment manufacturers and German research instrumentation buyers lock in 24-month supply agreements with locked purity certifications.
- High-Pressure High-Temperature:Diamond anvil and press methods generating larger crystallites for abrasive super-finishing applications.
- Others:Emerging plasma synthesis and laser ablation routes still at pilot scale for specialty optical grades.
Most installed capacity flows through Detonation Nanodiamonds. Expansion is steepest in Chemical Vapor Deposition.
Application:
End-use value capture ranges from high-volume industrial abrasives to premium biomedical platforms where surface engineering commands pricing multiples.
- Biomedical:Surface-functionalized particles enabling targeted drug delivery, implant coatings, and diagnostic platforms. FDA 510(k) pathway clarification is pulling medical device manufacturers toward active coating development programs in the United States.
- Electronics:Ultra-high purity grades for chemical-mechanical planarization and thermal interface materials. Japanese semiconductor fabrication clusters anchor procurement volume with specification-driven purchasing contracts displacing spot-market transactions.
- Coatings:Thermal management and wear-resistant formulations for automotive and aerospace components.
- Optical Devices:Quantum sensing, laser optics, and photonic applications requiring tight crystallinity tolerances.
Revenue concentration tilts toward Biomedical. Volume scaling runs fastest in Electronics.
End User:
Procurement sophistication varies from research laboratory spot-buying to defense contractor multi-year qualification programs.
- Healthcare:Pharmaceutical formulation houses and medical device manufacturers driving surface-functionalized dispersion demand. CDSCO accelerated approval pathways in India are positioning domestic houses for export qualification.
- Manufacturing:Precision polishing and thermal management applications concentrated in German automotive supply chains and Japanese electronics corridors.
- Aerospace:Thermal coating and lightweight composite applications with extended qualification timelines.
- Defense:Quantum sensing and secure communications applications with restricted supply chain requirements.
Contract value peaks in Healthcare. Procurement velocity runs highest in Manufacturing.
Distribution Channel:
Channel selection tracks customer technical capability and volume scale, with direct relationships dominating qualified supply chains.
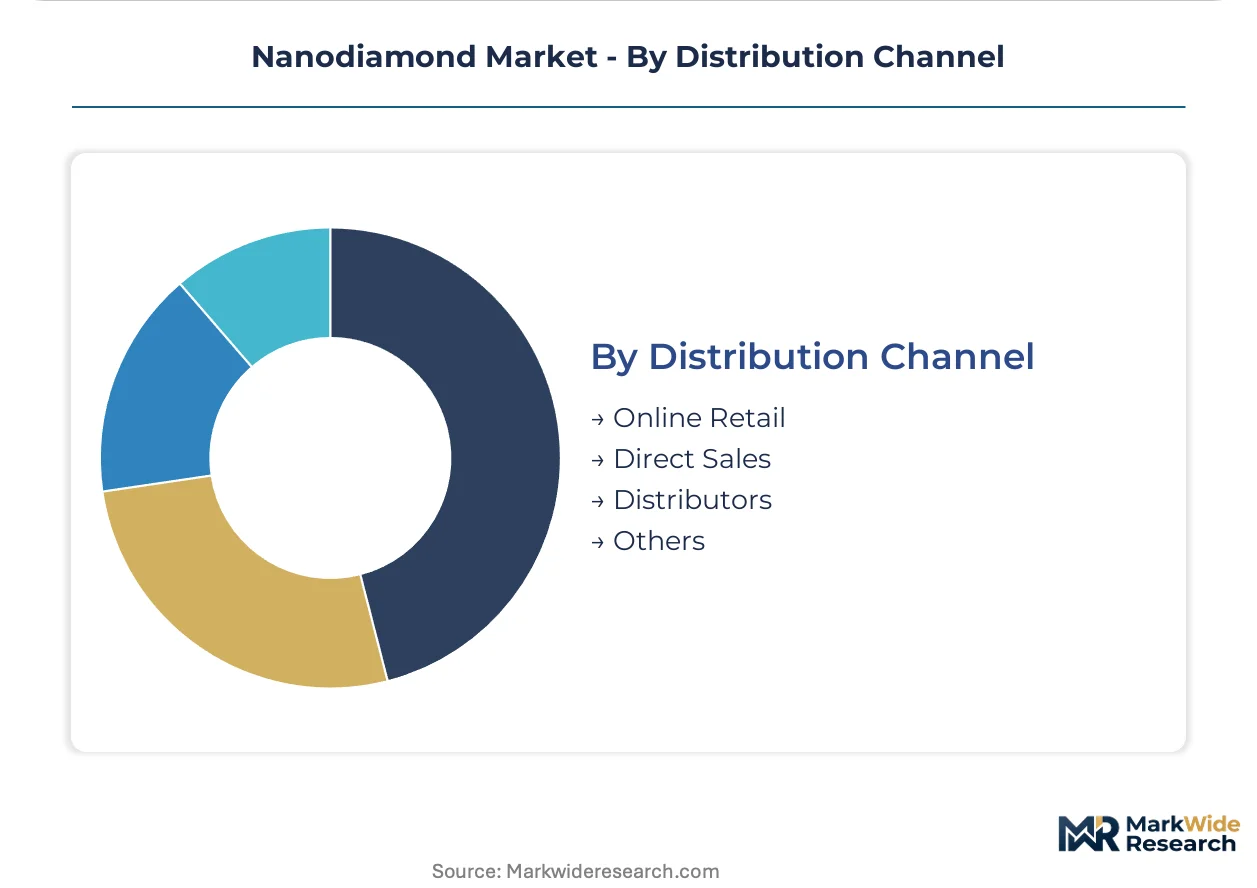
- Direct Sales:Captive technical service relationships for biomedical and electronics qualification programs. Surface-functionalized dispersion kits bypassing traditional chemical distributor markups are capturing life science laboratory procurement budgets.
- Distributors:Regional chemical and materials distributors holding certified inventory for spot-buying manufacturing customers.
- Online Retail:Research-grade dispersions and small-volume functionalized kits for academic laboratories.
- Others:Consortium purchasing and government procurement frameworks for defense and research instrumentation.
Transaction volume flows predominantly through Direct Sales. Channel experimentation is most active in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are shifting nanodiamond production toward jurisdictions with streamlined nanomaterial safety protocols, as REACH registration costs and EPA discharge permitting create compliance gaps between European, American, and Asian manufacturing bases.
United States
FDA 510(k) pathway clarification for implant coatings is accelerating medical device manufacturer procurement from domestic dispersion suppliers. EPA discharge thresholds constrain detonation synthesis facility expansion in industrial zones. Boston and Minneapolis medical technology clusters are qualifying surface-functionalized grades for cardiovascular stent pilot programs.
Germany
Automotive powertrain polishing demand from Stuttgart and Munich manufacturing corridors anchors European volume commitments. REACH registration requirements for uncharacterized powders tighten import documentation at Frankfurt and Hamburg customs checkpoints. ECHA substance evaluation protocols now mandate specific surface area reporting that pre-registered dispersion intermediates satisfy.
Japan
METI nanomaterial safety characterization protocols shape product qualification timelines for Asian suppliers seeking market access. Semiconductor equipment manufacturers in Tokyo-Osaka corridors require locked purity certifications across 24-month supply agreements. PMDA biocompatibility standards for implant coatings are converging with FDA pathways to streamline dual-market approval.
India
CDSCO accelerated approval pathways for drug delivery platforms position domestic pharmaceutical formulation houses for export qualification. Hyderabad and Mumbai manufacturing clusters are integrating nanodiamond-enabled therapeutic loading into generic active pharmaceutical ingredient production. BIS nanomaterial standards are aligning with ISO protocols to reduce technical barriers to trade.
Belarus
Legacy Soviet-era detonation reactor infrastructure concentrates feedstock conversion capacity in Mogilev industrial zones. Trade sanction friction and logistics disruption expose buyers to supply volatility. Microwave-assisted purification upgrades lag demand expansion from biomedical coating qualification pipelines in Western European markets.
Nanodiamond Market Competitive Landscape
Capacity expansion dominates the current landscape as established synthesis houses upgrade purification infrastructure to capture biomedical qualification volumes. The vendor base stratifies across three tiers: integrated detonation producers with captive reactor networks, surface-functionalization specialists commanding dispersion premiums, and regional trading houses holding certified inventory for spot manufacturing demand. Strategic archetypes include synthesis-originated players backward integrating into functionalization chemistry, and application-focused formulators outsourcing primary particle production. Geographic expansion and technology licensing represent the dominant competitive moves, as European and Japanese buyers seek supply chain redundancy outside former Soviet production zones.
Among synthesis-originated specialists, Adámas Nanotechnologies and Daicel Corporation exemplify the integrated archetype combining detonation capacity with captive purification controls. Carbodeon Ltd. Oy occupies a position within the European functionalization tier, representing surface-engineering specialists that transform commodity powders into qualified dispersion intermediates. These three anchors illustrate the competitive divergence between volume-driven primary production and value-capturing surface chemistry expertise.
| Leading Market Players |
|---|
| Adámas Nanotechnologies |
| Sinta |
| Carbodeon Ltd. Oy |
| Kerridge Commercial Systems Limited |
| FND Biotech |
| Daicel Corporation |
| Sino-Crystal Micro-Diamond |
| Columbus NanoWorks Inc |
| Ray Techniques Ltd |
| Others |
Supply & Pricing Matrix
Medical device manufacturers in Boston and Minneapolis clusters anchor pricing power through multi-year qualification contracts that lock in surface-functionalized dispersion premiums. This buyer concentration favors contract-based offtake structures over spot-market transactions, compressing margin flexibility for traders serving spot-buying polishing customers.
Pricing Analysis
Distributor markups of 15-25 percentage points separate research-grade kit pricing from direct OEM procurement for biomedical qualification programs. Three-tier pricing structure across medical-grade, electronics-grade, and industrial-grade levels tracks certification investment and purity thresholds. Pricing pressure stems from feedstock cost volatility in explosive-grade carbon precursors tied to defense procurement cycles. Academic laboratories exhibit highest price sensitivity, while Japanese semiconductor equipment manufacturers absorb premiums for locked purity certifications.
Supply Chain Analysis
Freight cost surcharges of 8-12 percentage points apply to detonation nanodiamond shipments from Belarus through Baltic ports subject to sanction screening delays. Primary production concentrates in Belarus, Russia, and Japan, with purification capacity expanding in Germany and the United States. Feedstock dependencies include explosive-grade carbon precursors, high-purity hydrogen for CVD processes, and fluorinated reagents for surface functionalization. Single-source vulnerability runs through legacy Soviet-era reactor infrastructure in Mogilev industrial zones. Distribution runs through direct technical service relationships for qualified biomedical and electronics supply chains, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanodiamond market has entered a late-cycle quality phase where biomedical implant coating specifications are displacing commodity polishing grades as the primary value capture mechanism. FDA 510(k) pathway clarification and converging PMDA standards are consolidating procurement around pre-qualified dispersion suppliers.
For Market Incumbents: Extend surface-functionalization chemistry capabilities to capture cardiovascular stent coating qualification volumes ahead of generic competition. Backward integration into captive microwave-assisted purification infrastructure defends margin position against feedstock volatility. Lock in 24-month supply agreements with Japanese semiconductor equipment manufacturers to replace spot-market exposure with contracted revenue visibility. For New Entrants and Emerging Players: CDSCO accelerated approval pathways in India open a window for domestic pharmaceutical formulation houses to capture export qualification for nanodiamond drug delivery platforms. Target direct-to-researcher dispersion kit distribution to bypass entrenched chemical distributor markups in European life science clusters. Lead with fluorinated surface chemistry expertise to differentiate from commodity detonation powder traders. For Investors and Strategic Acquirers: Medical device compounders are the most active acquirer in this space, seeking surface-engineering capabilities to internalize coating development. Five-to-ten year viability hinges on biocompatibility certification depth rather than synthesis scale. Target acquisition archetype: regional functionalization specialists with pre-registered REACH dispersion intermediates. Watch for EPA discharge permitting decisions in U.S. industrial zones as inflection signal for domestic detonation capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purification Infrastructure | Captive microwave-assisted processing captures biomedical margin premiums in Germany and Japan. |
| REACH Pre-Registration of Dispersion Intermediates | ECHA compliance documentation satisfies Frankfurt and Hamburg customs checkpoint requirements. |
| Dual FDA-PMDA Biocompatibility Qualification | Converging regulatory standards streamline cardiovascular stent coating approval timelines. |
| Direct-to-Researcher Distribution Launch | Surface-functionalized kits bypass distributor markups to capture academic laboratory budgets. |
| Carbon Capture Feedstock Integration | Industrial CO2 streams unify waste valorization with nanodiamond production economics. |
Research Methodology
Direct dialogue with nanodiamond synthesis plant managers, biomedical R&D directors at medical device manufacturers, pharmaceutical formulation scientists, and semiconductor equipment procurement leads grounded qualitative assessment. Secondary validation drew from EPA discharge permit filings, ECHA REACH registration databases, FDA 510(k) submission records, and METI nanomaterial safety protocols. Bottom-up and top-down triangulation cross-checked capacity expansion announcements against end-use demand qualification timelines.
Bottom-up modeling aggregated synthesis route capacity, purification yield assumptions, and end-use qualification penetration rates across the projection horizon. Segmentation dimensions spanned product type, application, functionalization chemistry, and regional regulatory cluster. CAGRs derived from volume-weighted average of segment growth trajectories calibrated to biomedical coating pipeline visibility. Forecast inputs included FDA review timeline acceleration metrics and Japanese semiconductor equipment capex cycles.
Revisions become necessary when trade sanction regimes expand to restrict Belarusian reactor output, when EPA discharge thresholds tighten for U.S. detonation facilities, or when quantum sensing crystallinity standards shift to exclude current CVD grades. Stakeholders should weight assumptions against their own operating context and certification investment horizons.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Global Nano Batteries Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
3D Xpoint Technology Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market