
 Ultra-Fine Ath Market | 2026-2036
Ultra-Fine Ath Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-Fine Ath Market Analysis
Pharmaceutical formulation demand is rebalancing toward high-purity ultra-fine aluminum trihydroxide grades as oral solid dosage manufacturers tighten particle-size specifications. Albemarle Corporation leverages its bromine-specialty backbone to sustain captive ATH feedstock quality across flame-retardant and pharma-adjacent lines. Huber Engineered Materials anchors North American supply through controlled precipitation infrastructure. Nabaltec AG competes on fine-particle consistency for European cable-compound buyers.
Ultra-fine aluminum trihydroxide consists of precipitated ATH with median particle diameters below one micron, engineered through controlled precipitation or aqueous processing to deliver high surface area, low iron content, and tailored morphology for flame retardancy, pharmaceutical excipient function, or cosmetic opacity. Powders dominate current volume owing to established handling infrastructure and compounder familiarity, while nanotechnology-enabled dispersions capture expanding margin pools in transparent cosmetic and high-voltage cable applications where agglomeration control determines performance. Spray drying is maturing as a scale pathway for spherical, free-flowing grades that reduce dust exposure and improve dosing precision.
FDA excipient guidance and REACH registration requirements for nanoforms shape product development priorities and market access conditions for imported grades. EMA quality guidelines for aluminum-containing APIs further tighten purity thresholds, pushing manufacturers toward GMP-certified micronization and validated aqueous processing. Stakeholders must monitor evolving nanomaterial classification debates in Brussels and Washington, as reclassification would trigger additional toxicity testing burdens and reshape competitive positioning between regional suppliers and Asian exporters.
Market Dynamics
Pharmaceutical-grade purity requirements are compressing supplier margins while concentrating volume among GMP-certified micronizers, forcing asset-light traders toward technical service partnerships or exit.
Growth Catalysts
- REACH nanoform registration:ECHA's evolving nanoform guidance is accelerating documented safety dossiers for sub-micron ATH, opening formulated access to European cable and cosmetic compounders.
- Flame-retardant polymer demand:EV battery enclosure specifications are pulling high-surface-area ATH into thermally stable engineering resin systems.
- Leverkusen-Ludwigshafen cluster:Germany's specialty chemical corridor concentrates aqueous precipitation expertise, reducing logistics friction for just-in-time pharmaceutical excipient supply.
Market Restraints
- Sodium aluminate feedstock volatility:Bayer process input costs fluctuate with alumina refinery operating rates, squeezing precipitated ATH margin predictability.
- Single-source micronization risk:Jet milling capacity for sub-0.5-micron grades concentrates among three German and Japanese equipment operators.
- Magnesium hydroxide substitution:Lower decomposition temperature and smoke suppression performance displace ATH in select polyolefin cable applications.
Strategic Opportunities
- Indian pharmaceutical formulation:CDSCO's tightening excipient quality guidelines create first-mover advantage for GMP-certified ATH suppliers establishing local technical service presence.
- Transparent cosmetic dispersions:Nanotechnology-enabled aqueous suspensions with controlled agglomeration unlock premium positioning in sun care and color cosmetics.
- IRA domestic content incentives:US wire and cable compounders face sourcing pressure for North American-manufactured flame retardants serving federally funded infrastructure projects.
Industry Challenges
- Particle-size metrology standardization:Laser diffraction versus sedimentation method disputes between compounders and suppliers delay batch release timelines.
- Cross-contamination protocols:Pharmaceutical-grade lines require dedicated jet milling infrastructure, doubling capital intensity per ton of certified capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-Fine Ath Market |
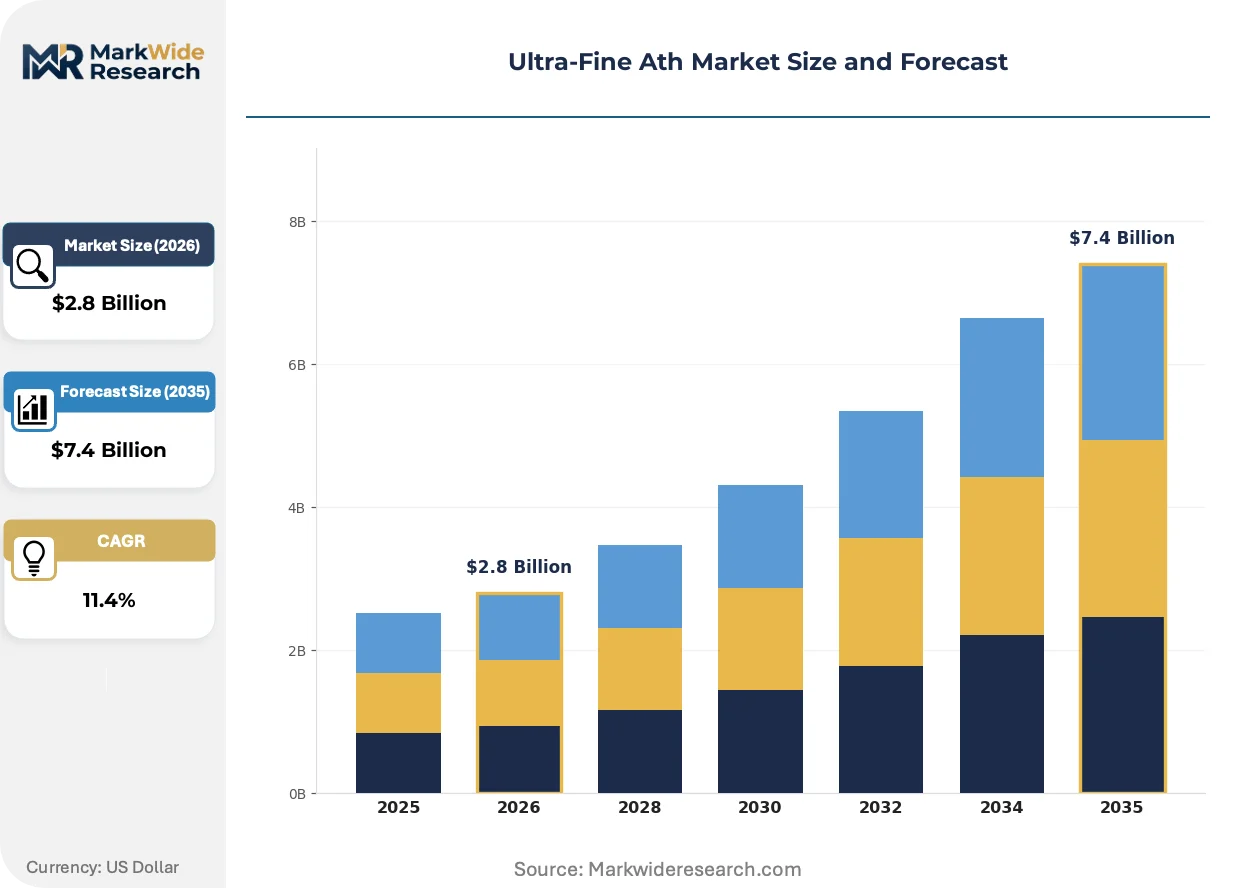
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powders, Suspensions, Dispersions, Coatings Application: Cosmetics, Pharmaceuticals, Food Additives, Agriculture End User: Manufacturers, Researchers, Distributors, Retailers Technology: Nanotechnology, Micronization, Aqueous Processing, Spray Drying |
| Companies Covered | Albemarle Corporation, Almatis, Huber Engineered Materials, J.M. Huber Corporation, Nabaltec AG, Nippon Light Metal Holdings, Showa Denko, Evonik Industries, Zibo Pengfeng New Material Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-Fine Ath Market Emerging Trajectories
Spray-dried spherical morphology is displacing conventional ground powders in high-throughput compounding operations, while regulatory nanoform classifications force simultaneous reformulation and dossier investment across multiple jurisdictions.
Controlled precipitation with in-line laser diffraction feedback is consolidating quality consistency for sub-micron median diameters. Pharmaceutical excipient manufacturers in Germany and Switzerland are adopting these closed-loop systems to reduce batch-to-batch particle distribution variance. The technology is consolidating specification-setting power among integrated producers who own both precipitation and real-time metrology capabilities.
EMA quality guidelines for aluminum-containing APIs are tightening elemental impurity thresholds for iron and heavy metals. Compounders serving European oral solid dosage markets must now validate aqueous processing steps against ICH Q3D elemental impurity limits. High-purity grade manufacturers with documented GMP micronization are capturing specification-driven volume from commodity ATH traders.
Formulators are unbundling technical service from material supply, demanding application-specific dispersion testing and regulatory dossier support as separate procurement line items. European cable compounders now contract standalone formulation advisory before committing to volume supply agreements. This behavior is most visible in Germany's specialty chemical corridor, where compounders maintain multiple qualified ATH sources but consolidate technical service relationships with single preferred suppliers.
Ultra-Fine Ath Market Segmentation
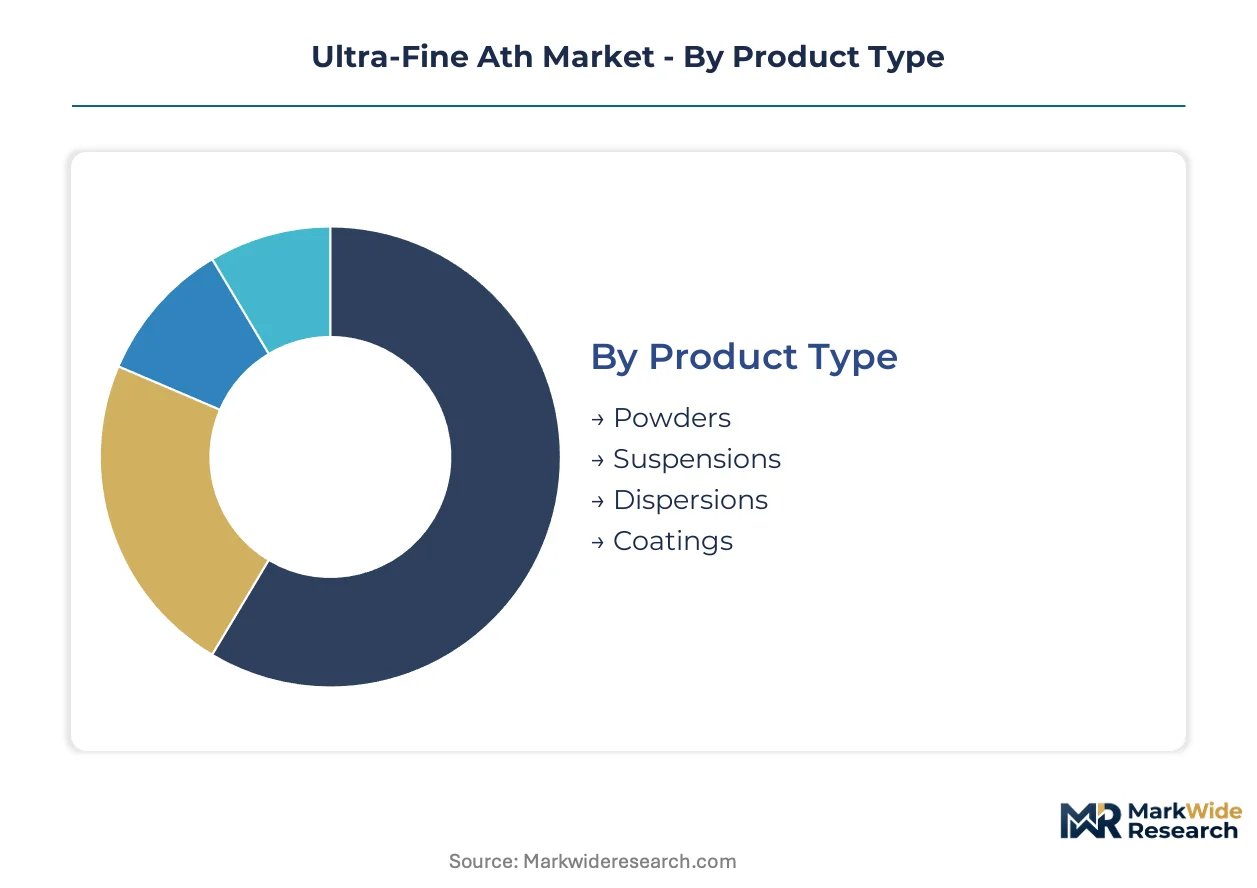
Ultra-fine ATH buyers face distinct trade-offs across particle morphology, regulatory compliance burden, and supply chain integration depth. Segmentation reveals where specification premiums concentrate and which processing technologies command pricing power.
Product Type:
Replacement cycles vary sharply by physical form, with powder users seeking handling efficiency upgrades while dispersion buyers pursue transparency performance thresholds.
- Powders:Precipitated ATH with median diameters below one micron delivers established flame-retardant performance in polymer compounding. Demand concentrates in German cable compounders serving EV battery enclosure specifications, where dust exposure concerns and dosing precision requirements are accelerating spray-dried spherical grade adoption.
- Suspensions:Aqueous ATH slurries with controlled solids loading eliminate dry powder handling hazards in high-throughput pharmaceutical manufacturing. CDSCO's tightening excipient guidelines in India are pulling GMP-certified suspension supply toward local technical service partnerships.
- Dispersions:Nanotechnology-enabled systems with deagglomerated primary particles enable transparent cosmetic applications.
- Coatings:Surface-modified ATH layers for functionalized filler applications in specialty polymer systems.
Powders sit at the top of the volume ranking, with suspensions climbing the fastest.
Application:
Margin structures diverge by end-use regulatory intensity, with pharmaceutical and cosmetic grades capturing specification premiums against commodity flame-retardant applications.
- Cosmetics:High-purity ATH functions as opacity agent and skin-feel modifier in sun care and color formulations. REACH nanoform registration requirements are reshaping supplier qualification criteria for European cosmetic compounders.
- Pharmaceuticals:Oral solid dosage excipient applications demand ICH Q3D-compliant elemental impurity profiles and validated aqueous processing. EMA quality guidelines for aluminum-containing APIs are compressing qualified supplier lists toward GMP-certified micronizers in Germany and Switzerland.
- Food Additives:Food-grade ATH serves as anticaking agent and pH buffer in processed food manufacturing.
- Agriculture:Micronized ATH applications in fertilizer coating and soil amendment formulations.
Pharmaceuticals command the steepest specification premiums, while cosmetics shows the most rapid formulation innovation cycle.
End User:
Procurement sophistication tiers separate integrated manufacturers from intermediaries, with direct buyers investing in application-specific validation capabilities.
- Manufacturers:Integrated polymer compounders and pharmaceutical formulators with in-house particle-size metrology and regulatory dossier management. IRA domestic content incentives are redirecting US wire and cable manufacturer sourcing toward North American-produced flame-retardant grades.
- Researchers:Academic and contract research organizations developing novel ATH applications in battery thermal management and drug delivery.
- Distributors:Technical service intermediaries unbundling formulation advisory from material supply in European markets.
- Retailers:Direct-to-consumer channels for cosmetic and specialty chemical applications.
Manufacturers dominate volume procurement, with researchers expanding most quickly as nanomaterial application development accelerates.
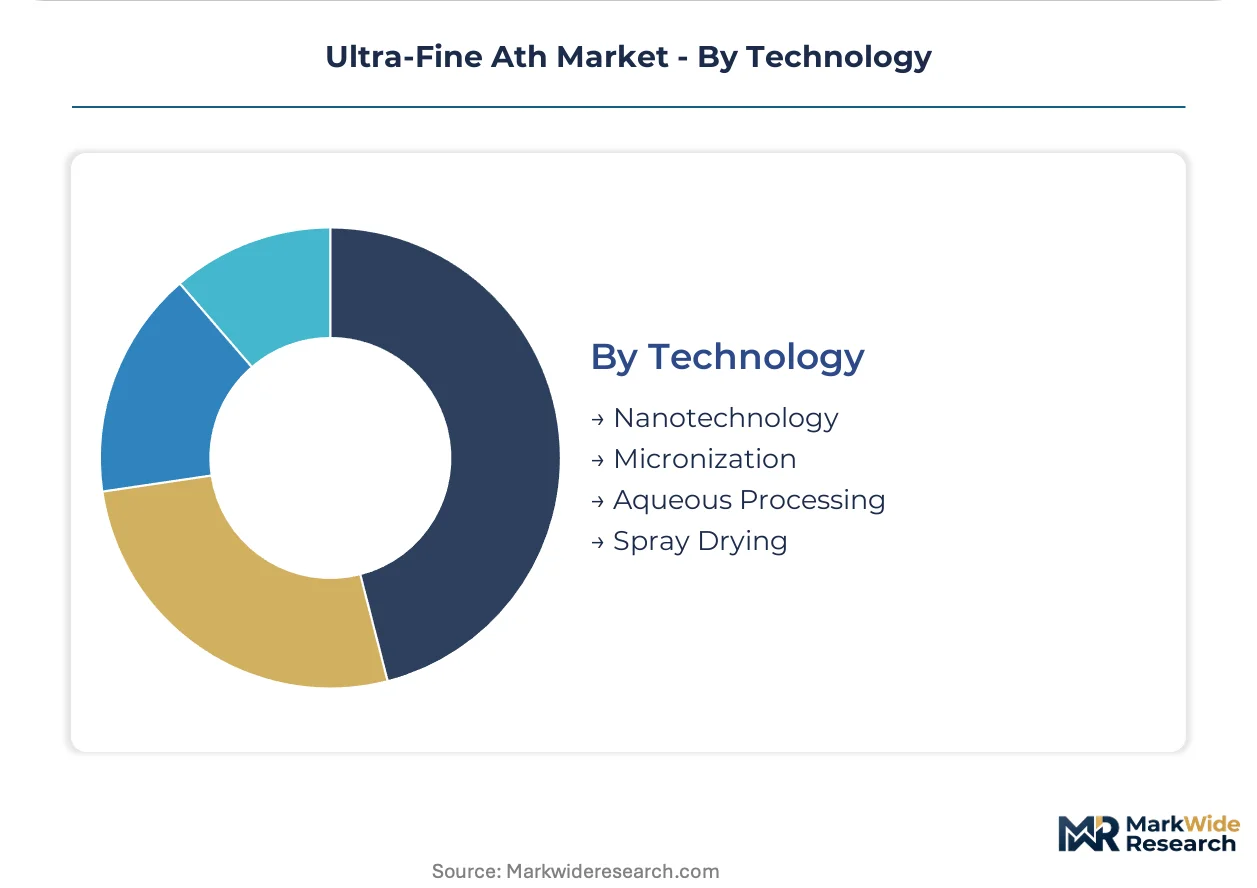
Technology:
Process control capabilities determine batch-to-batch consistency and regulatory documentation depth, with real-time metrology integration separating premium from commodity supply.
- Nanotechnology:Sub-100nm particle engineering with surface functionalization for transparent dispersion and targeted delivery applications. ECHA nanoform guidance is accelerating documented safety dossier investment.
- Micronization:Jet milling and mechanical grinding for sub-micron median diameters with narrow particle distribution. Capacity concentrates among German and Japanese equipment operators, creating single-source risk for sub-0.5-micron grades.
- Aqueous Processing:Controlled precipitation with in-line laser diffraction feedback for pharmaceutical-grade consistency.
- Spray Drying:Spherical morphology production for dust-reduced handling and improved flow properties in high-throughput compounding.
Micronization retains the largest installed base, while spray drying gains share fastest as handling efficiency priorities reshape compounder specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping ultra-fine ATH production geography as manufacturers migrate toward jurisdictions with harmonized nanoform guidance and lower cost-of-compliance structures. ECHA's REACH implementation in Europe and CDSCO's evolving excipient standards in India are creating divergent compliance burdens that advantage integrated producers with multi-site certification capabilities.
Germany
Pharmaceutical-grade ultra-fine ATH demand concentrates in the Leverkusen-Ludwigshafen specialty chemical corridor. EMA quality guidelines for aluminum-containing APIs enforce ICH Q3D elemental impurity thresholds. Jet milling capacity for sub-0.5-micron grades clusters around Ludwigshafen, where aqueous precipitation expertise supports just-in-time excipient supply.
United States
Flame-retardant polymer compounding for EV battery enclosures drives high-surface-area ATH consumption. IRA domestic content incentives redirect wire and cable manufacturer sourcing toward North American-produced grades. Huber Engineered Materials anchors supply through controlled precipitation infrastructure in the Southeast.
India
CDSCO's tightening excipient quality guidelines are pulling GMP-certified ATH supply toward local technical service partnerships. Pharmaceutical formulation growth in Maharashtra and Gujarat creates first-mover opportunities for certified suppliers. Mumbai-Pune corridor concentrates micronization demand from generic drug manufacturers.
Japan
Jet milling equipment operators in Osaka and Nagoya control critical capacity for sub-0.5-micron pharmaceutical grades. METI industrial standards for nanomaterial handling shape processing investment decisions. Kansai region expertise in mechanical micronization supports regional supply security.
China
Zibo and Shandong Province concentrate precipitated ATH production for flame-retardant polymer applications. GB standards for nanoform classification are converging with OECD guidelines, reducing export documentation friction. Yangtze River Delta demand from cable compounders is pulling higher-purity grades into domestic formulation.
Ultra-Fine Ath Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated producers scale aqueous precipitation and spray-drying infrastructure to capture pharmaceutical-grade premiums. The vendor base separates into three tiers: multinational specialty chemical conglomerates with captive bromine-ATH integration, regional precipitation specialists serving cable and cosmetic compounders, and asset-light traders retreating toward technical service partnerships. Strategic archetypes include GMP-certified micronizers, spray-dried morphology innovators, and nanoform dossier specialists. M&A activity and backward integration into sodium aluminate feedstock represent the dominant competitive moves.
Among North American-based integrated producers, Albemarle Corporation and Huber Engineered Materials exemplify the captive feedstock archetype, leveraging bromine-specialty and controlled precipitation backbones respectively. Nabaltec AG represents the European fine-particle consistency model, while Zibo Pengfeng New Material Technology occupies a position within the Chinese regional specialist tier.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Almatis |
| Huber Engineered Materials |
| J.M. Huber Corporation |
| Nabaltec AG |
| Nippon Light Metal Holdings |
| Showa Denko |
| Evonik Industries |
| Zibo Pengfeng New Material Technology |
| Others |
Supply Flow & Price Mechanics
Sodium aluminate feedstock costs cascade through three distinct pricing tiers as Bayer process alumina refinery operating rates fluctuate, compressing margins for precipitated ATH producers while concentrating premium realization power among GMP-certified micronizers serving pharmaceutical excipient markets.
Pricing Analysis
Distributor margins for technical-grade powders compress under magnesium hydroxide substitution pressure in European cable applications, while direct-to-manufacturer contracts for pharmaceutical-grade suspensions sustain specification premiums through ICH Q3D compliance documentation. Three-tier pricing structure across pharmaceutical, cosmetic, and flame-retardant grades separates GMP-certified supply from commodity precipitated volumes, with spray-dried spherical morphology commanding handling-efficiency premiums. Cost compression in technical-grade lines is intensifying because compounders unbundle formulation advisory from material supply. Generic drug manufacturers in India exhibit highest price sensitivity, while Swiss and German oral solid dosage formulators prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for sub-0.5-micron pharmaceutical grades force compounders to qualify both German and Japanese jet milling operators, mitigating single-source concentration risk. Supply concentrates in Germany's Leverkusen-Ludwigshafen corridor, Japan's Osaka-Nagoya equipment cluster, and China's Shandong Province precipitation centers. Production draws from sodium aluminate feedstock, specialized jet milling infrastructure, and aqueous precipitation capacity. Tariff exposure on REACH-registered nanoform imports from Asia threatens European cosmetic compounder cost structures. Distribution runs through integrated specialty chemical distributors unbundling technical service from material supply in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA quality guidelines for aluminum-containing APIs enforce ICH Q3D elemental impurity thresholds, concentrating demand among validated aqueous processors.
For Market Incumbents: Deploy backward integration into sodium aluminate feedstock to defend margin predictability against Bayer process cost volatility. Secure dedicated jet milling lines for pharmaceutical-grade production to eliminate cross-contamination risk and sustain GMP certification premiums against commodity traders. Capacity expansion in India's Maharashtra-Gujarat corridor captures CDSCO guideline tightening before local technical service partnerships consolidate. For New Entrants and Emerging Players: Spray-dried spherical morphology with in-line laser diffraction feedback offers entry into dust-sensitive high-throughput compounding segments underserved by conventional ground powder suppliers. Target transparent cosmetic dispersion applications where REACH nanoform registration barriers filter out commodity Asian exporters. Establish standalone formulation advisory capabilities to unbundle technical service from material supply per European procurement patterns. For Investors and Strategic Acquirers: Consolidation pressure builds where jet milling capacity for sub-0.5-micron grades concentrates among three German and Japanese equipment operators, creating acquisition scarcity value. Long-term viability favors integrated producers with multi-site GMP certification spanning aqueous precipitation and real-time metrology. Monitor ECHA nanoform classification debates as inflection signal; reclassification would trigger toxicity testing burdens reshaping competitive positioning between regional suppliers and Asian exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Aluminate Feedstock | Captive supply from Bayer process alumina refineries reduces margin volatility for precipitated ATH producers. |
| GMP-Certified Micronization Capacity Expansion | Validated jet milling infrastructure captures pharmaceutical-grade premiums as EMA tightens elemental impurity thresholds. |
| Spray-Dried Spherical Morphology Scale-Up | Dust-reduced handling properties align with EV battery enclosure compounder specifications for high-throughput operations. |
| REACH Nanoform Dossier Investment | Documented safety data unlocks formulated access for European cable and cosmetic compounders facing ECHA guidance. |
| Local Technical Service Partnerships in India | CDSCO excipient guideline tightening creates first-mover advantage for certified suppliers establishing Mumbai-Pune presence. |
Methodological Framework
Bottom-up pharmaceutical and flame-retardant polymer compounding modeling reconciled against top-down sodium aluminate feedstock and jet milling capacity tracking forms the analytical core. Primary interviews with plant managers at German and Indian precipitation facilities, procurement leads at European cable compounders, regulatory affairs directors navigating REACH nanoform guidance, and technical R&D heads developing spray-dried morphologies combined with secondary validation from ECHA registration databases, FDA excipient guidance documents, SEC filings of listed specialty chemical producers, and customs trade flow data for precipitated ATH grades.
Input-output matrices map sodium aluminate feedstock availability through precipitation capacity utilization to downstream pricing tier realization across the projection horizon. Segmentation dimensions modeled include physical form, application regulatory intensity, end-user procurement sophistication, and process control technology tier. CAGRs derive from capacity expansion announcements, regulatory milestone timelines, and substitution elasticity estimates for magnesium hydroxide in polyolefin cable applications. Forecast inputs incorporate EMA guideline implementation pace and CDSCO excipient standard evolution.
The model holds under stable REACH nanoform classification and gradual CDSCO guideline harmonization; deviation in ECHA reclassification triggering additional toxicity testing burdens would shift competitive positioning materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Roll to Roll Flexible Electronics Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market