
 Next-Generation Transistors Market | 2026-2036
Next-Generation Transistors Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Transistors Market Foresight
Automotive electrification is pivoting demand away from legacy silicon toward wide-bandgap next-generation transistors for traction inverters and onboard chargers. TSMC sustains foundry leadership by anchoring advanced FinFET production for high-performance logic clients. Infineon Technologies specializes in silicon carbide vertical integration from crystal growth to module packaging, while onsemi competes through its expanded gallium nitride portfolio for automotive power conversion.
Next-generation transistors are semiconductor devices engineered with sub-10 nanometer gate lengths, wide-bandgap compound semiconductors, or quantum-confined channels to achieve switching frequencies above 100 kilohertz and breakdown voltages exceeding 600 volts for power conversion and high-speed signal processing. Gallium Nitride Transistors now lead RF amplifier deployments in telecommunication base stations due to superior power density at millimeter-wave frequencies, while FinFET structures dominate logic device manufacturing as planar scaling approaches atomic limits. Carbon Nanotube technology occupies emerging research lanes for sub-3 nanometer nodes, though organic transistors remain confined to flexible display backplanes where processing temperature constraints govern adoption.
FDA device regulations intersect with transistor markets through implantable medical electronics requiring hermetic packaging standards, while EPA efficiency rules and the EU Green Deal F-Gas Regulation directly shape power supply and automotive inverter specifications. NHTSA propulsion safety standards further constrain automotive semiconductor qualification timelines, compressing supplier certification cycles. Stakeholders must monitor how REACH chemical restrictions on gallium and rare earth processing affect raw material access for wide-bandgap device fabrication.
Market Dynamics
Automotive electrification is compressing development cycles for wide-bandgap power devices as OEMs demand higher switching frequencies and thermal efficiency in traction inverters.
Growth Catalysts
- EPA tailpipe regulations:The US EPA's tightening CO2 standards for light-duty vehicles mandate efficiency gains that only silicon carbide and gallium nitride inverters can deliver at scale.
- China's MIIT semiconductor roadmaps:Domestic capacity targets for 8-inch SiC wafers and GaN-on-Si epitaxy are accelerating local supply chain maturation.
- Millimeter-wave 5G deployments:Base station OEMs specify GaN RF amplifiers for sub-6 GHz and mmWave massive MIMO arrays.
Market Restraints
- Substrate cost concentration:6H-SiC boule growth requires crucible-grade graphite and high-purity argon, with 70% of feedstock processing concentrated in Hubei province.
- REACH chemical restrictions:ECHA scrutiny of gallium chloride waste streams constrains European wet-chemical etching capacity expansion.
- Planar silicon persistence:Mature superjunction MOSFETs below 200V retain cost advantages in consumer adapter markets.
Strategic Opportunities
- India PLI scheme for semiconductors:Approved applicants receive 50% capex reimbursement for compound semiconductor fabs serving defense and space programs.
- Quantum computing cryogenic interfaces:Cryo-CMOS and Josephson junction transistor demand from superconducting qubit control electronics remains supply-constrained.
- EU Green Deal F-Gas Regulation:Phase-down of SF6 in medium-voltage switchgear creates vacuum-interrupter and solid-state circuit breaker substitution demand.
Industry Challenges
- Compound semiconductor process engineering:GaN HEMT epi growth on 200mm silicon substrates requires atomic-level defect control that exceeds silicon CMOS training pipelines.
- Automotive AEC-Q101 qualification:1,000-hour high-temperature reverse bias testing extends time-to-revenue for new wide-bandgap device families by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Transistors Market |
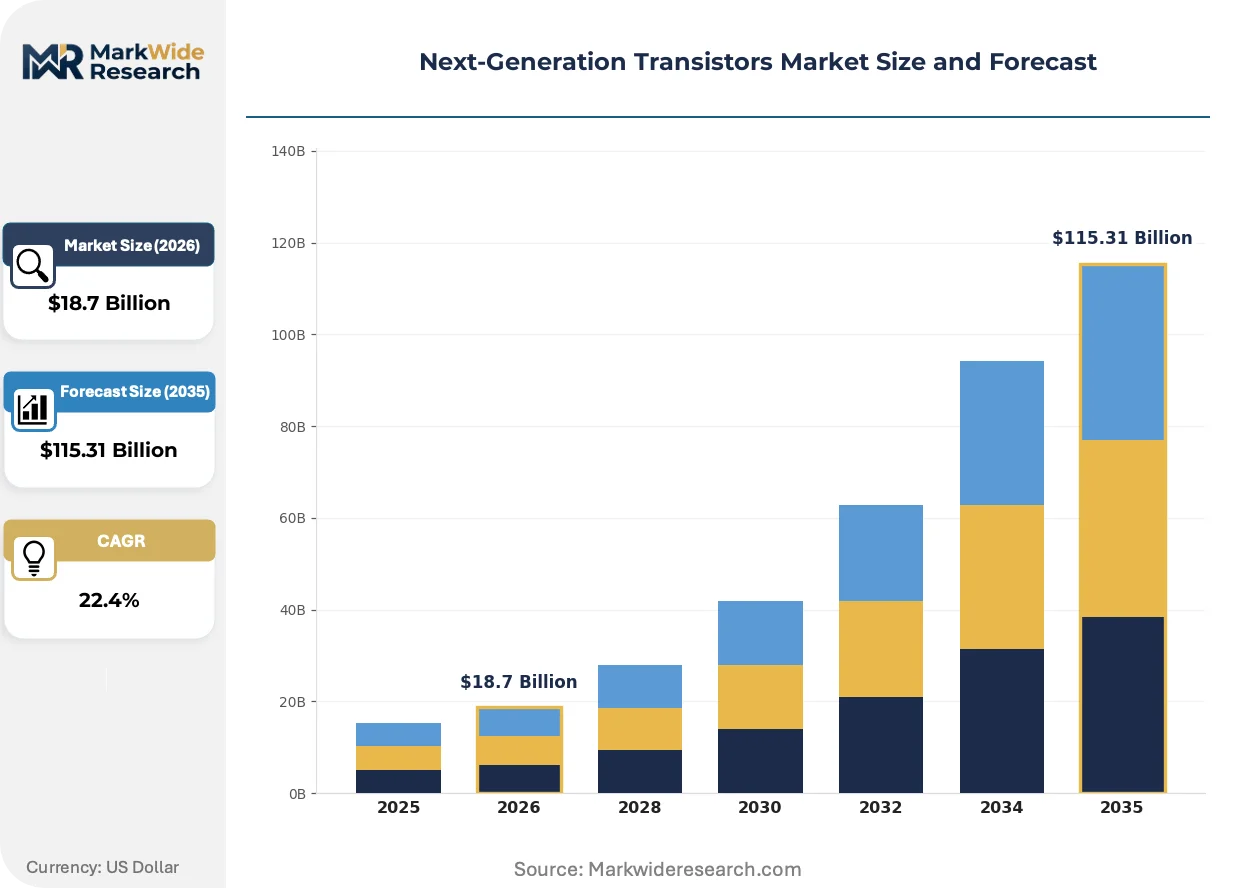
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Electron Mobility Transistors, FinFET, Gallium Nitride Transistors, Silicon Carbide Transistors Technology: Quantum Dot, 2D Materials, Organic Transistors, Carbon Nanotube End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunication Application: RF Amplifiers, Power Supply, Signal Processing, Logic Devices |
| Companies Covered | Intel Corporation, TSMC, Samsung Electronics, GLOBALFOUNDRIES, NXP Semiconductors, Infineon Technologies, STMicroelectronics, Texas Instruments, onsemi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Transistors Market Shifts & Advancements
Process automation and materials science breakthroughs are collapsing the boundary between power electronics and RF applications, creating hybrid device architectures.
Gallium nitride power ICs with integrated gate drivers and protection circuits are automating the transition from discrete component assemblies to single-chip power stages. Server power supply manufacturers at 48V rack architectures are adopting these monolithic solutions to reduce magnetic component count. This integration is automating the obsolescence of multi-chip driver boards in data center rectifiers.
The EU F-Gas Regulation's 2030 phase-down targets for fluorinated greenhouse gases are forcing redesigns of medium-voltage switchgear and industrial motor drives. Manufacturers must now certify vacuum interrupters or solid-state alternatives for grid infrastructure projects. German TSOs and French distribution operators are accelerating pilot deployments of SiC-based static transfer switches.
Direct procurement of bare die from foundries is displacing traditional module vendor relationships in automotive inverter programs. Tier-1 powertrain suppliers now negotiate wafer supply agreements with TSMC, GlobalFoundries, and X-FAB for custom trench-gate SiC MOSFET designs. This disintermediation is most pronounced in China, where BYD and NIO have established captive die-sort and module-assembly lines.
Next-Generation Transistors Market Segmentation
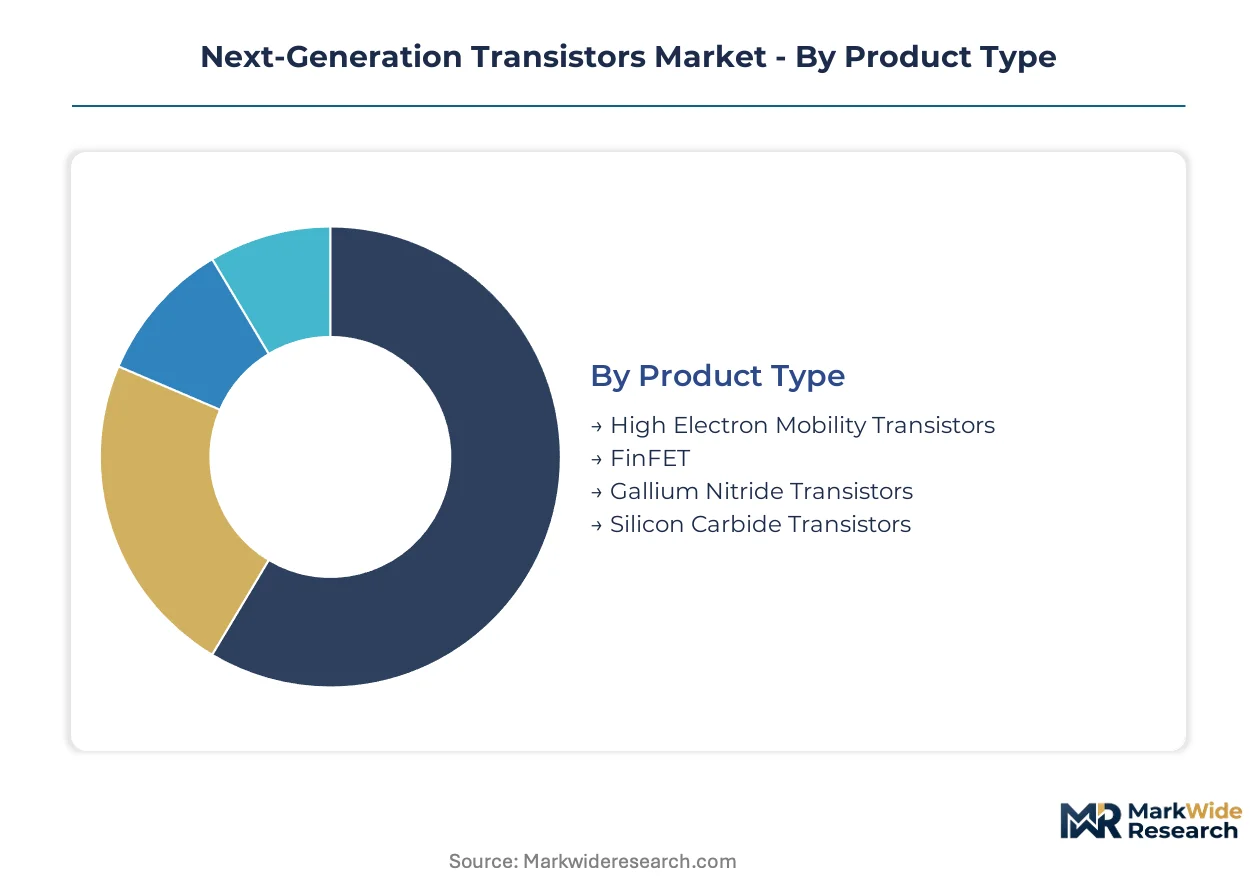
Next-generation transistor architectures fragment across material systems, dimensional scaling approaches, and integration complexity. Each segment carries distinct thermal budgets, switching frequency ceilings, and manufacturing maturity that dictate addressable application spaces.
Product Type:
Gate architecture and channel material define the performance envelope for power conversion and signal amplification tasks.
- Gallium Nitride Transistors:These wide-bandgap HEMT structures achieve switching frequencies above 100 kHz with breakdown voltages exceeding 600V. Data center power supply manufacturers at 48V rack architectures specify GaN for totem-pole PFC stages to shrink magnetic component volume.
- Silicon Carbide Transistors:Vertical trench-gate MOSFETs on 4H-SiC substrates deliver superior thermal conductivity for traction inverter applications. BYD and NIO in China have established captive die-sort and module-assembly lines for automotive qualification cycles.
- High Electron Mobility Transistors:III-V compound semiconductor devices exploit two-dimensional electron gas mobility for millimeter-wave RF amplification. Base station OEMs deploy these in sub-6 GHz massive MIMO arrays.
- FinFET:Three-dimensional gate-all-around structures enable sub-10 nanometer logic scaling where planar CMOS faces atomic limits. TSMC sustains foundry leadership by anchoring advanced node production for high-performance computing clients.
Gallium Nitride Transistors lead on scale; Silicon Carbide Transistors lead on momentum.
Technology:
Channel confinement mechanisms span quantum mechanical, van der Waals, molecular, and nanoscale carbon architectures.
- Quantum Dot:Discrete electron confinement in semiconductor nanocrystals enables single-electron transistor operation with ultra-low power dissipation. Cryogenic control electronics for superconducting qubits represent an emerging demand concentration.
- Carbon Nanotube:Semiconducting single-walled nanotubes offer ballistic transport with mean free paths exceeding 100 nanometers. IBM and IMEC maintain active research lanes for sub-3 nanometer node insertion.
- 2D Materials:Transition metal dichalcogenide monolayers such as MoS₂ provide atomically thin channels with dangling-bond-free interfaces. Flexible electronics manufacturers evaluate these for bendable sensor backplanes.
- Organic Transistors:Solution-processable polymer semiconductors enable low-temperature fabrication on plastic substrates. Display backplane applications dominate where silicon processing thermal budgets are incompatible with substrate materials.
Carbon Nanotube commands the steepest R&D investment trajectory; Quantum Dot occupies the narrowest commercial niche.
End User:
Application environments impose divergent reliability, temperature, and switching frequency requirements.
- Automotive:Traction inverters and onboard chargers mandate AEC-Q101 qualification with 1000-hour high-temperature reverse bias testing. EPA tailpipe regulations compress supplier certification cycles to 18-24 months for new wide-bandgap device families.
- Telecommunication:5G base station deployments specify GaN RF power amplifiers for macro cell and small cell infrastructure. Millimeter-wave massive MIMO arrays exploit superior power density at frequencies above 24 GHz.
- Consumer Electronics:Smartphone chargers and laptop adapters below 200W represent high-volume, cost-sensitive demand. Mature superjunction silicon MOSFETs retain advantages in this price-compressed segment.
- Industrial Automation:Motor drives and welding equipment require ruggedized packaging for harsh electromagnetic environments. EU F-Gas Regulation phase-down targets are forcing SF6 substitution in medium-voltage switchgear applications.
Automotive anchors absolute revenue concentration; Telecommunication offers the most aggressive frequency scaling requirements.
Application:
Functional purpose determines whether switching speed, breakdown voltage, or leakage current dominates device specification.
- Power Supply:AC-DC rectifiers and DC-DC converters prioritize efficiency at switching frequencies above 100 kHz. Server power supply manufacturers adopt monolithic GaN power ICs with integrated gate drivers to displace multi-chip driver boards.
- RF Amplifiers:Linear power amplification with high PAE drives base station and radar system specifications. GaN HEMTs dominate cellular infrastructure and electronic warfare transmitters.
- Logic Devices:Computational density and static power dissipation govern CMOS replacement candidates. FinFET structures currently dominate as foundries postpone gate-all-around transitions.
- Signal Processing:Analog front-ends and mixed-signal interfaces require low noise figures and high linearity. Precision instrumentation and medical imaging equipment specify these characteristics.
Power Supply captures the broadest addressable market; RF Amplifiers exhibit the most pronounced technology substitution dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping transistor production geography as fabs migrate toward jurisdictions with subsidized cleanroom construction and relaxed chemical processing rules. The cost-of-compliance gap between REACH-constrained Europe and Asia-Pacific industrial zones exceeds 340 basis points on wafer processing economics.
China
Domestic EV manufacturers and 5G base station rollouts drive gallium nitride and silicon carbide procurement. MIIT semiconductor roadmaps mandate 8-inch SiC wafer capacity targets by 2030. The Yangtze River Delta cluster around Shanghai anchors captive die-sort facilities for BYD and NIO powertrain programs.
United States
Data center hyperscalers and defense contractors sustain demand for advanced FinFET and RF power devices. EPA tailpipe regulations compress automotive qualification timelines for wide-bandgap suppliers. Arizona and Texas fab corridors attract TSMC and Samsung expansion projects under CHIPS Act incentives.
Germany
Automotive OEMs and industrial motor drive manufacturers specify SiC modules for traction inverters. EU F-Gas Regulation phase-down targets force SF6 substitution in medium-voltage switchgear. Bavaria's Ingolstadt and Stuttgart automotive clusters host captive module assembly for European EV platforms.
Japan
Precision instrumentation and telecommunications equipment sustain demand for high-electron-mobility transistors. METI technology roadmaps prioritize compound semiconductor supply chain security. The Kyushu silicon island cluster maintains specialized SiC crystal growth capacity for power device substrates.
South Korea
Memory foundry integration and consumer electronics manufacturing drive logic and power device demand. KBA vehicle safety standards constrain automotive semiconductor certification cycles. The Seoul Capital Area anchors Samsung's advanced node FinFET production and GaN RF amplifier lines for 5G infrastructure.
Next-Generation Transistors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device manufacturers commanding power electronics while pure-play foundries dominate logic scaling. The vendor base concentrates around three tiers: captive fabs serving automotive OEMs, merchant foundries with advanced node leadership, and compound semiconductor specialists with crystal-to-module control. Consolidation pressure intensifies as automotive electrification demands 18-24 month qualification cycles that favor incumbents with existing AEC-Q101 certifications. Strategic moves center on backward integration into substrate supply and geographic diversification of front-end capacity.
Within the foundry tier, TSMC and GLOBALFOUNDRIES occupy positions as scale anchors for advanced FinFET and RF silicon production. Among integrated device manufacturers, Infineon Technologies exemplifies the compound semiconductor archetype with in-house SiC crystal growth capabilities. These three entities represent the dominant competitive templates: pure-play foundry, IDM with wide-bandgap vertical control, and automotive-qualified power specialist.
| Leading Market Players |
|---|
| Intel Corporation |
| TSMC |
| Samsung Electronics |
| GLOBALFOUNDRIES |
| NXP Semiconductors |
| Infineon Technologies |
| STMicroelectronics |
| Texas Instruments |
| onsemi |
| Others |
Supply & Pricing Matrix
EPA tailpipe regulations and the EU Green Deal F-Gas Regulation gate qualified supply for wide-bandgap transistors, reserving premium-tier pricing access to vendors with AEC-Q101 automotive certifications and hermetic packaging capabilities. Buyers without EV platform qualification timelines face extended procurement cycles and cost penalties for non-compliant inventory.
Pricing Analysis
Distributor margins on silicon carbide modules run 12-18 points above legacy silicon MOSFETs, reflecting qualified supply scarcity and long-tail technical support obligations. Pricing stratifies across automotive-grade, industrial-grade, and consumer-grade certification tiers, with AEC-Q101 qualification adding 25-35% cost premiums. Cost compression in consumer adapter tiers is intensifying because mature superjunction silicon retains cost advantages below 200V. Smartphone charger OEMs exhibit the highest price sensitivity, while German automotive Tier 1s accept premiums for guaranteed die-sort traceability.
Supply Chain Analysis
High-purity SiC boule growth feeds from crucible-grade graphite suppliers concentrated in Hubei province, China, and specialty gas processors in Japan and Germany. The transistor supply chain draws from 6H-SiC crystal substrates, GaN-on-Si epitaxial wafers, and advanced ceramic packaging substrates. Single-source vulnerability in 8-inch SiC wafer capacity creates qualification bottlenecks for automotive inverter programs. Distribution runs through authorized distributors serving defense and space programs, direct foundry relationships for automotive OEMs, and spot markets for consumer electronics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The next-generation transistors market reads as a late-cycle quality story where automotive electrification has shifted procurement specifications toward AEC-Q101-qualified wide-bandgap devices with guaranteed thermal cycling performance.
For Market Incumbents: Cement backward integration into SiC crystal growth capacity to defend margin position against emerging Chinese substrate entrants. Prioritize AEC-Q101 certification maintenance for automotive inverter platforms, as EPA tailpipe regulations compress supplier qualification windows to 18-24 months. Channel control through captive die-sort facilities in the Yangtze River Delta anchors BYD and NIO supply relationships.
For New Entrants and Emerging Players: Capture white-space in cryogenic control electronics for superconducting quantum computing, where Josephson junction and cryo-CMOS transistor demand outstrips qualified supply. India's PLI scheme for compound semiconductor fabs offers 50% capex reimbursement for defense and space program suppliers. A foundry-services go-to-market angle bypasses 18-24 month automotive qualification barriers while building process credibility.
For Investors and Strategic Acquirers: Roll-up economics work for compound semiconductor specialists with in-house SiC crystal growth because automotive electrification demands 18-24 month qualification cycles that favor incumbents with existing AEC-Q101 certifications. Long-term viability centers on substrate supply security and geographic diversification of front-end capacity. Watch MIIT semiconductor roadmap revisions as the inflection indicator for Chinese domestic capacity buildout timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Crystal Growth | Infineon's in-house boule production secures substrate supply for automotive traction inverter qualification cycles. |
| AEC-Q101 Certification Investment | EPA tailpipe regulations compress supplier onboarding windows to 18-24 months for wide-bandgap device families. |
| Geographic Capacity Diversification | TSMC's Arizona fab expansion under CHIPS Act incentives reduces concentration risk in Taiwan front-end processing. |
| GaN Power IC Integration | Monolithic solutions with integrated gate drivers displace multi-chip driver boards in 48V data center rectifiers. |
| Cryogenic Transistor Development | Superconducting qubit control electronics demand outstrips qualified cryo-CMOS and Josephson junction supply. |
Research Methodology
Multiple input streams — primary interviews with semiconductor device engineers and automotive powertrain procurement leads, secondary validation through SEC 10-K filings and MIIT semiconductor roadmap documents, and customs data on SiC substrate trade flows — were reconciled to construct market estimates. Foundry executives, compound semiconductor process engineers, and Tier 1 supplier quality managers provided operational context. Bottom-up wafer shipment tallies and top-down OEM procurement budget analysis were cross-referenced for triangulation.
Historical capacity expansion patterns were cross-referenced against panel input from crystal growth equipment vendors and epitaxy tool manufacturers to anchor projections across the analysis window. Segmentation dimensions modeled include material system, gate architecture, end-use qualification tier, and regional fab capacity cluster. CAGRs were derived from supply-demand balance modeling for 8-inch SiC wafer capacity and GaN RF amplifier deployment in 5G massive MIMO arrays. Forecast inputs incorporated EPA regulatory timeline assumptions and EU F-Gas Regulation phase-down targets.
Substrate yield improvements, automotive platform cancellation decisions, and REACH chemical restriction enforcement are the dominant revision risks for transistor supply forecasts. A small set of named triggers — MIIT capacity target revisions, CHIPS Act funding disbursement pace, and SiC boule defect density breakthroughs — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Asia-Pacific MPU Market
Emerging and Next Generation Technologies
Global Neuromorphic Computing Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Next-Generation Organic Solar Cell Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market